

Cargo-to-Passenger Convertible eVTOL Cabin Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market Insights
EASA SC-VTOL special conditions is redrawing competitive boundaries for convertible cabin suppliers. BETA Technologies leverages its integrated airframe-cabin development pipeline to compress certification timelines. Diehl Aviation sustains engineering dominance through dedicated eVTOL interiors programs in Germany. Safran competes with propulsion-to-cabin thermal management solutions that address dual-use thermal loads.
Cargo-to-passenger convertible eVTOL cabin systems integrate quick-release seat tracks, modular floor panels, and reconfigurable sidewall attachments to enable same-day payload transformation between freight pallets and passenger seating. Composite materials technology leads structural segment investment due to weight-critical performance thresholds, while smart glass panels represent the fastest-growing technology sub-area as operators seek dynamic opacity control for mixed-use missions. Convertible cabin product types capture concentrated OEM interest, though fixed cabin variants retain margin pools in dedicated air ambulance configurations.
FAA Part 23 reform and EASA SC-VTOL frameworks dictate crashworthiness, egress, and fire suppression standards that cabin architectures must satisfy before type certification. China's CAAC AC-92-01 and Japan's MLIT rotorcraft guidance extend regulatory multiplicity for suppliers targeting Asia-Pacific qualification. Stakeholders must monitor which certification body achieves reciprocal acceptance first, as this determines where manufacturing investment and fleet deployment capital will flow.
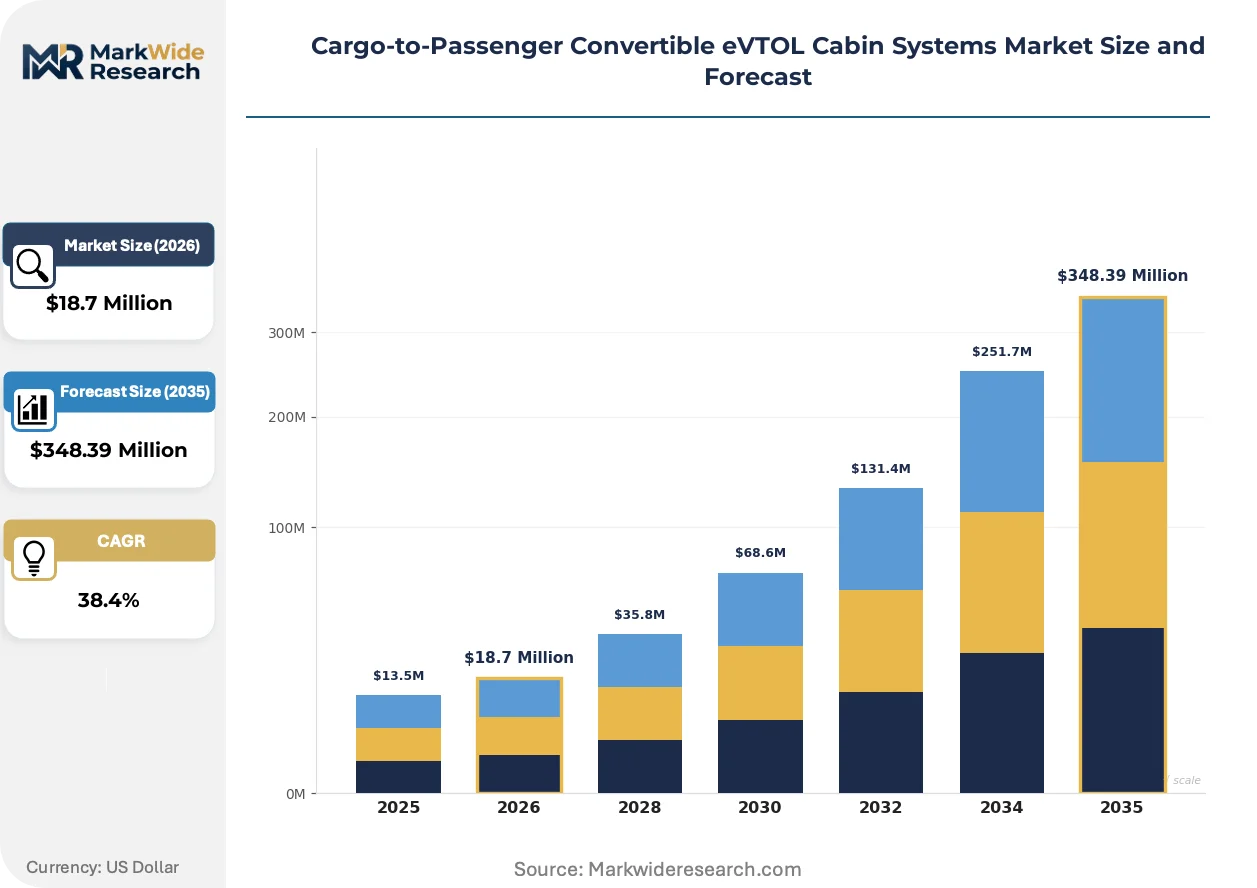
Market Dynamics
Reconfigurable cabin architectures are forcing suppliers to engineer for same-day payload transformation between freight and passenger configurations, compressing development cycles and recertification burdens simultaneously.
Growth Catalysts
- Urban air mobility operators:Fleet operators in the United States are specifying convertible cabins to maximize aircraft utilization across mixed-use missions, creating pull-through demand for modular floor systems.
- FAA Part 23 reform:Streamlined certification pathways for small aircraft are reducing type certification timelines for innovative cabin configurations previously blocked by legacy amendment cycles.
- Composite materials advancement:Automated fiber placement and resin transfer molding are cutting structural component weight while maintaining crashworthiness thresholds.
Market Restraints
- Thermal management complexity:Dual-use cabins must satisfy divergent heat-load profiles from cargo refrigeration and passenger HVAC, driving up system integration costs.
- Supply concentration in aerospace composites:Prepreg carbon fiber supply chains cluster in Germany, Japan, and the United States, exposing cabin manufacturers to input bottlenecks.
- EASA SC-VTOL special conditions:European crashworthiness requirements for vertical takeoff aircraft exceed existing Part 23 baselines, forcing redundant engineering for dual-certification programs.
Strategic Opportunities
- Asia-Pacific regulatory harmonization:China's CAAC AC-92-01 and Japan's MLIT rotorcraft guidance create first-mover advantage for suppliers achieving reciprocal acceptance between Asian regulators.
- Air ambulance dedicated configurations:Fixed-cabin variants for medical evacuation retain premium margins where reconfigurability adds no operational value.
- Smart glass integration:Electrochromic panels enabling dynamic opacity control are converging with structural health monitoring sensors to create intelligent cabin envelopes.
Industry Challenges
- Multidisciplinary engineering talent scarcity:Cabin system architects must synthesize composite structures, avionics integration, and human factors—a skill set concentrated at legacy Tier 1 suppliers.
- Parallel certification complexity:FAA Part 23, EASA SC-VTOL, and emerging CAAC frameworks demand divergent test matrices, stretching validation budgets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market Trends and Innovations
Three interconnected developments are restructuring how cabin systems are specified, certified, and manufactured. Material substitution, regulatory fragmentation, and operator procurement evolution are collectively elevating systems integration capabilities over component supply.
Modular floor panel systems with integrated seat tracks and cargo tie-down points are supplanting traditional fixed-floor architectures in new eVTOL programs. Urban air mobility operators in the United States are specifying these configurations for delivery routes requiring rapid turnaround between passenger and freight missions. This technology is compressing supplier margins on discrete components while expanding contract values for integrated subsystem providers.
EASA SC-VTOL special conditions are mandating occupant protection standards that exceed existing Part 23 baselines for energy absorption and post-crash fire suppression. European OEMs are redesigning sidewall attachments and emergency egress paths to satisfy these requirements ahead of reciprocal acceptance negotiations. Convertible cabin architectures face the steepest compliance burden, as reconfigurable elements must demonstrate crashworthiness across multiple payload states.
Operator procurement is consolidating around airframe OEMs offering bundled cabin configurations rather than discrete interior suppliers. Fleet managers are specifying performance guarantees covering weight, reconfiguration time, and mean time between failures rather than component specifications. This pattern is most visible in United States-based urban air mobility programs, where vertical integration between airframe and cabin engineering is becoming a competitive discriminator.
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market Segmentation
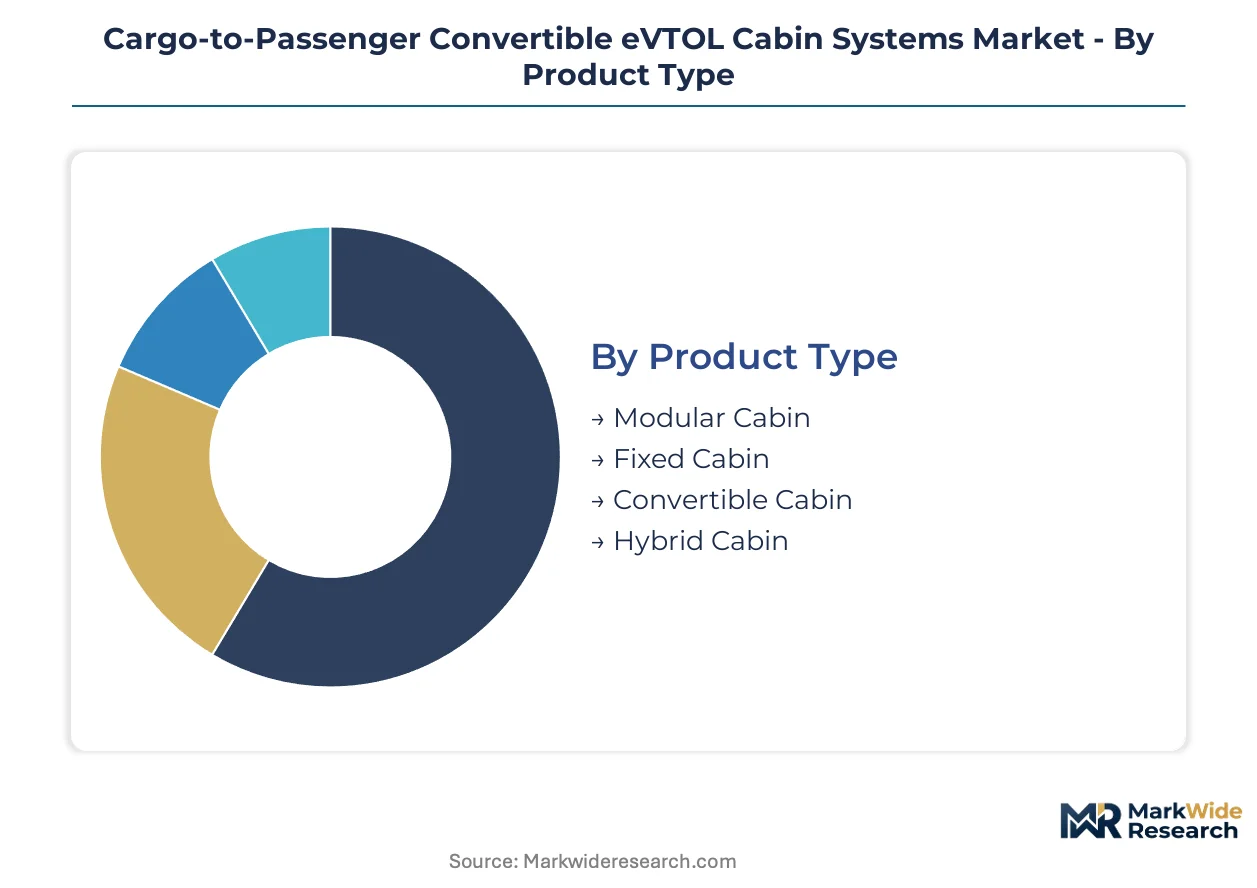
Segmentation in the cargo-to-passenger convertible eVTOL cabin systems market reveals how regulatory scope and operator mission profiles shape procurement decisions. Each dimension—product architecture, materials technology, application vertical, and supply chain position—carries distinct certification burdens and margin structures that determine supplier competitiveness.
Product Type:
Convertible cabin variants dominate domestic qualification programs in the United States, where FAA Part 23 reform enables rapid configuration cycling. Fixed and hybrid architectures concentrate in European and Asian export markets governed by EASA SC-VTOL and emerging CAAC frameworks requiring dedicated mission certification.
- Modular Cabin:Quick-release floor panels and reconfigurable sidewall attachments enable same-day payload transformation. United States-based urban air mobility operators specify these systems for mixed passenger-freight routes, compressing turnaround times below 45 minutes per reconfiguration cycle.
- Fixed Cabin:Dedicated architectures optimize weight and structural efficiency for single-mission profiles. Air ambulance operators in Germany and Japan favor fixed configurations where reconfigurability adds no operational value and crashworthiness certification paths are streamlined.
- Convertible Cabin:Integrated seat-track and cargo-tie-down systems support dual-use operations without airframe modification. Demand concentrates in North American fleet programs targeting maximum aircraft utilization across variable mission schedules.
- Hybrid Cabin:Semi-permanent partition systems allow limited reconfiguration with reduced mechanical complexity. Emerging in Asia-Pacific qualification programs where regulatory frameworks remain unsettled and operators seek operational flexibility without full convertible certification costs.
Convertible cabin holds the largest share; momentum sits with modular cabin systems as fleet operators prioritize reconfiguration speed over structural weight optimization.
Technology:
Material selection in cabin systems follows a cost-tier logic: composite and carbon fiber solutions command premium positioning for weight-critical applications, while aluminum variants serve cost-sensitive training and secondary cargo markets. Smart glass panels represent the emerging technology tier where functionality differentiation justifies price premiums.
- Composite Materials:Automated fiber placement and resin transfer molding produce structural components meeting EASA SC-VTOL energy absorption thresholds. United States and German suppliers lead qualification programs for primary cabin structures in certified eVTOL programs.
- Lightweight Aluminum:Conventional extrusion and machining processes deliver cost efficiency for non-structural interior elements. Aviation training centers in Japan and Australia specify aluminum sidewall panels where crash loads are reduced and acquisition cost dominates procurement criteria.
- Carbon Fiber:High-modulus prepreg layups achieve specific strength ratios exceeding metallic alternatives by 40-60%. Concentrated in German and Japanese supply chains, exposing cabin manufacturers to input concentration risk.
- Smart Glass Panels:Electrochromic and suspended particle devices enable dynamic opacity control for passenger comfort and cargo thermal management. Fastest-expanding technology sub-area as operators seek intelligent cabin envelopes integrating structural health monitoring.
Composite materials command the dominant revenue position; carbon fiber is climbing the fastest as OEMs prioritize weight reduction for range extension.
Application:
Application segmentation tracks directly to regulator engagement intensity: urban air mobility and on-demand taxi services face the most stringent ongoing oversight, while special cargo transport operates under modified certification with reduced occupant protection requirements.
- Urban Air Mobility:Scheduled and on-demand passenger services in metropolitan corridors drive convertible cabin specification. United States operators in Dallas, Los Angeles, and Miami anchor initial fleet deployments requiring rapid payload transformation capability.
- Air Ambulance:Medical evacuation missions demand fixed-cabin configurations with stretcher integration and life-support equipment mounting. Premium margin retention in this segment where reconfigurability offers no clinical value.
- On-Demand Taxi:Point-to-point passenger services prioritize passenger experience elements including smart glass and acoustic treatment. Regulatory frameworks in the United States and United Arab Emirates are advancing fastest for this application.
- Special Cargo Transport:Time-critical freight operations utilize convertible or dedicated cargo configurations with reduced pressurization and climate control. Emerging in Chinese and Southeast Asian markets where e-commerce logistics integration drives demand.
Urban air mobility holds the largest share; special cargo transport is gaining share fastest as e-commerce operators integrate aerial logistics networks.
End User:
End-user segmentation reflects supply chain position and technical capability: OEMs and Tier-1 suppliers possess integrated engineering resources for cabin-airframe co-development, while maintenance providers and training centers participate downstream with limited design authority.
- OEMs:Airframe manufacturers including BETA Technologies, Joby Aviation, and Archer Aviation specify bundled cabin configurations with performance guarantees rather than component procurement. Vertical integration between airframe and cabin engineering compresses certification timelines.
- Tier-1 Suppliers:Diehl Aviation and Safran compete through dedicated eVTOL interiors programs offering propulsion-to-cabin thermal management and structural subsystem integration. Engineering talent concentration at these suppliers creates competitive moats.
- Maintenance Providers:Post-certification modification and repair services address wear items and configuration updates. Limited to markets with deployed fleet populations sufficient to sustain service economics.
- Aviation Training Centers:Simulator and ground-based training equipment procurement drives demand for representative cabin mockups. Cost-sensitive segment where aluminum and composite hybrid constructions predominate.
OEMs hold the largest share; Tier-1 suppliers are expanding most quickly as airframe manufacturers outsource subsystem integration to de-risk development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 23 reform and EASA SC-VTOL special conditions are redirecting fleet deployment capital toward jurisdictions with clearer certification reciprocity. Urban air mobility operators prioritize markets where convertible cabin architectures can achieve dual-use airworthiness without redundant engineering cycles.
United States
Domestic fleet operators in Dallas, Los Angeles, and Miami are specifying modular cabin systems for mixed passenger-freight routes. FAA streamlined certification pathways enable rapid configuration cycling below 45 minutes. BETA Technologies, Joby Aviation, and Archer Aviation anchor integrated airframe-cabin development in California and Texas corridors.
Germany
Diehl Aviation sustains engineering concentration through dedicated eVTOL interiors programs in Hamburg and Laupheim. EASA SC-VTOL crashworthiness requirements exceed Part 23 baselines for energy absorption and post-crash fire suppression. Bavarian and Baden-Württemberg clusters host prepreg carbon fiber supply chains serving structural component manufacturers.
China
E-commerce logistics integration drives convertible cabin demand for time-critical aerial freight networks. CAAC AC-92-01 creates parallel certification requirements for vertical takeoff aircraft in the Yangtze River Delta and Pearl River Delta. EHang anchors test-flight programs in Guangzhou where special cargo transport applications advance fastest.
Japan
MLIT rotorcraft guidance extends regulatory multiplicity for suppliers targeting Asia-Pacific qualification. Aviation training centers in Osaka and Nagoya specify aluminum-construction cabin mockups where acquisition cost dominates procurement. Fixed-cabin air ambulance configurations retain premium margins in Tokyo and Kansai medical evacuation networks.
United Arab Emirates
On-demand taxi regulatory frameworks advance fastest in Dubai and Abu Dhabi for point-to-point passenger services. Smart glass integration with electrochromic panels converges with climate control specifications for premium cabin experience. Supernal positions integrated cabin configurations for Gulf Cooperation Council fleet deployment timelines.
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market Competitive Landscape
Player mix skews toward integrated airframe-cabin developers and specialized aerospace subsystem suppliers. Market structure concentrates around OEMs with captive engineering resources and Tier-1 suppliers offering bundled thermal management solutions. Two strategic archetypes dominate: vertically integrated airframe manufacturers compressing certification timelines, and dedicated interiors specialists leveraging composite materials expertise. Competitive moves center on regulatory pre-qualification investments and geographic certification stacking to capture first-mover advantage in emerging markets.
Among integrated developers, BETA Technologies exemplifies the airframe-cabin co-development archetype through its unified engineering pipeline. Diehl Aviation and Safran occupy positions within the Tier-1 subsystem tier, representing contrasting specialization vectors—dedicated eVTOL interiors programs versus propulsion-to-cabin thermal management integration. These three anchors illustrate how competitive positioning stratifies between captive development and outsourced subsystem procurement.
| Leading Market Players |
|---|
| BETA Technologies |
| Eve Air Mobility |
| Diehl Aviation |
| RECARO Aircraft Seating |
| Astronics |
| Supernal |
| EHang |
| Collins Aerospace |
| Safran |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber substitution for aluminum in primary cabin structures simultaneously shifts supply geography toward German and Japanese prepreg manufacturers and compresses pricing power among legacy metallic component suppliers. This materials transition concentrates procurement leverage with composite specialists while forcing aluminum-tier suppliers into cost-competitive defensive positioning.
Pricing Analysis
Cost-plus contracts with carbon fiber indexation dominate procurement between Tier-1 cabin integrators and airframe OEMs. Price differentiation rests on EASA SC-VTOL certification grade and volume scale, with dual-certified configurations commanding substantial premiums over single-jurisdiction alternatives. Pricing pressure intensifies as urban air mobility fleet operators consolidate procurement around bundled performance guarantees rather than discrete component specifications. Training centers and aviation mockup providers exhibit highest price sensitivity, while certified eVTOL OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Germany, Japan, and the United States anchor prepreg carbon fiber production for structural cabin components. The supply chain draws from aerospace-grade resin systems, high-modulus fiber tow, and specialized tooling equipment. Single-source vulnerability concentrates in German autoclave capacity and Japanese fiber precursor supply. Distribution runs through Tier-1 subsystem integrators delivering complete cabin modules to airframe manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against fixed-cabin dedicated configurations that threaten to capture premium-margin air ambulance segments. Incumbents must navigate regulatory fragmentation while preserving convertible architecture value propositions.
For Market Incumbents: Compound certification investments across FAA Part 23 and EASA SC-VTOL frameworks to compress dual-qualification timelines before fixed-cabin competitors lock air ambulance contracts. Deepen backward integration into composite manufacturing to secure carbon fiber supply against German and Japanese input concentration. Prioritize thermal management subsystem bundling as the defensive lever against propulsion-to-cabin specialists.
For New Entrants and Emerging Players: Lead with smart glass integration for on-demand taxi operators in Dubai and Abu Dhabi, where climate control specifications create white-space openings absent from established supplier portfolios. Target Asia-Pacific regulatory harmonization gaps between CAAC AC-92-01 and MLIT guidance as the most penetrable qualification pathway. Pursue airframe OEM partnership models rather than discrete component supply to bypass incumbent Tier-1 relationships.
For Investors and Strategic Acquirers: The market sits at a pre-scale certification phase that favors subsystem specialists with demonstrated regulatory pre-qualification. Long-term viability hinges on reciprocal acceptance achievement between FAA and EASA frameworks within the next development cycle. Acquisition targets should demonstrate composite materials expertise paired with thermal management integration capabilities. The signal to watch is first-mover fleet deployment announcements from Dallas, Los Angeles, or Miami operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous FAA Part 23 and EASA SC-VTOL qualification compresses market entry timelines for convertible architectures. |
| Composite Manufacturing Scale-Up | Automated fiber placement capacity expansion in Germany reduces dependency on Japanese prepreg supply. |
| Smart Glass Platform Integration | Electrochromic panel convergence with structural health monitoring creates differentiated cabin envelope offerings. |
| Thermal Management Subsystem Bundling | Propulsion-to-cabin heat load integration addresses dual-use mission complexity for urban air mobility operators. |
| Asia-Pacific Regulatory Pre-Qualification | Early CAAC AC-92-01 engagement captures first-mover advantage in Chinese e-commerce logistics networks. |
Research Methodology
Initial hypotheses were tested against primary input from eVTOL airframe engineering directors, cabin systems procurement leads, composite materials R&D specialists, and regulatory certification consultants, then refined through secondary validation against FAA type certification databases, EASA SC-VTOL special condition drafts, CAAC AC-92-01 guidance documents, and OEM supplier disclosure filings. Bottom-up segmentation modeling triangulated with top-down market sizing across product architecture, materials technology, and application vertical dimensions.
Variance decomposition across the projection horizon isolates regulatory timeline uncertainty, composite input cost volatility, and fleet deployment pace as primary forecast drivers. Segmentation modeling incorporates product type, technology tier, application vertical, and end-user supply chain position. CAGRs derive from logistic adoption curves fitted to airframe manufacturer production announcements and operator fleet commitment disclosures. Industry-specific inputs include certification body reciprocity negotiation status and urban air mobility route authorization timelines.
Forecasts assume regulatory continuity in FAA Part 23 reform implementation and EASA SC-VTOL special condition enforcement; material policy shifts or reciprocal acceptance delays would require re-modeling. Specific risks include carbon fiber supply disruption, certification timeline extension, and fixed-cabin configuration share capture in medical evacuation segments. Recalibration cycles align with material shifts in type certification award schedules and fleet deployment capital commitment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.