
 Lawn Mower Battery Market | 2026-2036
Lawn Mower Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Mower Battery Market Outlook
Commercial landscaping fleets is reorganizing demand away from weekend residential buyers toward professional groundskeeping operations. Trojan Battery Co. specializes in deep-cycle durability for sustained commercial uptime. Yuasa Battery, Inc. leverages its motorcycle heritage to dominate compact form-factor designs for walk-behind units. Johnson Controls International PLC anchors the segment through its automotive-scale manufacturing footprint and North American distribution density.
Lawn mower batteries are rechargeable electrochemical storage systems, typically lithium-ion or lead-acid configurations rated between 24V and 60V, engineered to deliver sustained discharge cycles under intermittent high-torque loads from brushless electric motors. Their primary purpose is replacing internal combustion engines in turf maintenance equipment with zero-emission propulsion. Lithium-ion chemistry leads in value contribution due to energy density advantages and declining cell costs, while lead-acid retains volume share in price-sensitive residential entry models. Fast charging infrastructure is emerging as a margin concentration point as commercial fleets prioritize equipment utilization rates over overnight standard charging cycles.
The EPA regulates small engine emissions under Title II of the Clean Air Act, compelling manufacturers to certify battery systems as compliant alternatives, while OSHA standards on workplace noise exposure reinforce electric mower adoption in commercial settings. The EU Green Deal and F-Gas Regulation indirectly channel investment toward battery-electric outdoor power equipment by restricting fluorinated greenhouse gases used in conventional engine cooling systems. Stakeholders must weigh charging infrastructure deployment against fleet electrification timelines to avoid stranded asset risk in commercial mower portfolios.
Market Dynamics
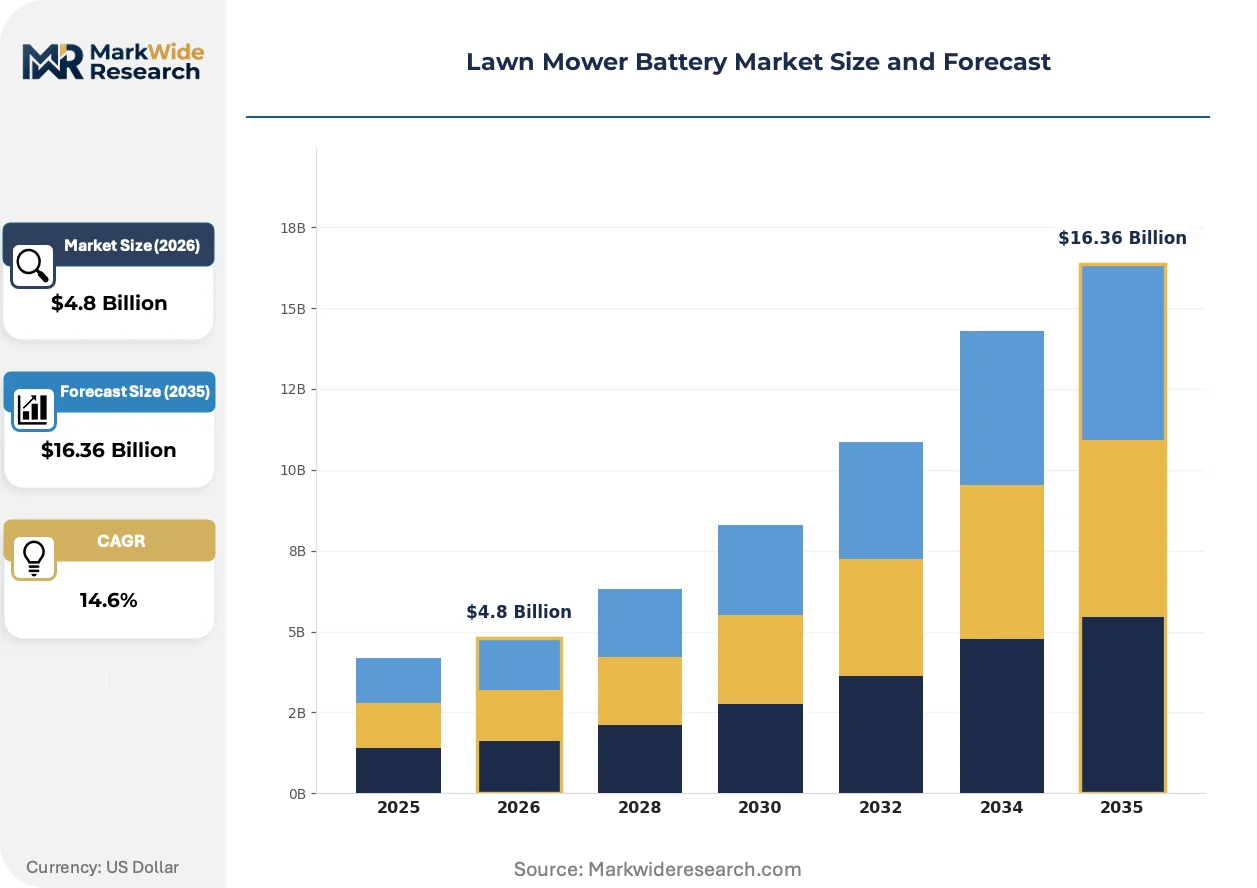
Commercial fleet electrification is compressing the replacement cycle for gas-powered mowers as landscaping contractors face Phase 3 emission compliance costs and municipal noise restrictions in suburban jurisdictions.
Growth Catalysts
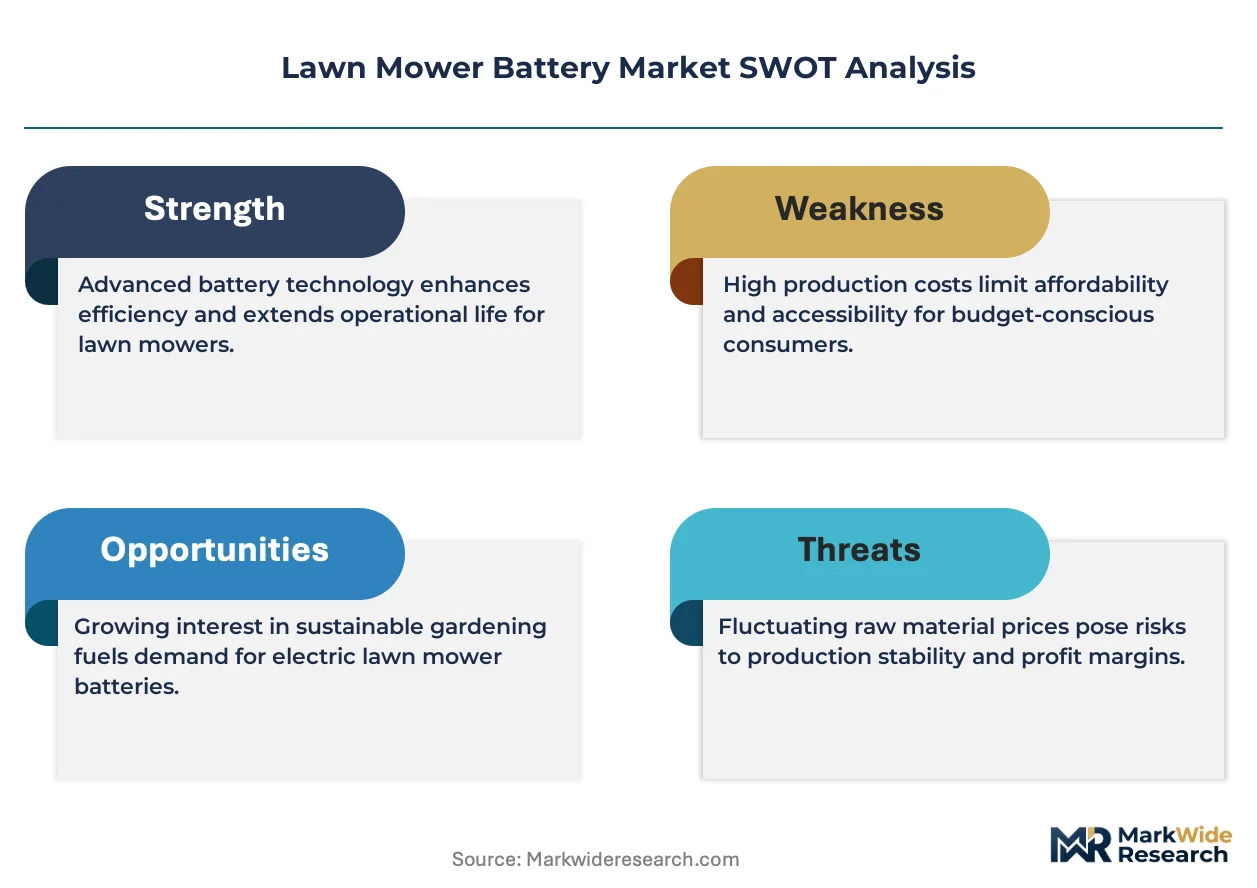
- EPA Phase 3 Emission Standards:Compliance costs for small spark-ignition engines are pushing commercial operators toward certified battery alternatives.
- Suburban Noise Ordinances:Municipal restrictions on decibel levels during operating hours favor zero-emission equipment in residential service territories.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements enable longer runtime per charge for sustained commercial uptime.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material input costs for cathode production create margin pressure on battery pack pricing.
- Fast-Charging Infrastructure Concentration:Depot charging hardware deployment lags fleet electrification timelines in secondary metropolitan markets.
- Lead-Acid Substitution Persistence:Price-sensitive residential entry segments retain legacy chemistry due to lower upfront acquisition costs.
Strategic Opportunities
- Battery-as-a-Service Models:Subscription-based powerpack provisioning reduces capex barriers for mid-sized landscaping contractors.
- Solar-Integrated Charging Depots:Renewable generation paired with stationary storage addresses grid dependency for off-peak fleet charging.
- Second-Life Automotive Cells:Repurposed EV battery modules enter the commercial mower aftermarket at reduced cost points.
Industry Challenges
- Battery Management System Integration:Firmware compatibility between cell packs and motor controllers requires specialized electrical engineering talent.
- UL 2580 Certification Timelines:Thermal runaway testing protocols for lithium-ion systems extend product launch schedules by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Mower Battery Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead Acid, Lithium-Ion, Nickel-Cadmium, AGM Power Rating: 24V, 36V, 48V, 60V Charging Method: Solar Charging, Fast Charging, Standard Charging, Smart Charging End User: Residential, Commercial, Municipal, Landscaping |
| Companies Covered | East Penn Manufacturing Co., Inc., Exide Technologies, Trojan Battery Co., Yuasa Battery, Inc., Anhui Uplus Energy Technology Co. Ltd., Harris Battery Co. Inc., Johnson Controls International PLC, Marshall Power Australia Pty Ltd., Yucell Industry Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Mower Battery Market Strategic Shifts
Electrochemical storage architectures are diverging between premium lithium-ion configurations and cost-optimized alternatives as commercial operators prioritize utilization economics over residential convenience features.
Solid-state electrolyte research is bifurcating the high-performance segment from conventional liquid-cell designs. Commercial fleet operators with intensive daily duty cycles are piloting next-generation prototypes that eliminate thermal management complexity. This chemistry is compressing the performance gap between automotive and outdoor power equipment storage standards.
The EU F-Gas Regulation is restricting fluorinated greenhouse gases in conventional engine cooling systems. This policy channels R&D investment toward fully electric architectures rather than emission-controlled combustion. Commercial groundskeeping divisions in Germany and France are accelerating procurement timelines to preempt equipment obsolescence.
Equipment utilization contracts are displacing traditional ownership models among municipal park services and corporate campus maintenance divisions. Third-party fleet operators assume battery lifecycle risk while charging per-acre pricing. This arrangement concentrates in the United States where large lot sizes and dispersed suburban geographies favor outsourced turf management.
Lawn Mower Battery Market Segmentation
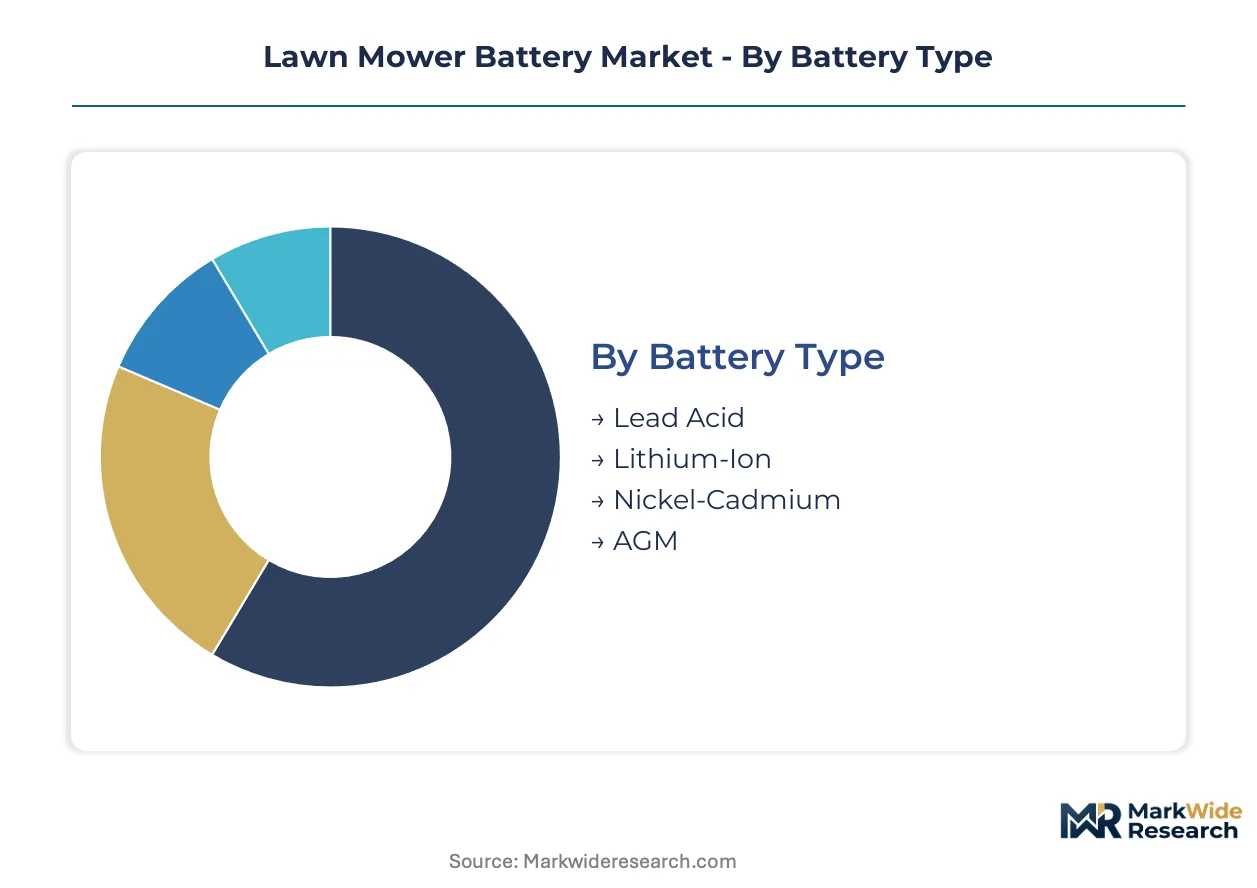
Segmentation in the lawn mower battery market reveals divergent channel strategies between retail distribution for residential replacement and direct fleet procurement for commercial operators. Understanding these pathways clarifies where margin concentration aligns with technical specification requirements.
Battery Type:
Channel mix varies sharply by chemistry, with lithium-ion flowing through professional distribution networks while lead-acid dominates big-box retail and aftermarket service channels.
- Lead Acid:Flooded and sealed lead-acid configurations deliver 24V-48V output at the lowest cost per kilowatt-hour. Demand concentrates in price-sensitive residential entry mowers sold through home improvement retailers in suburban United States markets where upfront acquisition cost outweighs lifecycle economics.
- Lithium-Ion:NMC and LFP cell architectures achieve 3-4x energy density versus lead-acid equivalents, enabling compact 60V packs for zero-turn riders. Commercial landscaping fleets in California and Texas prioritize these configurations to satisfy municipal noise ordinances while maintaining daily runtime targets.
- Nickel-Cadmium:Legacy chemistry retains niche presence in rental fleet maintenance due to tolerance for deep discharge abuse and temperature extremes.
- AGM:Absorbed glass mat construction bridges performance gaps with spill-proof operation for sloped terrain applications.
Lead Acid dominates installed base. Lithium-Ion is where expansion concentrates.
Power Rating:
Voltage tiering maps directly to equipment class and customer scale, with higher voltages commanding dedicated commercial distribution.
- 24V:Compact battery packs serve walk-behind push mowers and small robotic units. Residential homeowners in noise-restricted jurisdictions like Connecticut and New Jersey select these for weekend maintenance of modest lot sizes.
- 36V:Mid-range systems power self-propelled walk-behind equipment. Commercial entry-level contractors in Florida and Arizona deploy 36V fleets for gated community service routes where transport weight limits apply.
- 48V:Standard voltage for residential riding mowers and light commercial stand-on units.
- 60V:High-voltage architecture supports zero-turn riders and wide-area cutting decks.
48V anchors current revenue contribution. 60V is climbing the fastest as commercial fleet specifications migrate upward.
Charging Method:
Charging infrastructure investment separates ownership models, with subscription fleet operators prioritizing speed over residential overnight convenience.
- Solar Charging:Off-grid photovoltaic integration serves remote municipal parks and golf course maintenance divisions.
- Fast Charging:High-amperage depot systems restore 80% capacity within 30 minutes. Third-party fleet operators in metropolitan Dallas and Atlanta deploy these to maximize equipment utilization across multiple daily shifts.
- Standard Charging:Overnight 8-12 hour cycles dominate residential replacement battery sales.
- Smart Charging:Cellular-connected management systems optimize cell balancing and thermal regulation.
Standard Charging retains volume share. Fast Charging is gaining share fastest among commercial procurement specifications.
End User:
Customer type determines specification stringency, with municipal and commercial segments driving certified performance requirements versus residential price sensitivity.
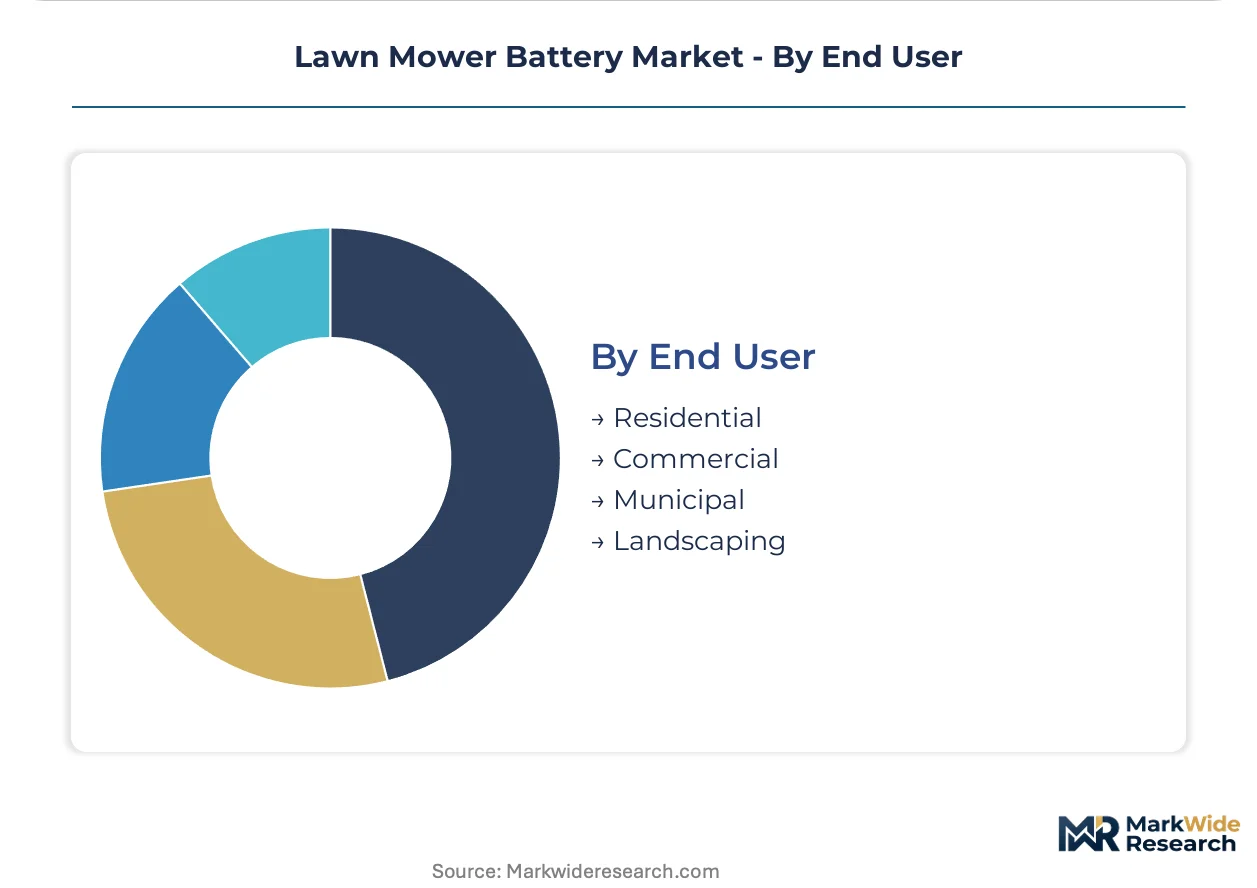
- Residential:Individual homeowners purchase replacement batteries through retail channels for self-directed lawn maintenance. EPA Phase 3 compliance costs for gas alternatives accelerate electric conversion in suburban United States markets with strict local noise enforcement.
- Commercial:Professional landscaping contractors operate fleet-scale deployments requiring standardized charging protocols and warranty uniformity. These operators in Georgia and North Carolina negotiate volume pricing with direct manufacturer relationships.
- Municipal:City and county park departments specify UL-certified systems with documented lifecycle testing.
- Landscaping:Dedicated groundskeeping divisions within corporate campuses and homeowner associations.
Residential holds unit volume leadership. Commercial is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese battery cell exports flow predominantly into North American and European lawn equipment supply chains, with South Korean cathode materials supporting tier-one pack assembly in Germany and the United States.
United States
Suburban noise ordinances in Connecticut and New Jersey accelerate electric mower procurement among residential homeowners. EPA Phase 3 emission standards tighten compliance costs for gas-powered alternatives. Commercial landscaping fleets in Georgia and North Carolina negotiate direct manufacturer relationships for standardized 60V charging protocols.
Germany
Corporate campus maintenance divisions in Bavaria and North Rhine-Westphalia pilot battery-as-a-service contracts to outsource lifecycle risk. The EU F-Gas Regulation restricts fluorinated greenhouse gases in conventional engine cooling systems. Stuttgart-based equipment manufacturers integrate repurposed automotive cells into commercial zero-turn rider platforms.
China
Domestic demand concentrates in Yangtze River Delta urban greening projects requiring compact 24V robotic units. MIIT battery safety standards shape cell certification requirements for export-bound packs. Shenzhen and Dongguan industrial clusters supply lithium-ion modules to North American OEMs under contract manufacturing arrangements.
Japan
METI carbon neutrality roadmaps channel R&D investment toward solid-state electrolyte prototypes for commercial duty cycles. Kansai region groundskeeping contractors test next-generation thermal management systems. Osaka-based industrial battery specialists leverage JIS certification protocols to differentiate premium-tier offerings.
Australia
Solar-integrated charging depots serve remote municipal parks in Queensland and Western Australia. Marshall Power Australia anchors domestic pack assembly for regional distribution. Melbourne and Sydney metropolitan councils specify UL-certified systems with documented lifecycle testing for fleet electrification timelines.
Lawn Mower Battery Market Competitive Environment
Listed leaders compete with private specialists across capital access and manufacturing scale dimensions. The vendor base separates into automotive-scale conglomerates, deep-cycle durability specialists, and regional pack assemblers. Three archetypes dominate: chemistry-agnostic volume producers, application-specific engineering houses, and vertically integrated cell-to-pack operators. Competitive moves concentrate on strategic partnerships with charging infrastructure providers and backward integration into cathode material sourcing.
Within the deep-cycle durability tier, Trojan Battery Co. and Yuasa Battery, Inc. exemplify engineering-focused positioning against automotive-scale alternatives. Johnson Controls International PLC anchors the conglomerate segment through North American distribution density. Chinese specialists including Anhui Uplus Energy Technology Co. Ltd. and Yucell Industry Limited occupy cost-optimized manufacturing positions serving export markets.
| Leading Market Players |
|---|
| East Penn Manufacturing Co., Inc. |
| Exide Technologies |
| Trojan Battery Co. |
| Yuasa Battery, Inc. |
| Anhui Uplus Energy Technology Co. Ltd. |
| Harris Battery Co. Inc. |
| Johnson Controls International PLC |
| Marshall Power Australia Pty Ltd. |
| Yucell Industry Limited |
| Others |
Value Chain & Pricing Dynamics
Ninety-day cathode material lead times from South Korean suppliers compress pricing power for pack assemblers in North America and Europe, concentrating margin capture with cell manufacturers who locked lithium carbonate contracts before spot volatility. This inventory pressure forces commercial fleet buyers toward longer-term offtake agreements to secure 60V pack availability.
Pricing Analysis
The technology-generation pricing gap separates legacy lead-acid residential packs from premium lithium-ion commercial configurations and emerging solid-state prototypes. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL 2580 certification status and volume commitment scale. Pricing pressure stems from cobalt and lithium hydroxide spot volatility, compressing margins for non-integrated pack assemblers. Residential replacement buyers exhibit highest price sensitivity, while municipal fleet operators prioritize certified lifecycle performance over acquisition cost.
Supply Chain Analysis
Port congestion on the Shanghai-Long Beach trade lane elevates inbound logistics costs for containerized cell shipments from Chinese manufacturing clusters. Supply concentrates in China for cathode active materials, South Korea for electrolyte formulations, and Japan for separator membranes. Raw material dependencies center on lithium carbonate from Chilean and Australian brine operations, cobalt hydroxide from the DRC, and nickel sulfate from Indonesian laterite processing. Single-source vulnerability in cathode precursor supply creates concentration risk. Distribution runs through professional equipment OEMs for commercial fleets and big-box retailers for residential replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lawn mower battery market is entering a cyclical recovery phase as EPA Phase 3 compliance deadlines force commercial fleet replacement decisions. Equipment utilization economics favor electric alternatives during this capital expenditure cycle.
For Market Incumbents: Consolidate cathode material sourcing through captive supply arrangements or long-term offtake agreements with Chilean and Australian lithium producers. Deepen backward integration into cell assembly to defend margin position against Chinese cost-optimized competitors. Priority investment targets UL 2580 certification acceleration and 60V platform standardization to lock in commercial fleet specifications. For New Entrants and Emerging Players: Battery-as-a-service provisioning gaps in mid-sized landscaping contractor segments offer white-space entry points where incumbents under-serve with transactional sales models. Target municipal park departments in secondary metropolitan markets with solar-integrated charging depot bundles. Go-to-market leverage rests on subscription pricing that converts capex to opex for budget-constrained public sector buyers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven replacement cycle play because emission standard tightening creates non-discretionary demand conversion rather than discretionary technology adoption. Acquisition target archetype: regional pack assemblers with established UL certification pathways and existing commercial fleet relationships. Signal to watch: municipal fleet electrification mandate announcements in suburban jurisdictions with strict noise enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive lithium carbonate supply from Chilean brine operations secures cost position against spot volatility. |
| UL 2580 Certification Acceleration | Thermal runaway testing completion unlocks commercial fleet procurement specifications in California and Texas. |
| Battery-as-a-Service Launch | Subscription pricing converts municipal capex constraints into recurring revenue with lifecycle risk retention. |
| Solar-Integrated Charging Depot Deployment | Photovoltaic generation paired with stationary storage addresses grid dependency for Queensland remote parks. |
| Second-Life Automotive Cell Sourcing | Repurposed EV modules from Stuttgart manufacturers reduce pack cost points for commercial zero-turn riders. |
Study Parameters
Cross-validation between OEM procurement director interviews and EPA regulatory filing analysis anchors the qualitative findings in documented compliance timelines. Primary fieldwork encompassed commercial landscaping fleet managers, municipal parks procurement officers, battery pack engineering leads, and charging infrastructure specialists. Secondary validation drew from EPA Phase 3 certification databases, UL 2580 test report summaries, customs trade flow records, and equipment OEM technical specification sheets. Bottom-up unit economics modeling triangulates against top-down market sizing from cathode material demand forecasts.
Sensitivity analysis on lithium carbonate price scenarios and fleet electrification adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include battery chemistry tier, voltage architecture class, charging method category, and end-user procurement scale. CAGRs derive from equipment replacement cycle compression rates and municipal mandate diffusion patterns. Industry-specific inputs incorporate Phase 3 compliance cost curves and suburban noise ordinance enforcement intensity indices.
Material uncertainties — cobalt price spike events, UL certification timeline delays, and municipal budget freeze decisions — sit outside the modeled envelope. Forecasts reflect assumptions on fleet operator utilization economics and residential electric conversion elasticity. Recalibration cycles align with material shifts in EPA enforcement posture and lithium contract pricing renegotiation windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
E-Axle Market