
 Global Electric Vehicle (EV) Management Solution Market | 2026-2036
Global Electric Vehicle (EV) Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Vehicle (EV) Management Solution Market Analysis
The EU Green Deal is repositioning the cost-of-entry calculus for EV management platforms across European markets. ChargePoint Holdings leverages its North American charging network density to compete in fleet-centric segments. Siemens AG anchors its position through industrial automation heritage applied to grid-integrated energy systems. Schneider Electric SE differentiates via deep expertise in building-to-vehicle energy orchestration.
Electric Vehicle (EV) Management Solutions encompass software and hardware systems that monitor, optimize, and coordinate battery performance, charging infrastructure, and energy flows across distributed vehicle assets, typically operating through cloud-native architectures with sub-second telemetry refresh rates. These platforms serve commercial and industrial users seeking to minimize downtime, reduce electricity costs, and extend battery cycle life. Fleet Management and Charging Management currently occupy the largest addressable value pools, while AI-driven predictive maintenance within the Technology dimension is attracting disproportionate R&D investment from platform providers. Energy Management solutions are gaining traction among Utilities and large Fleet Operators managing time-of-use tariffs and vehicle-to-grid bidirectional power flows.
The EPA tailpipe standards and the EU F-Gas Regulation are tightening product compliance requirements for thermal management components within battery systems. China's MIIT mandates data localization for connected vehicle platforms, creating divergent architecture requirements across major markets. India's BIS and PLI scheme are accelerating domestic manufacturing standards for EV components and software localization. Stakeholders must decide whether to architect region-specific compliance modules or pursue modular platforms adaptable to fragmented regulatory timelines.
Market Dynamics
Fleet operators are compressing total cost of ownership calculations as vehicle-to-grid bidirectional charging protocols mature, forcing platform providers to embed real-time energy arbitrage algorithms into core software stacks.
Growth Catalysts
- EU Green Deal ICE Phase-Out Mandates:Commercial fleet operators in Germany and the Netherlands are accelerating procurement timelines for integrated charging management platforms to meet binding 2035 deadlines.
- AI-Driven Predictive Maintenance:Machine learning models trained on battery telemetry data are reducing unplanned downtime for logistics fleets by flagging cell degradation patterns before thermal runaway events.
- China's MIIT Data Localization Requirements:Domestic cloud infrastructure mandates are creating captive demand for locally-hosted EV management architectures that foreign platforms must replicate or partner to access.
Market Restraints
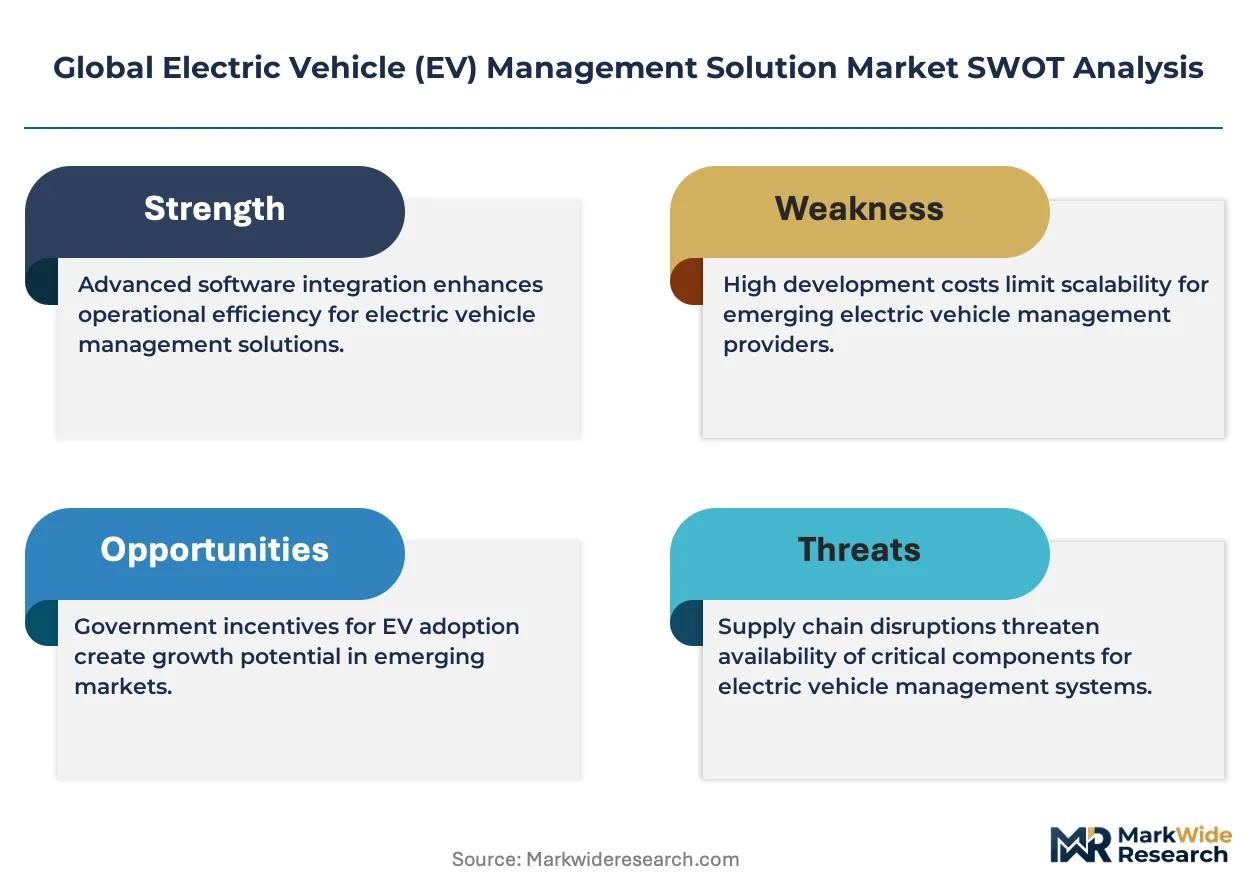
- Lithium-Ion Battery Raw Material Volatility:Cobalt and nickel price swings from Democratic Republic of Congo and Indonesian supply corridors are destabilizing total platform cost models for battery leasing integrators.
- Charging Hardware Supply Concentration:Power electronics manufacturing for DC fast chargers clusters in Shenzhen and Ningbo, exposing European and North American fleet operators to single-geography disruption risk.
- Interoperability Protocol Fragmentation:Competing standards between ISO 15118, CHAdeMO, and proprietary OEM communication stacks are inflating integration costs for multi-brand fleet deployments.
Strategic Opportunities
- India's PLI Scheme for Battery Swapping:Domestic manufacturing incentives are opening white space for management platforms optimized around modular battery exchange rather than fixed charging infrastructure.
- Vehicle-to-Building Energy Orchestration:Converging EV telematics with building management systems is enabling commercial real estate operators to monetize parked fleet assets as distributed grid resources.
- Japan's METI Carbon Neutrality Roadmap:Utility-backed demand response programs are creating new revenue streams for platforms that can aggregate fleet charging loads into virtual power plant architectures.
Industry Challenges
- Embedded Systems Cybersecurity Certification:UN R155 and R156 type approvals for software update management are extending product launch timelines by 12-18 months for platforms serving European automotive OEMs.
- Legacy Fleet Management System Migration:Diesel-era telematics infrastructure at major logistics operators requires costly middleware development to bridge proprietary data formats into cloud-native EV architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Vehicle (EV) Management Solution Market |
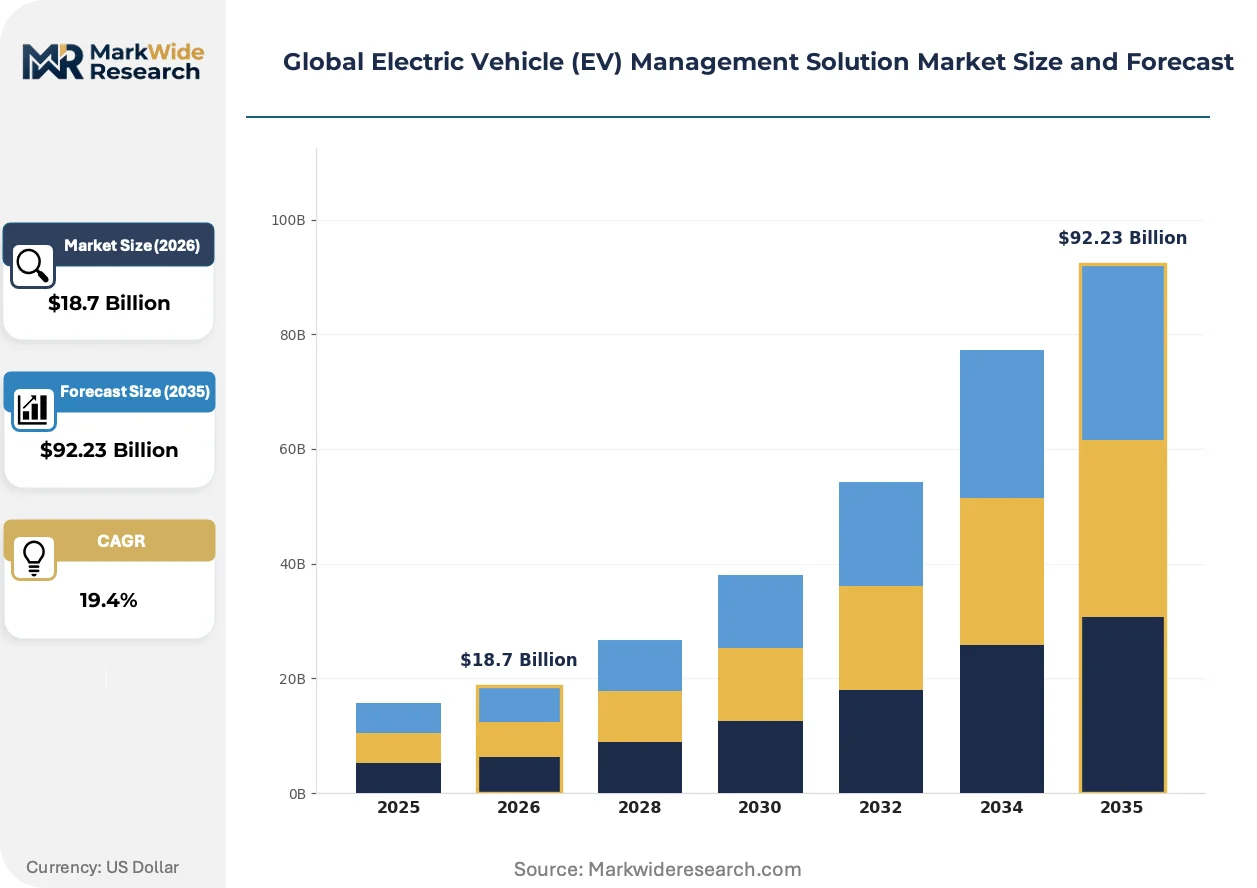
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Management, Fleet Management, Charging Management, Energy Management Technology: Telematics, IoT, AI, Blockchain End User: Automakers, Fleet Operators, Utilities, Charging Network Providers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | ChargePoint Holdings, ABB, Schneider Electric SE, Siemens AG, EVBox, Shell Recharge Solutions, Enel X, Driivz, EV Connect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Vehicle (EV) Management Solution Market Emerging Trajectories
Edge computing architectures are migrating battery state estimation from centralized clouds to onboard vehicle controllers, reducing latency for critical safety decisions while complicating software update orchestration across distributed assets.
Digital twin technology is automating fleet energy forecasting by replicating battery degradation trajectories across thousands of simulated duty cycles. Logistics operators in California are deploying these models to optimize charging schedules against time-of-use tariffs. The shift is compressing planning horizons from quarterly to weekly intervals as predictive accuracy improves.
EPA tailpipe standards finalized under the Inflation Reduction Act are tightening fleet average emissions benchmarks for commercial vehicle operators. Large-scale logistics providers are responding by mandating telematics integration from subcontractor fleets to prove compliance across Scope 3 value chains. The regulatory pressure is accelerating consolidation around platforms with certified audit trail capabilities.
Subscription-based platform licensing is displacing perpetual software purchases among mid-sized fleet operators seeking to convert capital expenditure into operational spend. Tier-2 logistics providers across Germany and France are piloting usage-based pricing tied to vehicles under management rather than feature tiers. The model shift is forcing incumbent vendors to restructure revenue recognition and customer success functions.
Global Electric Vehicle (EV) Management Solution Market Segmentation
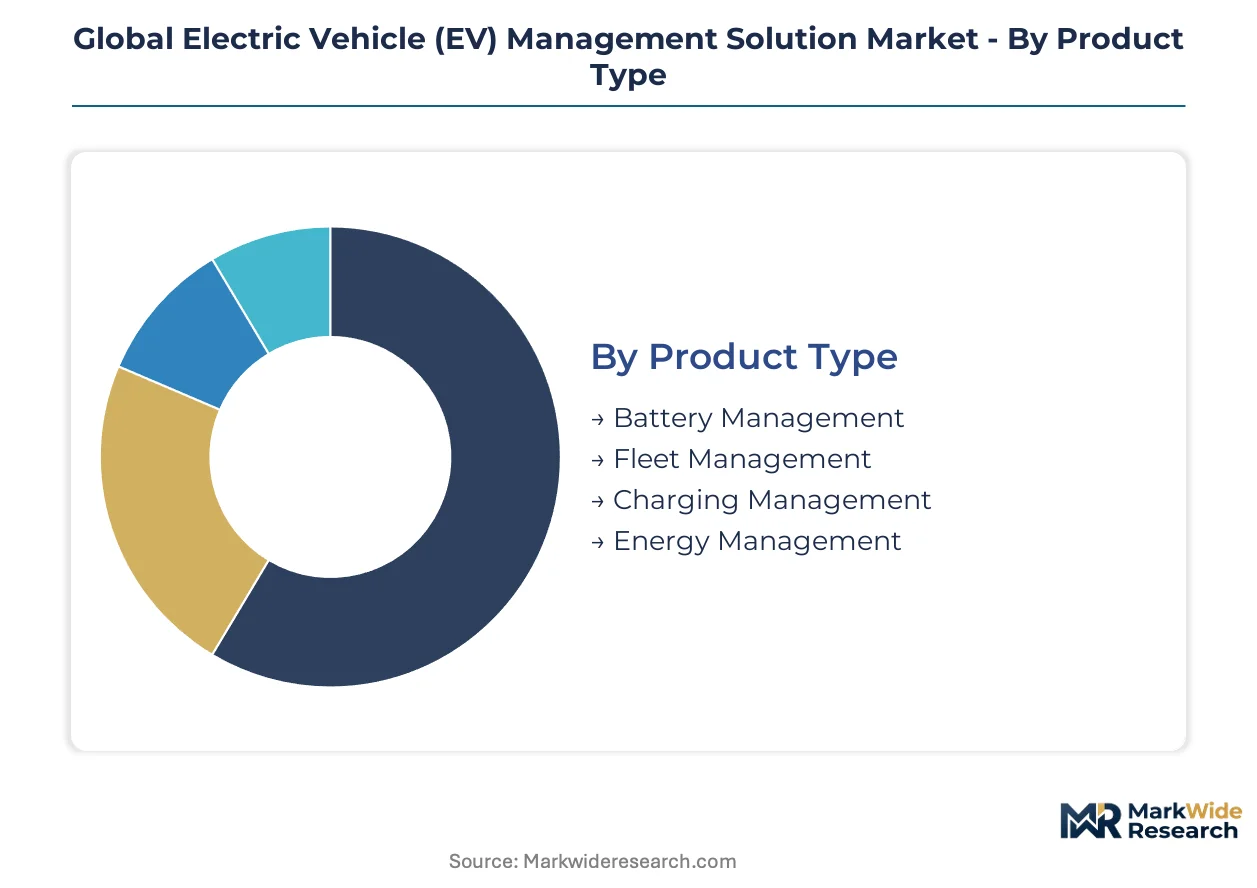
Segmentation in EV management solutions reflects divergent buyer priorities across hardware-centric fleet operators, software-first utilities, and integrated automakers. Procurement patterns cluster around deployment flexibility, data sovereignty requirements, and the depth of energy optimization needed.
Product Type:
Fleet operators prioritize total cost visibility when selecting product categories, weighing capital intensity against operational savings potential.
- Fleet Management:Comprehensive platforms tracking vehicle location, driver behavior, maintenance scheduling, and route optimization through centralized dashboards. Demand concentrates among logistics providers in Germany and California as EU Green Deal compliance deadlines and EPA tailpipe standards force diesel-to-electric conversions with audit-ready telematics.
- Charging Management:Systems orchestrating charger availability, session billing, and grid load balancing across distributed infrastructure networks. Large fleet depots in the Netherlands and China's industrial zones are deploying these platforms to manage time-of-use tariffs and avoid demand charge penalties from local utilities.
- Battery Management:Cell-level monitoring systems tracking state-of-charge, thermal conditions, and degradation patterns to extend cycle life.
- Energy Management:Bidirectional power flow platforms enabling vehicle-to-grid participation and building-integrated load shifting.
Fleet Management leads on scale; Energy Management leads on momentum.
Technology:
Technology selection hinges on latency tolerance, with real-time safety decisions demanding edge architectures while predictive analytics favor cloud-scale compute.
- AI:Machine learning models trained on battery telemetry datasets to predict thermal runaway events and optimize charging curves. California-based logistics operators are deploying these systems to compress maintenance windows and qualify for utility demand response incentives.
- Telematics:GPS and cellular-connected hardware transmitting vehicle position, speed, and diagnostic codes to centralized platforms. European fleet operators under EU Green Deal reporting mandates are standardizing these systems for Scope 3 emissions documentation.
- IoT:Sensor networks linking chargers, batteries, and grid interconnection points through low-latency protocols.
- Blockchain:Distributed ledger architectures for peer-to-peer energy trading and carbon credit verification.
Telematics dominates current deployment volumes; AI is climbing the fastest.
End User:
End-user segmentation maps to divergent regulatory exposure, with automakers facing type-approval burdens and utilities managing grid stability mandates.
- Fleet Operators:Commercial vehicle owners managing mixed electric and diesel assets through unified platforms. Germany's logistics sector is accelerating procurement as KBA enforcement of EU CO2 standards for heavy-duty vehicles tightens compliance documentation requirements.
- Utilities:Grid operators aggregating distributed EV loads into virtual power plants and managing time-of-use tariff structures. Japan's METI-backed demand response programs are creating captive demand for platforms with sub-second load modulation capabilities.
- Automakers:OEMs embedding management software into vehicle operating systems and warranty programs.
- Charging Network Providers:Infrastructure operators monetizing session data and grid services across multi-site deployments.
Fleet Operators anchor revenue concentration; Utilities are gaining share fastest.
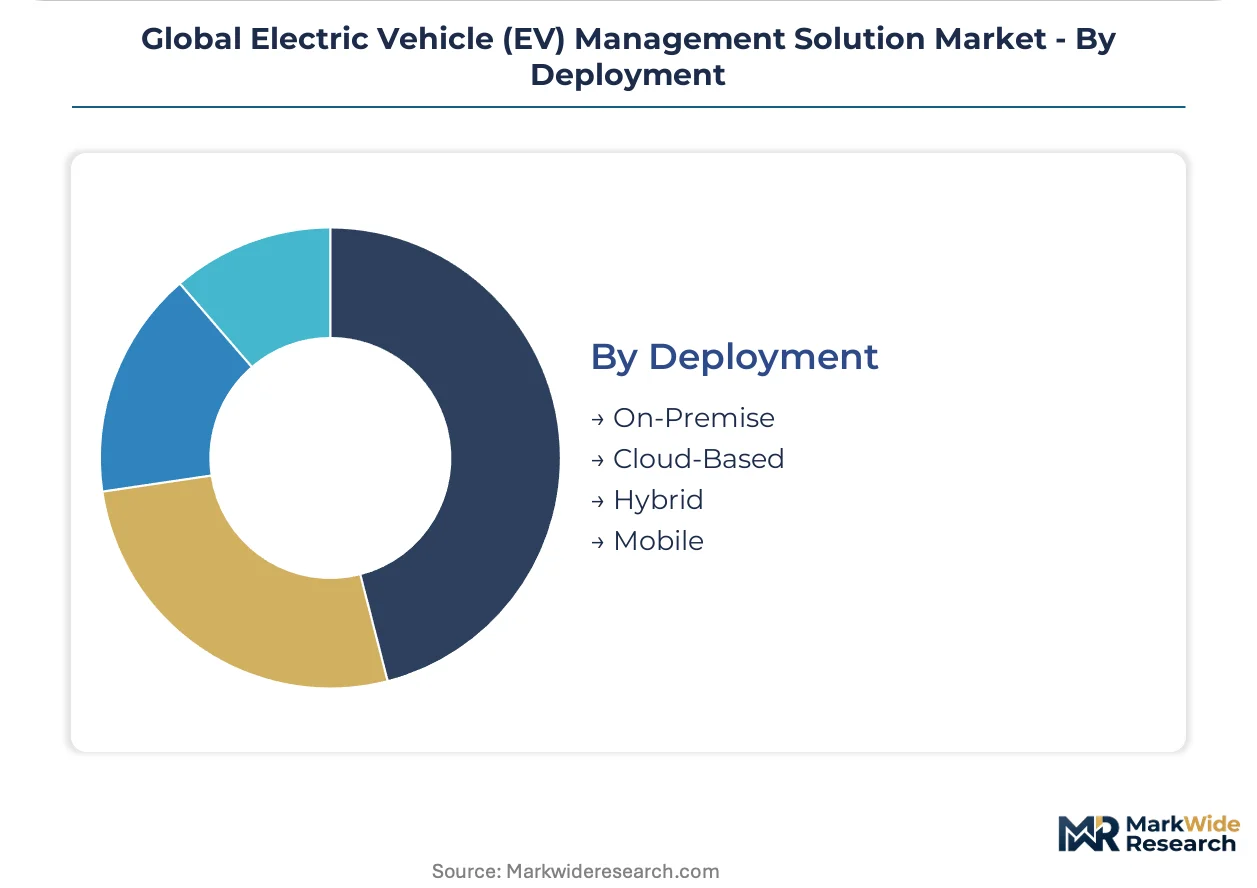
Deployment:
Deployment architecture decisions trade data sovereignty against scalability, with China's MIIT localization mandates forcing on-premise or domestic cloud configurations.
- Cloud-Based:Fully hosted SaaS platforms delivering elastic compute for predictive analytics and multi-tenant feature rollouts. India's mid-sized fleet operators are piloting these solutions under BIS data governance frameworks that permit offshore processing with encryption safeguards.
- Hybrid:Architectures splitting sensitive battery safety algorithms on-vehicle while pushing analytics workloads to centralized clouds. European automakers navigating UN R155 cybersecurity type approvals are favoring this model to isolate safety-critical functions.
- On-Premise:Self-hosted infrastructure for operators with strict data residency or air-gapped security requirements.
- Mobile:Smartphone-native interfaces for driver-facing charge scheduling and vehicle status monitoring.
Cloud-Based leads on scale; Hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineers specializing in grid integration and battery telemetry cluster in Germany, California, and Shenzhen, anchoring the geographic talent base for EV management platform development.
United States
Logistics operators in California and Texas are deploying fleet management platforms to comply with EPA tailpipe standards under the Inflation Reduction Act. The EPA mandates telematics documentation for Scope 3 emissions across subcontractor networks. Los Angeles-based fleet depots are piloting vehicle-to-grid bidirectional charging systems to capture utility demand response incentives.
Germany
Commercial vehicle operators are compressing procurement timelines for integrated charging management solutions ahead of binding EU Green Deal deadlines. The KBA enforces CO2 standards for heavy-duty vehicles with tightening documentation requirements. Industrial zones in North Rhine-Westphalia are deploying grid-integrated energy management platforms to optimize time-of-use tariffs for large fleet depots.
China
Domestic cloud infrastructure providers are capturing captive demand from MIIT data localization mandates for connected vehicle platforms. The MIIT requires locally-hosted architectures that foreign platforms must replicate or partner to access. Manufacturing clusters in Shenzhen and Ningbo are concentrating power electronics production for DC fast chargers, exposing supply chains to single-geography disruption risk.
India
Mid-sized logistics operators are piloting cloud-based SaaS platforms under BIS data governance frameworks that permit offshore processing with encryption safeguards. The PLI scheme accelerates domestic manufacturing standards for EV components and software localization. Fleet operators in Maharashtra and Gujarat are testing battery swapping management platforms optimized around modular exchange infrastructure.
Japan
Utilities are aggregating distributed EV loads into virtual power plant architectures under METI-backed demand response programs. The METI Carbon Neutrality Roadmap creates new revenue streams for platforms with sub-second load modulation capabilities. Industrial corridors around Nagoya and Osaka are integrating fleet charging schedules with building energy management systems.
Global Electric Vehicle (EV) Management Solution Market Vendor Landscape
The competitive structure tilts toward industrial automation conglomerates with legacy grid infrastructure expertise. Platform providers cluster into three tiers: charging hardware specialists, energy management software vendors, and integrated industrial technology groups. Consolidation pressure intensifies as fleet operators demand unified platforms spanning telematics, charging orchestration, and battery analytics. Dominant competitive moves include strategic partnerships between charging network operators and utility-backed energy service companies, plus technology licensing agreements to bridge proprietary OEM communication protocols.
Among European industrial technology groups, Siemens AG and Schneider Electric SE exemplify archetypes applying building automation heritage to vehicle-to-grid energy orchestration. ChargePoint Holdings anchors the North American charging network specialist tier, representing geographic density strategies competing for fleet-centric procurement contracts. These three companies occupy positions spanning hardware infrastructure, software platforms, and utility integration capabilities.
| Leading Market Players |
|---|
| ChargePoint Holdings |
| ABB |
| Schneider Electric SE |
| Siemens AG |
| EVBox |
| Shell Recharge Solutions |
| Enel X |
| Driivz |
| EV Connect |
| Others |
Supply Flow & Price Mechanics
Fleet operator consolidation around unified platform procurement is compressing vendor margins and forcing suppliers to absorb integration costs for multi-brand telematics stacks. This demand-side pressure rewards providers with captive hardware manufacturing while squeezing pure-software vendors on price.
Pricing Analysis
Subscription-versus-perpetual licensing splits dominate pricing architecture, with SaaS tiers stratifying across premium, standard, and economy levels based on vehicle count and analytics depth. Price differentiation rests on ISO 15118 certification status and after-sales service bundling. Cost compression in mid-market tiers is intensifying because charging hardware vendors are cross-subsidizing software to lock in infrastructure contracts. Small logistics operators exhibit highest price sensitivity; utilities and large fleet operators show lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment for charging hardware and telematics modules. Manufacturing concentrates in China, South Korea, and Germany for power electronics, battery management systems, and industrial controllers. The supply chain draws from cobalt and nickel feedstocks originating in the Democratic Republic of Congo and Indonesia. Single-source vulnerability around Shenzhen-based DC fast charger production exposes European and North American operators to disruption. Distribution runs through OEM-authorized service networks and direct-to-depot logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in EV management solutions are accelerating as software subscription models displace hardware-centric perpetual licenses, compressing customer acquisition costs while extending lifetime value.
For Market Incumbents: Deepen backward integration into power electronics manufacturing to defend against Chinese charging hardware vendors cross-selling subsidized software. Incumbents must also consolidate middleware capabilities for legacy diesel telematics migration, as logistics operators face UN R155 cybersecurity certification delays that threaten platform switching costs.
For New Entrants and Emerging Players: Utility-backed energy service companies represent the most penetrable channel partner type for platform distribution. New entrants should target India's battery swapping ecosystem under PLI scheme incentives, deploying lightweight SaaS architectures optimized for modular exchange infrastructure rather than fixed charging depots.
For Investors and Strategic Acquirers: Asymmetric upside sits with edge-computing specialists possessing onboard battery state estimation IP. Long-term viability favors platforms with demonstrated vehicle-to-grid aggregation capabilities under Japan METI demand response frameworks. Investors should monitor EPA tailpipe standard enforcement intensity as the inflection signal for fleet operator procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Grid-integrated deployments in Germany and California capture EU Green Deal and EPA compliance incentives. |
| Platform Integration | Unified telematics-charging-energy stacks reduce procurement friction for multi-brand fleet operators. |
| Acquisition of Specialist Firm | Edge-computing battery analytics targets compress latency for thermal runaway prevention decisions. |
| Geographic Expansion | Domestic cloud hosting in China satisfies MIIT data localization mandates for connected vehicle platforms. |
| Technology Licensing | ISO 15118 protocol bridges reduce integration costs for fleets deploying mixed OEM vehicle assets. |
Methodological Framework
Bottom-up fleet operator modeling reconciled against top-down charging infrastructure deployment tracking forms the analytical core of this study. Primary interviews with fleet procurement directors, utility demand response managers, OEM platform engineers, and charging network operations heads were combined with secondary validation from SEC filings, EPA regulatory dockets, EU Green Deal implementation reports, and MIIT connected vehicle policy circulars. This approach triangulates vendor-reported deployments against utility interconnection records and vehicle registration databases.
Historical trendline analysis of subscription revenue recognition patterns and hardware shipment volumes established baseline growth trajectories across the projection horizon. The forecast framework models segmentation dimensions including deployment architecture, end-user category, and technology tier, with CAGRs derived from elasticity analysis of regulatory compliance deadlines against fleet replacement cycles. Vehicle-to-grid protocol maturation timelines and battery degradation simulation accuracy serve as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion raw material price volatility and interoperability standard consolidation. Outputs reflect documented assumptions around regulatory enforcement intensity and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Global Electric Light Commercial Vehicles Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Belgium Solar E-Bike Market