
 Plug-In Hybrid Electric Vehicle Battery Market | 2026-2036
Plug-In Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Plug-In Hybrid Electric Vehicle Battery Market Insights
Commercial fleet procurement is realigning toward plug-in hybrid platforms as operators balance electrification targets with range security. Contemporary Amperex Technology Co. Limited leverages its cell-to-pack architecture to sustain cost leadership in high-volume contracts. BYD Company Ltd anchors vertical integration across cathode chemistry and vehicle assembly, controlling margin capture from mine to module. Samsung SDI Co. Ltd differentiates through prismatic cell reliability, occupying premium positioning in European OEM supply chains.
A plug-in hybrid electric vehicle battery is a rechargeable energy storage system engineered for dual-mode operation, typically employing lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate cathode formulations and liquid electrolyte architectures to deliver 8-25 kWh usable capacity for electric-only ranges. The system interfaces with onboard power electronics to enable grid charging, regenerative braking recovery, and seamless handoff to combustion propulsion, serving the primary purpose of reducing fleet-average emissions while eliminating range anxiety in passenger and light-commercial transport. Lithium-ion chemistry dominates installed capacity due to superior energy density and cycle stability, while high-capacity configurations are capturing disproportionate engineering investment as OEMs stretch electric-only range beyond regulatory minimums. Commercial fleets represent the fastest-expanding application segment, driven by depot-charging economics and urban low-emission zone compliance requirements.
The US EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates are tightening allowable fleet emissions, directly expanding PHEV qualification for consumer tax credits under the IRA. Europe's F-Gas Regulation and REACH chemical restrictions are reshaping cell manufacturing supply chains, forcing cathode material sourcing adjustments. China's MIIT new energy vehicle credit system and GB/T charging standards govern domestic product certification and interoperability requirements. Stakeholders must monitor how regulatory credit arbitrage between full-electric and plug-in hybrid categories shifts OEM battery procurement priorities.
Market Dynamics
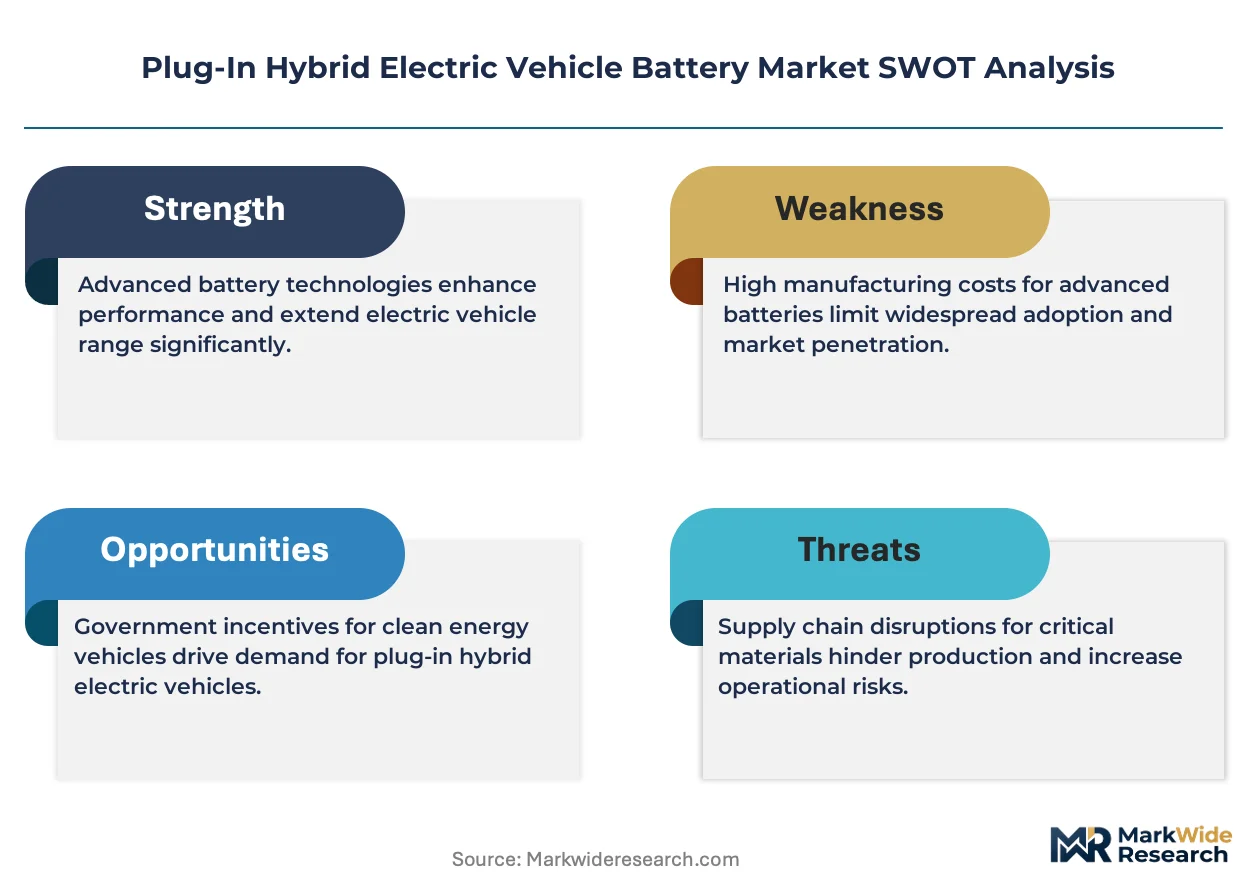
Cell-to-pack architecture is compressing module-level manufacturing steps, forcing incumbent suppliers to retool assembly lines or cede cost-competitive contracts to vertically integrated battery producers.
Growth Catalysts
- China's NEV Credit System:MIIT mandates require domestic OEMs to accumulate new energy vehicle credits, directly expanding procurement of 15-25 kWh PHEV battery packs for fleet compliance.
- Depot-Charging Economics:Commercial fleet operators in urban logistics are capturing 40-60% fuel cost reductions through overnight grid charging, accelerating replacement cycles for diesel vans.
- Nickel-Rich Cathode Chemistry:NMC 811 formulations are raising energy density above 250 Wh/kg, enabling electric-only ranges that satisfy last-mile delivery routes without combustion assist.
Market Restraints
- Cobalt Price Volatility:DRC supply concentration exposes cathode producers to 30-50% raw material cost swings, compressing gross margins on long-term cell supply agreements.
- Prismatic Cell Supply Bottleneck:Korean and Japanese producers dominate high-reliability prismatic formats, creating single-source risk for European OEMs qualifying alternative suppliers.
- REACH Chemical Restrictions:ECHA substance-of-very-high-concern listings are forcing reformulation of electrolyte additives and binder chemistries, extending qualification timelines by 12-18 months.
Strategic Opportunities
- India's FAME-II Subsidy Extension:The government's demand incentive scheme for electric and strong-hybrid vehicles opens procurement channels for 8-12 kWh PHEV packs in two-wheeler and three-wheeler conversions.
- V2G-Enabled Fleet Contracts:Bidirectional charging infrastructure allows commercial operators to monetize grid services, creating attach-rate opportunities for battery management system upgrades.
- Solid-State Electrolyte Convergence:Sulfide-based ceramic separators combined with lithium-metal anodes promise 400+ Wh/kg density, positioning early movers for next-generation platform wins.
Industry Challenges
- Thermal Runaway Simulation Expertise:Cell manufacturers face acute shortages of computational fluid dynamics engineers capable of modeling propagation containment in multi-cell modules.
- GB/T Charging Certification:China's interoperability testing protocols require 6-9 month validation cycles, delaying market entry for non-domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plug-In Hybrid Electric Vehicle Battery Market |
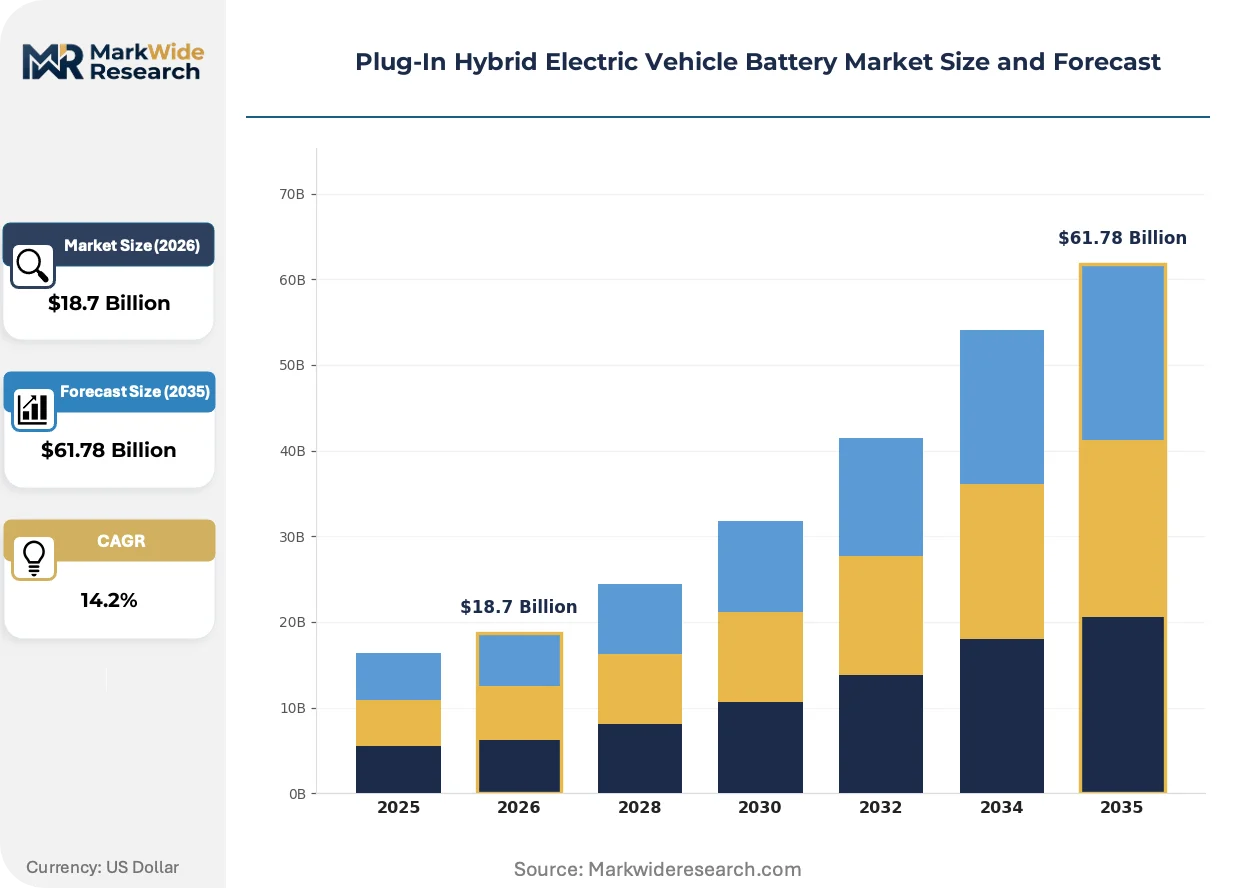
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer Application: Personal Vehicles, Commercial Fleets, Utility Vehicles, Delivery Vans Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Maintenance Type: Routine Inspections, Replacement Batteries, Repair Services, Upgrade Services |
| Companies Covered | Panasonic Holdings Corporation, BYD Company Ltd, Contemporary Amperex Technology Co. Limited, LG Chem Ltd, Samsung SDI Co. Ltd, Exide Industries Ltd, EnerSys, Gotion High Tech Co. Ltd, Amperex Technology Co. Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plug-In Hybrid Electric Vehicle Battery Market Trends and Innovations
Dual-mode powertrain architectures are forcing battery engineers to optimize for partial-state-of-charge cycling durability rather than full-depth cycling, rewiring cell chemistry roadmaps and warranty structures simultaneously.
Blade-style lithium-iron-phosphate cells are electrifying commercial van platforms by eliminating cobalt content and enabling prismatic formats that integrate directly into vehicle floor pans. European delivery fleet operators are specifying these configurations for 150,000-cycle durability guarantees. The technology is electrifying procurement criteria away from energy density toward total cost of ownership metrics.
The US EPA's revised tailpipe standards for model year 2027-2032 are tightening fleet-average CO2 thresholds, compelling light-truck manufacturers to expand PHEV offerings beyond compliance-car volumes. IRA consumer tax credits now require North American assembly and critical mineral sourcing, reshaping cell supplier qualification processes. Domestic OEMs are responding by localizing cathode active material production to secure credit eligibility.
Fleet procurement departments are consolidating battery supplier rosters from 6-8 vendors to 2-3 strategic partners, exchanging volume commitments for price transparency and dedicated engineering support. This concentration is displacing spot-market purchasing in municipal and corporate fleet segments. The shift is most pronounced in Germany and the Netherlands, where leasing companies bundle charging infrastructure with battery service contracts.
Plug-In Hybrid Electric Vehicle Battery Market Segmentation
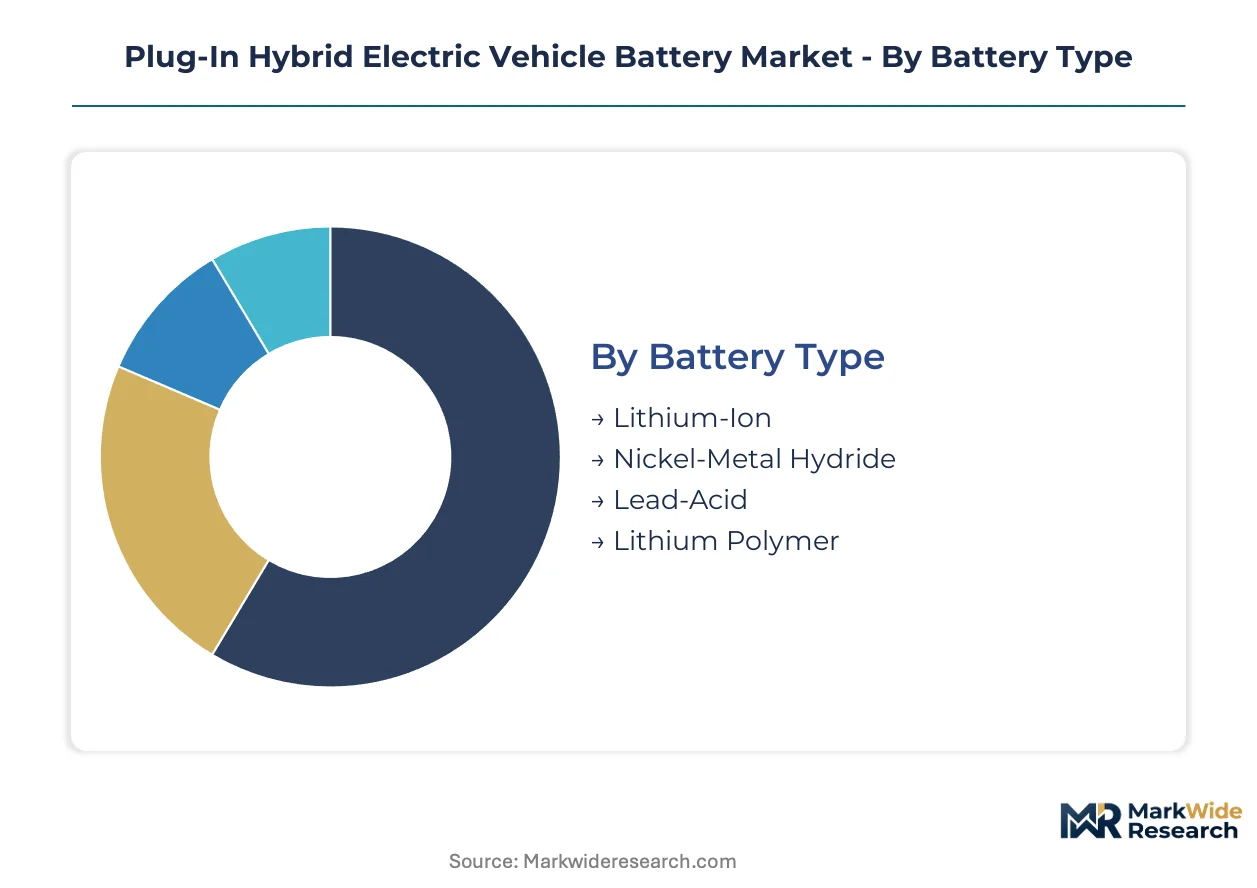
Segmentation in the PHEV battery market reveals how procurement priorities diverge between cost-optimized passenger applications and durability-focused commercial deployments. Understanding these splits enables suppliers to align cell chemistry roadmaps with distinct warranty and performance requirements.
Battery Type:
Lithium-ion platforms dominate volume production while alternative chemistries occupy specific durability or cost niches.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathode formulations deliver 250+ Wh/kg energy density with liquid electrolyte architectures. Demand concentrates in China's Yangtze River Delta manufacturing corridor, where CATL and BYD anchor gigascale production for domestic OEM compliance with MIIT credit mandates.
- Lithium Polymer:Gel electrolyte configurations enable flexible form factors and reduced thermal management overhead. European premium passenger segments specify these for packaging efficiency in floor-integrated modules, driven by ECE R100 safety certification requirements.
- Nickel-Metal Hydride:Mature chemistry retains position in cost-sensitive mild-hybrid conversions where plug-in range requirements remain minimal. Toyota's captive production network sustains limited procurement volumes for legacy platform continuity.
- Lead-Acid:Auxiliary power unit applications and aftermarket starter battery replacements persist in emerging market retrofit segments. India's FAME-II subsidy exclusions for lead-based chemistries are compressing addressable demand.
Mature deployment sits with Nickel-Metal Hydride. Newer deployment is concentrated in Lithium-Ion.
Application:
Fleet procurement patterns separate depot-charging economics from residential overnight charging infrastructure.
- Commercial Fleets:Depot-charged logistics operators specify 15-25 kWh packs with 150,000-cycle durability guarantees. Municipal procurement in Germany and the Netherlands bundles charging infrastructure with battery service contracts, displacing spot-market purchasing.
- Delivery Vans:Last-mile operators prioritize 8-12 kWh configurations balancing urban low-emission zone compliance with payload preservation. European leasing companies consolidate supplier rosters to 2-3 strategic partners in exchange for price transparency.
- Personal Vehicles:Consumer tax credit eligibility under IRA North American assembly requirements is reshaping OEM supplier qualification. Domestic cathode active material localization secures credit compliance for light-truck PHEV offerings.
- Utility Vehicles:Agricultural and construction equipment applications demand enhanced vibration tolerance and IP67 ingress protection. Japanese OEMs specify prismatic cell formats from Samsung SDI for reliability in off-highway duty cycles.
Volume concentration tracks Commercial Fleets. Margin expansion concentrates in Delivery Vans.
Capacity:
Regulatory thresholds and route economics determine optimal kWh specifications across passenger and commercial segments.
- High Capacity:20-25 kWh usable configurations enable 80+ km electric-only range, satisfying China's NEV credit system thresholds without combustion assist. European OEMs stretch specifications beyond regulatory minimums to qualify for CO2 fleet target compliance.
- Medium Capacity:12-18 kWh packs balance cell cost against daily driving cycle coverage for suburban passenger applications. US EPA tailpipe standards for model years 2027-2032 are expanding procurement of this tier for light-truck electrification.
- Low Capacity:8-12 kWh systems serve urban two-wheeler and three-wheeler conversions under India's FAME-II subsidy extension. Cost-per-kWh sensitivity dominates procurement criteria in price-constrained emerging markets.
- Ultra High Capacity:Experimental 30+ kWh prototypes target commercial V2G-enabled fleet contracts where bidirectional charging monetizes grid services. Solid-state electrolyte convergence promises 400+ Wh/kg density for next-generation platform wins.
Engineering investment concentrates in High Capacity. Ultra High Capacity prototypes are climbing the fastest toward commercialization.
Maintenance Type:
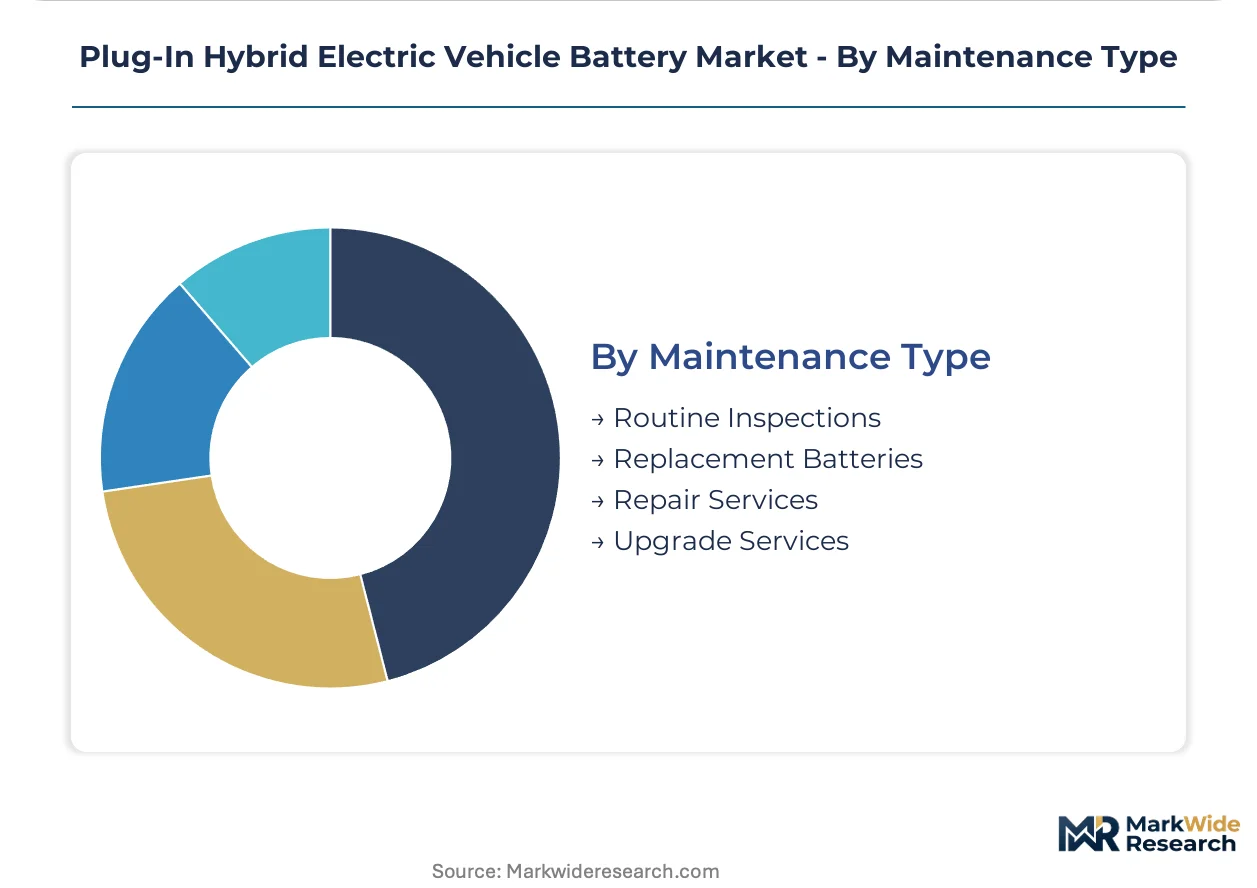
Service revenue models separate warranty-covered replacement from aftermarket upgrade opportunities.
- Replacement Batteries:End-of-life cell degradation drives 8-10 year replacement cycles in high-mileage commercial applications. European F-Gas Regulation and REACH chemical restrictions complicate end-of-life handling and second-life repurposing logistics.
- Upgrade Services:Capacity expansion retrofits and battery management system firmware updates extend vehicle service life. V2G-enabled fleet contracts create attach-rate opportunities for bidirectional charging infrastructure integration.
- Routine Inspections:Thermal runaway prevention protocols and state-of-health diagnostics dominate depot-based fleet maintenance. GB/T charging certification requirements in China mandate 6-9 month validation cycles for diagnostic equipment.
- Repair Services:Module-level replacement and cell balancing address isolated degradation without full pack replacement. Korean and Japanese prismatic cell supply concentration creates single-source risk for European repair network parts availability.
Revenue stability sits with Replacement Batteries. Upgrade Services are gaining share fastest as V2G deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zone concentrates cell manufacturing capacity for PHEV battery production. Germany's Rhine-Ruhr industrial corridor anchors European cathode material processing. The United States IRA tax credit zones are localizing assembly operations to secure consumer incentive eligibility.
China
MIIT credit mandates require domestic OEMs to accumulate new energy vehicle credits, expanding procurement of 15-25 kWh PHEV packs. GB/T charging standards govern product certification with 6-9 month validation cycles for interoperability testing. The Yangtze River Delta manufacturing corridor hosts CATL and BYD gigascale production facilities serving compliance-driven fleet demand.
Germany
Commercial fleet operators consolidate supplier rosters to 2-3 strategic partners for price transparency and engineering support. ECHA REACH chemical restrictions force reformulation of electrolyte additives, extending qualification timelines. The Rhine-Ruhr industrial corridor concentrates cathode active material processing for European OEM supply chains.
United States
IRA consumer tax credits require North American assembly and critical mineral sourcing, reshaping supplier qualification. EPA tailpipe standards for model years 2027-2032 tighten fleet-average CO2 thresholds for light-truck electrification. Michigan and Ohio industrial zones localize cathode production to secure credit eligibility for domestic OEM platforms.
South Korea
Prismatic cell producers dominate high-reliability formats for European OEM qualification, creating supply concentration risk. Korean manufacturers face qualification delays from China's GB/T certification protocols for non-domestic suppliers. The Seoul Capital Area anchors R&D investment in solid-state electrolyte convergence for next-generation density targets.
India
FAME-II subsidy extensions for electric and strong-hybrid vehicles open procurement channels for 8-12 kWh PHEV packs in two-wheeler conversions. BIS certification requirements govern domestic product standards for emerging market retrofit segments. Maharashtra and Gujarat industrial corridors concentrate battery assembly for price-sensitive commercial vehicle applications.
Plug-In Hybrid Electric Vehicle Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration favoring captive producers in high-volume contracts and independent suppliers occupying premium reliability niches. The supplier base concentrates around three strategic archetypes: integrated mining-to-module operators, cell-to-pack architecture specialists, and prismatic format reliability leaders. Capacity expansion and strategic partnerships dominate competitive moves as OEMs consolidate vendor rosters.
Within the integrated operator tier, BYD Company Ltd and Contemporary Amperex Technology Co. Limited exemplify backward integration strategies controlling margin capture from raw material through vehicle assembly. Samsung SDI Co. Ltd occupies a position among prismatic cell specialists serving premium European OEM supply chains. These three anchors represent divergent pathways to qualification in tightening regulatory environments across China, Europe, and North America.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| BYD Company Ltd |
| Contemporary Amperex Technology Co. Limited |
| LG Chem Ltd |
| Samsung SDI Co. Ltd |
| Exide Industries Ltd |
| EnerSys |
| Gotion High Tech Co. Ltd |
| Amperex Technology Co. Limited |
| Others |
Pricing and Supply Chain Analysis
LME cobalt price volatility cascades through cathode active material costs into tiered contract structures, compressing margins on long-term supply agreements while spot-market premiums widen for urgent procurement.
Pricing Analysis
Short lead-time premiums of 15-25% apply to qualified cell deliveries under 90 days, while excess inventory liquidates at spot discounts. Contract-based long-term offtake dominates procurement for commercial fleets, with price differentiation driven by volume scale and UL9540A thermal runaway certification tier. Pricing pressure stems from nickel and cobalt feedstock cost compression in NMC 811 formulations. Municipal fleet operators exhibit highest price sensitivity; European premium OEMs show least sensitivity due to reliability-weighted sourcing criteria.
Supply Chain Analysis
Dual-sourcing mandates from European OEMs require qualification of at least two prismatic cell suppliers per platform, forcing Korean and Japanese producers to expand capacity. Manufacturing concentrates in China, South Korea, and Japan, with cathode precursor processing anchored in the DRC, Indonesia, and Australia. The supply chain draws from lithium carbonate, nickel sulfate, and cobalt hydroxide inputs. Single-source vulnerability persists in high-reliability prismatic formats. Distribution runs through OEM direct contracts and Tier 1 system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated producers as MIIT credit arbitrage and IRA domestic content rules force out module-level assemblers lacking captive cathode supply.
For Market Incumbents: To counter cobalt price volatility eroding NMC 811 margins, secure offtake agreements with Indonesian nickel-cobalt integrated producers and accelerate LFP chemistry qualification for commercial fleet contracts. Cell-to-pack architecture investment preserves cost leadership against emerging Chinese competitors.
For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer white-space entry for 8-12 kWh retrofit packs in India's FAME-II two-wheeler segment and European last-mile van conversions. Target depot-charging logistics operators with battery-as-a-service pricing and integrated telematics.
For Investors and Strategic Acquirers: Distressed-cycle entries favor solid-state electrolyte specialists in South Korea and Japan with sulfide-ceramic separator IP. Five-to-ten year viability hinges on next-generation platform wins. Monitor GB/T certification approval timelines for non-domestic suppliers as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Scale-Up | CATL and BYD compress module assembly costs, forcing incumbent retooling. |
| Cathode Active Material Localization | Michigan and Ohio facilities secure IRA credit eligibility for domestic OEMs. |
| Prismatic Cell Reliability Certification | Samsung SDI maintains premium positioning in European CO2 compliance supply chains. |
| V2G-Enabled Fleet Contracts | Bidirectional charging infrastructure monetizes grid services for commercial operators. |
| Solid-State Electrolyte Convergence | Sulfide-based ceramic separators promise 400+ Wh/kg density for next-generation platforms. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier 1 battery system procurement leads, cathode material R&D heads, and commercial fleet operations managers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from MIIT production databases, EPA certification filings, customs trade records, and IHS Markit vehicle registration data. Bottom-up cell shipment tallies and top-down OEM platform mix analysis triangulate volume estimates.
Rate-of-change decomposition separates volume growth from value-per-kWh erosion across the projection horizon. Segmentation models incorporate battery chemistry, vehicle class, capacity tier, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves calibrated to policy mandate timelines and fleet replacement cycles. Forecast inputs include MIIT credit price trajectories and IRA critical mineral sourcing thresholds.
Inputs from OEM procurement systems and cathode producer order backlogs were available through the study window; gaps in solid-state prototype commercialization timelines introduce uncertainty bands around ultra-high capacity adoption curves. Deviation in China's NEV credit system stringency or EPA tailpipe standard enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
Africa Electric Vehicle Market