
 Commercial Vehicle (CV) Active Power Steering Market | 2026-2036
Commercial Vehicle (CV) Active Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle (CV) Active Power Steering Market Outlook
The EU Green Deal is expanding the addressable market for active power steering as commercial vehicle manufacturers face binding CO2 reduction mandates across European fleets. Robert Bosch GmbH leverages its integrated sensor-to-actuator portfolio to capture value from electrification transitions. ZF Friedrichshafen AG anchors its position through manufacturing scale across German and Czech production hubs. JTEKT Corporation competes on precision manufacturing strength in rack-and-pinion systems for heavy duty applications.
Commercial Vehicle (CV) Active Power Steering refers to electronically augmented steering systems that modulate hydraulic or electric assist based on vehicle speed, load, and lane-keeping inputs, typically operating at voltages from 12V to 48V in modern architectures and incorporating torque sensors with sub-degree accuracy for real-time feedback. Its primary purpose is to reduce driver physical effort while enabling advanced driver assistance functions such as lane centering and emergency steering in commercial fleets. Electric Steering leads product type adoption as fleets prioritize weight reduction and energy recuperation over traditional hydraulic architectures. Variable Ratio technology dominates the technology dimension by offering speed-sensitive responsiveness that improves maneuverability at low speeds and stability at highway velocities. Heavy Duty Trucks represent the most concentrated end user segment due to the direct correlation between steering assist sophistication and operator retention in long-haul logistics.
NHTSA in the United States mandates electronic stability control and steering performance standards that effectively require active assist architectures in new commercial vehicles above specified gross vehicle weight ratings. ECE R79 in Europe governs steering equipment approval, forcing alignment between active steering logic and automated lane-keeping system certifications. Japan's METI promotes next-generation mobility standards that incentivize steering electrification through energy efficiency benchmarks. Stakeholders must monitor divergence between regional cybersecurity requirements for steer-by-wire architectures and the current validation protocols governing mechanical backup systems.
Market Dynamics
The EU Green Deal's binding CO2 reduction mandates are forcing commercial vehicle manufacturers to abandon hydraulic steering architectures in favor of lighter electric systems, compressing supplier transition timelines and reshaping component sourcing patterns across European production clusters.
Growth Catalysts
- ECE R79 alignment requirements:European steering equipment approval standards now mandate compatibility between active steering logic and automated lane-keeping certifications, compelling OEMs to upgrade system architectures.
- Long-haul logistics operator retention:Fleet managers in Germany and Poland are prioritizing driver fatigue reduction through speed-sensitive steering assist, directly linking steering sophistication to workforce stability.
- 48V electrical architecture proliferation:Heavy duty truck electrification roadmaps are standardizing on higher-voltage steering systems that enable energy recuperation during highway operation.
Market Restraints
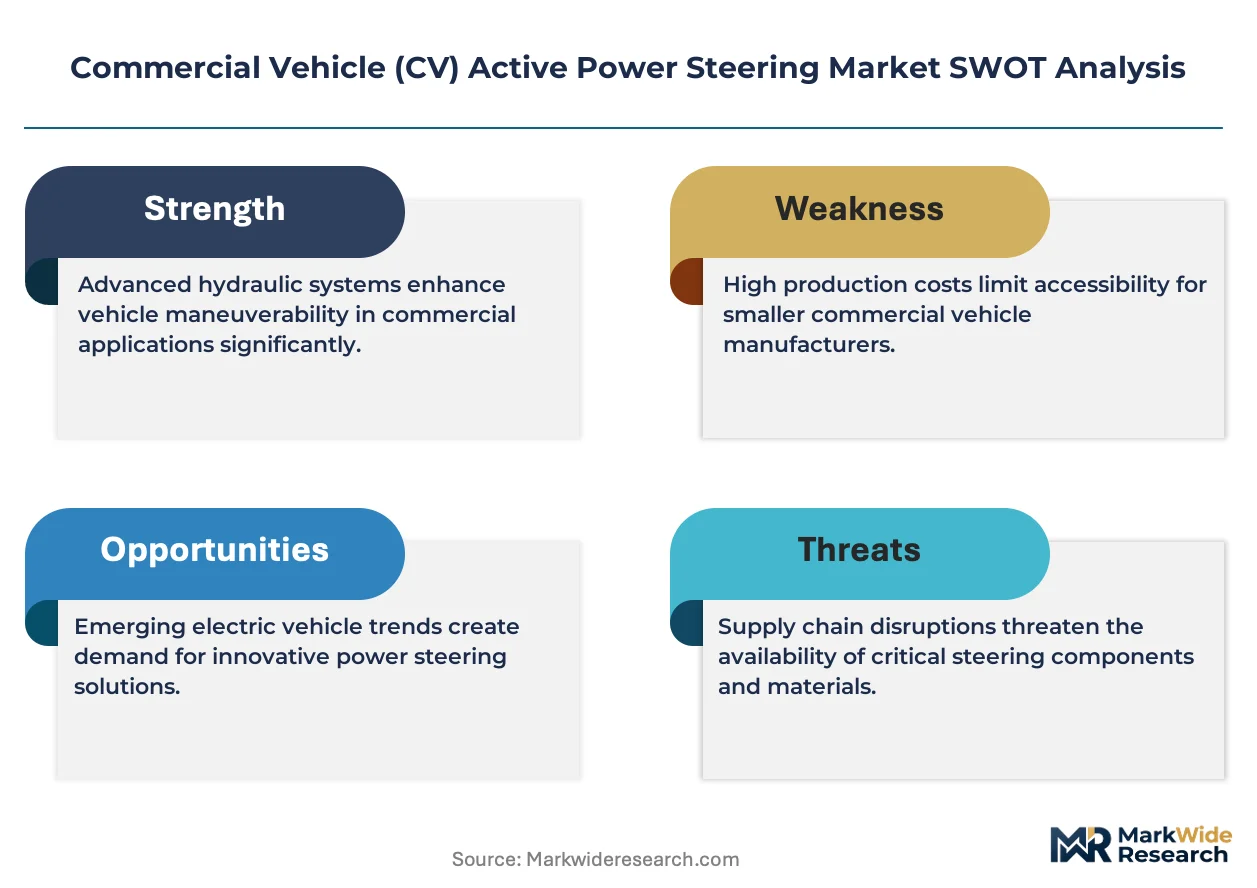
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese supply chains are compressing margins for permanent magnet-based electric steering motor producers.
- Steer-by-wire validation gaps:ISO 26262 functional safety certification timelines for fully electric steering without mechanical backup are extending development cycles by 18-24 months.
- Hydraulic system installed base:Existing fleet maintenance infrastructure and technician training investments create switching friction for incumbent hydraulic architecture users.
Strategic Opportunities
- Czech Republic manufacturing expansion:Central European production hubs offer lower labor costs and proximity to German OEM assembly plants for steering component suppliers.
- Retrofit aftermarket channel:Second-life active steering system installation for 5-7 year old heavy duty trucks represents an underserved demand pool in Eastern European logistics corridors.
- AI-assisted predictive maintenance:Integration of torque sensor data with fleet telematics platforms enables subscription-based steering health monitoring services.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineers with ISO 26262 ASIL-D certification command premium compensation and face poaching from autonomous driving divisions.
- Legacy CAN bus integration complexity:New electric steering controllers must maintain backward compatibility with decade-old vehicle communication protocols without compromising real-time performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle (CV) Active Power Steering Market |
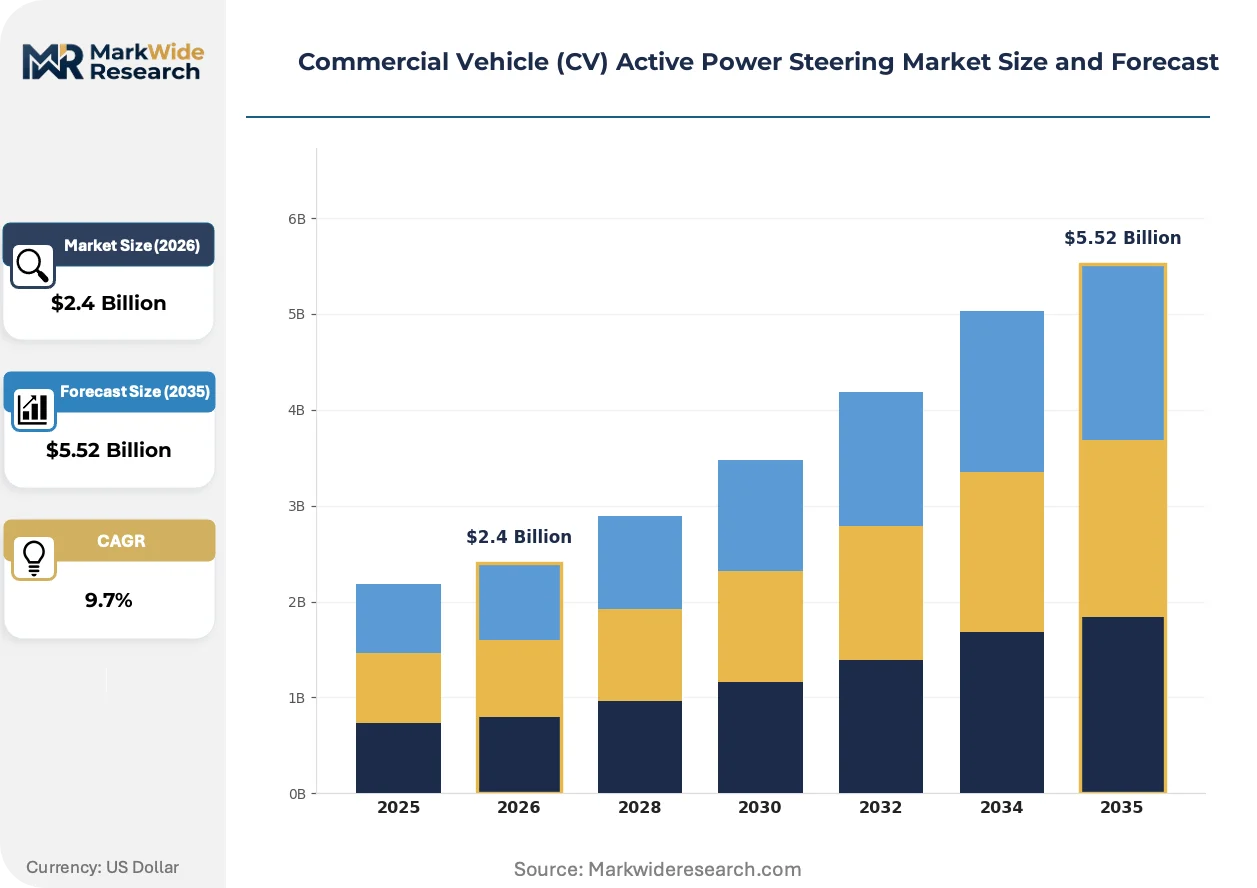
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Steering, Electric Steering, Electro-Hydraulic Steering, Others Technology: Variable Ratio, Closed Loop, Open Loop, Direct Drive End User: Heavy Duty Trucks, Light Duty Trucks, Buses, Vans Application: On-Road Vehicles, Off-Road Vehicles, Specialized Vehicles, Emergency Vehicles |
| Companies Covered | Robert Bosch GmbH, JTEKT Corporation, ZF Friedrichshafen AG, Mando Corporation, Nexteer Automotive Corporation, Knorr-Bremse Commercial Vehicle Systems GmbH, Thyssenkrupp AG, NSK Ltd., Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle (CV) Active Power Steering Market Strategic Shifts
Steering electrification is absorbing capital and engineering resources across the commercial vehicle supply base, with ripple effects compressing hydraulic component demand and accelerating software-defined functionality roadmaps.
Dual-motor redundant electric steering actuators are absorbing the safety-critical redundancy requirements previously served by hydraulic-electric hybrid architectures. Heavy duty truck OEMs in Germany and Sweden are adopting these systems for SAE Level 2+ lane-keeping applications. The technology is absorbing development budgets that previously funded incremental hydraulic pump efficiency improvements, forcing tier-two suppliers to pivot or exit.
NHTSA's updated electronic stability control mandates for commercial vehicles above 26,000 pounds gross vehicle weight are accelerating steering sensor standardization. The regulation forces alignment between stability control modules and active steering torque overlay systems. Heavy duty truck segments serving US long-haul routes are responding by pre-integrating steering and braking control domains during platform development.
Fleet procurement departments are consolidating steering system sourcing decisions at the corporate level rather than delegating to regional maintenance managers. This centralization is displacing fragmented aftermarket purchasing through authorized dealer networks. The pattern is most visible in German and Dutch logistics conglomerates operating cross-border European routes.
Commercial Vehicle (CV) Active Power Steering Market Segmentation
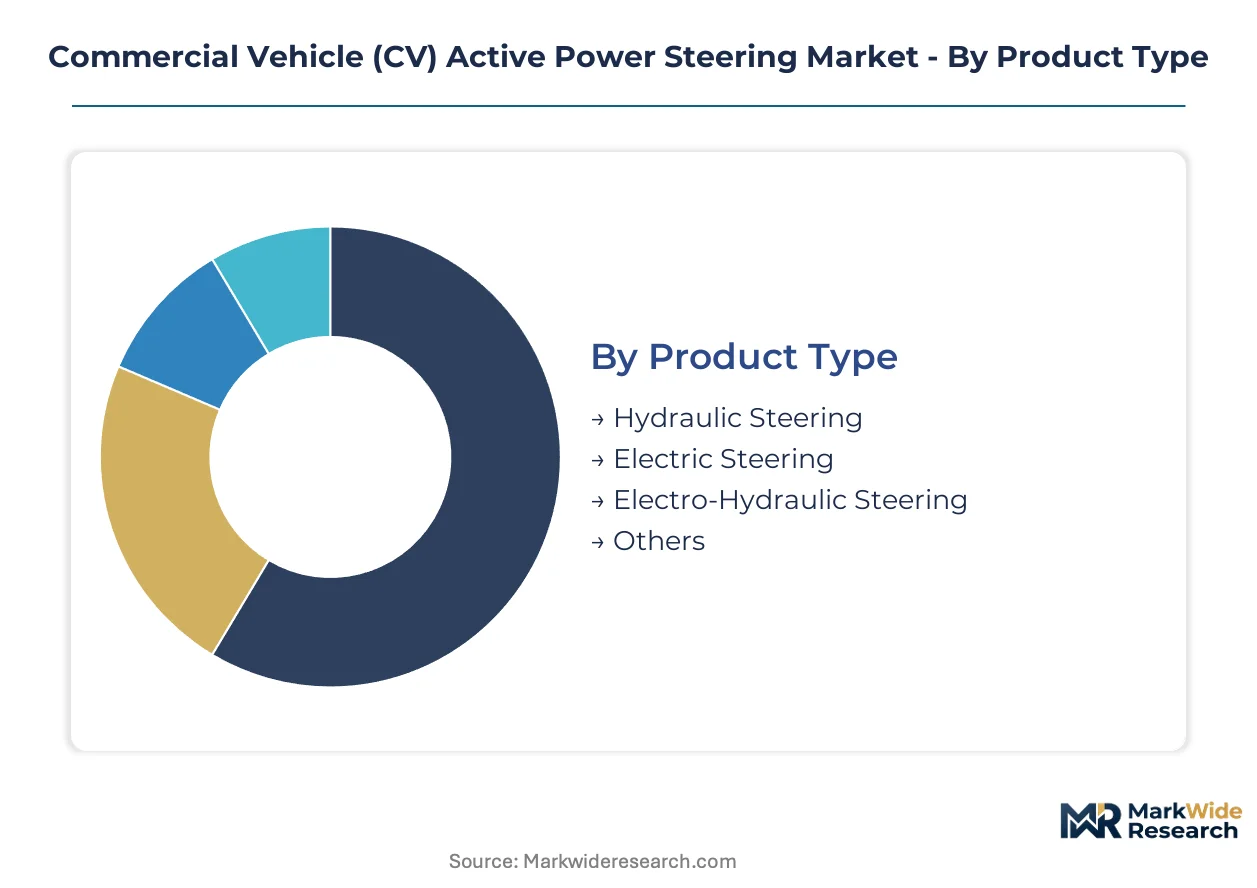
Segmentation in the CV Active Power Steering Market reveals how electrification roadmaps, duty-cycle requirements, and regulatory compliance reshape purchasing priorities across fleet operators. Understanding these divisions exposes where component suppliers must align R&D investment with diverging technical specifications and total-cost-of-ownership calculations.
Product Type:
Volume deployment concentrates in legacy hydraulic architectures, while premium positioning belongs to fully electric systems that command higher per-unit pricing but deliver fuel savings and ADAS enablement.
- Electric Steering:Motor-driven rack or column assist eliminates hydraulic pumps and fluid circuits, cutting parasitic losses. Demand clusters in German long-haul fleets facing EU Green Deal CO2 penalties, where every percentage point of fuel efficiency affects compliance margins.
- Hydraulic Steering:Engine-driven pumps with variable displacement valves remain entrenched in price-sensitive segments and emerging markets with limited 48V infrastructure. Eastern European logistics operators prioritize lowest acquisition cost over lifecycle efficiency, preserving installed base relevance.
- Electro-Hydraulic Steering:Hybrid architecture pairs electric motor control with hydraulic actuation, bridging legacy fleets toward electrification without full platform redesign.
- Others:Experimental steer-by-wire prototypes and hydraulic-electric retrofit kits serve niche validation programs and aftermarket upgrade paths.
Mature deployment sits with Hydraulic Steering. Newer deployment is concentrated in Electric Steering.
Technology:
Application complexity determines technology selection, with highway automation requirements forcing convergence toward closed-loop precision while urban maneuverability favors ratio variability.
- Variable Ratio:Rack-and-pinion geometry changes effective steering ratio based on vehicle speed, tightening response at parking speeds and stabilizing lane-keeping at highway velocity. Polish and Dutch fleet operators specify this technology for cross-border routes mixing urban distribution with motorway transit.
- Closed Loop:Torque feedback sensors enable real-time assist modulation and direct integration with lane-keeping algorithms. Swedish truck OEMs mandate closed-loop architectures for SAE Level 2+ highway pilot functions, absorbing development resources from open-loop alternatives.
- Open Loop:Pre-mapped assist curves without real-time feedback suit cost-constrained light commercial vehicles where ADAS penetration remains minimal.
- Direct Drive:Elimination of mechanical reduction stages between motor and rack delivers precision for autonomous emergency steering, though validation timelines extend certification cycles.
Technology maturation clusters around Variable Ratio implementations. Steepest expansion trajectory belongs to Closed Loop as automation mandates harden.
End User:
Fleet scale and duty intensity create diverging specifications, with heavy-duty applications absorbing development investment that later cascades to lighter segments.
- Heavy Duty Trucks:Gross vehicle weights above 15 tonnes demand steering columns rated for sustained high-torque operation and redundant actuator architectures. German logistics conglomerates operating 24-hour long-haul rotations specify these systems to reduce driver injury claims and improve retention.
- Light Duty Trucks:Urban delivery vehicles below 7.5 tonnes prioritize compact packaging and 12V compatibility, with electric steering penetration climbing fastest in last-mile electrification programs.
- Buses:Low-floor city transit configurations require extreme steering angles and sustained low-speed assist, preserving hydraulic-electric hybrid demand.
- Vans:Parcel delivery fleets specify standardized electric steering modules across multiple chassis lengths, driving procurement consolidation at fleet headquarters.
Specification leadership originates in Heavy Duty Trucks. Volume scaling is accelerating fastest in Vans as e-commerce logistics expand.
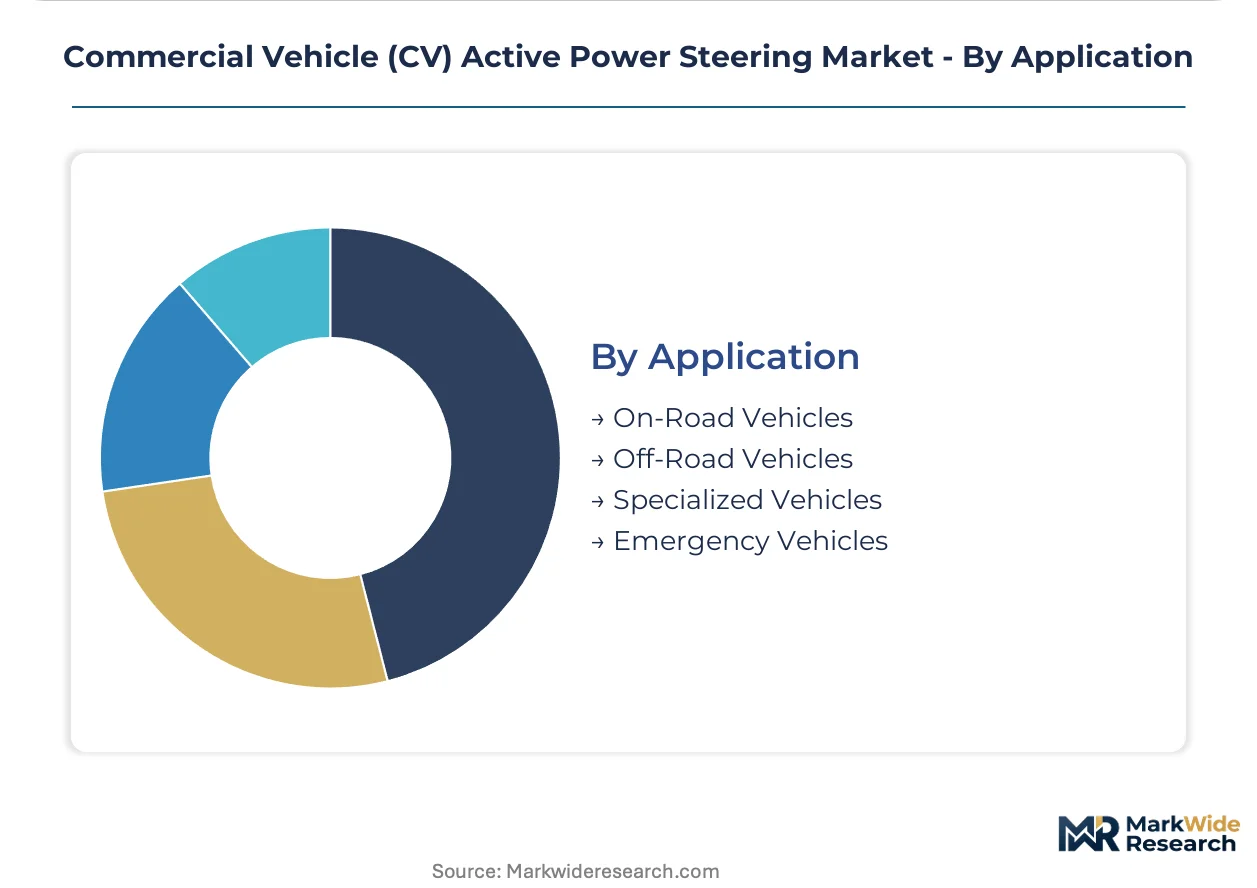
Application:
Operating environment dictates durability requirements and regulatory exposure, with on-road compliance complexity creating technology gaps that off-road and specialized segments exploit differently.
- On-Road Vehicles:Highway and urban commercial transport faces binding emissions and safety regulations across US, European, and Japanese jurisdictions. NHTSA stability control mandates and ECE R79 steering approval standards force active assist architecture adoption regardless of fleet size.
- Off-Road Vehicles:Construction and agricultural equipment operates outside highway regulations, allowing hydraulic retention and slower electrification timelines. Czech and Slovak manufacturers serving Central European contractors prioritize field durability over energy efficiency.
- Specialized Vehicles:Refuse collection, concrete mixing, and tanker applications impose unique steering load profiles that demand customized actuator sizing.
- Emergency Vehicles:Fire apparatus and ambulance chassis require fail-operational redundancy and extreme maneuverability, absorbing premium pricing for dual-motor electric architectures.
Regulatory pressure concentrates heaviest on On-Road Vehicles. Technical differentiation is widening fastest in Emergency Vehicles as safety-critical specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors commercial vehicle active power steering demand through Mercedes-Benz Trucks and MAN production facilities, with component suppliers clustering along the Neckar Valley corridor to serve electrification roadmaps.
Germany
Long-haul logistics operators in Bavaria and Baden-Württemberg specify electric steering systems to meet EU Green Deal CO2 reduction mandates. KBA enforces ECE R79 steering equipment approval standards that mandate automated lane-keeping compatibility. Manufacturing concentrates around Stuttgart and Munich, where Bosch and ZF operate integrated sensor-to-actuator production facilities.
United States
Fleet operators across the Midwest and Southeast prioritize driver retention through fatigue-reducing steering assist in heavy-duty long-haul routes. NHTSA mandates electronic stability control integration with active steering torque overlay systems for vehicles above 26,000 pounds gross vehicle weight. Production clusters in Michigan and Ohio, where Detroit-based OEMs pre-integrate steering and braking control domains during platform development.
China
Domestic heavy-duty truck manufacturers in Shandong and Hubei provinces accelerate electric steering adoption to meet MIIT energy efficiency benchmarks for commercial fleets. GB standards govern steering system safety and electromagnetic compatibility for electrified architectures. Manufacturing concentrates in the Yangtze River Delta, where component suppliers serve FAW and Dongfeng assembly plants.
Japan
Isuzu and Hino integrate active steering with lane-keeping assist for highway logistics corridors connecting Tokyo to Osaka. METI promotes next-generation mobility standards that incentivize steering electrification through fleet energy efficiency benchmarks. Engineering resources cluster in Kanagawa and Aichi prefectures, where JTEKT maintains precision manufacturing operations for rack-and-pinion systems.
Sweden
Volvo Trucks and Scania specify closed-loop torque feedback architectures for SAE Level 2+ highway pilot functions across Nordic logistics routes. EU Green Deal emissions targets compel abandonment of hydraulic steering in favor of lighter electric systems. Development concentrates in Gothenburg and Södertälje, where OEMs validate dual-motor redundant actuators for safety-critical automation.
Commercial Vehicle (CV) Active Power Steering Market Competitive Environment
The competitive structure tilts toward diversified automotive suppliers with integrated electromechanical portfolios. Tier-one system integrators dominate through manufacturing scale and OEM platform relationships, while specialized steering component manufacturers occupy niche precision segments. Three archetypes prevail: full-system integrators with sensor-to-actuator capabilities, precision gear and bearing specialists, and brake-system diversifiers extending into steering. Consolidation pressure is accelerating through strategic partnerships for 48V architecture development and geographic expansion into Central European production hubs.
Among German-based diversified suppliers, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify full-system integration archetypes with broad sensor and actuator portfolios. JTEKT Corporation represents the precision manufacturing specialist tier, occupying a position in rack-and-pinion systems for heavy-duty applications. These three companies anchor the competitive landscape through distinct capability positioning rather than overlapping market pursuit.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| Mando Corporation |
| Nexteer Automotive Corporation |
| Knorr-Bremse Commercial Vehicle Systems GmbH |
| Thyssenkrupp AG |
| NSK Ltd. |
| Schaeffler AG |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ISO 26262 ASIL-D validated systems and basic electric assist modules manifests in pricing spreads exceeding two-to-one, with premium architectures commanding value-based premiums tied to fleet uptime guarantees while commodity hydraulic-electronic hybrids compete on per-unit procurement metrics. This bifurcation feeds directly into supply chain configuration, where ASIL-D qualified suppliers in Germany and Japan maintain captive magnet and sensor production while standard-tier vendors source from distributed Chinese component markets.
Pricing Analysis
Uptime-guarantee contracting anchors value-based pricing for heavy-duty fleet operators, with ASIL-D certified electric steering systems pricing against fuel savings and driver retention outcomes rather than hardware cost-plus. Price differentiation rests on functional safety certification tier and magnet grade specification, with rare earth content separating premium from standard offerings. Cost compression in the standard tier intensifies as Chinese motor suppliers expand 48V actuator production. Eastern European logistics operators exhibit highest price sensitivity, prioritizing lowest acquisition cost over lifecycle efficiency.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth magnet supply, where neodymium and dysprosium refining concentration creates exposure to export restriction and price volatility. Component sourcing draws from Germany for precision rack-and-pinion manufacturing, China for permanent magnet motors and electronic controllers, and Japan for torque sensor fabrication. Tariff exposure on magnet imports into European assembly plants represents the dominant structural risk. Distribution runs through authorized dealer networks serving OEM platform engineering teams and fleet procurement headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CV active power steering sector occupies a technology-transition phase where electric architectures displace hydraulic systems under regulatory and efficiency pressure. Fleet electrification roadmaps and automation mandates are compressing supplier transition timelines and reshaping competitive positioning.
For Market Incumbents: Anticipate margin compression from Chinese motor suppliers entering the standard-tier 48V segment by securing captive magnet supply through backward integration into rare earth processing partnerships. Defensive consolidation around ASIL-D certification capabilities and software-defined functionality roadmaps protects against commodity erosion in hydraulic-electronic hybrid architectures. For New Entrants and Emerging Players: Launch via aftermarket retrofit channels targeting 5-7 year old heavy-duty trucks in Polish and Czech logistics corridors, where fleet operators seek fatigue-reduction upgrades without full platform replacement. The retrofit segment remains underpenetrated by incumbent system integrators focused on OEM platform business. For Investors and Strategic Acquirers: Re-rating potential sits with precision gear and bearing specialists possessing ISO 26262 certification capabilities given accelerating OEM requirements for SAE Level 2+ steering redundancy. Long-term viability hinges on software-defined functionality integration and 48V architecture standardization. Monitor rare earth magnet price volatility as an inflection indicator for margin compression timing in electric motor supply.| Strategic Initiative | Industry Significance |
|---|---|
| 48V Architecture Standardization | Enables energy recuperation and dual-motor redundancy for German OEM automation roadmaps. |
| Rare Earth Magnet Supply Agreement | Secures dysprosium and neodymium feedstock against Chinese export restriction exposure. |
| ASIL-D Certification Investment | Unlocks safety-critical steering contracts with Volvo Trucks and Scania for highway pilot functions. |
| Retrofit Channel Partnership | Captures second-life demand from Eastern European fleet operators extending hydraulic platform service. |
| Software-Defined Vehicle Integration | Aligns steering control domains with braking and propulsion for NHTSA stability mandate compliance. |
Study Parameters
Trade databases, OEM production filings, and regulatory submission records formed the secondary backbone, supplemented by primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet maintenance managers. Bottom-up and top-down triangulation validated segment sizing across electric, hydraulic, and electro-hydraulic product architectures.
Bottom-up modeling aggregated content-per-vehicle assumptions across heavy-duty trucks, light-duty trucks, buses, and vans, while top-down verification cross-checked against vehicle production databases and steering system bill-of-materials estimates. CAGRs derived from regression analysis against EU Green Deal compliance timelines and NHTSA mandate implementation schedules. Forecast inputs included 48V electrical architecture penetration curves and rare earth magnet price indices.
The model assumes a particular technology adoption path; alternative pathways for steer-by-wire validation and mechanical backup elimination would alter the outlook. Forecasts reflect assumptions regarding regulatory mandate enforcement timing and fleet electrification investment cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Europe Van Market