
 Philippines Commercial Vehicles Market | 2026-2036
Philippines Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Commercial Vehicles Market Insights
Modular chassis configurations with swappable body types is broadening buyer choice in the Philippines commercial vehicle sector. Isuzu Philippines Corporation leverages its diesel engine heritage to sustain dominance in light-duty truck configurations for provincial distribution. Toyota Motor Philippines Corporation anchors its position through hybrid powertrain options that appeal to cost-conscious fleet operators navigating fuel price volatility. Hino Motors differentiates via dedicated bus chassis platforms engineered for the archipelago's steep terrain and stop-start urban corridors.
Commercial vehicles in the Philippines encompass motorized transport equipment engineered for goods carriage and passenger movement, typically featuring reinforced ladder-frame construction, gross vehicle weight ratings exceeding 3.5 tonnes, and powertrains calibrated for tropical humidity and frequent idling. Light-duty trucks lead volume as SMEs replace aging jeepneys and AUVs with purpose-built cargo platforms for last-mile delivery. Electric powertrains represent the fastest-growing fuel category, though diesel retains margin concentration in heavy-duty mining and construction applications where torque requirements and charging infrastructure gaps persist. Fleet operators as a customer segment command disproportionate negotiating leverage through volume procurement contracts and centralized maintenance programs.
The Department of Transportation's PUV Modernization Program mandates Euro 4 emission compliance and safety equipment fitment, reshaping procurement specifications for public transport operators. The Bureau of Product Standards enforces Philippine National Standards alignment with UN-ECE braking and lighting regulations, creating compliance cost barriers for smaller importers. Stakeholders must monitor how the Board of Investments' vehicle manufacturing incentive structures interact with rising Chinese EV platform competition to determine local assembly versus import strategies.
Market Dynamics
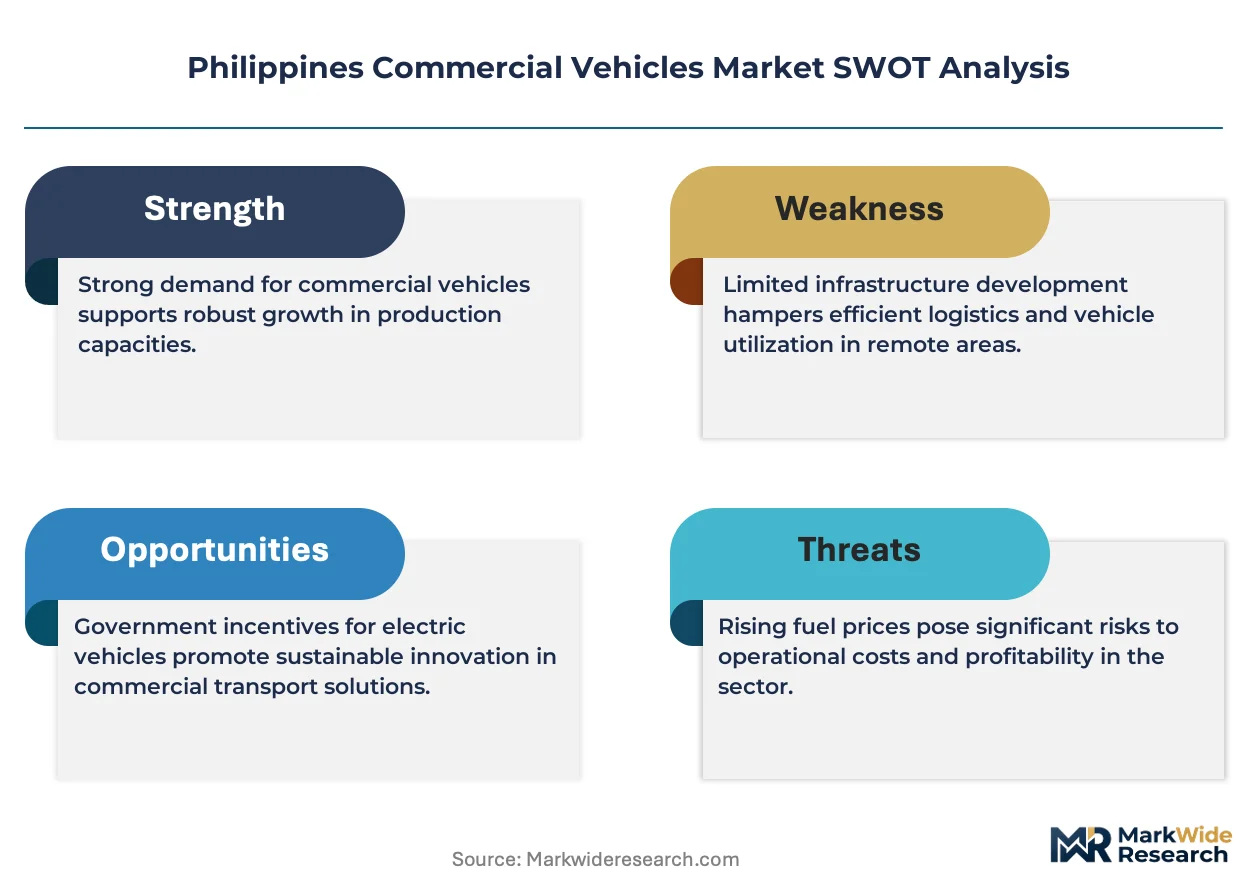
The Public Utility Vehicle Modernization Program is compressing replacement cycles for jeepney operators while e-commerce logistics operators scale fleet procurement across Luzon's fulfillment corridors. This dual demand pull from regulatory mandate and digital commerce infrastructure is restructuring procurement volumes and specifications simultaneously.
Growth Catalysts
- PUV Modernization Program:The Department of Transportation's Euro 4 emission mandate is forcing fleet turnover among 200,000+ aging jeepney units, creating concentrated demand for compliant minibus and midi-bus chassis.
- E-commerce fulfillment networks:Last-mile delivery operators across Metro Manila and CALABARZON are expanding light-duty truck procurement to serve warehouse-to-doorstep logistics density.
- Hybrid powertrain adoption:Fuel price volatility is accelerating fleet operator interest in dual-power configurations for urban distribution routes with frequent stop-start patterns.
Market Restraints
- Charging infrastructure gaps:Heavy-duty electric vehicle deployment faces range anxiety and depot charging limitations outside Metro Manila's power grid density.
- Euro 4 compliance costs:Smaller provincial operators lack capital reserves for engine upgrades and safety equipment fitment mandated by the Bureau of Product Standards.
- Steep terrain torque requirements:Mining and construction applications in the Cordillera and Mindanao highlands retain diesel dependency due to elevation gradients and payload demands.
Strategic Opportunities
- Visayas and Mindanao logistics corridors:Port modernization at Cebu and Cagayan de Oro is creating warehousing clusters with underpenetrated commercial vehicle service networks.
- Modular chassis-body configurations:Swappable cargo, passenger, and refrigerated body types enable single-platform fleet flexibility for multi-use operators.
- Board of Investments manufacturing incentives:Local assembly qualification through the Motor Vehicle Development Program reduces import duty exposure for qualifying producers.
Industry Challenges
- Technician training deficits:Hybrid and electric powertrain diagnostics require specialized skill sets that vocational institutions in provincial hubs have not scaled.
- Parts availability latency:Euro 4-compliant engine components and after-treatment systems face supply lead times that extend vehicle downtime for critical fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Commercial Vehicles Market |
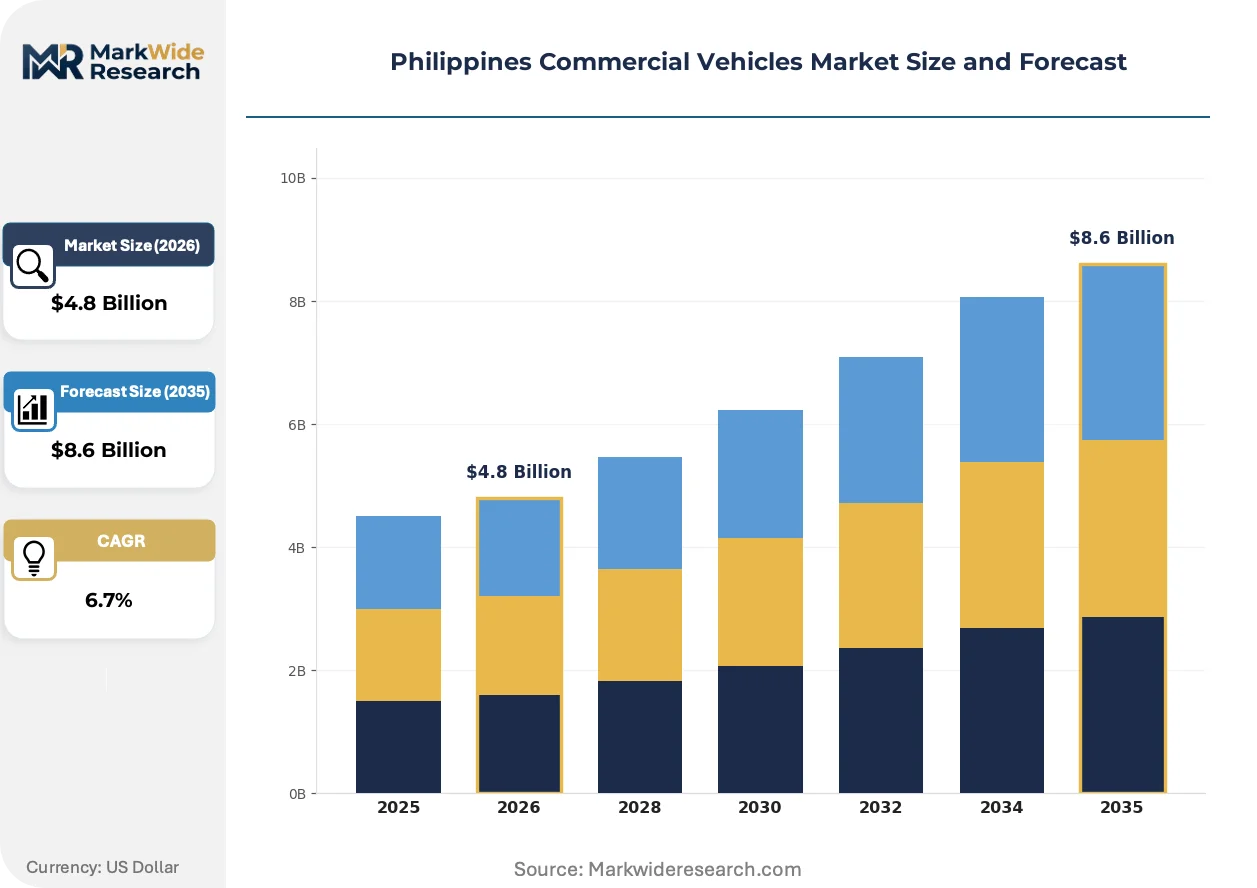
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty Trucks, Heavy Duty Trucks, Buses, Vans Fuel Type: Diesel, Gasoline, Electric, Hybrid Application: Transportation, Construction, Logistics, Public Transport Customer Type: Private Enterprises, Government Agencies, Fleet Operators, SMEs |
| Companies Covered | Isuzu Philippines Corporation, Hino Motors, Mitsubishi Motors Philippines Corporation, IVECO Group, Toyota Motor Philippines Corporation, Jiangling Motors Corporation Group, Foton Motor Philippines, Columbian Motor Corporation, Diamond Motor Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Commercial Vehicles Market Trends and Innovations
Telematics integration and alternative powertrain development are converging to reshape fleet management economics and vehicle specification priorities across Philippine commercial operators.
Telematics platforms with real-time fuel monitoring and predictive maintenance alerts are automating fleet oversight for logistics operators managing dispersed vehicle assets across Luzon's highway networks. Large-scale distributors are deploying these systems to compress maintenance scheduling intervals and reduce unplanned downtime. The technology is automating route optimization decisions that previously required manual dispatcher intervention.
The Department of Transportation's PUV Modernization Program is mandating franchise consolidation and vehicle age limits that eliminate pre-2010 jeepney units from revenue service. This regulatory compression is forcing cooperative operators to pool capital for compliant vehicle procurement or exit routes entirely. Urban corridors in Metro Manila and Cebu are experiencing the fastest fleet turnover as local government units enforce route rationalization.
Fleet operators are consolidating procurement authority through centralized purchasing agreements that displace traditional dealer-relationship buying. Large logistics and public transport cooperatives now negotiate direct manufacturer contracts with standardized maintenance provisions. This concentration is most visible among e-commerce fulfillment providers operating multi-hub networks across CALABARZON and Central Luzon.
Philippines Commercial Vehicles Market Segmentation
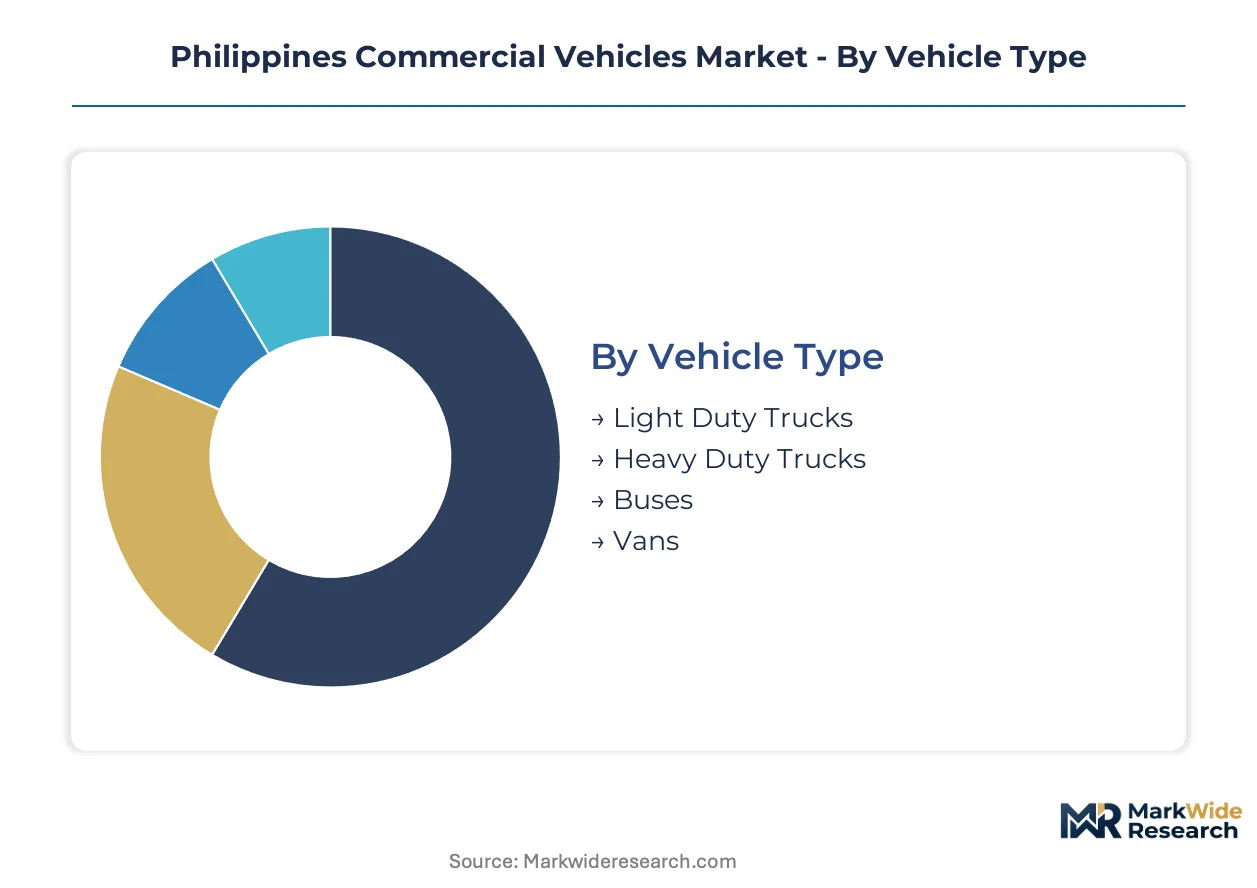
Segmentation in the Philippine commercial vehicle sector reveals how capital deployment, regulatory pressure, and logistics infrastructure interact to shape procurement patterns. Fleet operators and provincial distributors prioritize different vehicle specifications based on route terrain, payload requirements, and access to service networks across the archipelago.
Vehicle Type:
Capital intensity varies sharply across vehicle categories, with heavy-duty platforms demanding substantially higher upfront investment in chassis engineering and powertrain durability.
- Light Duty Trucks:Reinforced ladder-frame platforms with gross vehicle weight ratings between 3.5 and 7.5 tonnes, engineered for tropical humidity and frequent idling cycles. Metro Manila and CALABARZON logistics corridors concentrate replacement demand as e-commerce fulfillment operators retire aging jeepneys and AUVs for purpose-built cargo configurations.
- Heavy Duty Trucks:Mining and construction applications in the Cordillera and Mindanao highlands retain diesel dependency due to elevation gradients and payload demands exceeding 16 tonnes. Bureau of Product Standards enforcement of Philippine National Standards alignment with UN-ECE braking regulations elevates compliance costs for imported chassis.
- Buses:Public Utility Vehicle Modernization Program mandates are compressing replacement cycles for cooperative operators.
- Vans:Last-mile delivery fleets favor compact footprints for urban corridor navigation.
Light duty trucks absorb the bulk of installed capacity; electric and hybrid configurations within heavy duty platforms are expanding most quickly as depot charging infrastructure densifies.
Fuel Type:
Procurement decisions track fuel price volatility and charging infrastructure availability across Luzon's power grid density versus provincial coverage gaps.
- Diesel:Compression-ignition powertrains calibrated for high-torque applications in mining and construction retain margin concentration where charging infrastructure remains sparse. Cordillera and Mindanao highland operators depend on established fuel distribution networks.
- Electric:Battery-electric platforms with thermal management systems for tropical climates are gaining traction in Metro Manila fleet depots with centralized charging. Range anxiety and depot charging limitations outside Luzon's power grid density constrain heavy-duty deployment.
- Hybrid:Dual-power configurations appeal to cost-conscious fleet operators navigating stop-start urban distribution routes.
- Gasoline:Spark-ignition variants serve lighter payload applications with lower annual mileage requirements.
Diesel retains the largest share of heavy-duty applications; electric powertrains are climbing the fastest in light-duty urban logistics segments.
Application:
End-use concentration determines specification priorities, with public transport operators facing distinct regulatory timelines compared to private logistics fleets.
- Logistics:Warehouse-to-doorstep fulfillment networks across CALABARZON and Central Luzon drive standardized procurement for last-mile density. Fleet operators negotiate centralized purchasing agreements with predictive maintenance provisions.
- Public Transport:Jeepney cooperative operators pool capital for Euro 4-compliant minibus chassis or exit routes entirely under franchise consolidation mandates. Metro Manila and Cebu urban corridors experience accelerated fleet turnover.
- Construction:Steep terrain torque requirements favor diesel powertrains for earthmoving and material transport.
- Transportation:Interprovincial freight corridors connect port modernization clusters at Cebu and Cagayan de Oro.
Logistics applications absorb the bulk of light-duty procurement; public transport is gaining share fastest as PUV Modernization Program deadlines approach.
Customer Type:
Buyer scale determines negotiating leverage and maintenance program structure, with large fleets displacing traditional dealer-relationship purchasing.
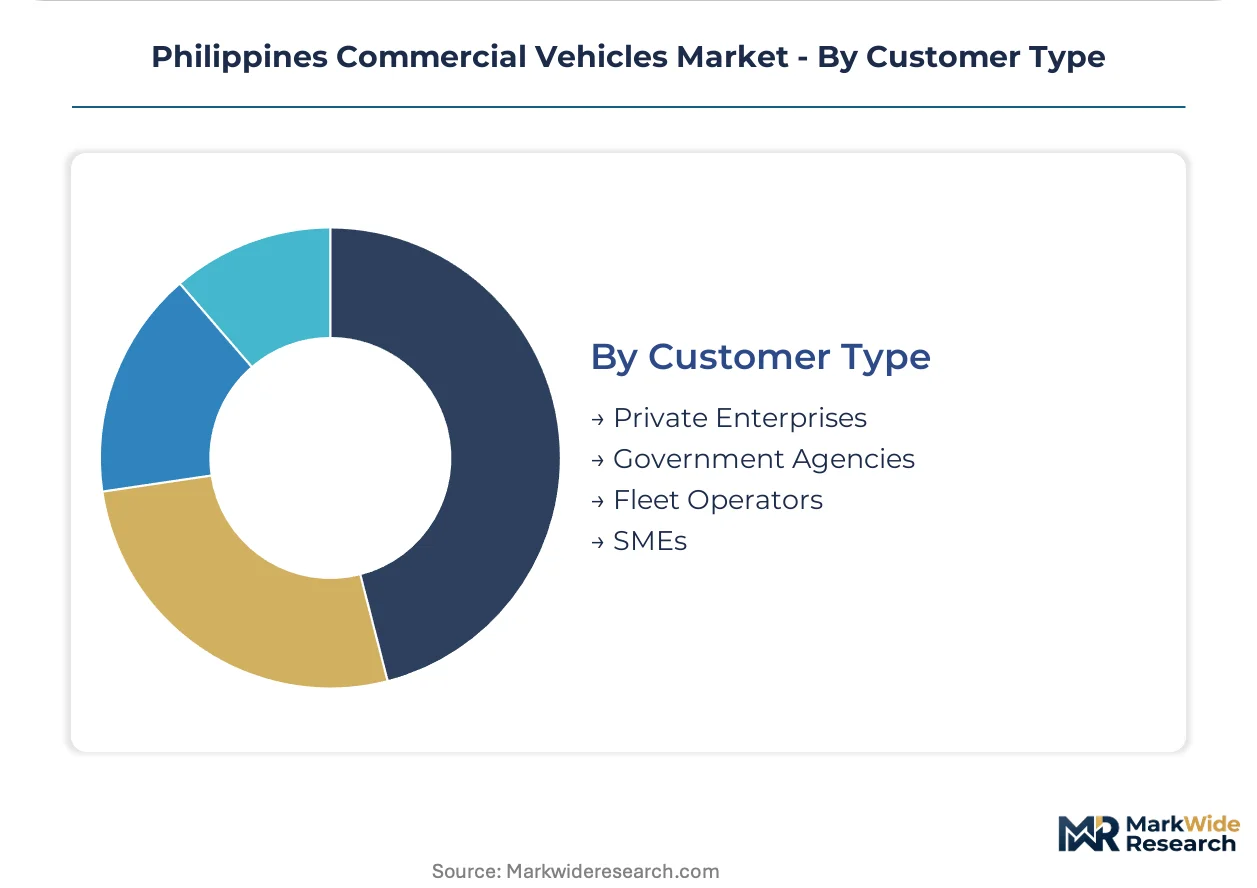
- Fleet Operators:Centralized procurement authority through volume contracts enables standardized specifications across multi-hub networks. Telematics integration with real-time fuel monitoring automates oversight for dispersed assets.
- SMEs:Provincial distribution businesses lack capital reserves for Euro 4 engine upgrades and after-treatment systems, creating compliance barriers.
- Private Enterprises:Corporate logistics divisions prioritize hybrid powertrain options for fuel price volatility hedging.
- Government Agencies:Public sector procurement follows Motor Vehicle Development Program incentive structures for local assembly qualification.
Fleet operators command the largest procurement volumes; SMEs are adopting compliant platforms fastest through cooperative financing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CALABARZON's special economic zones and Metro Manila's logistics corridors anchor commercial vehicle demand concentration. The Department of Transportation's PUV Modernization Program drives fleet turnover across Luzon's urban centers. Provincial distribution networks in Visayas and Mindanao present underpenetrated service territories for chassis suppliers.
Metro Manila
E-commerce fulfillment operators dominate light-duty truck procurement for last-mile density. The Department of Transportation enforces Euro 4 emission mandates through the Bureau of Product Standards. Port modernization at Manila and Subic Bay concentrates warehousing investment and vehicle replacement cycles.
CALABARZON
Logistics corridor development between Laguna and Cavite drives standardized fleet procurement. The Board of Investments extends Motor Vehicle Development Program incentives for local assembly qualification. Batangas Port expansion creates warehousing clusters with sustained commercial vehicle service demand.
Central Luzon
Provincial distribution businesses replace aging jeepneys with purpose-built cargo platforms. The Department of Transportation's franchise consolidation mandates compress cooperative operator timelines. Clark Freeport Zone logistics parks attract fleet operator depot consolidation.
Visayas
Cebu Port modernization generates interisland freight corridor expansion. The country's national transport regulator enforces route rationalization for public utility vehicle cooperatives. Mandaue City's industrial estates concentrate light-duty truck deployment for regional distribution.
Mindanao
Mining and construction applications in Davao and Cagayan de Oro retain diesel powertrain dependency. The Bureau of Product Standards enforces Philippine National Standards alignment with UN-ECE braking regulations. Cagayan de Oro Port warehousing clusters create underpenetrated service network opportunities.
Philippines Commercial Vehicles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across chassis configuration tiers. Japanese-origin manufacturers anchor the market through established diesel engine heritage and hybrid powertrain portfolios. Three archetypes dominate: legacy engine specialists with provincial service networks, hybrid technology integrators targeting fuel-price-sensitive fleets, and modular platform providers enabling body-type flexibility. Competitive moves concentrate on local assembly qualification through Board of Investments incentives and telematics integration for fleet management contracts.
Among Japanese-origin manufacturers, Isuzu Philippines Corporation and Hino Motors exemplify the engine-heritage archetype with established provincial distribution footprints. Toyota Motor Philippines Corporation occupies a position bridging hybrid technology integration with volume fleet contracts. These three entities represent distinct strategic postures: diesel specialization for high-torque applications, dedicated bus chassis engineering for archipelago terrain, and dual-powertrain hedging against fuel volatility.
| Leading Market Players |
|---|
| Isuzu Philippines Corporation |
| Hino Motors |
| Mitsubishi Motors Philippines Corporation |
| IVECO Group |
| Toyota Motor Philippines Corporation |
| Jiangling Motors Corporation Group |
| Foton Motor Philippines |
| Columbian Motor Corporation |
| Diamond Motor Corporation |
| Others |
Pricing and Supply Chain Analysis
Fleet operator consolidation into centralized procurement agreements is compressing dealer margins and forcing manufacturers toward direct-contract pricing models with embedded service bundling. This buyer-side concentration is reshaping how chassis suppliers structure volume discounts and after-sales commitments across Luzon's logistics corridors.
Pricing Analysis
Short-lead-time chassis configurations command premium positioning as Euro 4 compliance deadlines compress replacement timelines for cooperative operators. The dominant structure is contract-based long-term offtake with volume-scaled pricing tiers, differentiated by engine certification grade and geographic service coverage density. Pricing pressure stems from Chinese EV platform competition entering through Board of Investments incentive loopholes. SMEs exhibit highest price sensitivity due to capital constraints for after-treatment system fitment.
Supply Chain Analysis
Regional distribution centers in Metro Manila and CALABARZON operate hub-and-spoke patterns feeding provincial dealer networks across the archipelago. Manufacturing concentrates in Japan, Thailand, and China for diesel powertrain components and hybrid system integration. Critical dependencies include high-strength steel for ladder-frame construction, Euro 4-compliant engine control modules, and thermal management systems for tropical climates. Single-source vulnerability sits with Japanese-origin transmission suppliers. Distribution runs through manufacturer-captive logistics networks with third-party last-mile service partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into battery pack assembly and telematics platform development is becoming the decisive competitive lever as fleet operators demand bundled hardware-software procurement contracts.
For Market Incumbents: Hedge diesel margin erosion by accelerating hybrid powertrain localization through Motor Vehicle Development Program qualification. Secure captive supply of Euro 4 after-treatment components to compress parts availability latency for fleet maintenance contracts. Reinforce provincial service network density against emerging Chinese entrants with price-aggressive EV platforms. For New Entrants and Emerging Players: Enter via modular chassis-body configurations targeting Visayas and Mindanao logistics corridors where incumbent service penetration remains thin. Prioritize Cebu and Cagayan de Oro warehousing clusters with direct sales teams bypassing traditional dealer hierarchies. Anchor positioning through telematics-native fleet management bundles. For Investors and Strategic Acquirers: The window for entry favors hybrid-electric powertrain specialists with existing ASEAN manufacturing footprints. Long-term viability hinges on local assembly qualification securing import duty advantages. Monitor Board of Investments incentive rule changes as the primary inflection signal for competitive cost positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Qualification | Motor Vehicle Development Program incentives reduce duty exposure for qualifying producers serving Luzon fleet contracts. |
| Telematics Platform Integration | Real-time fuel monitoring and predictive maintenance automation compress downtime for logistics operators across CALABARZON. |
| Hybrid Powertrain Localization | Battery and motor assembly within Philippine economic zones hedges currency exposure for cost-conscious fleet procurement. |
| Provincial Service Network Expansion | Visayas and Mindanao depot coverage captures port modernization-driven warehousing clusters at Cebu and Cagayan de Oro. |
| Modular Chassis-Body Partnership | Swappable cargo and passenger configurations enable single-platform fleet flexibility for multi-use cooperative operators. |
Research Methodology
Document review covered Bureau of Product Standards regulatory filings, Department of Transportation PUV Modernization Program implementation reports, and Board of Investments incentive qualification records, complemented by interviews with fleet procurement managers, provincial distributor principals, and logistics park developers. Secondary validation drew from vehicle registration databases, customs import records, and economic zone employment statistics. Bottom-up chassis shipment analysis triangulated against top-down fleet operator capital expenditure surveys.
Unit shipment and value estimates across the projection horizon reflect segmentation by vehicle class, propulsion architecture, and regional logistics corridor density. CAGRs derive from regression analysis of historical replacement cycles against regulatory mandate deadlines and e-commerce fulfillment network expansion trajectories. Key inputs include Euro 4 compliance cost curves, charging infrastructure deployment schedules, and cooperative operator financing access indicators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PUV Modernization Program deadline extensions or accelerated Chinese EV platform import penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market