
 Fleet Telematics System Market | 2026-2036
Fleet Telematics System Market Size, Share, and Industry Trends Forecast 2026-2036
Fleet Telematics System Market Insights
Last-mile delivery and cold-chain logistics is hardening as the dominant end-use vertical, displacing traditional long-haul freight as the primary growth engine. Verizon Connect sustains its position through deep channel partnerships with North American utility fleets. Samsara differentiates via AI-driven video safety and unified cloud architecture. Geotab anchors European market presence through open-platform APIs and OEM integrations.
A fleet telematics system integrates GPS receivers, onboard diagnostic ports, cellular modems, and accelerometers to capture real-time vehicle location, engine diagnostics, and driver behavior data for centralized fleet optimization. Cloud-based deployment now commands the largest installed base, though edge computing architectures are gaining traction where low-latency collision avoidance or geofenced compliance enforcement is critical. Sensor fusion technology is expanding fastest as fleets combine video, radar, and CAN-bus feeds into unified risk scoring models. Fuel management applications retain the deepest margin pools due to direct diesel cost savings and carbon reporting requirements.
The U.S. Department of Transportation's FMCSA mandates on electronic logging devices and the European Commission's Mobility Package regulations on driver hours enforcement have created compulsory demand for compliant telematics hardware. Japan's METI fuel efficiency standards and the EPA's Phase 3 greenhouse gas rules for heavy-duty vehicles are pushing OEMs to embed factory telematics rather than rely on aftermarket retrofits. Stakeholders must weigh whether to build proprietary data lakes or federate across Geotab and Samsara ecosystems as platform consolidation accelerates.
Market Dynamics
Cloud-to-edge migration is reconfiguring fleet telematics architectures as operators seek millisecond latency for collision avoidance and geofenced compliance enforcement, forcing hardware vendors to bifurcate product roadmaps between centralized SaaS platforms and distributed edge nodes.
Growth Catalysts
- EU Green Deal emissions mandates:The European Commission's binding carbon monitoring requirements for commercial fleets are mandating real-time telematics integration across diesel and electric vehicle pools, creating compulsory hardware refresh cycles.
- Sensor fusion technology:Video, radar, and CAN-bus data streams are converging into unified risk scoring models that insurers and fleet operators use to price coverage and driver incentives dynamically.
- Last-mile logistics concentration:E-commerce fulfillment networks in Germany, the United States, and Japan are deploying dense telematics grids to optimize delivery density and customer time-window compliance.
Market Restraints
- Semiconductor supply concentration:GPS receiver and cellular modem chip fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to single-source disruption risks and allocation delays.
- Aftermarket installation cost structures:Hardwired OBD-II and J1939 port installations require certified technician labor that inflates total cost of ownership for small fleets operating fewer than fifty vehicles.
- Cellular connectivity fragmentation:Cross-border fleet operators face roaming tariff complexity and carrier interoperability gaps between North American, European, and Asian mobile network standards.
Strategic Opportunities
- Embedded OEM factory telematics:EPA Phase 3 greenhouse gas rules and Japan METI fuel efficiency standards are pushing truck manufacturers to pre-install compliant hardware, displacing aftermarket retrofit demand.
- AI-driven predictive maintenance:Machine learning models trained on engine diagnostic telematics are enabling component-failure forecasting that reduces unplanned downtime for cold-chain and hazardous-material fleets.
- Subscription-based fleet software:Per-vehicle-per-month pricing models are lowering capital barriers for mid-sized logistics operators in India and Brazil to adopt enterprise-grade route optimization and driver coaching tools.
Industry Challenges
- Data science talent scarcity:Fleet operators lack in-house expertise to configure anomaly detection algorithms and interpret sensor fusion outputs, creating implementation bottlenecks and underutilized platform features.
- Legacy fleet management system integration:Decades-old dispatch and maintenance software in municipal and utility fleets requires expensive API middleware development to synchronize with modern telematics data lakes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fleet Telematics System Market |
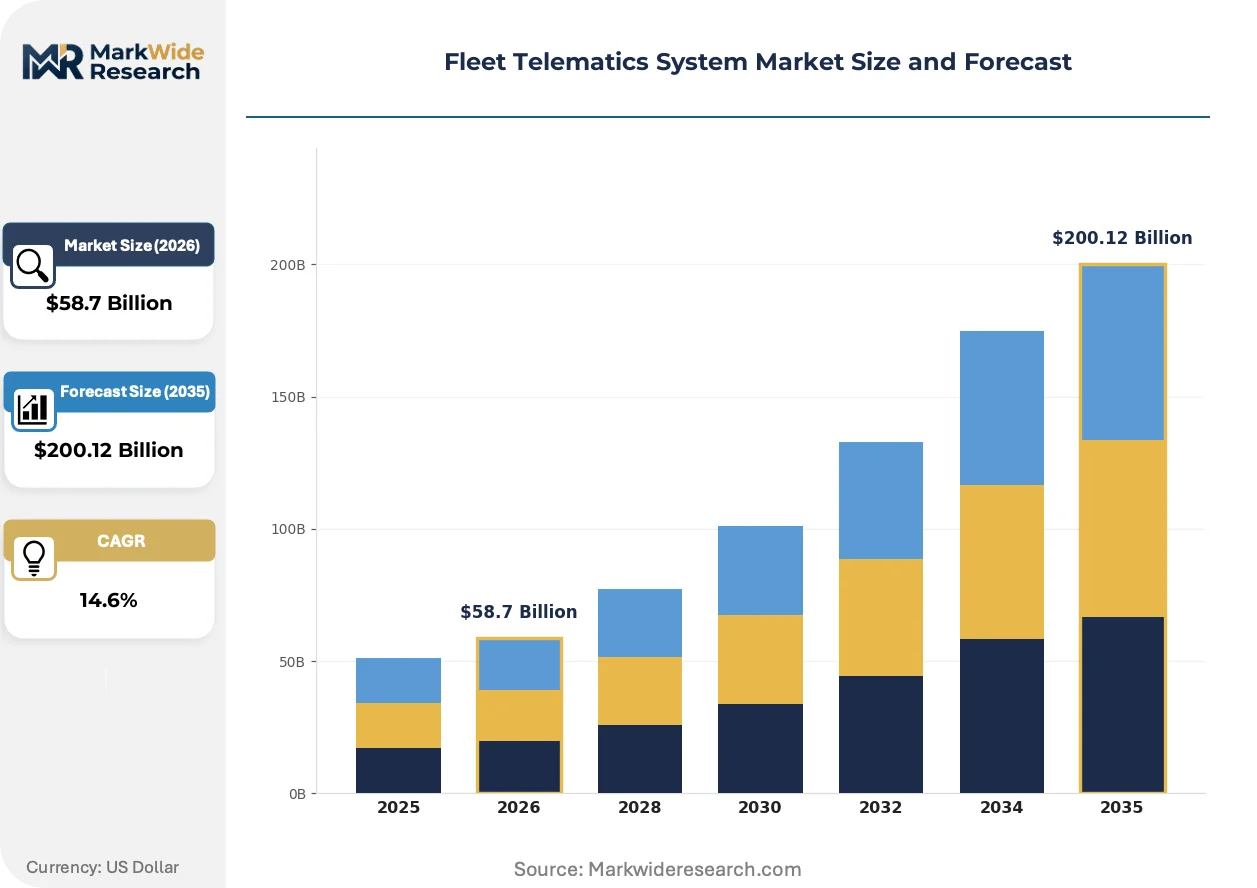
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $200.12 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Tracking, OBD Data, RFID, Sensor Fusion Deployment: Cloud-based, On-premises, Hybrid, Edge Computing End User: Logistics Companies, Public Transportation, Fleet Operators, Emergency Services Application: Vehicle Tracking, Fuel Management, Driver Behavior, Maintenance Scheduling |
| Companies Covered | Geotab, Verizon Connect, Samsara, Trimble, MiX Telematics, Powerfleet, Omnitracs, Teletrac Navman, Fleet Complete, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fleet Telematics System Market Trends and Innovations
Edge computing architectures are fragmenting traditional cloud-centric deployment models as latency-sensitive applications demand localized processing, while regulatory mandates accelerate hardware refresh cycles and procurement patterns shift toward outcome-based fleet optimization contracts.
Edge-native telematics gateways with onboard GPUs is decentralizing inference workloads for video-based driver monitoring and forward-collision warning systems. Heavy-duty trucking fleets operating in mountainous terrain are adopting these units fastest to maintain safety system functionality through cellular dead zones. This shift is decentralizing vendor power away from pure-play cloud platforms toward hardware-software integrated stack providers.
California Air Resources Board's Clean Truck Check regulation now mandates annual emissions reporting via telematics for all diesel vehicles above fourteen thousand pounds. The rule forces fleet operators to upgrade to cellular-connected diagnostic hardware or face registration holds. Drayage and regional freight operators serving Los Angeles and Long Beach ports are retrofitting fastest to maintain terminal access privileges.
Buying committees now specify total cost of ownership guarantees rather than hardware unit pricing when evaluating telematics vendors. Large logistics enterprises are consolidating supplier relationships from multi-vendor point solutions to single-platform contracts spanning asset tracking, fuel management, and compliance reporting. This behavioral shift is most pronounced among German and Dutch pharmaceutical distributors operating temperature-controlled fleets under GDP guidelines.
Fleet Telematics System Market Segmentation
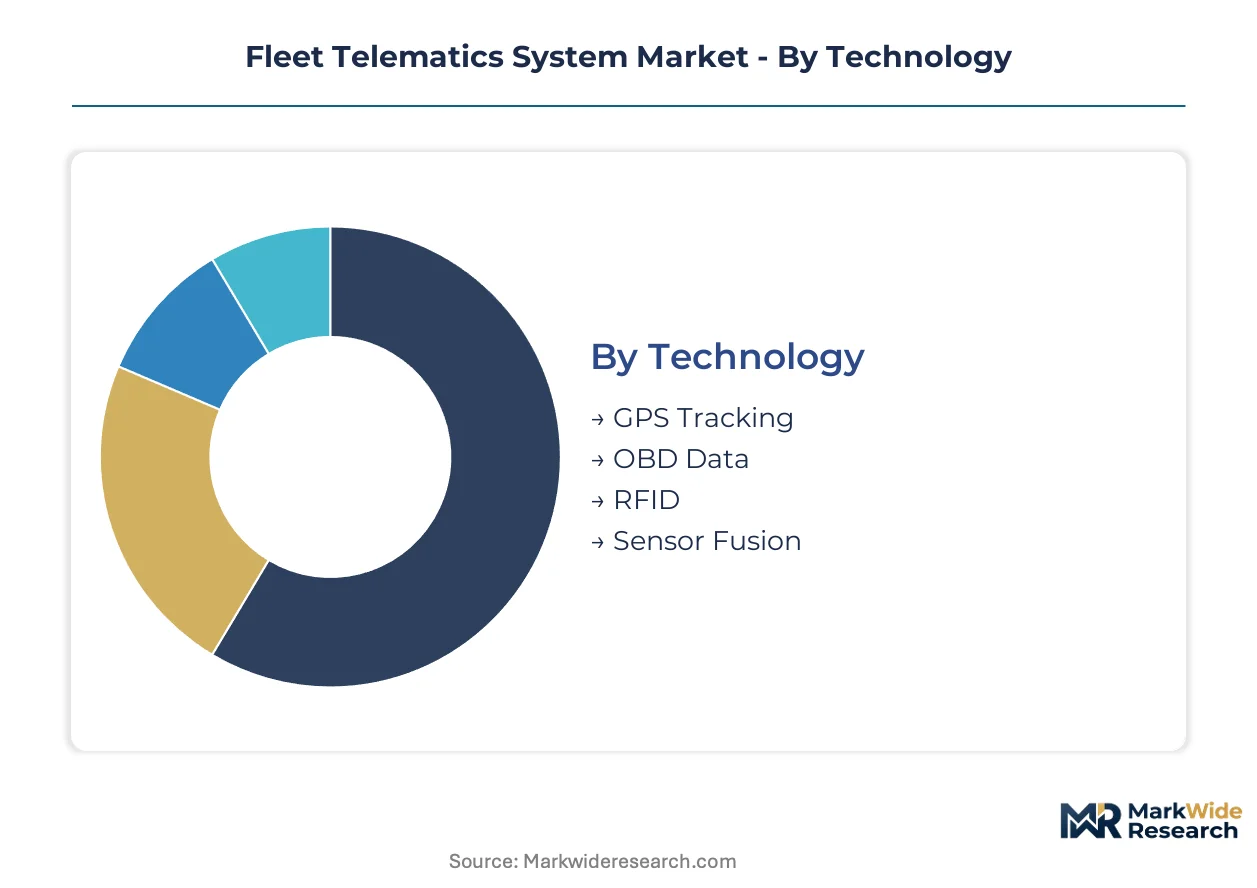
Fleet telematics vendors configure product portfolios across four intersecting dimensions. Technology choices determine hardware bill-of-materials, while deployment architecture dictates latency performance and data sovereignty compliance. End-user verticals impose divergent regulatory requirements, and application depth separates commodity tracking from premium optimization services.
Technology:
Standalone GPS and OBD modules dominate retrofit installations, whereas sensor fusion and RFID integrate natively into factory-built platforms.
- GPS Tracking:Satellite triangulation receivers provide geolocation accuracy within three meters for route optimization and geofenced compliance enforcement. Demand concentrates in long-haul freight corridors across Germany and the United States where hours-of-service regulations mandate position logging.
- Sensor Fusion:Converged video, radar, and CAN-bus data streams enable unified risk scoring for insurers and dynamic driver incentive programs. Japanese pharmaceutical distributors deploy these systems fastest to maintain GDP temperature compliance across cold-chain lanes.
- OBD Data:Engine diagnostic port readers capture fuel consumption, fault codes, and emissions profiles through standardized J1939 and OBD-II protocols.
- RFID:Passive and active radio-frequency tags automate yard management and trailer inventory tracking without cellular connectivity dependency.
Volume placements concentrate in GPS Tracking; the faster expansion belongs to Sensor Fusion.
Deployment:
Cost tiering separates capital-intensive on-premises installations from operational-expense cloud subscriptions, with hybrid and edge architectures occupying premium positioning.
- Cloud-based:Centralized SaaS platforms aggregate fleet-wide data lakes for predictive analytics and remote software updates. Mid-sized logistics operators in Brazil and India adopt these deployments to avoid server infrastructure investment.
- Edge Computing:Onboard GPU-enabled gateways process video inference and collision warnings locally without cellular latency. Mountainous trucking routes in Japan and the Swiss Alps drive adoption where network coverage gaps threaten safety system reliability.
- Hybrid:Split architectures synchronize critical safety functions at the edge while batching analytics workloads to cloud data centers.
- On-premises:Private server installations serve defense contractors and government fleets with classified operational security requirements.
Cloud-based deployments hold the deepest installed base; edge computing gains share fastest in latency-sensitive safety applications.
End User:
Customer type determines procurement complexity, from standardized utility fleet tenders to bespoke emergency services integrations requiring hardened hardware.
- Logistics Companies:E-commerce fulfillment networks and third-party carriers specify telematics bundles spanning route optimization, fuel tax reporting, and customer delivery notifications. German last-mile operators deploy densest sensor grids to meet EU Green Deal emissions documentation mandates.
- Fleet Operators:Vehicle leasing and rental companies monetize telematics data through usage-based insurance partnerships and sublease utilization analytics.
- Public Transportation:Municipal bus and rail authorities integrate telematics with passenger information systems and priority signaling infrastructure.
- Emergency Services:Police, fire, and ambulance fleets require MIL-STD-810G ruggedization and priority cellular network access during disaster response.
Logistics companies generate the highest unit volumes; emergency services command the steepest per-vehicle pricing premiums.
Application:
Functional depth separates commodity location services from high-margin predictive systems that directly reduce operating expenditure.
- Fuel Management:Real-time consumption monitoring, idle-time alerts, and carbon reporting tools deliver measurable diesel cost reductions. California Air Resources Board compliance deadlines force drayage operators serving Los Angeles and Long Beach ports to upgrade to connected diagnostic hardware.
- Driver Behavior:Accelerometer-based harsh braking detection and AI-video coaching reduce collision frequency and insurance premiums. Cold-chain fleets in the Netherlands adopt these tools to defend GDP certification and pharmaceutical distribution contracts.
- Vehicle Tracking:Basic geolocation and historical route replay serve asset recovery and customer service transparency requirements.
- Maintenance Scheduling:Predictive algorithms flag component degradation before failure, minimizing unplanned downtime for hazardous-material carriers.
Vehicle tracking retains the broadest penetration; maintenance scheduling climbs fastest as OEM embedded telematics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the Netherlands and Singapore are concentrating fleet telematics procurement for cross-border logistics operators. These hubs attract vendors seeking duty-efficient hardware distribution and regional compliance certification.
United States
California Air Resources Board mandates on heavy-duty diesel emissions are forcing drayage fleets serving Los Angeles and Long Beach ports to retrofit connected diagnostic hardware. The EPA's Phase 3 greenhouse gas rules push OEMs toward factory-embedded telematics. Texas energy corridor fleets deploy edge-computing gateways for remote safety monitoring.
Germany
EU Green Deal carbon monitoring requirements compel commercial fleets to install real-time emissions tracking across diesel and electric vehicle pools. The country's national automotive regulator enforces stringent type-approval standards for connected vehicle systems. Bavarian pharmaceutical distributors operate dense sensor grids for GDP-compliant cold-chain documentation.
Japan
METI fuel efficiency standards accelerate OEM factory telematics adoption over aftermarket installations. Pharmaceutical distributors in the Kanto region deploy sensor fusion systems for temperature-controlled logistics certification. Mountainous trucking routes in Hokkaido drive edge-computing adoption where cellular coverage gaps threaten safety system reliability.
India
The country's national automotive research agency promotes telematics integration under Bharat Stage VI emission compliance frameworks. Logistics operators in Maharashtra adopt subscription-based fleet software to avoid capital-intensive infrastructure investment. Gujarat port operators install GPS tracking for container yard management and customs clearance optimization.
Fleet Telematics System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud-platform vendors commanding recurring revenue streams while hardware-integrated stack providers capture edge-computing safety applications. The vendor landscape organizes into three tiers: enterprise-scale platform consolidators, vertical-specialist solution providers, and regional system integrators. Dominant competitive moves include strategic partnerships with OEMs for factory-embedded installations and API federations that reduce customer switching costs.
Within the enterprise-platform tier, Geotab anchors European market presence through open-architecture positioning, while Verizon Connect sustains North American utility fleet relationships through channel depth. Samsara occupies a position exemplifying AI-native video safety and unified cloud deployment. These three represent divergent strategic bets on platform consolidation versus vertical specialization.
| Leading Market Players |
|---|
| Geotab |
| Verizon Connect |
| Samsara |
| Trimble |
| MiX Telematics |
| Powerfleet |
| Omnitracs |
| Teletrac Navman |
| Fleet Complete |
| Others |
Pricing and Supply Chain Analysis
German pharmaceutical distributors and California drayage operators concentrate procurement power through multi-year platform contracts, shifting vendor pricing models from hardware unit sales toward subscription-based fleet optimization guarantees with fuel cost reduction clauses.
Pricing Analysis
Short lead-time premiums apply to edge-computing gateways with onboard GPUs for collision avoidance systems, while spot inventory discounts emerge for legacy OBD-II hardware facing displacement by factory-embedded OEM telematics. Three-tier pricing structure across premium sensor-fusion platforms, standard GPS tracking bundles, and economy vehicle-location units reflects certification grade and after-sales service bundling. Pricing pressure stems from semiconductor allocation constraints and certified technician labor shortages inflating installation costs. Small fleets operating fewer than fifty vehicles exhibit highest price sensitivity, whereas enterprise logistics operators prioritize total cost of ownership guarantees over unit pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for factory-embedded telematics, while authorized distributor networks serve aftermarket retrofit installations for mid-sized fleet operators. Component fabrication concentrates in Taiwan and South Korea for GPS receivers and cellular modems, with final assembly anchored in Mexico and Eastern Europe for North American and EU market access. Raw material dependencies include lithium-ion battery cells for backup power, automotive-grade semiconductors for CAN-bus processing, and ruggedized enclosures for heavy-duty applications. Single-source vulnerability in Taiwan semiconductor foundries exposes hardware vendors to allocation disruption. Distribution runs through tier-one automotive suppliers integrating telematics modules into OEM vehicle platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-to-edge architecture migration is displacing centralized SaaS-only platforms as fleets prioritize millisecond-latency safety systems, creating competitive openings for hardware-software integrated stack providers.
For Market Incumbents: Anchor European market position through open-platform API ecosystems that reduce customer switching costs against Samsara and Verizon Connect consolidation efforts. Deepen backward integration into GPU-enabled gateway manufacturing to capture edge-computing growth in mountainous trucking corridors. Defensive patenting around sensor fusion algorithms protects margin pools in pharmaceutical cold-chain verticals. For New Entrants and Emerging Players: Municipal and utility fleets with decades-old dispatch software represent underserved buyer archetypes requiring expensive API middleware integration. Brazil and India subscription-based fleet software markets offer lowest capital barriers for mid-sized logistics operators. White-space penetration demands per-vehicle-per-month pricing models with route optimization and driver coaching bundled as standardized offerings. For Investors and Strategic Acquirers: The window for entry favors vertically integrated hardware-software providers with edge-computing safety certifications and OEM factory-embed relationships. Long-term viability hinges on platform consolidation acceleration reducing multi-vendor point solution fragmentation. Watch EPA Phase 3 greenhouse gas rule implementation timelines as inflection indicator for embedded telematics displacement of aftermarket demand.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Factory Telematics Partnership | EPA Phase 3 rules push truck manufacturers toward pre-installed compliant hardware displacing retrofit demand. |
| Edge Computing Gateway Launch | Onboard GPU-enabled units process video inference locally for cellular dead zones in Japanese mountain routes. |
| Sensor Fusion Platform Integration | Converged video, radar, and CAN-bus data enables unified risk scoring for Dutch pharmaceutical GDP compliance. |
| API Federation Development | Open-architecture positioning reduces switching costs and anchors European market share against consolidators. |
| Predictive Maintenance Algorithm Investment | Machine learning on engine diagnostics forecasts component failure for hazardous-material fleet uptime. |
Research Methodology
Document review covered regulatory filings from EPA, EU Green Deal implementation documents, and METI fuel efficiency standards, complemented by interviews with fleet operations directors, telematics platform engineers, OEM procurement managers, and insurance risk modelers. Secondary validation drew from FMCSA ELD mandate compliance databases, California Air Resources Board Clean Truck Check records, automotive production statistics, and customs trade data for GPS receiver and cellular modem imports. Bottom-up unit shipment estimates triangulated against top-down fleet operator spend analysis.
Segmentation outputs reflect technology type, deployment architecture, end-user vertical, and application depth modeled across the projection horizon. CAGRs derived from regression analysis of historical hardware installation rates, SaaS subscription growth, and regulatory mandate enforcement timelines. Industry-specific inputs included OEM factory telematics penetration curves, semiconductor allocation constraints, and certified technician labor availability.
Revisions become necessary when EPA Phase 3 rule implementation delays, Taiwan semiconductor supply disruptions, or EU Green Deal carbon monitoring enforcement modifications materialize. Forecasts reflect assumptions regarding cellular network coverage expansion, edge-computing hardware cost reduction, and platform consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Transport Data Logger Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Roadside Assistance Software Market