
 Tire Building Machinery Market | 2026-2036
Tire Building Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Building Machinery Market Analysis
Asian tire machinery production is shifting toward integrated automation suites. Continental AG leverages in-house curing press development to anchor its European installed base. Michelin competes through robotics-intensive green tire building lines that reduce cycle times. Bridgestone Corporation extends its footprint across Southeast Asian tire plant expansions with localized service networks.
Tire building machinery encompasses equipment that assembles tire components—tread, sidewall, bead, and carcass—into green tires prior to curing, with modern systems achieving positioning tolerances below 0.5 millimeters to ensure uniformity. These machines serve tire manufacturers producing passenger, commercial, and off-road tires at volumes exceeding thousands of units daily. Tread builders and tire curing presses command the largest share of capital expenditure among product categories, reflecting their centrality to throughput and final product quality. Robotics-based technology segments are displacing manual and semi-automatic configurations as labor costs rise and OEM customers mandate traceability in tire construction.
The EPA enforces emissions thresholds for rubber processing equipment in the United States, while REACH governs chemical exposure in European tire plant environments, and China's MEE imposes energy-efficiency benchmarks on industrial machinery procurement. Tire building machinery suppliers must certify compliance with these divergent frameworks to maintain market access across major manufacturing geographies. Stakeholders should monitor how carbon-border adjustment mechanisms reshape machinery sourcing decisions for tire plants serving export markets.
Market Dynamics
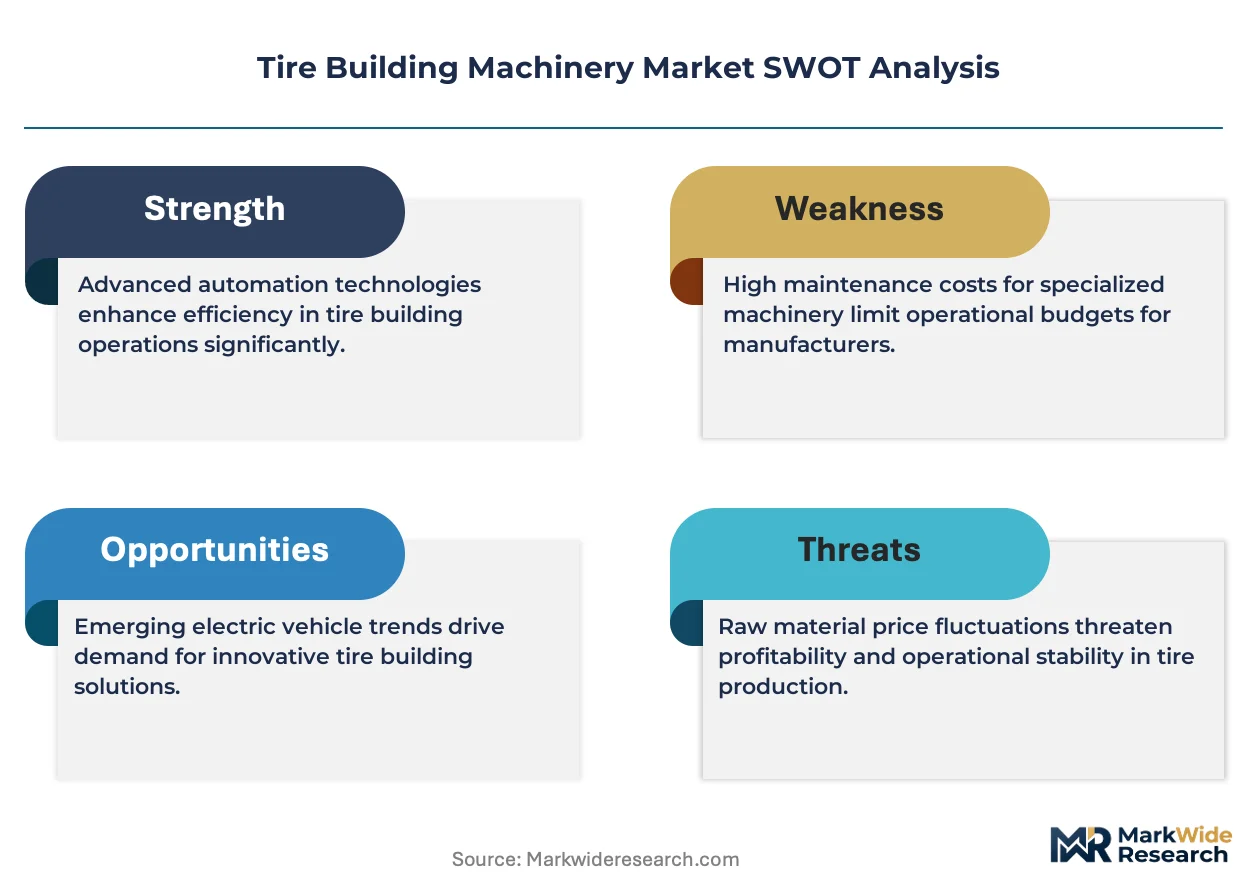
Robotics integration across tire assembly lines is compressing cycle times and forcing incumbent equipment suppliers to reengineer their curing press architectures for seamless automation compatibility.
Growth Catalysts
- EV Platform Scaling:Passenger vehicle OEMs are expanding dedicated electric vehicle tire capacity, requiring green tire building systems with higher precision tolerances for low-rolling-resistance designs.
- REACH Compliance Mandates:European chemical exposure regulations are accelerating replacement of legacy curing equipment with enclosed, lower-emission press configurations.
- Robotics Adoption:Labor cost pressures in Germany, China, and the United States are pulling tire manufacturers toward fully automated tread builder and sidewall assembly lines.
Market Restraints
- Steel and Aluminum Input Volatility:Curing press frames and precision rollers depend on commodity metal prices that swing with energy markets and trade policy uncertainty.
- Specialized Component Concentration:High-precision servo motors and linear motion systems for tire building drums concentrate among German and Japanese industrial automation suppliers.
- Curing Energy Intensity:Thermal processing requirements for green-to-finished tire conversion face escalating carbon border adjustment exposure for export-oriented plants.
Strategic Opportunities
- Southeast Asian Plant Expansion:Thailand, Indonesia, and Vietnam are attracting greenfield tire manufacturing investments that require localized machinery service networks and spare parts logistics.
- Dual-Carbon Policy Alignment:China's MEE energy-efficiency benchmarks create procurement preference for machinery vendors with verified carbon intensity documentation.
- Predictive Maintenance Convergence:Integration of IoT sensors with tire building equipment is opening subscription-based uptime guarantee contracts as an alternative to traditional capex sales.
Industry Challenges
- Mechatronics Talent Scarcity:Tire machinery vendors struggle to hire engineers capable of integrating precision mechanical systems with real-time control software.
- Legacy Control System Migration:Decades-old proprietary PLC architectures in installed curing presses resist seamless integration with modern MES and quality traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Building Machinery Market |
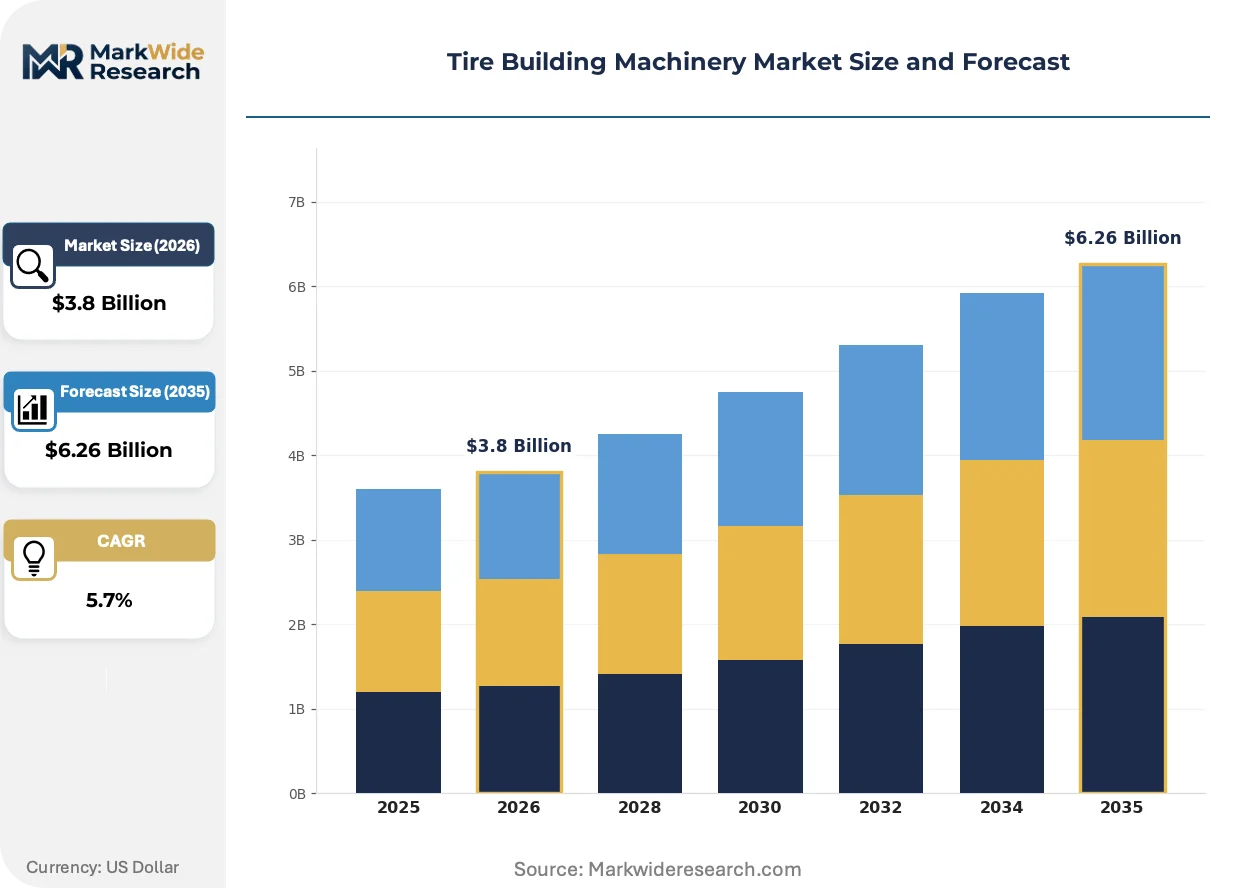
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tread Builders, Bead Builders, Tire Curing Presses, Wrapping Machines Technology: Automation, Manual, Semi-Automatic, Robotics Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Specialty Tires End User: Tire Manufacturers, OEMs, Aftermarket Suppliers, Re-treaders |
| Companies Covered | Manuli, Marangoni, Borealis, Continental AG, Bridgestone Corporation, Kiefel Technologies, Prometeon, Michelin, Technomatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Building Machinery Market Emerging Trajectories
Digital thread technologies are penetrating tire manufacturing workflows, compressing the feedback loop between green tire construction anomalies and curing parameter adjustments.
Modular curing press architectures are modularizing the traditional monolithic vulcanization system into standardized heating modules, cooling stations, and handling units. Tier-one tire manufacturers in Germany and South Korea are piloting these configurations to enable capacity scaling without full line replacement. This approach is modularizing supplier relationships, allowing tire plants to source heating systems, control software, and mechanical frames from different vendors while maintaining interface compatibility.
EPA emissions thresholds for rubber processing equipment are tightening volatile organic compound limits in US tire plant environments. Machinery suppliers must now certify curing press ventilation and thermal oxidizer integration to maintain market access. North American tire manufacturers are responding by specifying enclosed press designs with integrated fume capture, shifting procurement evaluation criteria toward total emissions footprint rather than throughput alone.
Service contract unbundling is fragmenting the traditional bundled maintenance model for tire building machinery. Large tire manufacturers in Japan and Germany are separating preventive maintenance, spare parts logistics, and remote diagnostics into discrete purchasing decisions. This shift pressures machinery OEMs to demonstrate standalone value for each service component, favoring vendors with transparent IoT-enabled performance dashboards over those relying on opaque bundled pricing.
Tire Building Machinery Market Segmentation
Tire building machinery procurement hinges on matching equipment specifications to precise regulatory and performance requirements across tire categories. Segmentation reveals how certification burdens, automation intensity, and end-use durability demands reshape supplier prioritization and capital allocation decisions.
Product Type:
REACH compliance in Europe and EPA thresholds in the United States impose distinct certification timelines on each equipment category, with enclosed curing systems facing the most stringent validation protocols.
- Tire Curing Presses:Thermal vulcanization systems convert green tires to finished products through precisely controlled heat and pressure cycles. Demand concentrates in Germany and China as tire OEMs replace legacy open presses with enclosed, low-emission configurations to satisfy tightening fume capture mandates.
- Tread Builders:These machines layer tread compounds onto carcass assemblies with positioning tolerances below 0.5 millimeters. Passenger vehicle tire plants in the United States and South Korea are pulling toward robotics-integrated tread builders as labor costs rise and traceability requirements harden.
- Bead Builders:Wire winding and rubber coating systems form tire bead assemblies.
- Wrapping Machines:Sidewall and inner liner application equipment completes green tire construction.
Leading the category by volume: Tire Curing Presses. Growing fastest: Tread Builders.
Technology:
Capital expenditure tiers separate automation levels, with fully robotic lines commanding three to five times the investment of manual configurations but delivering payback through labor displacement and yield improvement.
- Robotics:Articulated arms and vision-guided systems execute tire component placement with repeatability exceeding human capability. Tire manufacturers in Germany, China, and the United States are accelerating robotics adoption as cycle time compression becomes competitive necessity.
- Automation:Programmable logic controller-driven systems with integrated material handling reduce operator intervention without full robotic substitution. Southeast Asian greenfield plants favor this tier for balancing precision with localized serviceability.
- Semi-Automatic:Operator-assisted machines with powered assists for heavy component handling.
- Manual:Conventional equipment requiring skilled labor for component positioning and assembly.
Highest installed base: Automation. Steepest expansion trajectory: Robotics.
Application:
Durability specifications and production batch sizes diverge sharply across vehicle categories, dictating machinery scale and flexibility requirements.
- Passenger Vehicles:High-volume production lines for radial tires with low-rolling-resistance compounds. Electric vehicle platform scaling in Germany, China, and the United States is intensifying demand for precision green tire builders capable of handling advanced silica-reinforced tread formulations.
- Commercial Vehicles:Heavy-duty truck and bus tire manufacturing with reinforced carcass requirements. Fleet operator pressure for retreadable casings is shaping bead builder specifications toward durability verification systems.
- Off-Road Vehicles:Agricultural and construction tire production with extreme ply rating demands.
- Specialty Tires:Aviation, racing, and industrial tire categories with low-volume, high-specification production.
Dominant volume segment: Passenger Vehicles. Gaining share fastest: Commercial Vehicles.
End User:
Procurement authority and service contract structures fragment across the value chain, with tire manufacturers retaining direct machinery relationships while aftermarket channels rely on re-treader equipment suppliers.
- Tire Manufacturers:Integrated producers operating captive tire plants with dedicated machinery engineering teams. Bridgestone, Michelin, and Continental AG maintain direct supplier relationships for curing press development and robotics integration roadmaps.
- OEMs:Vehicle manufacturers with captive tire operations or joint venture arrangements. Their procurement specifications increasingly mandate IoT-enabled predictive maintenance compatibility.
- Aftermarket Suppliers:Independent tire producers serving replacement markets.
- Re-treaders:Specialized operators remanufacturing worn tire casings for commercial fleet customers.
Primary equipment demand source: Tire Manufacturers. Fastest-growing procurement authority: OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and rubber feedstock availability anchors tire machinery demand across manufacturing geographies. Germany, China, the United States, Japan, and South Korea concentrate the installed base of curing presses and green tire builders.
Germany
Electric vehicle platform scaling at BMW and Mercedes-Benz plants drives demand for precision tread builders with sub-millimeter tolerances. REACH mandates from ECHA accelerate replacement of open curing presses with enclosed, low-emission configurations. The Stuttgart and Hanover industrial corridors host Continental AG's in-house machinery development teams.
China
Domestic tire OEMs expand capacity for export markets serving Europe and Southeast Asia. MEE energy-efficiency benchmarks favor machinery vendors with verified carbon intensity documentation. The Shandong Peninsula clustering around Qingdao concentrates greenfield tire plant investments requiring localized service networks.
United States
EPA emissions thresholds tighten volatile organic compound limits for rubber processing equipment in Ohio and South Carolina tire corridors. Robotics integration accelerates as labor costs rise in legacy manufacturing states. The Southeast region attracts greenfield investments from Bridgestone and Michelin for EV-dedicated tire capacity.
Japan
Premium tire exports to North American and European markets sustain demand for high-throughput curing systems. METI industrial efficiency guidelines shape machinery procurement specifications for Yokohama Rubber and Sumitomo Rubber facilities. The Kansai region around Osaka maintains specialized mechatronics engineering talent pools.
South Korea
Hankook Tire and Kumho Tire expand robotics-intensive green tire building lines to serve German OEM supply contracts. National industrial policy supports smart factory transformation with IoT-enabled predictive maintenance compatibility. The Daejeon-Sejong corridor concentrates tire machinery engineering and control systems development.
Tire Building Machinery Market Vendor Landscape
Global majors compete with regional champions across automation technology and service network depth. The vendor base separates into three tiers: integrated tire manufacturers with captive machinery engineering, specialized industrial automation suppliers, and regional fabricators serving aftermarket channels. Strategic moves concentrate on robotics integration partnerships and modular curing press architecture licensing.
Within the integrated manufacturer tier, Continental AG and Bridgestone Corporation exemplify backward integration into curing press development and robotics roadmaps. Among specialized automation suppliers, Kiefel Technologies occupies a position serving multiple tire OEMs with modular equipment configurations. Marangoni represents the regional specialist archetype with concentrated service presence in European retreading markets.
| Leading Market Players |
|---|
| Manuli |
| Marangoni |
| Borealis |
| Continental AG |
| Bridgestone Corporation |
| Kiefel Technologies |
| Prometeon |
| Michelin |
| Technomatic |
| Others |
Supply Flow & Price Mechanics
REACH compliance deadlines in Europe gate qualified supplier access for enclosed curing press configurations, restricting premium-tier pricing to vendors with verified ECHA certification documentation. Tire manufacturers in Germany and the United States now face procurement premiums for machinery meeting dual EPA and REACH emission thresholds, compressing margins for uncertified equipment providers.
Pricing Analysis
Service contract unbundling separates preventive maintenance, spare parts logistics, and remote diagnostics into discrete purchasing decisions. Three-tier pricing structure across premium robotics-integrated, standard automation, and economy semi-automatic levels reflects automation intensity and certification grade. Price erosion runs through the semi-automatic tier as Southeast Asian greenfield plants favor fully automated alternatives. Tier-one tire manufacturers in Germany and Japan demonstrate lowest price sensitivity due to throughput-critical requirements, while independent aftermarket suppliers in Southeast Asia prioritize capital efficiency.
Supply Chain Analysis
High-precision servo motors and linear motion systems for tire building drums rest on German and Japanese industrial automation suppliers. Steel and aluminum frame materials draw from Chinese and South Korean metal producers, with curing press thermal systems sourcing from Italian and German heating component specialists. Single-source vulnerability concentrates in precision motion control electronics subject to export licensing variability. Distribution runs through direct OEM relationships for tier-one tire manufacturers, while regional fabricators serve aftermarket channels through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around automation-capable vendors as robotics integration mandates force semi-automatic equipment suppliers toward acquisition or exit.
For Market Incumbents: Extend predictive maintenance subscription offerings to capture recurring revenue streams and deepen customer captivity. Anchor European installed bases through REACH-certified curing press upgrades before ECHA enforcement windows tighten. Backward integration into precision motion control components reduces exposure to German and Japanese supplier concentration. For New Entrants and Emerging Players: Regional service partners in Thailand, Indonesia, and Vietnam offer the fastest channel establishment path for greenfield tire plant expansions. Target Southeast Asian aftermarket re-treaders with modular, serviceable automation tiers lacking complex robotics integration. Position through transparent IoT-enabled performance dashboards that challenge opaque bundled pricing from established vendors. For Investors and Strategic Acquirers: Predictive maintenance contract penetration exceeding thirty percent of installed base revenue is the leading indicator that a machinery vendor has achieved viable recurring economics. Five-to-ten year viability favors vendors with demonstrated MEE carbon intensity documentation for Chinese market access. Acquisition candidates should demonstrate captive robotics integration roadmaps or specialized mechatronics engineering capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Integration Partnership | Articulated arm deployment from KUKA or FANUC accelerates cycle time compression for German OEM customers. |
| Modular Curing Press Licensing | Standardized heating module architectures enable capacity scaling without full line replacement at Korean tire plants. |
| REACH Certification Investment | ECHA-compliant enclosed press configurations secure premium pricing access in European procurement evaluations. |
| Predictive Maintenance Platform Launch | IoT sensor integration supports subscription-based uptime guarantees as alternative to traditional capex sales. |
| Southeast Asian Service Network Expansion | Localized spare parts logistics in Thailand and Indonesia captures greenfield tire plant investment flows. |
Methodological Framework
Independent corroboration across machinery procurement directors at tier-one tire manufacturers, aftermarket service heads, and precision component suppliers underwrites the qualitative findings. Primary interviews with plant engineers, OEM procurement teams, and regional distributor operators combined with secondary validation from customs trade data, SEC machinery supplier filings, and MEE energy-efficiency disclosure records. Bottom-up equipment shipment analysis and top-down tire production capacity triangulation anchored volume estimates.
Comparable historical periods across the analysis window established baseline growth trajectories for robotics displacement rates and curing press replacement cycles. Segmentation modeling incorporated product type, automation technology tier, application durability requirements, and end-user procurement authority. CAGRs derived from regression analysis against tire OEM capital expenditure disclosures and electric vehicle platform scaling announcements. Forecast inputs included REACH compliance timeline acceleration and MEE carbon intensity benchmark adoption curves.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting German-Japanese precision component flows and unscheduled regulatory enforcement date changes. Forecasts reflect documented assumptions regarding EV tire capacity scaling continuity and robotics integration cost reduction trajectories. Supply chain disruption from commodity metal price volatility and mechatronics engineering talent scarcity warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Bicycle Rim Market
Tires and Wheels
Global Automotive Tire Socks Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Agricultural Tires Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Off-The-Road (OTR) Tire Market