
 Automotive Telematics System Market | 2026-2036
Automotive Telematics System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Telematics System Market Analysis
Subscription-based fleet financing is tilting capital deployment toward telematics-enabled asset-light operators. Verizon Connect leverages its cellular infrastructure to dominate commercial fleet connectivity in North America. Robert Bosch GmbH anchors its position through in-house production of sensor-to-cloud telematics stacks. Continental AG competes by specializing in integrated OEM systems for European car manufacturers.
Automotive telematics systems comprise embedded hardware modules, wireless communication protocols, and cloud-based software platforms that transmit vehicle location, performance metrics, and diagnostic data to centralized servers. These systems typically integrate GPS receivers, cellular modems operating on 4G LTE or 5G bands, and CAN bus interfaces sampling data at 10-100 Hz for real-time processing. OEM systems command the largest revenue pool due to factory-installed integration mandates and long-term service contracts. Fleet operators represent the fastest-expanding end-user category as logistics companies prioritize fuel optimization and regulatory compliance through driver behavior monitoring applications.
The European Union's eCall mandate under EENA and the GDPR data governance framework shape product architecture and cross-border data flows for telematics providers. In the United States, NHTSA crash notification standards and FCC spectrum allocations for dedicated short-range communications influence hardware certification timelines. China's MIIT enforces GB standards for connected vehicle cybersecurity that foreign suppliers must satisfy for market access. Stakeholders should monitor evolving mandates around vehicle-to-everything interoperability as regulators in multiple jurisdictions finalize testing protocols.
Market Dynamics
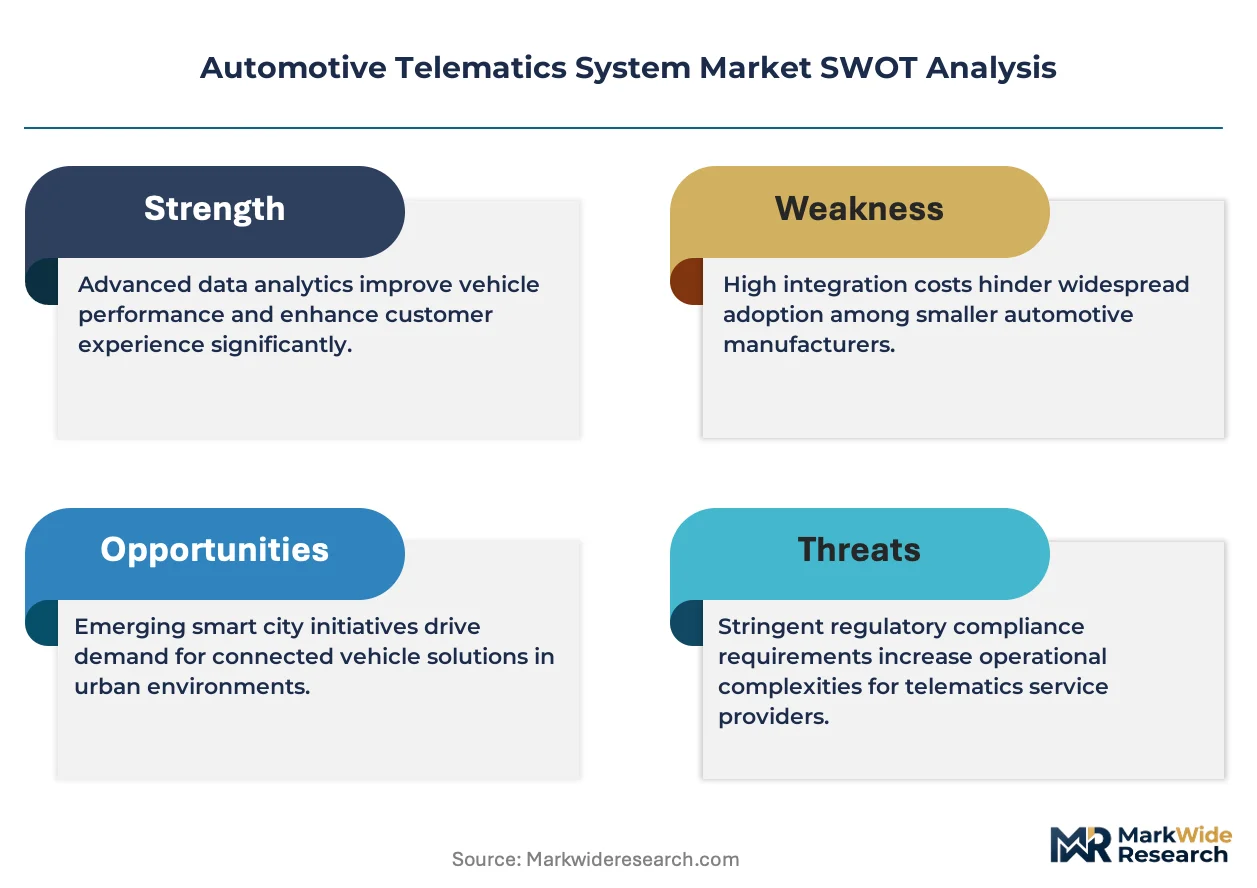
Cellular protocol migration from 4G LTE to 5G-V2X is compressing hardware refresh cycles and forcing module suppliers to redesign antenna configurations for millimeter-wave compatibility. This transition concentrates purchasing power among OEMs with sufficient volume to amortize certification costs across multi-year production commitments.
Growth Catalysts
- Mandatory eCall deployment:The EU's EENA framework requires automatic crash notification in all new vehicles, creating a baseline installed base for expanded telematics services across member states.
- Fuel optimization mandates:Logistics operators in Germany and the Netherlands face tightening CO2 reporting requirements that telematics platforms satisfy through real-time driver behavior analytics.
- 5G network densification:Verizon and T-Mobile expanding low-band coverage across rural US interstate corridors enables continuous fleet tracking previously limited by cellular dead zones.
Market Restraints
- Semiconductor supply concentration:Automotive-grade LTE and 5G modems depend on Qualcomm and MediaTek chipsets, creating vulnerability to foundry allocation decisions in Taiwan.
- GDPR compliance architecture:Cross-border data flows between vehicle sensors and cloud servers require EU-approved Standard Contractual Clauses, adding legal review costs to every deployment.
- Aftermarket hardware substitution:Smartphone-based OBD-II dongles from consumer electronics suppliers capture price-sensitive owner-operators unwilling to pay embedded system premiums.
Strategic Opportunities
- Commercial vehicle electrification:Battery electric trucks and vans require thermal monitoring and range prediction that telematics platforms integrate with charging infrastructure APIs.
- India's AIS-140 mandate:The country's transport ministry requires GPS tracking in all commercial vehicles, opening a compliance-driven market for hardware-software bundles.
- Edge computing convergence:On-vehicle AI inference chips from NVIDIA and Qualcomm enable real-time video analytics without cellular backhaul, reducing latency for collision avoidance applications.
Industry Challenges
- Embedded software talent scarcity:Automotive OEMs compete with consumer tech firms for engineers proficient in AUTOSAR Adaptive Platform and ISO 26262 functional safety.
- Multi-protocol certification timelines:Simultaneous FCC, CE marking, and MIIT approval for a single hardware variant extends time-to-revenue by 14-18 months.
- Legacy fleet integration:Pre-2018 commercial vehicles lack CAN bus standardization, forcing expensive retrofit harnesses for telematics module installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Telematics System Market |
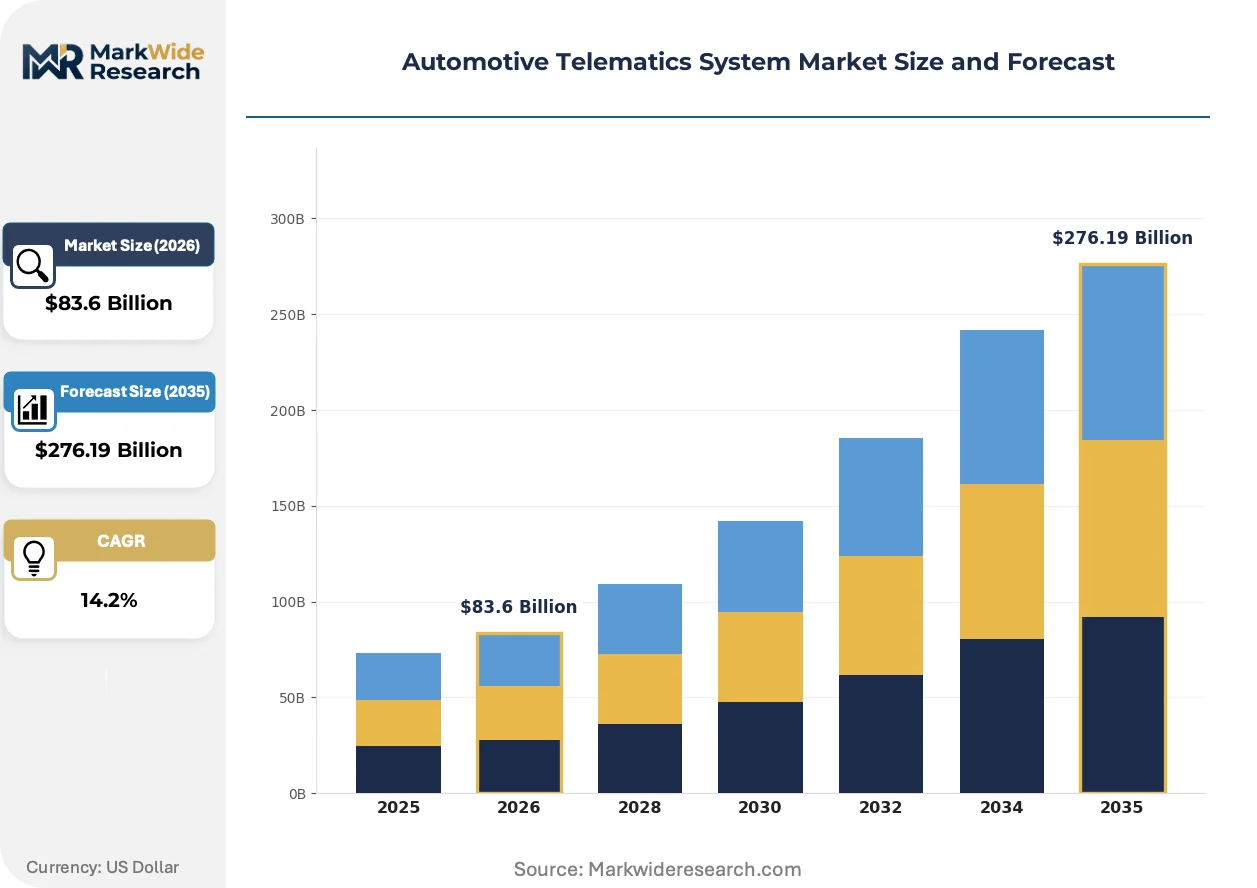
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $276.19 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OEM Systems, Aftermarket Solutions, Integrated Systems, Standalone Units End User: Fleet Operators, Individual Consumers, Car Manufacturers, Service Providers Connectivity: Cellular, Satellite, Wi-Fi, Bluetooth Application: Vehicle Tracking, Navigation, Remote Diagnostics, Driver Behavior Monitoring |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Harman International, Verizon Connect, LG Electronics, Qualcomm Technologies, TomTom International BV, Trimble Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Telematics System Market Emerging Trajectories
Telematics architectures are bifurcating between centralized cloud processing and distributed edge intelligence, with hardware suppliers redesigning modules to accommodate both paradigms. This duality is fragmenting procurement patterns as fleet operators and OEMs place divergent bets on data sovereignty versus computational latency.
Dual-mode 4G/5G cellular modules with integrated C-V2X direct communication are rendering obsolete single-protocol hardware that cannot support vehicle-to-infrastructure safety messaging. Tier-1 suppliers including Continental and Bosch are qualifying these chipsets for 2027 model-year platforms. The shift is compressing margins for module vendors unable to secure automotive-grade certifications before protocol sunsets.
GDPR's data minimization principles and the EU AI Act's risk classification for automated decision-making are forcing telematics providers to re-architect cloud platforms with granular consent management and algorithmic audit trails. German fleet operators now demand data residency guarantees that limit vendor selection to EU-hosted infrastructure. This regulatory layering is advantaging European system integrators with existing GDPR-compliant operations over US-based competitors.
Usage-based insurance contracts tied to actual driving telemetry are displacing traditional risk-pooling models in commercial auto coverage. Munich Re and Swiss Re have launched parametric products priced on hard-braking frequency and nighttime mileage exposure. The UK and Germany show the fastest contract migration, with logistics fleets accepting onboard monitoring in exchange for premium reductions of 15-25 percent.
Automotive Telematics System Market Segmentation
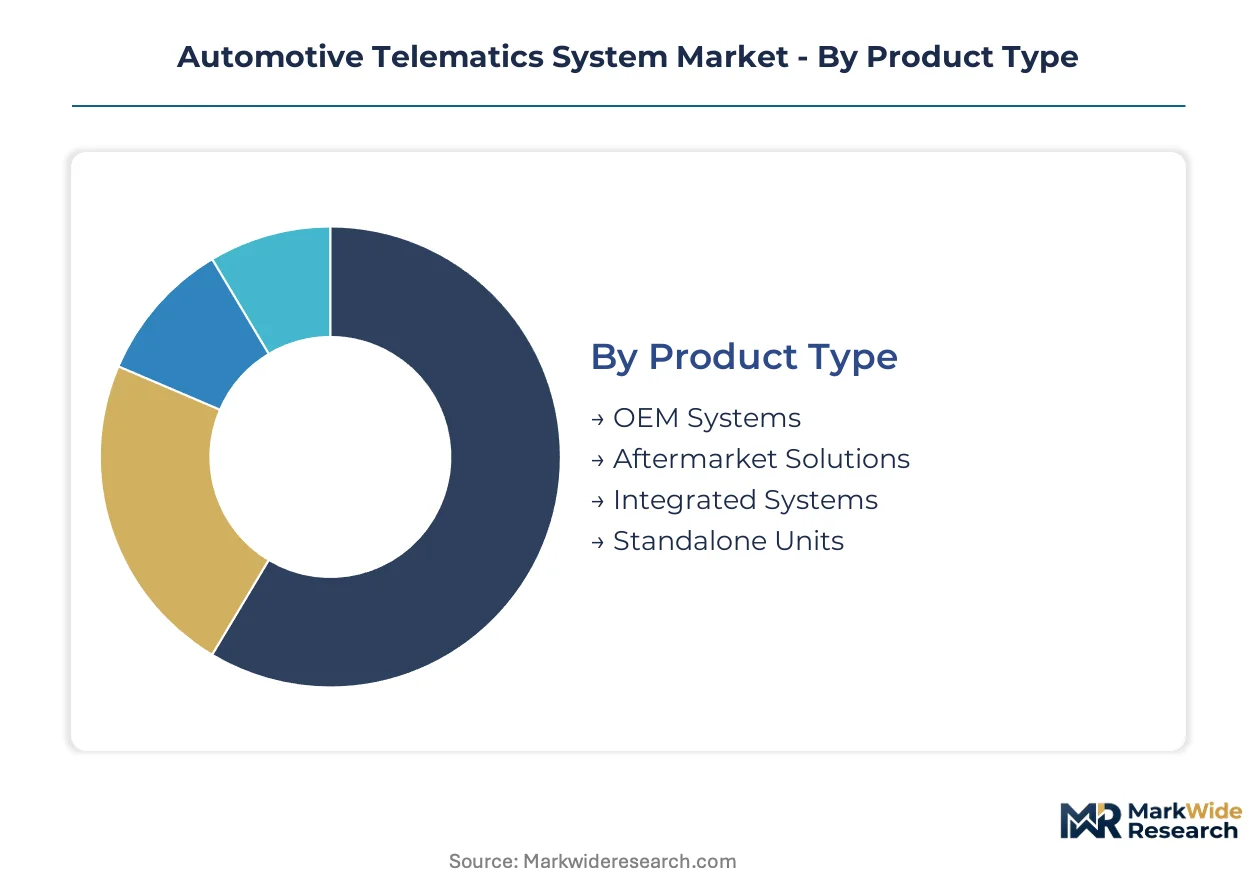
Automotive telematics systems fragment across four distinct dimensions that shape procurement patterns and technology roadmaps. Product architecture, end-user requirements, connectivity protocols, and application focus each create discrete competitive arenas with divergent margin structures and certification demands.
Product Type:
Use-case spectrum spans factory-integrated platforms to retrofit hardware for legacy vehicle populations.
- OEM Systems:Factory-installed modules with CAN bus integration and sealed environmental housings meeting automotive-grade temperature specifications. German premium vehicle lines anchor demand concentration, driven by EENA eCall mandates and long-term service contract monetization.
- Aftermarket Solutions:Retrofit hardware including OBD-II dongles and windshield-mounted cellular units. Price-sensitive owner-operators in North America drive volume, constrained by smartphone substitution and limited CAN bus access on pre-2018 commercial vehicles.
- Integrated Systems:Bundled hardware-software stacks combining telematics with infotainment or ADAS controllers.
- Standalone Units:Single-purpose devices for asset tracking without vehicle system integration.
Established volume favors OEM Systems; emerging adoption favors Aftermarket Solutions.
End User:
Customer archetypes range from enterprise fleet managers to individual vehicle owners with divergent data sovereignty requirements.
- Fleet Operators:Logistics companies managing vehicle populations exceeding 50 units, prioritizing fuel optimization and driver behavior analytics. Netherlands and Germany show fastest contract expansion, driven by tightening CO2 reporting requirements and usage-based insurance premium reductions.
- Car Manufacturers:OEMs embedding telematics as standard equipment to satisfy regulatory mandates and enable subscription service revenue streams. Bosch and Continental supply integrated stacks to European premium brands under multi-year platform commitments.
- Individual Consumers:Private vehicle owners accessing telematics through insurance-linked programs or stolen vehicle recovery services.
- Service Providers:Third-party platforms aggregating data across multiple vehicle brands for insurance, maintenance, or fleet management applications.
Procurement scale concentrates with Fleet Operators; margin expansion concentrates with Car Manufacturers.
Connectivity:
Protocol selection determines latency profiles, coverage continuity, and hardware refresh cycle timing.
- Cellular:4G LTE and 5G-V2X modems operating on licensed spectrum with tower infrastructure dependency. Verizon and T-Mobile densification across rural US interstate corridors eliminates dead zones that previously limited continuous fleet tracking.
- Satellite:L-band and Ku-band transceivers for coverage beyond cellular reach, including maritime and remote mining operations.
- Wi-Fi:Local area connectivity for depot-based data offload and software updates.
- Bluetooth:Short-range pairing with driver smartphones for proximity authentication and cabin interface.
Volume leadership sits with Cellular; specialty applications favor Satellite.
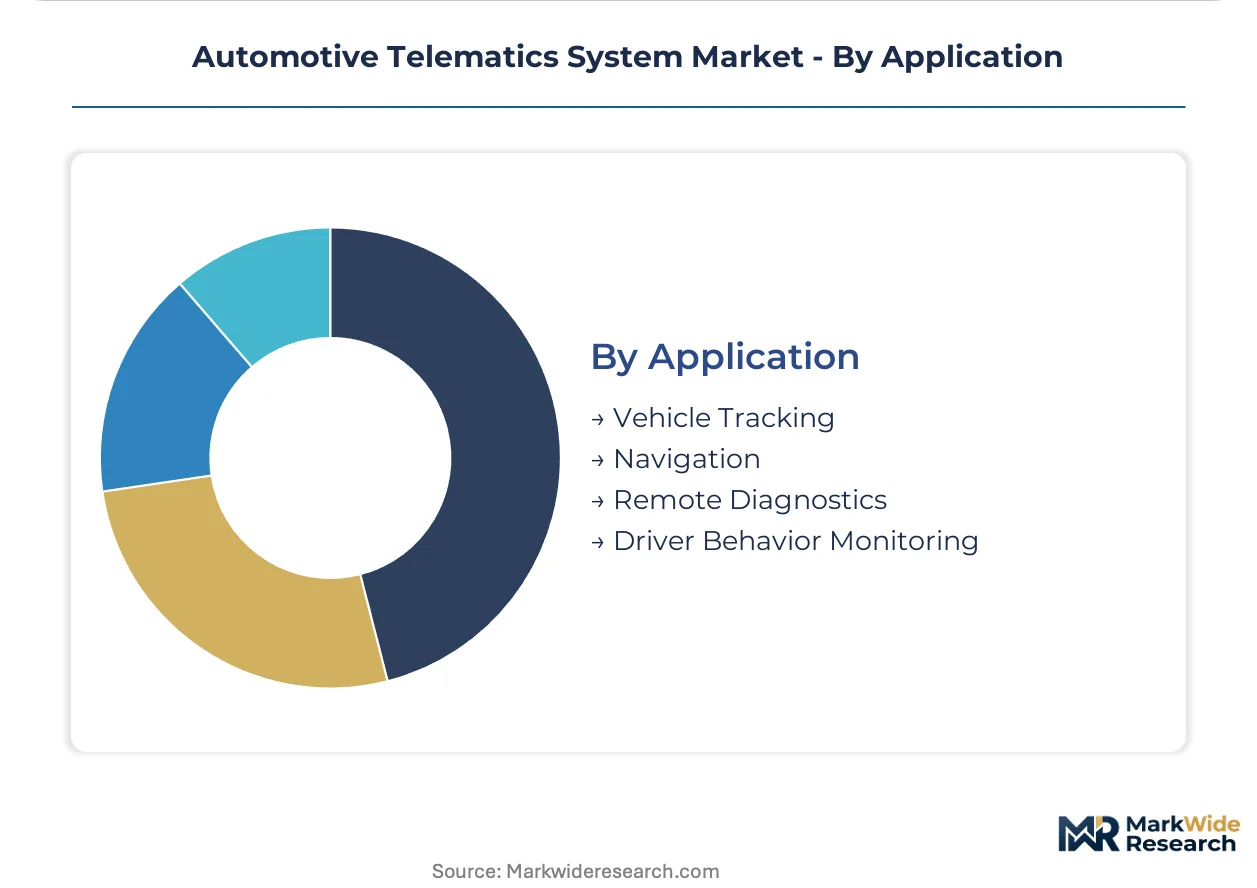
Application:
Functional deployment ranges from passive location logging to real-time predictive maintenance and risk scoring.
- Vehicle Tracking:GPS-based location services with geofencing and route history. India's AIS-140 mandate creates compliance-driven demand for hardware-software bundles across all commercial vehicle classes.
- Driver Behavior Monitoring:Accelerometer and CAN bus data analysis for harsh braking, acceleration, and cornering detection. Munich Re and Swiss Re parametric insurance products price coverage on these telemetry streams, with UK and German logistics fleets accepting monitoring for 15-25 percent premium reductions.
- Navigation:Turn-by-turn routing with real-time traffic integration and predictive ETA calculation.
- Remote Diagnostics:Predictive maintenance alerts based on powertrain sensor thresholds and historical failure pattern matching.
Regulatory compliance anchors Vehicle Tracking; insurance innovation accelerates Driver Behavior Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany, the United States, and India are driving hardware procurement volumes through distinct regulatory and commercial pathways. Each geography imposes unique certification demands on module suppliers while concentrating demand within specific industrial corridors.
United States
Commercial fleet operators across Texas and the Southeast prioritize fuel optimization platforms for long-haul logistics corridors. FCC spectrum allocations for dedicated short-range communications shape hardware certification timelines for module suppliers. Verizon and T-Mobile densification across rural interstate corridors eliminates cellular dead zones that previously limited continuous fleet tracking.
Germany
Premium automotive OEMs anchor telematics integration into factory-installed platforms for domestic and export vehicle lines. The EU's EENA eCall mandate under GDPR data governance frameworks shapes product architecture for cross-border data flows. Stuttgart and Munich industrial clusters concentrate Bosch and Continental engineering facilities for sensor-to-cloud stack development.
China
Domestic EV manufacturers require thermal monitoring and range prediction modules for battery electric commercial vehicles. MIIT enforces GB standards for connected vehicle cybersecurity that foreign suppliers must satisfy for market access. Shenzhen and Shanghai technology corridors host module assembly operations serving both domestic OEMs and export markets.
India
Logistics operators face compliance-driven hardware procurement under the AIS-140 mandate for GPS tracking in all commercial vehicles. The Ministry of Road Transport and Highways enforces real-time location transmission standards for interstate freight. Maharashtra and Gujarat industrial corridors concentrate telematics hardware assembly for domestic fleet retrofit programs.
Japan
Automotive OEMs integrate telematics with ADAS controllers for domestic premium vehicle platforms. METI guidelines on connected vehicle data security influence cloud platform architecture for export compliance. Nagoya and Tokyo metropolitan areas anchor Denso engineering facilities for integrated telematics-ADAS stack development.
Automotive Telematics System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Cellular infrastructure owners and Tier-1 automotive suppliers command platform-level relationships with fleet operators and OEMs. Module vendors and software platforms occupy specialized niches with narrower margin structures. Dominant competitive moves include strategic partnerships between hardware suppliers and cloud platforms, plus geographic expansion through regulatory-compliant product variants.
Among German-based integrated system suppliers, Robert Bosch GmbH and Continental AG exemplify the Tier-1 archetype with captive production of sensor-to-cloud telematics stacks. Verizon Connect occupies a position representing the cellular infrastructure archetype, leveraging tower networks for commercial fleet connectivity. These three companies anchor the competitive structure by controlling distinct value chain segments.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Harman International |
| Verizon Connect |
| LG Electronics |
| Qualcomm Technologies |
| TomTom International BV |
| Trimble Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwan semiconductor foundries is compressing module supplier margins and forcing tiered pricing concessions to OEM anchor customers. This utilization slack allows automotive telematics vendors to negotiate volume commitments that lock in component costs across multi-year platform cycles.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate procurement between module vendors and automotive OEMs. Pricing stratifies across automotive-grade certified, industrial-grade, and consumer-grade tiers based on ISO 26262 functional safety compliance and temperature specification margins. Cost compression in the aftermarket dongle segment is intensifying because smartphone-based substitutes eliminate hardware premiums for price-sensitive owner-operators. Fleet operators demonstrate lowest price sensitivity due to fuel savings and insurance discounts offsetting upfront system costs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Tier 1 suppliers are stabilizing working capital for module assemblers facing 90-day OEM receivable cycles. Manufacturing concentrates in Taiwan, China, and Germany for chipset fabrication, module assembly, and system integration respectively. The supply chain draws from automotive-grade LTE modems, multi-layer ceramic capacitors, and GPS receiver chipsets. Single-source vulnerability sits with Qualcomm and MediaTek baseband silicon subject to foundry allocation decisions. Distribution runs through direct OEM supply agreements and aftermarket distributor networks serving independent fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across North American logistics corridors is shifting procurement leverage toward buyers managing 500-plus vehicle populations. This concentration demands volume-scaled pricing and API integration guarantees from telematics vendors.
For Market Incumbents: Harden platform stickiness through captive cloud infrastructure and multi-protocol hardware certification ahead of 5G-V2X sunsets. Bosch and Continental should deepen in-house production of edge AI chipsets to offset NVIDIA and Qualcomm supply constraints. Defensive patent positioning around C-V2X direct communication protocols blocks emerging module competitors from automotive-grade qualifications.
For New Entrants and Emerging Players: India's AIS-140 compliance-driven retrofit market for pre-2018 commercial vehicles represents the most penetrable entry point for hardware-software bundles lacking OEM integration depth. Mid-size European fleet operators underserved by Verizon Connect's North American infrastructure offer white-space for cellular-agnostic platform plays. A direct sales model targeting transport ministry certification consultants accelerates regulatory approval velocity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 5G-V2X module development due to millimeter-wave antenna redesign and multi-jurisdiction certification requirements. Target acquisition profiles favor edge computing specialists with AUTOSAR Adaptive Platform expertise and existing MIIT cybersecurity approvals for China market access. Monitor FCC spectrum auction outcomes for dedicated short-range communications as inflection signals for V2X infrastructure deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| 5G-V2X Module Certification | Qualifies hardware for 2027 EU model-year platforms under EENA mandate expansion. |
| Edge AI Chipset Integration | Enables real-time collision avoidance without cellular latency dependency. |
| GDPR-Compliant Cloud Infrastructure | Satisfies German fleet operator data residency requirements blocking US competitors. |
| AIS-140 Hardware Bundle Deployment | Captures compliance-driven demand across India's commercial vehicle retrofit market. |
| Usage-Based Insurance Platform Partnership | Locks in Munich Re and Swiss Re telemetry data streams for premium pricing. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, FCC equipment authorization filings, and EU type-approval documentation. Bottom-up module shipment estimates triangulated against top-down OEM telematics penetration rates across vehicle classes.
Forecast inputs included propulsion architecture segmentation, content-per-vehicle trajectories, and regional regulatory mandate schedules across the analysis window. The modeling framework applied logistic diffusion curves for 5G-V2X adoption and S-curve penetration rates for usage-based insurance integration. CAGRs derived from segment-level value projections indexed to automotive semiconductor pricing cycles and cellular infrastructure densification timelines.
Practitioners should monitor MIIT cybersecurity standard revisions, FCC DSRC spectrum reallocation proceedings, and EU AI Act enforcement patterns for early signals of demand inflection. Forecasts reflect documented assumptions around semiconductor foundry capacity normalization and OEM platform cycle timing. Macroeconomic contraction in commercial vehicle procurement, regulatory delay in V2X protocol finalization, or sustained chipset supply disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
Edge Computing in Automotive Market