
 United States Commercial Telematics Market | 2026-2036
United States Commercial Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Telematics Market Intelligence
Modular hardware-software bundling is pivoting how fleet buyers configure telematics investments, shifting from standalone GPS units toward subscription-based platforms combining diagnostics, compliance, and analytics. Omnitracs leverages its legacy routing dominance to anchor long-haul carrier relationships. Platform Science competes through open-architecture APIs that integrate third-party logistics apps. Samsara specializes in cloud-native video telematics for mid-size fleets seeking rapid deployment.
United States Commercial Telematics encompasses onboard vehicle hardware, wireless data transmission infrastructure, and cloud-based software platforms that capture location, engine diagnostics, driver behavior, and regulatory compliance metrics in real time. These systems process CAN-bus data at 500 kbps while transmitting compressed telemetry via cellular LTE or 5G modems to centralized fleet portals for dispatch optimization and predictive maintenance scheduling. Fleet Management solutions dominate current revenue pools as logistics companies prioritize route efficiency and asset utilization across dispersed tractor-trailer networks. Insurance Telematics represents the fastest-expanding segment as underwriters deploy usage-based pricing models tied to actual driver risk scores rather than demographic proxies. Cloud-based deployment architectures command widening preference over on-premise installations due to lower capital requirements and faster feature iteration cycles.
FAA regulations governing commercial drone integration intersect with NHTSA autonomous vehicle guidelines to shape emerging telematics data standards for mixed-fleet coordination. FMCSA Electronic Logging Device mandates continue driving baseline compliance demand while EPA emissions reporting requirements push telematics providers to incorporate fuel consumption analytics and idle-time reduction tools. Stakeholders must monitor how state-level privacy statutes in California and emerging jurisdictions constrain cross-border data flows between fleet operators and platform vendors.
Market Dynamics
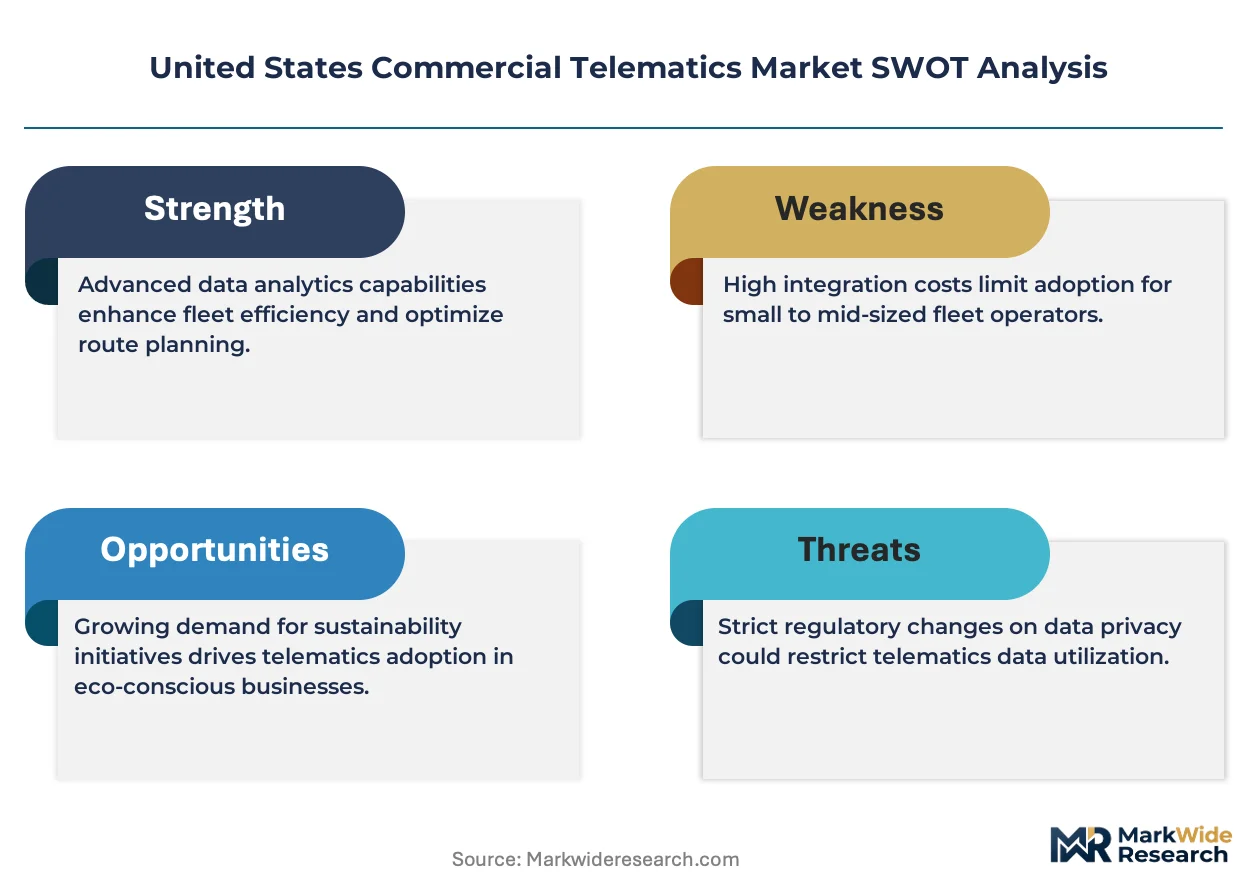
Fleet operators face mounting pressure to unify disparate data streams from FMCSA compliance logs, EPA emissions reports, and insurance risk scoring into single-platform architectures, compressing vendor selection cycles and favoring integrated suite providers over point-solution specialists.
Growth Catalysts
- FMCSA Electronic Logging Device mandate:Hours-of-service compliance requirements force long-haul carriers to maintain certified telematics infrastructure, creating baseline hardware demand that sustains replacement cycles and feature upgrades.
- Last-mile delivery electrification:E-commerce fulfillment networks deploying battery-electric vans require real-time battery state-of-charge monitoring and thermal management telemetry distinct from internal combustion engine diagnostics.
- Cellular 5G network densification:Major carriers expanding low-band coverage along interstate corridors enable higher-frequency data transmission for video telematics and predictive maintenance algorithms.
Market Restraints
- Semiconductor supply concentration:CAN-bus controller and LTE modem sourcing remains concentrated among Asian foundries, exposing hardware vendors to lead-time volatility and inventory carrying costs.
- State privacy statute fragmentation:California Consumer Privacy Act and emerging state-level data protection laws create compliance complexity for cross-border fleet data flows between operators and platform vendors.
- Legacy fleet asset inertia:Smaller owner-operator trucking businesses retain functional but non-compliant hardware, delaying upgrade cycles and compressing addressable market expansion.
Strategic Opportunities
- Integrated insurance telematics:Usage-based pricing models from commercial auto underwriters create attach-rate opportunities for driver behavior scoring and incident reconstruction video.
- Western state zero-emission mandates:California Advanced Clean Trucks regulation and aligned Oregon and Washington policies accelerate demand for electric vehicle-specific telematics covering charging optimization and grid integration.
- API marketplace ecosystems:Open-architecture platforms enabling third-party logistics application integration capture fleet software budgets previously allocated to standalone dispatch and maintenance systems.
Industry Challenges
- Embedded systems cybersecurity certification:Fleet operators demand ISO/SAE 21434-aligned hardware to mitigate remote access vulnerabilities, extending vendor validation timelines and engineering overhead.
- Multi-generational fleet integration:Large carriers operating mixed-vintage tractors must reconcile incompatible telematics protocols across J1939, OBD-II, and proprietary OEM data buses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Telematics Market |
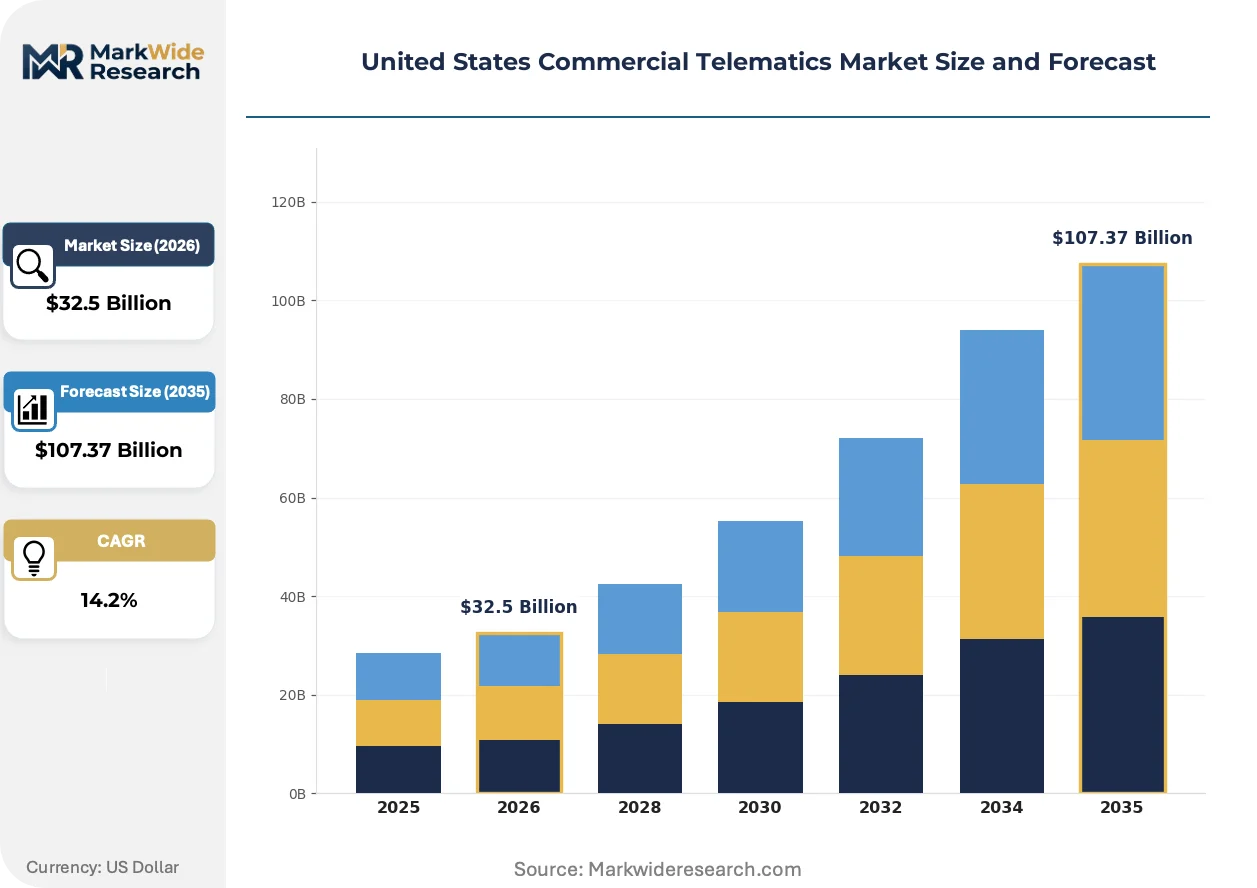
| Market Size in 2026 | $32.5 Billion |
| Market Size in 2035 | $107.37 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Insurance Telematics, Onboard Diagnostics, Navigation Systems End User: Logistics Companies, Transportation Firms, Government Agencies, Construction Businesses Deployment: Cloud-based, On-premise, Hybrid, Mobile Solutions Service Type: Real-time Tracking, Data Analytics, Maintenance Alerts, Driver Behavior Monitoring |
| Companies Covered | Omnitracs, Platform Science, Geotab Inc., Zonar, Teletrac Navman, Verizon Connect, Trimble Inc., MiX Telematics, Samsara Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Telematics Market Strategic Shifts & Innovations
Artificial intelligence inference at the network edge is compressing latency for critical safety alerts while reshaping how fleet managers consume predictive insights. Three developments are reconfiguring competitive positioning.
Edge-computing video analytics is expanding into real-time driver fatigue detection and collision avoidance systems. Mid-size regional fleets with dispersed operations are adopting these capabilities fastest, drawn by reduced cloud data transmission costs. The technology is expanding into insurance underwriting workflows, enabling immediate incident reconstruction rather than post-event claims investigation.
EPA greenhouse gas reporting requirements for heavy-duty trucks now mandate fuel consumption telemetry capture and idle-time documentation. This regulatory pressure forces telematics providers to embed certified flow meters and engine load sensors rather than inferred fuel economy estimates. Western state fleets operating under California Air Resources Board jurisdiction face the most stringent verification protocols, driving hardware specification premiums.
Subscription-based platform economics are displacing perpetual license models across fleet software procurement. Large trucking enterprises now demand consumption-aligned pricing tied to active vehicle counts rather than upfront capital deployment. This shift concentrates most visibly among refrigerated transport operators managing seasonal capacity fluctuations, who prioritize operational expense predictability over asset ownership.
United States Commercial Telematics Market Segmentation
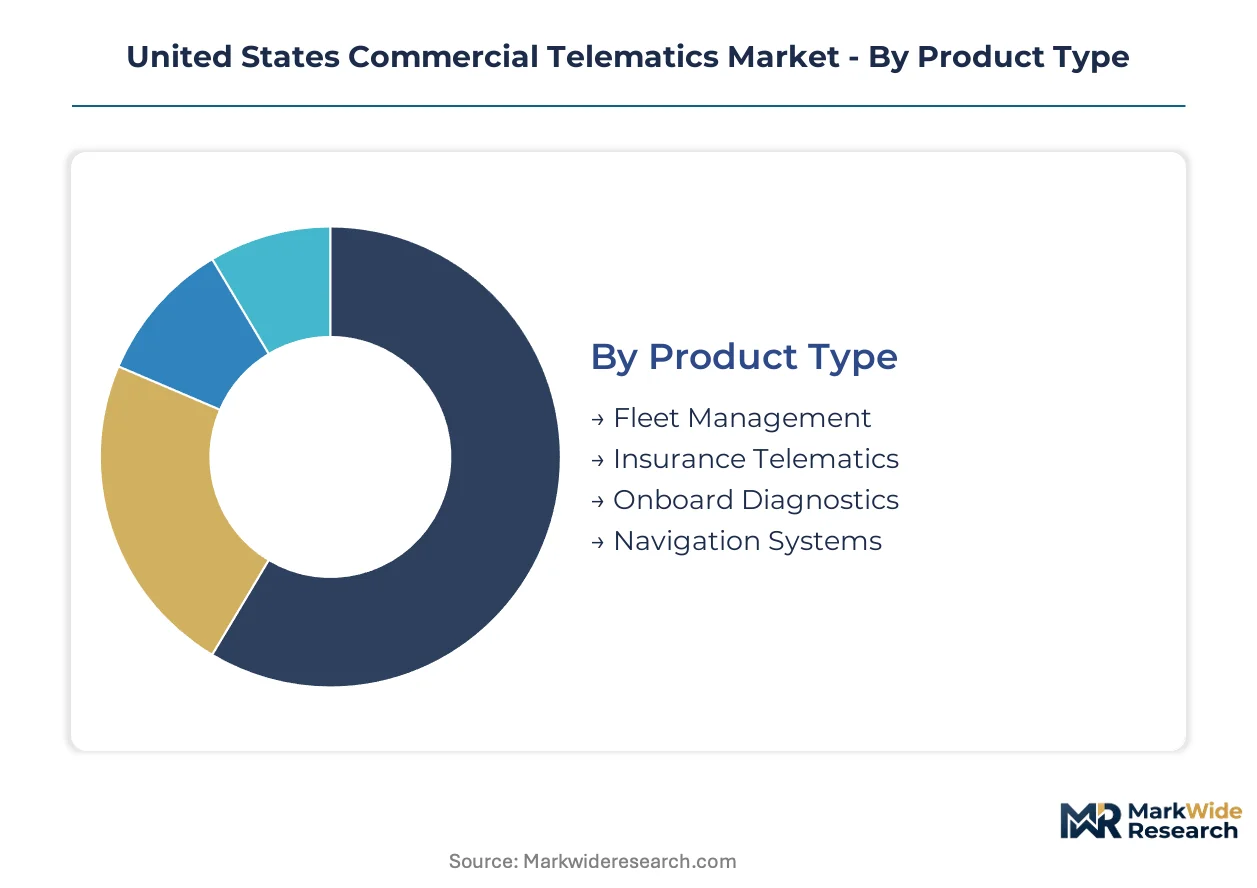
Fleet operators configure telematics investments across hardware, software, and service layers that must integrate with FMCSA compliance mandates and state-level emissions regulations. Segmentation reveals where standardization dominates versus where customization commands pricing premiums.
Product Type:
Standardization concentrates in compliance-driven hardware, while customization dominates analytics platforms serving specialized fleet verticals.
- Fleet Management:Integrated platforms combining GPS tracking, route optimization, and dispatch coordination process CAN-bus data at 500 kbps for real-time asset visibility. Long-haul carriers operating under FMCSA hours-of-service rules anchor demand in the Midwest and Southeast corridors where freight density justifies full-featured deployments.
- Insurance Telematics:Usage-based pricing models deploy accelerometers, gyroscopes, and video event recorders to reconstruct incidents and score driver risk. Commercial auto underwriters in Texas and California are attaching these systems fastest where litigation costs drive premium differentiation.
- Onboard Diagnostics:J1939 and OBD-II protocol translators capture engine fault codes and emission system status for predictive maintenance scheduling.
- Navigation Systems:Truck-specific routing algorithms incorporate bridge height clearances, hazardous materials restrictions, and real-time traffic overlays.
Most installed capacity flows through Fleet Management. Expansion is steepest in Insurance Telematics.
End User:
Volume scales inversely with contract complexity, as asset-light operators prioritize rapid deployment over deep system integration.
- Logistics Companies:E-commerce fulfillment networks and third-party logistics providers operate mixed fleets requiring API interoperability with warehouse management and customer notification systems. Last-mile delivery electrification in California and New York is forcing battery state-of-charge telemetry into standard procurement specifications.
- Transportation Firms:For-hire trucking carriers face the most stringent FMCSA ELD enforcement and EPA greenhouse gas reporting obligations, compressing vendor selection toward integrated suite providers.
- Government Agencies:Municipal fleets and federal installations emphasize cybersecurity certification and domestic supply chain provenance over feature breadth.
- Construction Businesses:Heavy equipment telematics tracks idle time, engine load factors, and geofenced operating zones for dispersed project sites.
Logistics Companies deploy the densest sensor networks. Transportation Firms are gaining share fastest as compliance mandates harden.
Deployment:
Capital intensity separates cloud-native adopters from operators retaining legacy on-premise infrastructure for data sovereignty.
- Cloud-based:Multi-tenant architectures with consumption-aligned pricing tied to active vehicle counts eliminate upfront server deployment. Refrigerated transport operators managing seasonal capacity fluctuations in the Pacific Northwest and Gulf Coast prioritize operational expense predictability.
- On-premise:Dedicated server installations persist among defense contractors and critical infrastructure operators subject to NIST cybersecurity frameworks.
- Hybrid:Edge-computing nodes process video analytics locally while transmitting aggregated telemetry to cloud portals, reducing cellular data costs.
- Mobile Solutions:Smartphone-based driver applications substitute for dedicated hardware in owner-operator segments with sub-ten-vehicle fleets.
Cloud-based architectures carry the majority of new subscriptions. Hybrid deployments are climbing the fastest as edge AI capabilities mature.
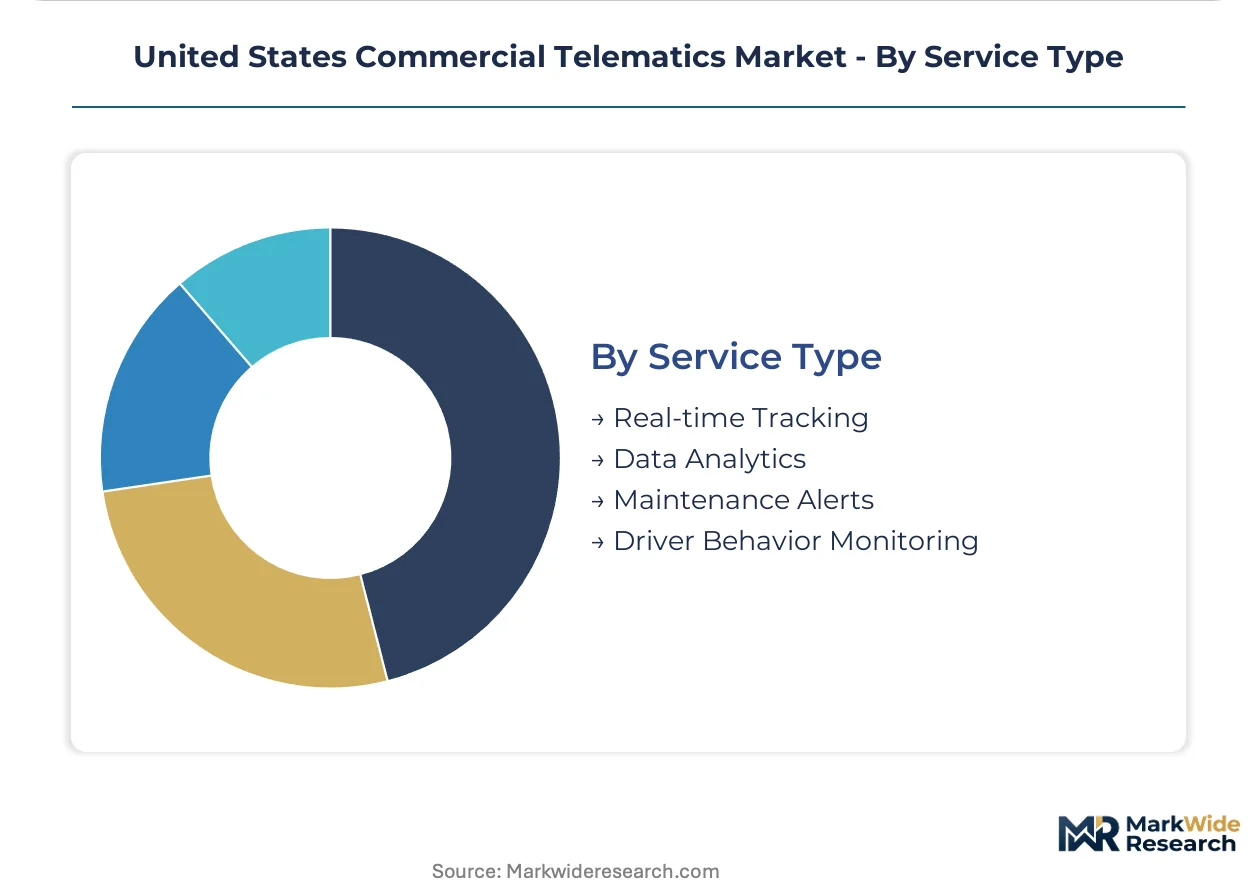
Service Type:
Margin structure varies sharply between commoditized location tracking and predictive analytics commanding recurring revenue premiums.
- Real-time Tracking:Cellular LTE and emerging 5G modems transmit compressed GPS coordinates and geofence alerts at sub-minute intervals. Baseline fleet visibility services face pricing pressure as hardware costs commoditize.
- Data Analytics:Machine learning models consuming fuel consumption patterns, driver behavior scores, and maintenance histories generate actionable recommendations. Large enterprise fleets in the Ohio River Valley freight corridor are consolidating vendor relationships around platforms with embedded business intelligence tools.
- Maintenance Alerts:Predictive algorithms flag component degradation before failure, scheduling depot interventions during planned downtime windows.
- Driver Behavior Monitoring:Video telematics with AI inference at the network edge detects fatigue, distraction, and following-distance violations for immediate coaching intervention.
Real-time Tracking retains the largest installed base. Data Analytics is expanding most quickly as fleet operators seek ROI demonstration from telematics investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial telematics infrastructure first achieved meaningful scale in California's Central Valley freight corridors during the early 2000s, where agricultural logistics operators pioneered satellite-linked fleet tracking for perishable cargo monitoring.
California
California's Advanced Clean Trucks regulation mandates zero-emission vehicle telematics integration for fleets operating within state borders. CARB verification protocols require certified fuel flow meters and battery thermal management sensors that exceed federal baseline specifications. Los Angeles-Long Beach port complex operators deploy the densest sensor networks for drayage truck electrification monitoring.
Texas
Texas energy sector logistics drive specialized telematics demand for hazardous materials routing and pipeline security coordination. FMCSA enforcement along I-35 and I-10 corridors maintains strict hours-of-service compliance verification. Dallas-Fort Worth metroplex hosts the highest concentration of insurance telematics underwriting partnerships for commercial auto risk scoring.
Illinois
Illinois anchors Midwest refrigerated transport telematics adoption with Chicago's intermodal rail-truck transfer facilities requiring real-time cold chain monitoring. EPA greenhouse gas reporting obligations for heavy-duty trucks operating through Ohio River Valley freight corridors push fleets toward integrated emissions telemetry. Peoria-based construction equipment manufacturers influence telematics protocol standards for off-highway machinery.
Georgia
Georgia's Savannah Port expansion accelerates last-mile delivery electrification telematics for e-commerce fulfillment networks serving the Southeast. State-level incentives for electric commercial vehicle deployment align with federal IRA clean fleet provisions. Atlanta metropolitan area logistics operators prioritize cloud-native platforms with API interoperability for warehouse management integration.
Michigan
Michigan automotive manufacturing heritage shapes telematics hardware engineering talent concentration around Detroit-Ann Arbor corridor. NHTSA autonomous vehicle testing guidelines intersect with FMCSA commercial truck regulations to create mixed-fleet data standardization challenges. Grand Rapids-based furniture logistics networks deploy specialized asset tracking for high-value freight damage prevention.
United States Commercial Telematics Market Key Industry Players
Premium-margin players sit above commodity-margin players across compliance-certification and analytics-integration dimensions, with integrated suite providers commanding pricing power over point-solution vendors. The vendor base clusters into three strategic archetypes: legacy routing specialists anchoring long-haul carrier relationships, open-architecture platform builders enabling third-party app integration, and cloud-native specialists targeting rapid-deployment mid-size fleets. Dominant competitive moves include API marketplace expansion and edge-computing video analytics capability acquisition.
Within the legacy infrastructure tier, Omnitracs exemplifies established carrier relationship anchoring, while Platform Science occupies a position as an open-architecture API integrator. Samsara represents the cloud-native deployment specialist archetype targeting mid-size fleet rapid adoption. These three entities collectively illustrate how vendor selection criteria have shifted from standalone hardware procurement toward subscription-based platform economics.
| Leading Market Players |
|---|
| Omnitracs |
| Platform Science |
| Geotab Inc. |
| Zonar |
| Teletrac Navman |
| Verizon Connect |
| Trimble Inc. |
| MiX Telematics |
| Samsara Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up telematics specialists have consolidated fragmented hardware vendors across the Midwest and Southeast, concentrating procurement leverage with fleet buyers while compressing margins on commoditized GPS units and cellular modems. This ownership pattern feeds pricing discipline through volume-tiered SaaS contracts that bundle compliance hardware with analytics subscriptions, shifting margin capture toward recurring software revenue.
Pricing Analysis
Consumption-aligned subscription tiers dominate fleet procurement, separating enterprise-grade platforms with FMCSA-certified ELD integration from mid-market video telematics bundles and entry-level smartphone-based tracking. Price differentiation hinges on cellular data throughput allowances and API interoperability depth, with California CARB-compliant hardware commanding specification premiums. Cost compression in entry-level hardware is intensifying as Asian modem suppliers expand direct-to-fleet distribution, eroding traditional reseller margins. Owner-operators with sub-ten-vehicle fleets exhibit highest price sensitivity, while refrigerated transport enterprises prioritize operational expense predictability over upfront capital deployment.
Supply Chain Analysis
Dual-sourcing requirements from large trucking enterprises mandate qualified secondary suppliers for CAN-bus controllers and LTE modems, reducing concentration risk but extending vendor validation timelines. Manufacturing concentrates in Taiwan for semiconductor components, Mexico for final hardware assembly, and China for cellular modem production. Raw material dependencies include lithium-ion battery cells for electric vehicle telematics, rare earth magnets for GPS antennas, and epoxy resins for ruggedized enclosures. Tariff exposure on Chinese-origin electronics creates margin pressure for hardware vendors without diversified sourcing. Distribution runs through direct enterprise sales teams for large carriers, value-added resellers for mid-size fleets, and mobile application stores for owner-operator segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial telematics offers margin expansion through cloud-native platform economics displacing perpetual license models, with software attach rates rising as fleet operators consolidate vendor relationships around integrated suites.
For Market Incumbents: Deepen vertical integration into edge-computing hardware to capture video analytics premiums and defend against open-architecture API competitors. Fortify FMCSA certification moats through accelerated ISO/SAE 21434 cybersecurity alignment, extending validation timelines that disadvantage point-solution entrants. Prioritize API marketplace expansion to lock in third-party logistics application budgets before platform competitors consolidate fleet software procurement. For New Entrants and Emerging Players: Edge AI inference capabilities for real-time driver fatigue detection represent the most penetrable wedge into mid-size regional fleet segments underserved by legacy routing specialists. Target Western state zero-emission mandate compliance as a regulatory-forced replacement cycle, offering battery-electric vehicle-specific telemetry with charging optimization algorithms. Deploy consumption-based pricing with rapid-deployment cloud infrastructure to bypass incumbent enterprise sales cycles. For Investors and Strategic Acquirers: Fleet management software consolidators are the most active acquirer in this space, seeking cloud-native platforms with proven API ecosystems to augment legacy hardware portfolios. Acquisition target archetypes include mid-size video telematics specialists with edge-computing IP and regional compliance software vendors with CARB or FMCSA certification authority. Watch cellular 5G network densification pace along interstate corridors as the signal for video telematics attach-rate inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API Marketplace Expansion | Open-architecture platforms capture fleet software budgets previously allocated to standalone dispatch systems. |
| Edge-Computing Video Analytics Acquisition | Real-time AI inference capabilities differentiate platforms for insurance telematics underwriting partnerships. |
| FMCSA Cybersecurity Certification Investment | ISO/SAE 21434-aligned hardware extends vendor validation timelines that protect incumbent market position. |
| Zero-Emission Vehicle Telematics Development | California CARB verification protocols create specification premiums for battery thermal management sensors. |
| Subscription Pricing Model Transition | Consumption-aligned contracts tied to active vehicle counts displace upfront capital deployment in refrigerated transport. |
Research Approach
Direct dialogue with fleet operations directors, telematics platform product managers, commercial auto underwriters, and FMCSA compliance officers grounded qualitative findings in operational reality. Secondary validation drew from FMCSA ELD certification databases, EPA greenhouse gas reporting filings, SEC 10-K disclosures from listed telematics providers, and cellular carrier infrastructure deployment announcements. Bottom-up fleet adoption modeling triangulated against top-down market sizing from hardware shipment data and SaaS subscription metrics.
Bottom-up segment analysis across fleet management, insurance telematics, and onboard diagnostics product categories informed value projections over the analysis window. Deployment models segmented by cloud-native, on-premise, hybrid, and mobile solution architectures captured differential adoption velocities. Organization size tiers from owner-operators through enterprise carriers, vertical specialization across refrigerated transport and hazardous materials, and regional regulatory clusters including California CARB and Texas energy sector requirements structured the analytical framework. CAGRs derived from logistic curve penetration modeling against compliance mandate enforcement timelines.
The model holds under steady FMCSA enforcement intensity and continued 5G network densification; deviation in semiconductor supply availability or state privacy statute fragmentation would shift hardware deployment timelines materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
In-Car Infotainment Market