
 Hot Food Display Cabinet Market | 2026-2036
Hot Food Display Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Food Display Cabinet Market Foresight
Cloud kitchen operators and ghost kitchen networks is reorganizing procurement priorities toward compact, high-throughput hot food display cabinets. Alto-Shaam Inc. anchors its position through controlled-humidity technology that extends holding time without quality degradation. Hatco Corporation competes through a broad electric warming portfolio that dominates North American chain restaurant specifications. True Manufacturing Co. Inc. leverages its domestic fabrication footprint to sustain short-lead-time fulfillment for regional foodservice distributors.
A hot food display cabinet is an electrically or gas-heated enclosure with tempered glass panels, calibrated thermostats maintaining food at safe temperatures, and humidity controls to prevent moisture loss, designed for commercial kitchens to merchandise prepared items while holding them at service-ready conditions. Floor standing units command the largest installed base due to their capacity for multi-pan buffet and cafeteria lines, though countertop configurations are gaining traction in space-constrained urban food halls and mobile operations. Electric power source models lead volume shipments as induction and hybrid systems remain premium alternatives limited by kitchen electrical infrastructure and operator familiarity.
The U.S. Department of Energy appliance standards and EU Ecodesign Directive impose minimum efficiency thresholds that filter out non-compliant imports and elevate insulated glass and LED lighting as baseline specifications. NSF International sanitation certification and equivalent EU hygiene frameworks determine market access for cabinet surfaces, door seals, and interior materials. Stakeholders must monitor evolving food safety temperature logging requirements and refrigerant-phaseout timelines that will reshape cabinet insulation and heating element supply chains.
Market Dynamics
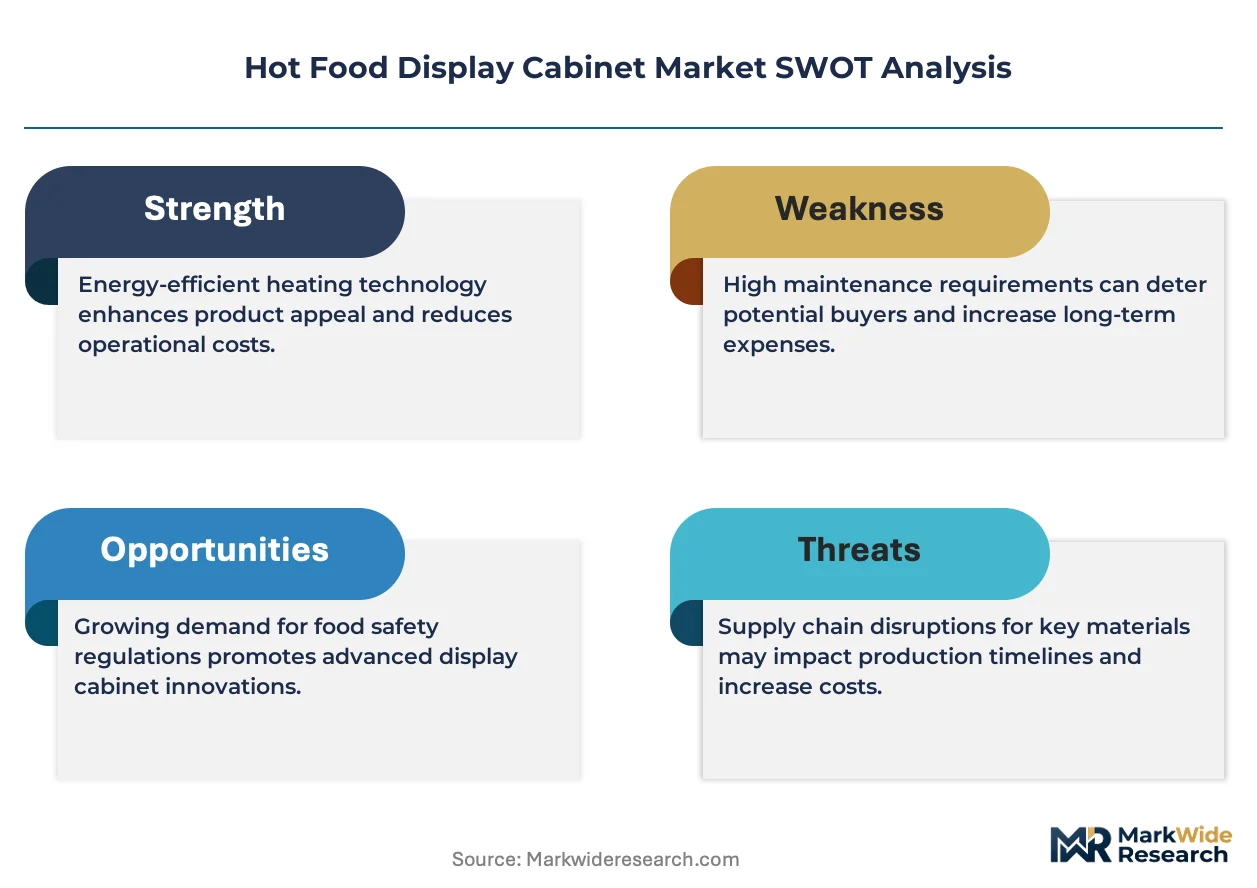
The U.S. Department of Energy appliance standards and EU Ecodesign Directive are compressing replacement cycles toward insulated glass and LED-lit configurations, while quick-service restaurant chains in North America and Europe expand hot-holding infrastructure to offset labor cost pressures.
Growth Catalysts
- Energy-efficiency mandates:The U.S. Department of Energy and EU Ecodesign Directive enforce minimum efficiency thresholds that filter non-compliant imports and elevate LED lighting and insulated glass as baseline specifications across commercial foodservice.
- Cloud kitchen proliferation:Ghost kitchen networks are reorganizing procurement priorities toward compact, high-throughput hot food display cabinets designed for space-constrained urban delivery operations.
- Food safety automation:Labor cost pressures and food safety standards in the United States, Germany, and Japan are accelerating automation of display and holding equipment to reduce manual temperature monitoring.
Market Restraints
- Electrical infrastructure constraints:Induction and hybrid heating systems remain limited by kitchen electrical capacity and operator familiarity, constraining premium technology penetration in older foodservice facilities.
- Input cost volatility:Tempered glass panel and stainless steel enclosure costs fluctuate with commodity markets, compressing margins for manufacturers serving price-sensitive regional distributors.
- Certification friction:NSF International sanitation certification and equivalent EU hygiene frameworks create multi-month approval timelines for cabinet surfaces, door seals, and interior materials before market access.
Strategic Opportunities
- Mobile food operations:Countertop configurations are gaining traction in space-constrained urban food halls, food trucks, and temporary event catering where floor standing units prove impractical.
- Temperature logging integration:Evolving food safety requirements for automated temperature documentation are creating white space for connected cabinets with embedded sensors and cloud-based compliance reporting.
- Refrigerant-phaseout adaptation:Cabinet insulation and heating element supply chains face restructuring timelines that favor early movers in alternative thermal barrier materials and element designs.
Industry Challenges
- Skilled technician scarcity:Calibration of humidity controls and thermostat accuracy requires specialized service expertise that regional foodservice distributors struggle to source consistently.
- Legacy system integration:Connected hot food display cabinets must interface with existing kitchen management platforms, creating API compatibility and data standardization hurdles for operators with heterogeneous equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Food Display Cabinet Market |
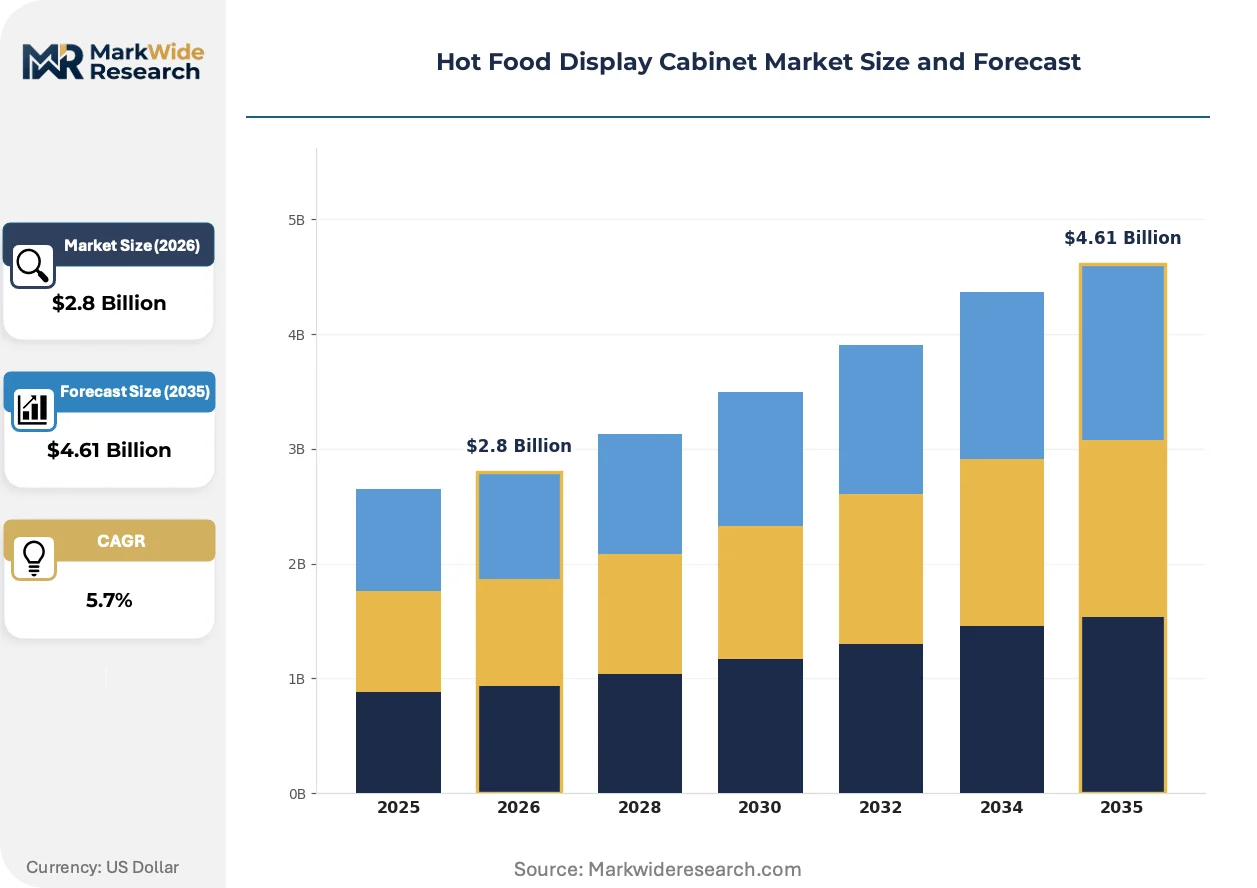
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Wall Mounted, Floor Standing, Heated Shelf Application: Restaurants, Cafeterias, Bakeries, Food Trucks Design Style: Modern, Classic, Rustic, Minimalist Power Source: Electric, Gas, Induction, Hybrid |
| Companies Covered | Alto-Shaam Inc., Hatco Corporation, True Manufacturing Co. Inc., Carrier Global Corporation, Hoshizaki Corp, The Vollrath Company LLC, The Middleby Corporation, Beverage Air, Lincat Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Food Display Cabinet Market Shifts & Advancements
Controlled-humidity technology and induction heating systems are actively reshaping competitive positioning in hot food display cabinets, while regulatory pressure on energy consumption and food safety documentation accelerates hardware-software convergence.
Humidity-controlled holding technology maintains precise moisture levels to extend food quality duration without dehydration or sogginess. Quick-service chains and institutional cafeterias in the United States and Germany are adopting these systems at accelerated rates to reduce waste and extend service windows. This capability is supplanting traditional dry-heat holding in premium segments where food quality consistency commands procurement priority.
The EU Ecodesign Directive and U.S. Department of Energy appliance standards impose escalating efficiency thresholds on commercial foodservice equipment. These frameworks are filtering out non-compliant imports and mandating LED lighting, insulated glass, and improved thermal seals as baseline specifications. European manufacturers and their North American distribution partners are responding by accelerating R&D cycles to maintain market access.
Cloud kitchen operators and ghost kitchen networks are consolidating procurement decisions at the network level rather than individual unit level. This buyer concentration is compressing vendor negotiation timelines and favoring suppliers with configurable product platforms and rapid fulfillment capabilities. The shift is most visible in dense urban clusters across the United States, United Kingdom, and United Arab Emirates where delivery-only food production scales fastest.
Hot Food Display Cabinet Market Segmentation
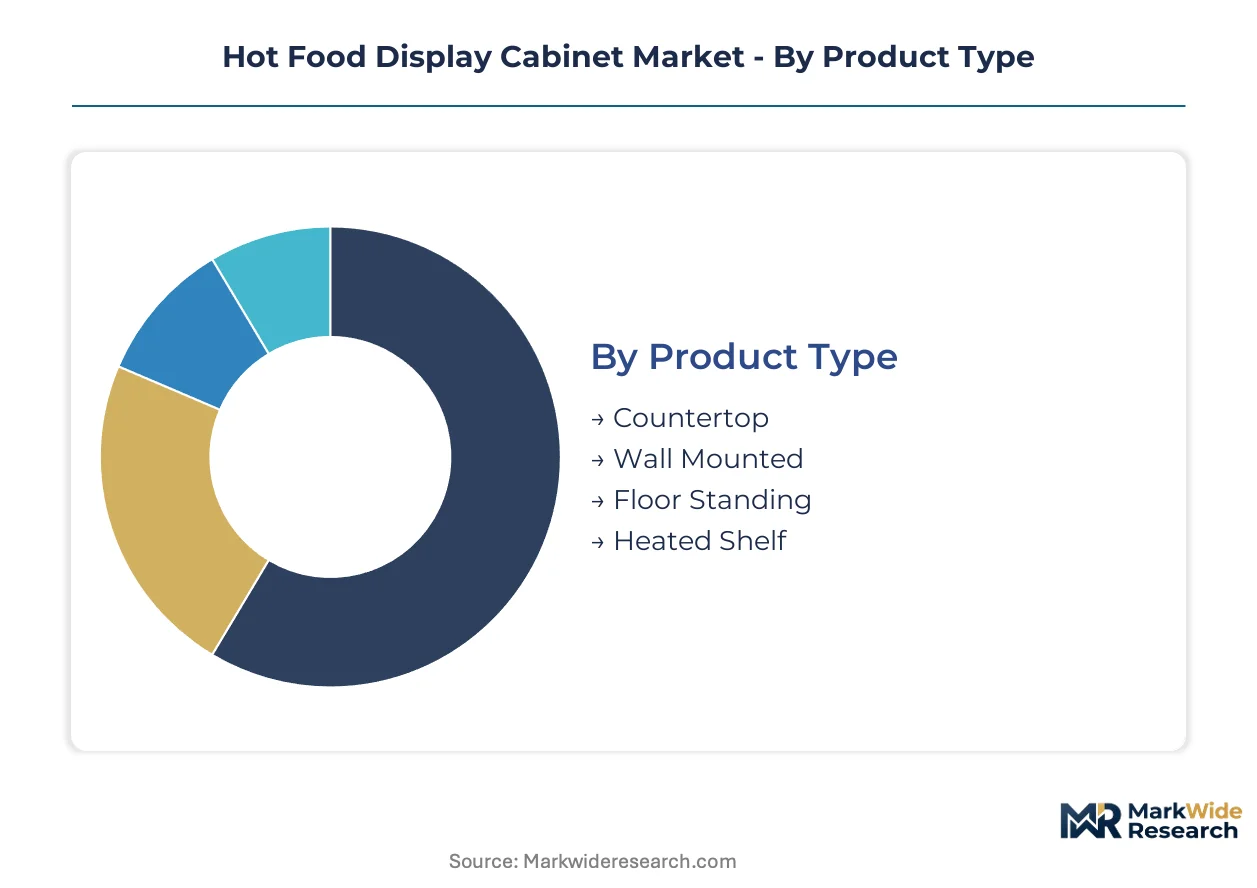
Hot food display cabinet procurement patterns diverge sharply between domestic foodservice operations and export-led equipment distributors. Understanding these segment boundaries clarifies why certain configurations dominate specific geographies while others remain niche specialties.
Product Type:
Domestic North American and European demand concentrates in floor standing and countertop formats, while wall mounted and heated shelf variants ship disproportionately to export markets in Asia-Pacific and Middle East cloud kitchen clusters.
- Floor Standing:Multi-pan capacity with tempered glass enclosures and calibrated thermostats serves high-volume buffet lines and institutional cafeterias. Quick-service chains in the United States and Germany specify these units to offset labor cost pressures through extended holding windows. Floor standing configurations command the established base across commercial foodservice.
- Countertop:Compact footprints with reduced pan capacity target space-constrained urban food halls and ghost kitchen operations. Cloud kitchen networks in dense metropolitan clusters favor these units for delivery-only production environments. The steepest expansion runs through countertop configurations as mobile and temporary operations multiply.
- Wall Mounted:Vertical orientation preserves floor space in compact kitchen layouts common in European urban restaurants and Japanese convenience store formats.
- Heated Shelf:Open-display warming surfaces suit bakery merchandising and front-of-house presentation in Middle Eastern hotel foodservice operations.
Procurement volume stratifies by kitchen footprint constraints rather than cuisine type alone.
Application:
Cost tier segmentation separates premium-specified institutional cafeterias from price-sensitive independent restaurants, with food trucks and bakeries occupying intermediate positions.
- Restaurants:Full-service and quick-service operators demand humidity-controlled holding technology to maintain food quality across extended service periods. Chains in the United States specify NSF-certified surfaces and LED-lit displays to satisfy FDA food safety visibility requirements. Restaurants absorb the majority of electric-powered floor standing shipments.
- Cafeterias:Institutional feeding operations in Germany and Japan prioritize high-capacity multi-pan units with automated temperature logging for compliance documentation. EU Ecodesign Directive efficiency thresholds filter procurement toward insulated glass and improved thermal seal configurations. Cafeterias anchor demand for connected cabinets with embedded sensor networks.
- Bakeries:Heated shelf and countertop formats dominate pastry and bread warming applications where moisture retention is critical.
- Food Trucks:Compact countertop and wall mounted units with dual-power compatibility serve mobile operations requiring rapid deployment and breakdown.
Cafeterias anchor institutional procurement volume. Food trucks are climbing the fastest as mobile foodservice regulations liberalize across North American metropolitan markets.
Design Style:
Customer type differentiation separates specification-driven chain procurement from aesthetic-driven independent operator purchases.
- Modern:Clean lines, LED accent lighting, and stainless steel finishes align with quick-service chain brand standards and contemporary food hall environments. Chains in the United Kingdom and United Arab Emirates specify modern styling for customer-facing display positions. Modern configurations integrate most seamlessly with connected kitchen management platforms.
- Classic:Traditional curved glass and brass trim elements persist in heritage hotel dining rooms and upscale independent restaurants in France and Italy. Classic styling commands premium pricing in front-of-house applications where visual warmth supports brand positioning.
- Rustic:Wood-accented enclosures and matte black steel frames target farm-to-table concepts and specialty coffee chains in Pacific Northwest United States markets.
- Minimalist:Frameless glass and concealed hardware serve high-design urban food halls in Copenhagen and Amsterdam where architectural integration takes priority.
Modern styling dominates chain specifications. Minimalist designs are gaining share fastest among architect-led food hall developments.
Power Source:
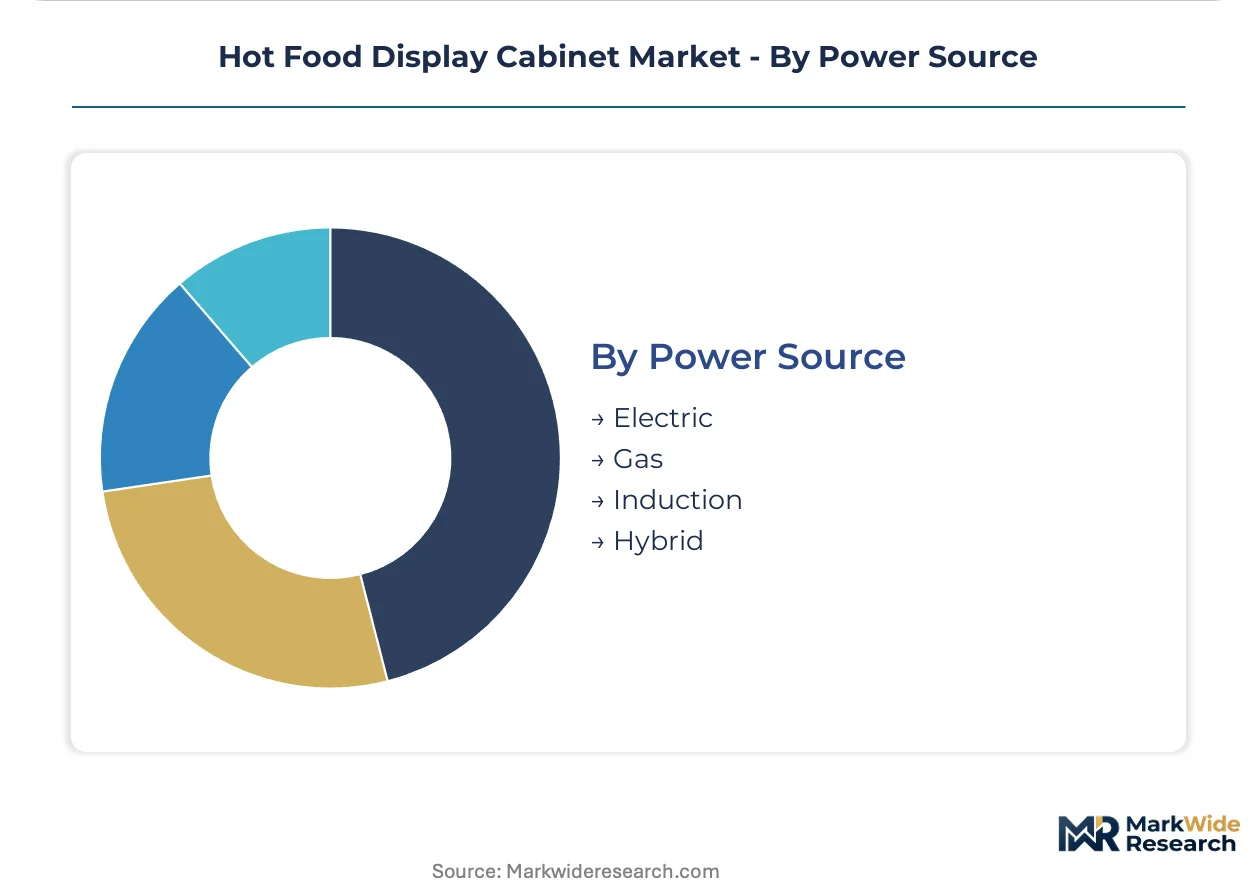
Supply concentration in electric heating element manufacturing shapes regional availability, while gas and hybrid systems face infrastructure-dependent adoption curves.
- Electric:Resistance and radiant heating elements with precise thermostat control constitute the standard specification across North American and European commercial kitchens. The U.S. Department of Energy appliance standards and EU Ecodesign Directive accelerate LED lighting and insulated glass bundling with electric platforms. Electric systems anchor the installed base through distributor familiarity and service network coverage.
- Induction:Magnetic field heating delivers rapid temperature response and energy efficiency advantages in premium quick-service test kitchens and institutional renovation projects. Japan's METI efficiency labeling program and German technical institute certifications validate induction performance claims. Induction is expanding most quickly in new-build facilities with adequate electrical capacity.
- Gas:Propane and natural gas configurations persist in mobile food operations and older facilities with limited electrical infrastructure.
- Hybrid:Dual-source systems combining electric holding with gas boost heating serve high-peak-demand catering operations and temporary event installations.
Electric platforms anchor replacement cycles. Induction configurations are climbing the fastest as energy-efficiency mandates tighten and electrical infrastructure upgrades proceed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered hot food display cabinets to quick-service chains across the United States and United Kingdom, while Japanese fabricators supply humidity-controlled systems to cloud kitchen operators in Singapore and Dubai.
United States
Quick-service restaurant chains expand hot-holding infrastructure to offset labor cost pressures in California and Texas metropolitan clusters. The U.S. Department of Energy appliance standards enforce minimum efficiency thresholds that filter non-compliant imports. Chicago and Atlanta distribution hubs channel floor standing electric units to regional foodservice operators.
Germany
Institutional cafeteria operators prioritize high-capacity multi-pan units with automated temperature logging for compliance documentation. The EU Ecodesign Directive mandates LED lighting and insulated glass as baseline specifications. Bavarian technical institutes validate induction heating performance claims for export markets.
Japan
Convenience store chains and urban restaurant operators demand compact wall mounted configurations for space-constrained kitchen layouts. METI efficiency labeling programs accelerate adoption of energy-optimized holding technology. Tokyo and Osaka manufacturing clusters supply controlled-humidity systems throughout East Asian markets.
United Arab Emirates
Hotel foodservice operations in Dubai and Abu Dhabi specify heated shelf configurations for front-of-house bakery merchandising. MOHAP hygiene frameworks determine market access for cabinet surfaces and interior materials. Jebel Ali logistics corridors re-export European and Asian equipment to Saudi Arabia and Qatar.
United Kingdom
Ghost kitchen networks in London and Manchester reorganize procurement toward compact countertop units for delivery-only production environments. EU Ecodesign Directive compliance remains mandatory for post-Brexit equipment imports. Birmingham distribution centers serve regional cloud kitchen clusters.
Hot Food Display Cabinet Market Competitive Landscape
Player mix skews toward mid-cap specialists with controlled-humidity expertise alongside diversified commercial foodservice conglomerates. The vendor base separates into three strategic archetypes: precision-holding technology specialists, broad-line warming equipment manufacturers, and regional fabrication houses with short-lead-time fulfillment capabilities. Dominant competitive moves include portfolio diversification into connected sensor platforms and strategic partnerships with cloud kitchen network operators.
Within the precision-holding tier, Alto-Shaam Inc. and Hatco Corporation exemplify divergent approaches to market positioning. Alto-Shaam Inc. anchors the controlled-humidity technology segment through Wisconsin-based engineering capabilities. Hatco Corporation occupies a position within the broad electric warming portfolio space that dominates North American chain restaurant specifications. True Manufacturing Co. Inc. represents the domestic fabrication archetype with Missouri-based production assets.
| Leading Market Players |
|---|
| Alto-Shaam Inc. |
| Hatco Corporation |
| True Manufacturing Co. Inc. |
| Carrier Global Corporation |
| Hoshizaki Corp |
| The Vollrath Company LLC |
| The Middleby Corporation |
| Beverage Air |
| Lincat Group |
| Others |
Supply & Pricing Matrix
NSF International sanitation certification gates both supplier qualification and price differentiation simultaneously in hot food display cabinets, filtering non-compliant imports from Asia-Pacific while creating certification-grade premiums for domestic manufacturers serving quick-service chains in the United States and Germany.
Pricing Analysis
Current-generation humidity-controlled cabinets command substantial premiums over prior-generation dry-heat units and next-generation induction systems. Three-tier pricing structure across premium, standard, and economy levels separates Alto-Shaam's controlled-humidity technology from Hatco's broad electric warming portfolio and regional fabricators' basic insulated models. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because commodity stainless steel and tempered glass input volatility squeezes regional distributor margins. Independent restaurants exhibit highest price sensitivity, while institutional cafeterias in Germany and Japan absorb premium pricing for automated temperature logging compliance.
Supply Chain Analysis
Strait of Malacca transit underwrites critical component flows from Southeast Asian heating element manufacturers to final assembly plants in the United States, Germany, and Japan. Supply concentrates in China for tempered glass panels, Wisconsin and Missouri for controlled-humidity system fabrication, and Bavaria for induction heating validation. Raw material dependencies center on nickel-chromium heating alloys, low-iron tempered glass, and polyurethane insulation foams facing refrigerant-phaseout restructuring. Single-source vulnerability runs through Chinese glass panel suppliers subject to EU Ecodesign Directive carbon border adjustments. Distribution runs through Chicago, Atlanta, and Birmingham foodservice equipment hubs serving regional quick-service chains and cloud kitchen networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from combi-oven holding modes and refrigerated display-to-serve systems that threaten dedicated hot food display cabinet volumes in compact kitchen footprints.
For Market Incumbents: Secure backward integration into heating element supply to offset nickel-chromium price volatility from Chinese suppliers. Deepen channel control through exclusive service partnerships with cloud kitchen network operators in London and Dubai, insulating against Hatco's broad-line distributor relationships. Controlled-humidity patent portfolios provide the strongest defensive moat against combi-oven substitution threats. For New Entrants and Emerging Players: Post-installation calibration and IoT sensor maintenance represent a service-layer gap where incumbents under-serve regional distributors struggling to source skilled technicians. Target countertop configurations for Southeast Asian cloud kitchen clusters in Singapore and Bangkok where electrical infrastructure constraints favor compact electric units over induction. Go-to-market angle should emphasize rapid fulfillment through domestic fabrication partnerships rather than premium technology positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified commercial foodservice conglomerates seeking to divest non-core warming equipment divisions amid portfolio rationalization. Long-term viability centers on software-embedded connected cabinets with recurring sensor maintenance revenue rather than transactional hardware sales. Watch for EU Ecodesign Directive enforcement acceleration as the inflection signal indicating replacement cycle compression toward efficiency-compliant models.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Humidity Patent Expansion | Extends Alto-Shaam's quality-holding differentiation against dry-heat competitors in quick-service chains. |
| Cloud Kitchen Network Partnership | Hatco's distributor relationships with ghost kitchen operators in London secure specification lock-in for countertop units. |
| Induction Heating Certification | Bavarian technical institute validation opens German-manufactured systems to METI-labeled Japanese institutional procurement. |
| IoT Sensor Platform Integration | Embedded temperature logging satisfies FDA automated documentation requirements in California and Texas cafeteria chains. |
| Domestic Fabrication Footprint Expansion | True Manufacturing's Missouri capacity sustains short-lead-time fulfillment against Asian import lead time variability. |
Research Methodology
A standing panel of quick-service chain procurement directors, institutional cafeteria operators, foodservice equipment distributors, and NSF International certification specialists provided ongoing calibration throughout the study. Primary interviews with cloud kitchen network operators in London, Dubai, and Singapore combined with secondary validation from U.S. Department of Energy appliance standard filings, EU Ecodesign Directive compliance databases, and METI efficiency labeling registrations. Bottom-up shipment data from regional distributors triangulated against top-down capacity assessments from Wisconsin, Missouri, and Bavarian manufacturing clusters.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled product type, application, design style, and power source segmentation alongside kitchen footprint constraint tiers. CAGRs derived from replacement cycle timing, regulatory mandate phase-in schedules, and cloud kitchen network expansion trajectories. Industry-specific inputs included tempered glass and stainless steel commodity price indices, electrical infrastructure upgrade rates in urban metropolitan clusters, and food safety temperature logging regulatory evolution.
Underlying assumptions cover energy-efficiency mandate enforcement continuity, cloud kitchen network consolidation patterns, and commodity input price stability, with deviation risk concentrated in refrigerant-phaseout timeline acceleration and trade policy shifts affecting Chinese glass panel imports. Forecasts reflect these documented assumptions. Revision becomes warranted when EU carbon border adjustment thresholds or U.S. Department of Energy standard escalations cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Food Trays and Bowls Market