
 Asia-Pacific Commercial Dishwashers Market | 2026-2036
Asia-Pacific Commercial Dishwashers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Dishwashers Market Outlook
Market Context
China's Guangdong and Zhejiang manufacturing corridors is rewriting supply geography for commercial dishwasher assembly across the Asia-Pacific. Middleby Corporation leverages its established production footprint in the region to serve high-volume institutional buyers with conveyor and flight-type systems. ITW Hobart sustains premium positioning through intensive R&D on heat-recovery technologies and water optimization. Midea Group Co Ltd anchors mass-market penetration with cost-engineered undercounter units distributed through broad hospitality channels.
Technical Definition and Segmentation
Asia-Pacific commercial dishwashers comprise industrial-grade warewashing equipment engineered for high-temperature sanitization cycles exceeding 82°C final rinse temperatures, designed to process 200 to 10,000 rack equivalents per hour across continuous food service operations. The equipment serves restaurants, hotels, hospitals, and institutional cafeterias where manual washing fails health code throughput requirements. Conveyor systems dominate capital deployment in large-scale hotel and hospital central kitchens where rack volume justifies fixed infrastructure investment. Smart technology segments are gaining fastest traction as IoT-enabled units from Electrolux AB and Haier Group Corporation allow remote diagnostics and predictive maintenance, shifting margin pools toward software-integrated service contracts. Undercounter formats remain the volume workhorse for independent restaurants and smaller cafeterias across tier-two Chinese and Indian cities.
Regulatory Environment
China's SAMR enforces GB standards on water efficiency and thermal performance for commercial kitchen equipment, while India's BIS certification mandates electrical safety and energy consumption disclosures that filter import eligibility. Japan's METI Top Runner program pushes manufacturers toward heat-pump recovery and reduced standby power, reshaping product development priorities for Panasonic Corporation and LG Electronics Inc. Stakeholders must monitor how Australia's WELS water rating scheme and emerging ASEAN harmonization talks on commercial kitchen energy labels will reshape cross-border equipment specifications and certification costs.
Market Dynamics
Labor cost inflation across Southeast Asian hospitality corridors is accelerating automated warewashing deployment faster than organic volume growth alone would justify. Full-service restaurant chains in Bangkok and Jakarta now specify conveyor systems as standard build-out equipment, treating dishwashing automation as essential infrastructure rather than optional efficiency.
Growth Catalysts
- India's hotel construction pipeline:Mumbai and Bangalore hospitality developments are triggering synchronized equipment procurement cycles that pull forward replacement demand from adjacent tier-two markets.
- China's GB standards tightening:SAMR-mandated water efficiency thresholds are forcing kitchen equipment upgrades in institutional cafeterias and hospital central kitchens across Guangdong and Zhejiang.
- Heat-pump recovery technology:METI's Top Runner program in Japan is normalizing thermal energy recapture systems that cut operating costs for high-throughput flight-type installations.
Market Restraints
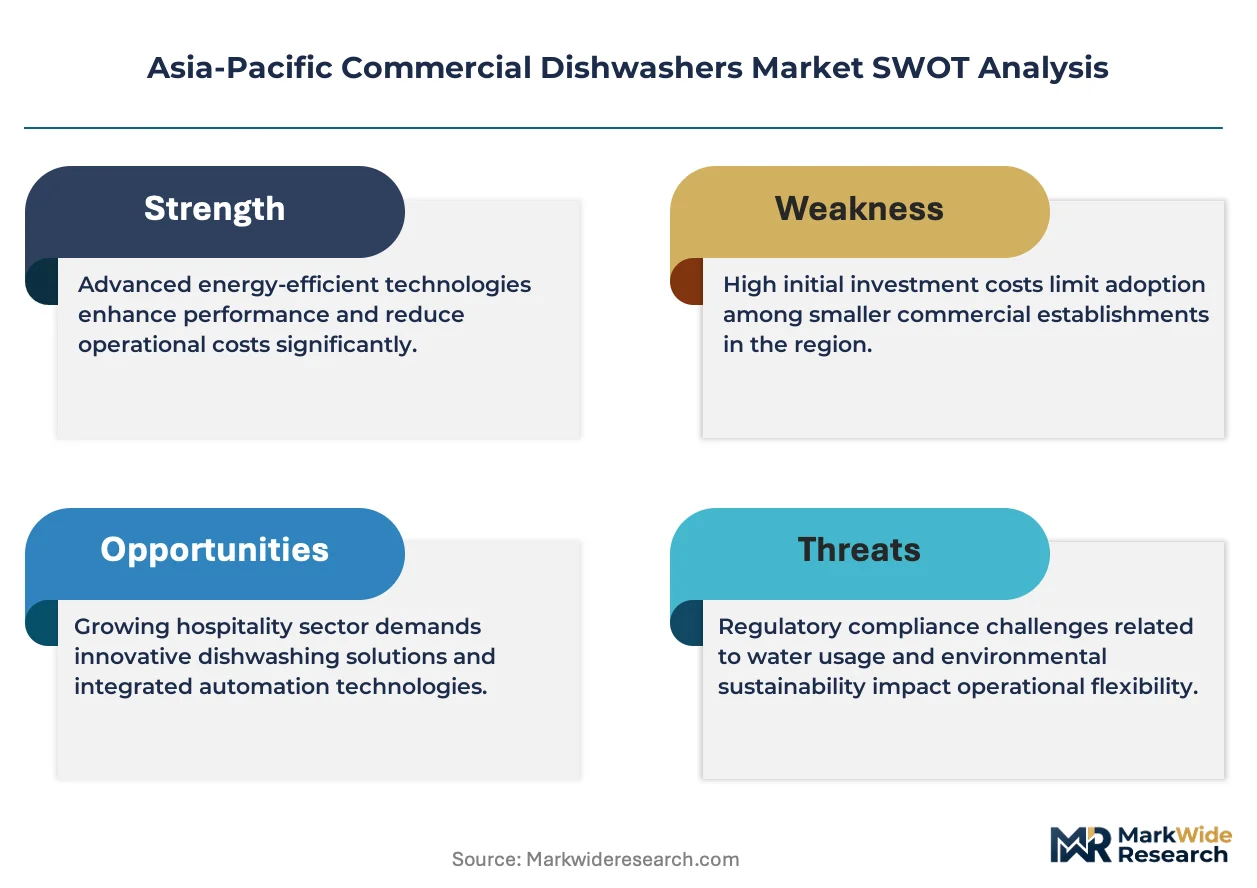
- Stainless steel input volatility:Grade 304 sheet metal price swings compress margin predictability for undercounter unit manufacturers serving cost-sensitive independent restaurants.
- Guangdong supply concentration:Component sourcing clusters around Foshan and Zhongshan create vulnerability to regional logistics disruptions or environmental compliance shutdowns.
- Water infrastructure heterogeneity:Variable municipal pressure and filtration quality across Indonesian and Philippine secondary cities limits standardized product deployment without costly site engineering.
Strategic Opportunities
- Vietnam's emerging hospitality corridor:Da Nang and Nha Trang resort construction is outpacing local distributor capacity, creating first-mover advantage for direct manufacturer-to-contractor relationships.
- IoT-enabled predictive maintenance:Remote diagnostics convergence with cloud-based parts inventory management is opening recurring revenue streams that decouple service profitability from unit sales cycles.
- Australia's WELS expansion:Water rating scheme extension to commercial kitchen equipment creates compliance-driven replacement demand and premium positioning for certified high-efficiency systems.
Industry Challenges
- Field service technician scarcity:Specialized electromechanical repair skills for heat-recovery and smart control modules remain concentrated in Shanghai, Tokyo, and Sydney, leaving secondary markets underserved.
- Legacy electrical integration:Older hotel and hospital buildings across Malaysia and Thailand lack three-phase power infrastructure, requiring expensive electrical retrofits or limiting product specification flexibility.
- BIS certification timelines:India's electrical safety testing backlog stretches import clearance cycles, constraining inventory planning for multinational suppliers serving Mumbai's procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Dishwashers Market |
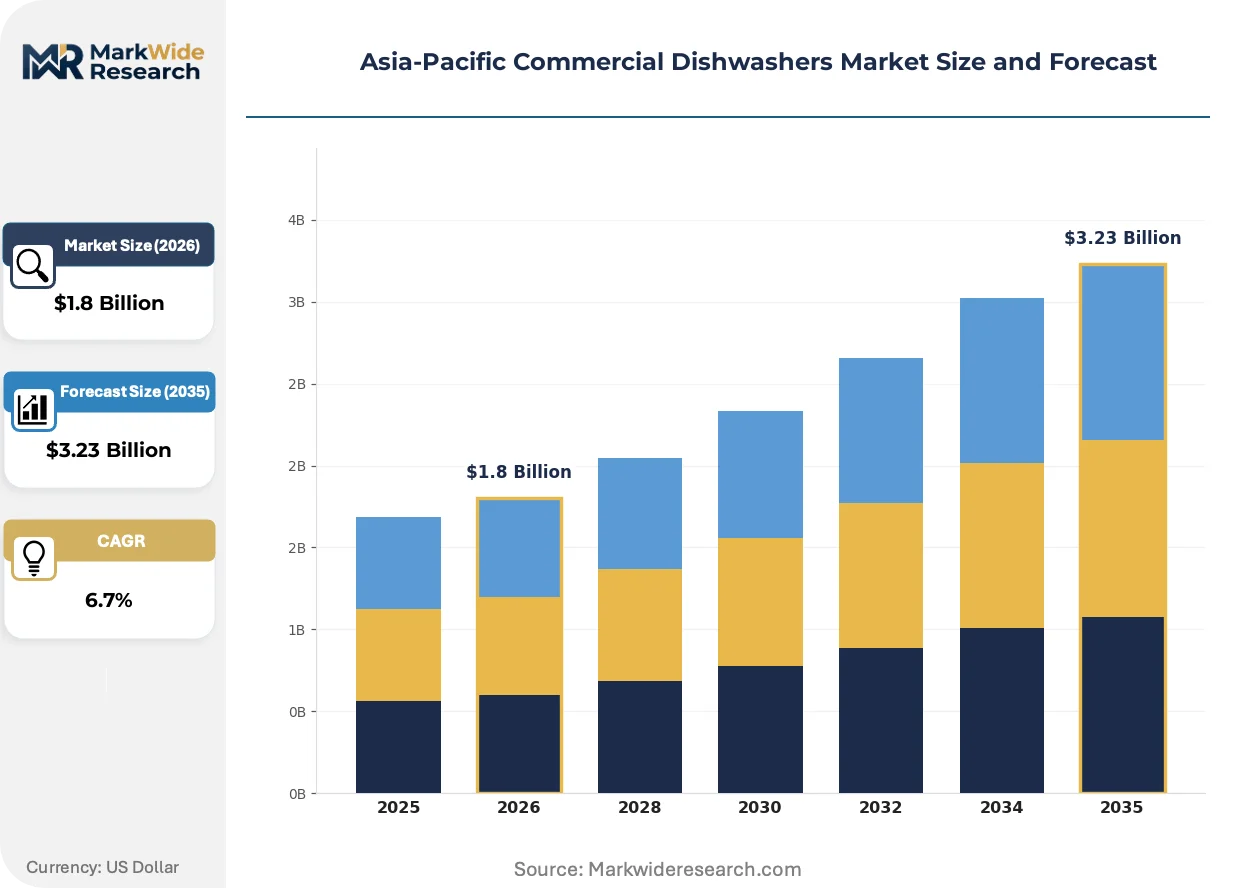
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Undercounter, Door Type, Conveyor, Batch Type End User: Restaurants, Hotels, Cafeterias, Hospitals Technology: Thermal, Chemical, Hybrid, Smart Installation Type: Built-in, Freestanding, Modular, Portable |
| Companies Covered | Middleby Corporation, ITW Hobart, Electrolux AB, Whirlpool Corporation, Haier Group Corporation, Panasonic Corporation, LG Electronics Inc, Samsung Electronics Co, Midea Group Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Dishwashers Market Strategic Shifts
Smart sensor arrays and connected control systems are rewriting competitive advantage in commercial warewashing, shifting value capture from hardware durability toward uptime optimization and operating cost transparency. Equipment buyers now evaluate total lifecycle economics rather than capital expenditure alone.
Ultraviolet-C LED sanitization modules are rendering obsolete traditional high-temperature final rinse systems in sensitive healthcare and pharmaceutical cafeteria environments. Hospital food service directors in Singapore and Melbourne are specifying UVC-equipped undercounter units to eliminate thermal shock damage to delicate serveware while maintaining HACCP compliance. This transition compresses energy consumption profiles and reduces steam ventilation infrastructure requirements in retrofit installations.
China's SAMR is tightening GB standards on commercial kitchen equipment water efficiency and thermal performance, forcing manufacturers to redesign spray arm geometry and pump specifications. The regulatory pressure is accelerating product obsolescence cycles for water-intensive conveyor systems in institutional settings. Domestic suppliers in Guangdong are responding with modular heat exchanger retrofits that extend existing equipment compliance windows without full replacement.
Cloud-based subscription service models are displacing traditional break-fix maintenance contracts among mid-scale restaurant groups across South Korea and Taiwan. Equipment-as-a-service arrangements bundle chemical supply, preventive maintenance, and performance monitoring into per-rack pricing that aligns vendor incentives with operational uptime. This shift is most visible in Seoul's multi-unit franchise operators, where procurement departments prioritize predictable operating expenditure over capital ownership.
Asia-Pacific Commercial Dishwashers Market Segmentation
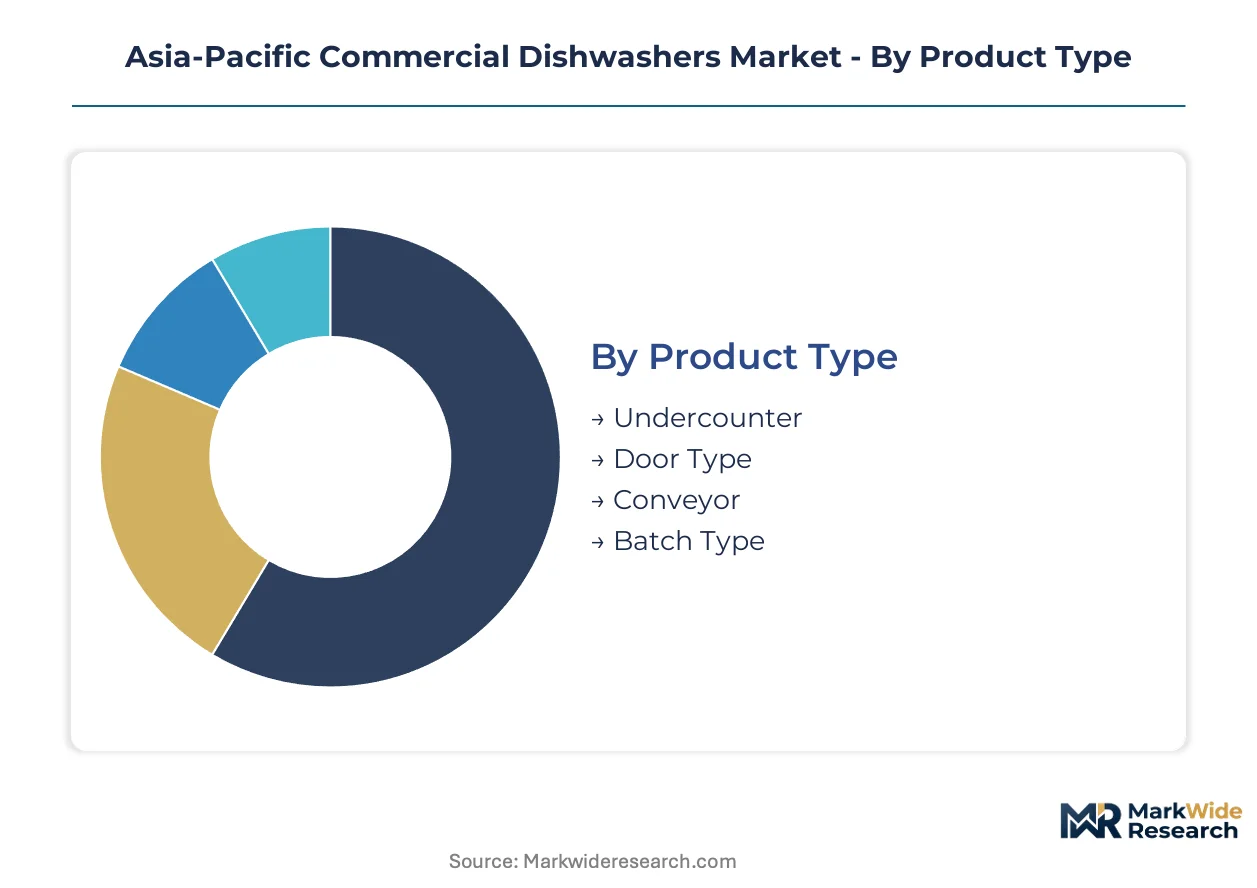
Segmentation in commercial warewashing equipment determines capital allocation cycles, service contract structures, and regulatory compliance pathways. Equipment buyers match product specifications to throughput requirements, energy infrastructure, and building constraints. Manufacturers configure distribution and field service networks around segment-specific replacement frequencies and technical complexity.
Product Type:
Cycle times vary dramatically across formats: undercounter units turn over every 5-7 years in high-volume independent restaurants, while conveyor systems operate on 12-15 year depreciation schedules in institutional central kitchens.
- Undercounter:Compact single-rack units processing 20-40 racks per hour, designed for space-constrained kitchens with 240V single-phase power. Demand concentrates in Mumbai's independent restaurant corridors and tier-two Chinese cities where kitchen footprints average under 80 square meters and labor turnover accelerates equipment wear.
- Conveyor:Continuous-belt flight-type systems handling 200-10,000 racks per hour with integrated drying zones and heat-recovery modules. Bangkok and Jakarta full-service restaurant chains specify these as standard build-out equipment, treating dishwashing automation as essential infrastructure rather than optional efficiency.
- Door Type:Rack-at-a-time batch machines with vertical opening hoods, occupying the middle ground between undercounter convenience and conveyor throughput. Hotels across Malaysia and Thailand deploy these for mid-scale banquet operations.
- Batch Type:Specialized pot-and-pan washers with extended wash cycles and heavy-duty spray arm configurations. Central kitchens in Guangdong institutional cafeterias utilize these for cookware sanitization alongside standard dish machines.
Undercounter dominates installed base. Conveyor is where expansion concentrates.
End User:
Procurement sophistication and total cost of ownership calculations vary sharply across buyer categories, with hospitals and hotel chains employing dedicated equipment specifiers while independent restaurants rely on distributor recommendations.
- Restaurants:Full-service chains across Southeast Asia drive conveyor system deployment as labor cost inflation accelerates automated warewashing adoption. Independent operators in India's metro hospitality corridors prioritize undercounter units with minimal installation complexity.
- Hotels:Central kitchen and banquet operations require matched equipment suites combining conveyor flight-types for peak service with undercounter units for satellite bars and executive floors. Mumbai and Bangalore construction pipelines are triggering synchronized procurement cycles.
- Cafeterias:Institutional feeding operations in China's Guangdong and Zhejiang provinces face SAMR-mandated water efficiency upgrades, forcing equipment replacement in university and corporate dining facilities.
- Hospitals:Healthcare food service directors in Singapore and Melbourne specify UVC-equipped undercounter units to eliminate thermal shock damage to delicate serveware while maintaining HACCP compliance.
Restaurants command volume leadership. Hotels represent the steepest expansion trajectory.
Technology:
Margin pools are shifting from hardware durability toward software-integrated service contracts as connectivity penetration advances across buyer segments.
- Smart:IoT-enabled units with remote diagnostics, predictive maintenance algorithms, and cloud-based performance monitoring. Seoul's multi-unit franchise operators prioritize these for uptime optimization and operating cost transparency.
- Thermal:Conventional high-temperature sanitization exceeding 82°C final rinse, still dominant in legacy installations across secondary Indonesian and Philippine cities where water pressure inconsistency complicates chemical dosing.
- Chemical:Low-temperature sanitization using chlorine or quaternary ammonium compounds, favored where steam ventilation infrastructure is absent or energy costs are prohibitive.
- Hybrid:Dual-mode systems switching between thermal and chemical sanitization based on load type and energy pricing signals.
Thermal dominates installed base. Smart is where expansion concentrates.
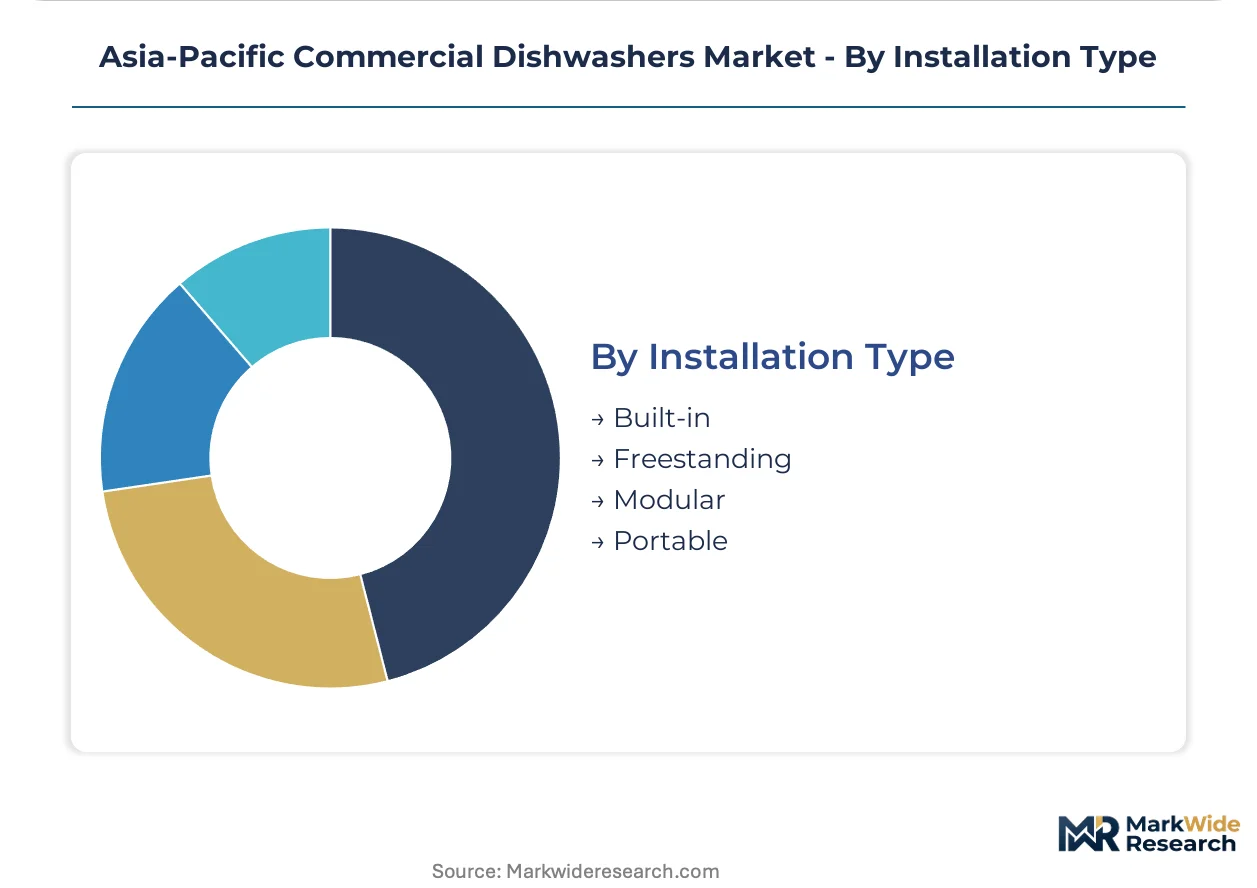
Installation Type:
Building age and electrical infrastructure quality across the region constrain specification flexibility, with older properties in Malaysia and Thailand lacking three-phase power for high-capacity equipment.
- Built-in:Custom-integrated units flush with kitchen millwork, specified in new-construction hotels and hospitals where architectural coordination occurs during design phase. Da Nang and Nha Trang resort construction is outpacing local distributor capacity for these complex installations.
- Freestanding:Self-contained castor-mounted units requiring only utility connections, dominating replacement cycles in existing restaurant and cafeteria operations.
- Modular:Component-based systems allowing capacity expansion through additional wash tanks or conveyor extensions, favored by growing chain operators.
- Portable:Temporary or seasonal deployments with quick-connect plumbing, utilized in catering and event hospitality across Australia's remote mining and resource sector sites.
Freestanding dominates installed base. Built-in is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors the regulatory framework reshaping equipment specifications across the Asia-Pacific, with GB standards on water efficiency and thermal performance forcing redesigns of spray arm geometry and pump specifications throughout Guangdong and Zhejiang manufacturing corridors.
China
Institutional cafeteria procurement cycles in Guangdong and Zhejiang provinces are accelerating as SAMR-mandated water efficiency thresholds force kitchen equipment upgrades. GB standards tightening on commercial kitchen equipment thermal performance is compressing product obsolescence cycles for water-intensive conveyor systems. Domestic suppliers in Foshan and Zhongshan are responding with modular heat exchanger retrofits.
India
Hotel construction pipelines in Mumbai and Bangalore are triggering synchronized equipment procurement cycles that pull forward replacement demand from adjacent tier-two markets. BIS certification mandates electrical safety and energy consumption disclosures that filter import eligibility. Metro hospitality corridors concentrate demand visibility where procurement departments specify undercounter units for independent restaurant build-outs.
Japan
METI's Top Runner program is normalizing heat-pump recovery and reduced standby power in high-throughput flight-type installations. Thermal energy recapture systems are cutting operating costs for hospital central kitchens and large-scale hotel banquet operations. Panasonic Corporation and LG Electronics Inc are reshaping product development priorities around these efficiency benchmarks.
Australia
WELS water rating scheme extension to commercial kitchen equipment is creating compliance-driven replacement demand across institutional cafeterias and hospitality operations. Premium positioning accrues to certified high-efficiency systems that meet tightened consumption thresholds. Sydney and Melbourne equipment specifiers now prioritize lifecycle water economics in procurement decisions.
Vietnam
Da Nang and Nha Trang resort construction is outpacing local distributor capacity for built-in installations requiring architectural coordination. First-mover advantage is opening for direct manufacturer-to-contractor relationships in emerging hospitality corridors. Three-phase power infrastructure gaps in older properties are constraining specification flexibility for high-capacity equipment.
Asia-Pacific Commercial Dishwashers Market Competitive Environment
Multinational conglomerates and specialized commercial kitchen equipment fabricators split the market along technology-tier lines. The vendor base organizes into three strategic archetypes: premium-tier heat-recovery specialists, mass-market volume manufacturers, and smart-connected platform builders. Competitive moves concentrate on M&A to acquire IoT capabilities and geographic expansion through direct-to-contractor relationships in underserved resort corridors.
Within the premium-tier vector, ITW Hobart and Electrolux AB exemplify positioning around intensive R&D investment and heat-recovery technology leadership. Middleby Corporation anchors the institutional-scale segment with conveyor and flight-type systems for high-volume buyers. Midea Group Co Ltd occupies the mass-market penetration position with cost-engineered undercounter units distributed through broad hospitality channels across tier-two Chinese and Indian cities.
| Leading Market Players |
|---|
| Middleby Corporation |
| ITW Hobart |
| Electrolux AB |
| Whirlpool Corporation |
| Haier Group Corporation |
| Panasonic Corporation |
| LG Electronics Inc |
| Samsung Electronics Co |
| Midea Group Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Guangdong and Zhejiang manufacturing corridors concentrate stainless steel component fabrication and pump assembly capacity, anchoring margin pools with original equipment manufacturers while distributor networks capture value through installation and aftermarket service bundling. Grade 304 sheet metal price volatility propagates directly into undercounter unit cost structures, compressing profitability for mass-market suppliers serving independent restaurants across tier-two Chinese and Indian cities.
Pricing Analysis
Price spreads of 40-60% separate premium heat-recovery systems in Tokyo and Sydney from basic undercounter units in Jakarta and Manila. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and after-sales service bundling. Pricing pressure stems from stainless steel input volatility and distributor margin stacking in fragmented secondary markets. Independent restaurants in tier-two cities exhibit highest price sensitivity, while hospital and hotel chains prioritize lifecycle operating cost over capital outlay.
Supply Chain Analysis
Contract manufacturing for electronic control modules and IoT sensor arrays concentrates with EMS providers in Taiwan and South Korea, while mechanical fabrication remains captive to Foshan and Zhongshan metalworking clusters. Supply chains draw from Grade 304 stainless steel mills in China and Indonesia, pump assemblies from Zhejiang province, and heat exchanger components from Japanese specialists. Single-source vulnerability around Guangdong environmental compliance shutdowns threatens component availability. Distribution runs through regional equipment distributors with captive installation crews, supplemented by direct manufacturer-to-contractor relationships in Vietnam's emerging resort corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific commercial dishwashing equipment sits in early-cycle expansion as labor cost inflation across Southeast Asian hospitality corridors accelerates automated warewashing deployment ahead of organic volume growth. IoT-enabled predictive maintenance adoption in Seoul and Taipei signals penetration inflection toward software-integrated service models.
For Market Incumbents: Pre-empt margin erosion in undercounter segments by securing captive stainless steel supply through backward integration into Zhejiang sheet metal processing. Accelerate heat-pump recovery R&D to meet METI Top Runner benchmarks before regulatory tightening spreads to ASEAN markets. Defend against emerging smart-connected platform builders by embedding predictive diagnostics into standard equipment configurations. For New Entrants and Emerging Players: Build out direct manufacturer-to-contractor relationships in Vietnam's Da Nang and Nha Trang resort corridors where distributor capacity lags construction pipelines. Target Australia's WELS compliance-driven replacement cycle with certified high-efficiency systems. Penetrate through equipment-as-a-service arrangements bundling chemical supply and preventive maintenance into per-rack pricing for Seoul's multi-unit franchise operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributor networks possessing captive installation and field service capabilities across Southeast Asia. Long-term viability hinges on recurring revenue mix from service contracts decoupled from unit sales cyclicality. Monitor IoT penetration rates in Seoul and Taipei as inflection indicator for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Recovery Technology Deployment | METI Top Runner compliance in Japan normalizes thermal energy recapture systems for hospital central kitchens. |
| IoT-Enabled Predictive Maintenance Platform | Cloud-based subscription models in Seoul shift margin pools toward software-integrated service contracts. |
| Direct-to-Contractor Distribution Expansion | Da Nang and Nha Trang resort construction outpaces local distributor capacity for built-in installations. |
| WELS Certification Investment | Australia's water rating scheme extension creates compliance-driven replacement demand for high-efficiency systems. |
| Modular Heat Exchanger Retrofit Development | Guangdong suppliers extend existing equipment compliance windows without full replacement amid SAMR tightening. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SAMR regulatory filings, and hospitality construction pipeline databases. Primary interviews incorporated equipment procurement managers at hotel chains, central kitchen directors at institutional cafeterias, aftermarket service heads at regional distributors, and plant managers at Guangdong manufacturing facilities. Secondary validation drew from BIS certification records, METI efficiency program disclosures, and WELS water rating registrations. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Forecast inputs span product type segmentation by throughput capacity, technology tier by connectivity and sanitization mode, end-user category by procurement sophistication, and installation type by building age and electrical infrastructure. CAGRs derive from regression analysis against hospitality construction permits, labor cost indices, and regulatory compliance timelines. Industry-specific inputs incorporate SAMR GB standard implementation schedules and METI Top Runner efficiency benchmark trajectories across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by smart-connected platform builders or sudden stainless steel price spikes would shift outcomes. Quarterly review of BIS certification backlogs, Guangdong environmental compliance actions, and Vietnam resort construction permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Commercial Griddles and Flat Top Grills Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Food and Beverage Vending Machine Market