
 Global Glass Door Cooler Market | 2026-2036
Global Glass Door Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glass Door Cooler Market Analysis
A capital-intensity divergence between in-house compressor manufacturing and outsourced assembly is bifurcating competitive returns across the industry. True Manufacturing Co., Inc leverages captive metal fabrication and foaming operations to sustain margin stability in North American foodservice channels. Epta S.p.A. anchors its position through integrated refrigeration system design across European supermarket retrofit programs. Arneg S.p.A. competes on custom vertical cabinet configurations for premium retail concepts in Mediterranean markets.
A glass door cooler is a refrigerated display enclosure with transparent hinged or sliding panels, typically employing polyurethane-injected insulation between steel or aluminum frames, designed to maintain temperatures between 0°C and 10°C for visible merchandise storage. Vapor compression systems dominate installed bases due to proven efficiency at medium-scale capacities, while thermoelectric variants occupy niche countertop segments where noise and vibration constraints matter. Vertical configurations lead volume shipments across supermarket end users, whereas merchandising formats with LED-integrated framing capture expanding placement in cafes seeking impulse-purchase optimization. Custom sizing is accelerating as boutique retail chains specify dimensional constraints for constrained urban footprints.
EPA SNAP restrictions on high-GWP hydrofluorocarbons and the EU F-Gas Regulation are forcing refrigerant transitions toward propane and carbon dioxide architectures, directly impacting compressor sourcing and safety certification requirements. BIS energy efficiency labeling in India and GB standards compliance in China add parallel conformity burdens for exporters serving multiple assembly origins. Stakeholders must monitor refrigerant transition timelines against regional manufacturing relocation decisions.
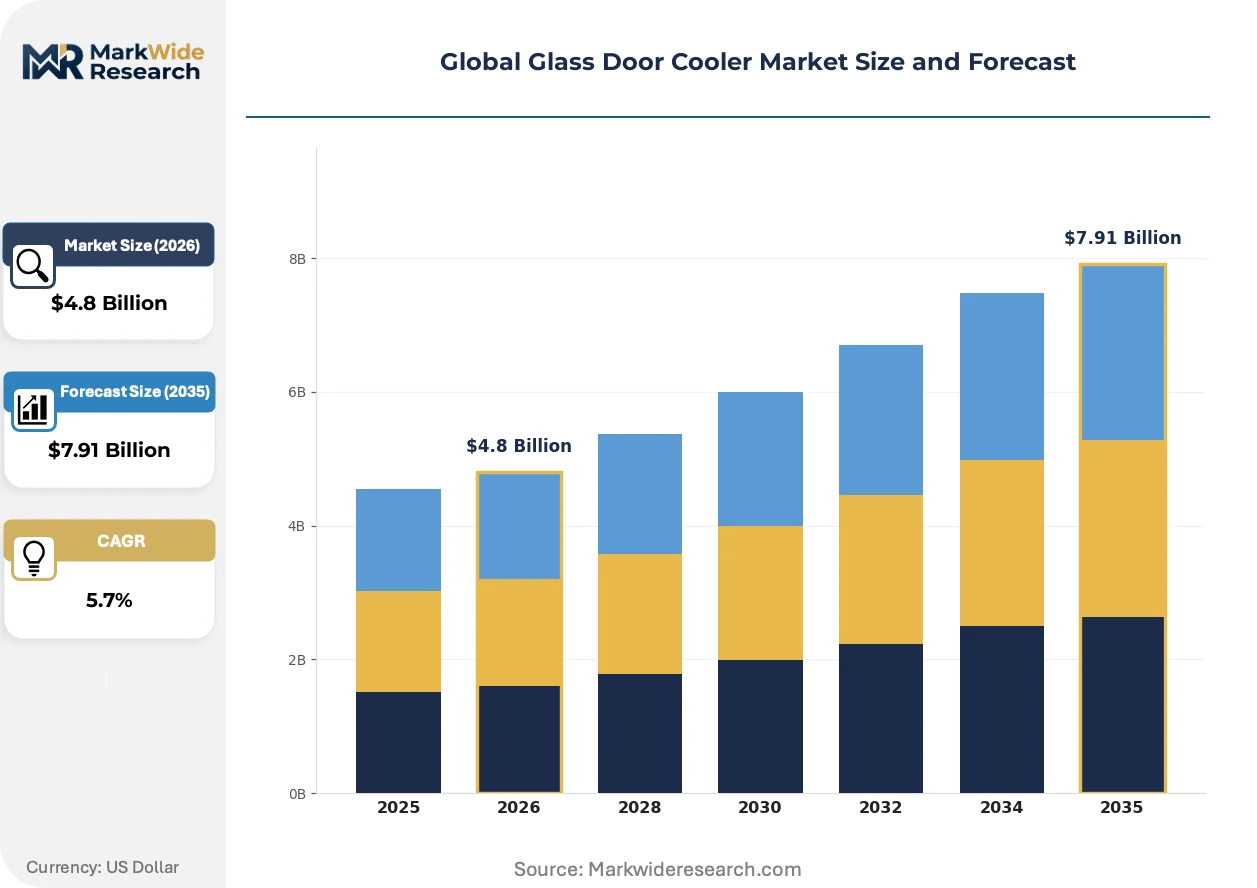
Market Dynamics
The EU F-Gas Regulation and EPA SNAP rules are forcing refrigerant transitions toward propane and carbon dioxide architectures, directly reshaping compressor sourcing, safety certification requirements, and equipment replacement cycles across the installed base.
Growth Catalysts
- Modern trade expansion:Convenience store chains in Vietnam and quick-service restaurants across Southeast Asia are deepening cold-chain display infrastructure investments. Urban format penetration drives unit demand.
- Natural refrigerant mandates:The EU F-Gas Regulation accelerates equipment replacement cycles as operators face phasedown schedules for high-GWP hydrofluorocarbons. Compliance deadlines compress procurement timelines.
- LED-integrated merchandising:Cafes and boutique retail formats specify transparent enclosures with embedded lighting systems for impulse-purchase optimization. Aesthetic differentiation commands placement priority.
Market Restraints
- Copper and steel input volatility:Polyurethane-injected insulation between metal frames faces raw material price swings. Margin pressure concentrates in outsourced assembly operations.
- Compressor supply concentration:Propane-compatible compressor sourcing narrows to qualified European and Japanese suppliers. Safety certification bottlenecks extend lead times.
- Thermoelectric efficiency ceiling:Peltier systems face fundamental COP limitations above 100-liter capacities. Vapor compression retains lock-in for medium-scale deployments.
Strategic Opportunities
- India BIS efficiency labeling:The Bureau of Indian Standards energy grade system creates first-mover positioning for compliant exporters. Modern trade format penetration lags organized retail saturation.
- Carbon dioxide system convergence:Transcritical CO2 architectures merge with vertical cabinet designs for premium supermarket retrofit programs. Integrated refrigeration system design separates technical leaders.
- Urban footprint constraints:Boutique retail chains in São Paulo and Mumbai specify custom dimensional constraints. Captive metal fabrication enables rapid prototyping for constrained floor plans.
Industry Challenges
- Refrigerant handling certification gaps:Propane system installation requires specialized technician training programs. Workforce pipeline lags equipment rollout schedules in emerging markets.
- Multi-jurisdiction compliance synchronization:Exporters face parallel conformity burdens from BIS labeling, GB standards, and EU safety directives. Testing timeline fragmentation extends product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glass Door Cooler Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Countertop, Merchandising End User: Retail, Restaurants, Cafes, Supermarkets Cooling Technology: Absorption, Vapor Compression, Thermoelectric, Magnetic Size: Small, Medium, Large, Custom |
| Companies Covered | AHT Cooling Systems GmbH, Beverage-Air, True Manufacturing Co., Inc, Blue Star Limited, Arneg S.p.A., Epta S.p.A., Dometic Group, Everest Refrigeration, Hussmann Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glass Door Cooler Market Emerging Trajectories
Refrigeration architecture is bifurcating between legacy vapor compression and emerging natural refrigerant systems, while display enclosure design converges with retail merchandising objectives and energy compliance frameworks.
Propane-based vapor compression is fragmenting competitive positioning in medium-capacity segments. European supermarket retrofit programs specify R290 compressors for their GWP advantages. True Manufacturing and Epta S.p.A. are capturing differentiated margin pools through in-house safety engineering and captive compressor integration.
REACH and RoHS substance restrictions are tightening material specifications for polyurethane foaming agents and frame coatings. Manufacturers face reformulation costs for insulation systems. Asian export-oriented assembly operations absorb disproportionate testing burden for dual-market certification.
Buyer specification patterns are compressing traditional equipment procurement cycles. Quick-service restaurant chains now bundle cooler placement with beverage supplier agreements. India and Brazil exhibit the most pronounced shift toward integrated equipment-service contracts that transfer maintenance liability to OEMs.
Global Glass Door Cooler Market Segmentation
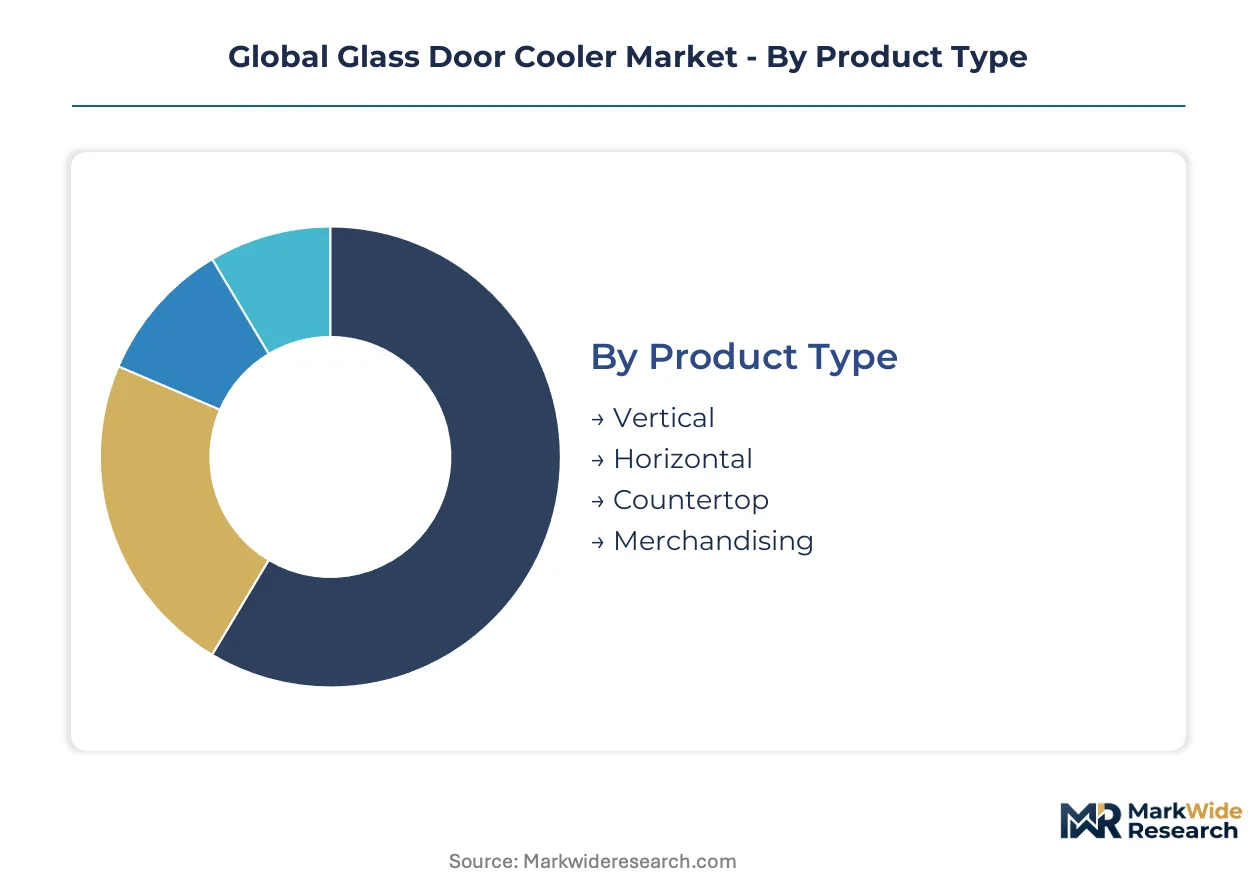
Glass door cooler segmentation reveals divergent engineering requirements across retail formats and regulatory jurisdictions. Product configuration, cooling architecture, and dimensional specifications each carry distinct compliance burdens and margin profiles that shape procurement patterns.
Product Type:
EU F-Gas Regulation refrigerant mandates favor cabinet designs with optimized internal volume-to-surface ratios that minimize charge requirements. EPA SNAP rules in the United States impose parallel constraints on hydrofluorocarbon-dependent configurations.
- Vertical:Tall cabinet configurations with polyurethane-injected steel frames dominate supermarket retrofit programs across Germany and France. Epta S.p.A. and Arneg S.p.A. anchor European volume through integrated refrigeration system design for R290-compatible vertical units.
- Merchandising:LED-integrated transparent enclosures with hinged or sliding glass panels capture expanding placement in Vietnam convenience stores and Brazilian quick-service restaurants. Aesthetic differentiation for impulse-purchase optimization drives specification priority in urban format expansion.
- Horizontal:Chest-style configurations with top-opening glass lids serve back-of-house storage in restaurant chains across India and Southeast Asia.
- Countertop:Compact thermoelectric variants occupy niche segments where noise and vibration constraints matter most.
Established volume favors vertical configurations in European retrofit cycles; emerging adoption favors merchandising formats in Southeast Asian convenience store expansion.
End User:
Procurement authority concentrates differently across buyer types, with beverage supplier agreements increasingly bundling equipment placement and maintenance liability.
- Supermarkets:Large-format operators in Germany and France specify transcritical CO2 architectures with custom vertical cabinet designs. Integrated equipment-service contracts transfer maintenance liability to OEMs, compressing traditional procurement cycles.
- Retail:Boutique chains in São Paulo and Mumbai specify custom dimensional constraints for constrained urban footprints. Captive metal fabrication capabilities enable rapid prototyping for floor plan limitations.
- Restaurants:Quick-service chains across Vietnam and Thailand bundle cooler placement with beverage supplier agreements.
- Cafes:Smaller-footprint operators prioritize LED-integrated merchandising formats for impulse-purchase optimization.
Supermarket retrofit programs in Europe absorb premium engineering investment; retail format penetration in Brazil and India climbs the fastest.
Cooling Technology:
Refrigerant transition timelines fragment competitive positioning between legacy vapor compression and emerging natural refrigerant architectures.
- Vapor Compression:Proven efficiency at medium-scale capacities dominates installed bases across North American foodservice channels. True Manufacturing Co., Inc sustains margin stability through captive compressor integration and in-house safety engineering for propane-compatible systems.
- Thermoelectric:Peltier systems face fundamental COP limitations above 100-liter capacities, restricting deployment to countertop segments in noise-sensitive environments.
- Absorption:Gas-fired configurations serve off-grid applications in rural India and Southeast Asian markets with unreliable electrical infrastructure.
- Magnetic:Emerging solid-state refrigeration approaches remain pre-commercial for glass door cooler deployments.
Vapor compression retains lock-in for medium-scale supermarket and restaurant deployments; thermoelectric gains share fastest in compact cafe and countertop segments.
Size:
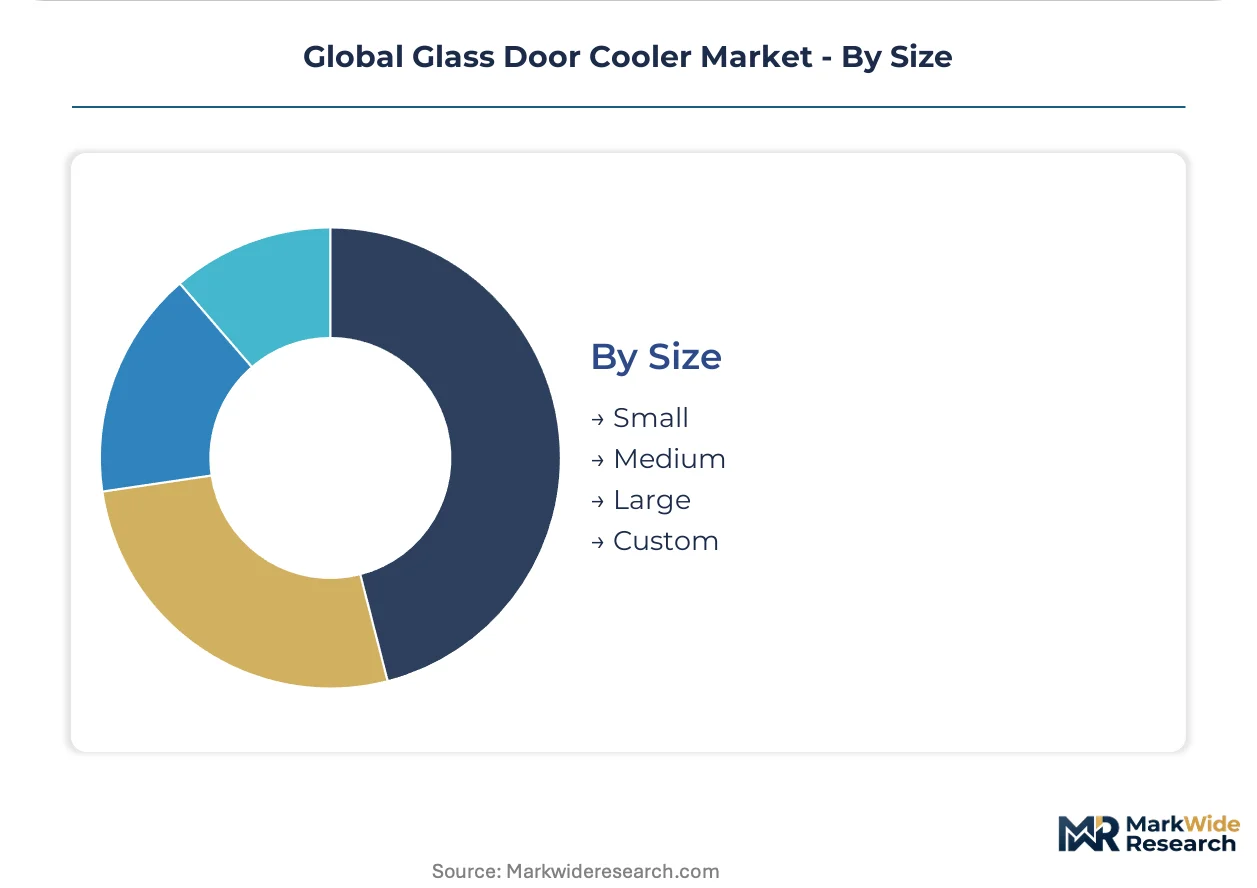
Dimensional specification patterns reflect urban real estate constraints and format-specific merchandise visibility requirements.
- Custom:Boutique retail chains in Mumbai and São Paulo specify dimensional constraints for constrained floor plans. Captive metal fabrication and foaming operations enable rapid prototyping without outsourced assembly delays.
- Large:Supermarket retrofit programs in Germany and France demand high-capacity vertical configurations with integrated transcritical CO2 systems.
- Medium:Standardized dimensions serve quick-service restaurant chains across Southeast Asia with predictable volume requirements.
- Small:Compact units address countertop and cafe placement where footprint minimization overrides capacity optimization.
Custom sizing accelerates in urban-constrained markets; large-format volume concentrates in European supermarket retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and France where supermarket retrofit cycles command premium engineering investment, while Vietnam and Brazil compete on volume absorption with compressed procurement timelines and bundled equipment-service contracts.
United States
Quick-service restaurant chains across the Southeast and Texas bundle cooler placement with beverage supplier agreements, transferring maintenance liability to OEMs. EPA SNAP rules compress procurement timelines for high-GWP hydrofluorocarbon phaseout. The Dallas-Fort Worth corridor anchors distribution infrastructure for national foodservice channel supply.
Germany
Supermarket operators in Bavaria and North Rhine-Westphalia specify transcritical CO2 architectures with integrated vertical cabinet designs. EU F-Gas Regulation mandates accelerate equipment replacement cycles with strict phasedown schedules. The Stuttgart industrial cluster concentrates safety engineering capabilities for propane-compatible compressor integration.
India
Modern trade format penetration in Maharashtra and Karnataka drives cold-chain display infrastructure investments from convenience store chains. BIS energy efficiency labeling creates first-mover positioning hurdles for compliant exporters. The Mumbai-Pune corridor anchors captive metal fabrication operations serving boutique retail dimensional constraints.
Brazil
Quick-service restaurant expansion in São Paulo and Rio de Janeiro absorbs merchandising formats with LED-integrated transparent enclosures. ANVISA compliance requirements parallel energy efficiency mandates for commercial refrigeration equipment. The São Paulo metropolitan area dominates custom sizing demand for constrained urban footprints.
Vietnam
Convenience store chains in Ho Chi Minh City and Hanoi deepen cold-chain display infrastructure investments amid urban format penetration. National energy efficiency standards for commercial refrigeration compress procurement timelines for imported equipment. The Red River Delta industrial zone concentrates assembly operations for Southeast Asian export markets.
Global Glass Door Cooler Market Vendor Landscape
Concentration sits with vertically integrated European specialists and North American foodservice fabricators who control captive compressor integration and in-house safety engineering. The vendor base splits between consolidated supermarket retrofit specialists and fragmented regional assemblers serving quick-service channels. Three archetypes dominate: integrated refrigeration system designers, custom metal fabrication specialists, and scale-driven outsourced assemblers. Competitive moves center on refrigerant transition certification acceleration and geographic expansion through equipment-service contract bundling.
Among European integrated specialists, Epta S.p.A. and Arneg S.p.A. exemplify the refrigeration system design archetype with anchored positions in supermarket retrofit programs. True Manufacturing Co., Inc. occupies a distinct tier among North American fabricators through captive metal fabrication and foaming operations. These three companies represent the divergence between in-house manufacturing control and outsourced assembly models bifurcating competitive returns across the industry.
| Leading Market Players |
|---|
| AHT Cooling Systems GmbH |
| Beverage-Air |
| True Manufacturing Co., Inc |
| Blue Star Limited |
| Arneg S.p.A. |
| Epta S.p.A. |
| Dometic Group |
| Everest Refrigeration |
| Hussmann Corporation |
| Others |
Supply Flow & Price Mechanics
Equipment-service contract bundling locks in multi-year procurement commitments for quick-service restaurant chains across Vietnam and Brazil, securing compressor allocation priority while capping price escalation exposure for OEMs facing copper and steel input volatility. This contractual architecture concentrates purchasing power with beverage supplier networks that specify R290-compatible cabinet configurations under parallel EU F-Gas and EPA SNAP compliance deadlines.
Pricing Analysis
The customization-premium spread separates boutique retail chains in Mumbai and São Paulo from standardized quick-service deployments across Southeast Asia. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation for BIS energy efficiency labeling and transcritical CO2 safety engineering. Cost compression in economy-tier outsourced assembly intensifies because polyurethane foam and steel frame inputs face commodity price swings. Quick-service restaurant chains exhibit highest price sensitivity; European supermarket retrofit programs demonstrate lowest sensitivity due to integrated equipment-service contract structures.
Supply Chain Analysis
Strategic stockpile preferences dominate compressor sourcing for propane-compatible systems, with qualified European and Japanese suppliers extending lead times amid safety certification bottlenecks. Manufacturing concentrates in Germany, Italy, and China, with the Stuttgart industrial cluster anchoring safety engineering capabilities and the Red River Delta zone serving Southeast Asian export markets. Component dependencies center on R290 compressors, polyurethane foaming agents, and LED-integrated glass panel assemblies. Single-source vulnerability concentrates in qualified propane compressor suppliers. Distribution runs through beverage supplier networks that bundle cooler placement with maintenance liability transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigeration architecture convergence around natural refrigerant ecosystems creates platform-economics inflection, where interoperability between transcritical CO2 systems and vertical cabinet designs determines competitive survival. Equipment-service contract bundling accelerates this shift by transferring maintenance liability to OEMs with captive compressor integration capabilities.
For Market Incumbents: Consolidate safety engineering capabilities for R290-compatible systems through captive compressor integration, mirroring True Manufacturing's North American foodservice model. Compress procurement timelines for European supermarket retrofit programs facing EU F-Gas phasedown deadlines. Capacity addition in the Stuttgart industrial cluster reinforces technical leadership against emerging Asian assemblers. For New Entrants and Emerging Players: Lead with BIS energy efficiency labeling compliance for India's modern trade format expansion, where organized retail penetration lags saturation. Target boutique retail chains in São Paulo and Mumbai specifying custom dimensional constraints for constrained urban footprints. Go-to-market through rapid prototyping partnerships with captive metal fabrication operations. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists controlling in-house safety engineering and captive compressor sourcing. Long-term viability across the projection horizon hinges on refrigerant transition certification acceleration and geographic expansion through equipment-service contract bundling. The signal to watch is propane-compatible compressor supply concentration extending lead times beyond equipment rollout schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Certification | EU F-Gas Regulation and EPA SNAP deadlines compress procurement timelines for compliant R290 systems. |
| Captive Compressor Integration | In-house safety engineering separates True Manufacturing and Epta S.p.A. from outsourced assemblers. |
| Equipment-Service Contract Bundling | Quick-service chains in Vietnam and Brazil transfer maintenance liability to OEMs with technical capabilities. |
| Custom Sizing Rapid Prototyping | Boutique retail chains in Mumbai and São Paulo specify dimensional constraints for urban footprint limits. |
| Transcritical CO2 Architecture Convergence | Premium supermarket retrofit programs in Germany and France demand integrated vertical cabinet designs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with supermarket procurement directors, quick-service restaurant chain facility managers, commercial refrigeration OEM engineering leads, and beverage supplier network operators. Secondary validation drew from EU F-Gas Regulation implementation timelines, EPA SNAP rule filings, BIS energy efficiency labeling databases, and GB standards compliance records. Bottom-up unit shipment estimates by product configuration and cooling technology were triangulated against top-down market value reconstruction across the analysis window.
Across the modeling period, projections were derived from segment-level volume build-ups across vertical, merchandising, horizontal, and countertop product types, intersecting with vapor compression, thermoelectric, absorption, and emerging magnetic cooling technologies. CAGRs were calculated from annualized growth rate progression through the projection horizon. Industry-specific forecast inputs incorporated refrigerant transition timelines against regional manufacturing relocation decisions and modern trade format penetration curves in India, Brazil, and Vietnam.
The analysis sits within stated boundaries; outcomes outside parallel EU F-Gas and EPA SNAP compliance synchronization or sustained copper and steel input volatility would require recalibration. Forecasts reflect documented assumptions regarding technician training pipeline development for propane system installation and multi-jurisdiction certification timeline fragmentation. Revision becomes warranted when safety certification bottlenecks for R290-compatible compressors extend lead times beyond equipment replacement cycle deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Food Trays and Bowls Market