
 Food Holding Equipment Market | 2026-2036
Food Holding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Holding Equipment Market Foresight
NSF International certification is unwinding competitive dynamics by filtering out suppliers lacking validated sanitation and performance credentials. Alto-Shaam, Inc. leverages its Halo Heat technology to dominate premium holding cabinet installations across North American hospital and hotel chains. Illinois Tool Works Inc. anchors its position through the Vulcan and Traulsen brands, sustaining manufacturing scale in refrigerated and heated holding systems. Hatco Corporation competes on countertop warming and display solutions, extending its reach through broad foodservice distributor partnerships.
Food holding equipment comprises thermally insulated enclosures, radiant heat sources, and humidity control systems engineered to maintain prepared food within FDA-specified temperature danger zones, typically 135°F to 165°F for hot holding applications. The primary commercial purpose is to bridge production and service timing gaps while preserving food safety, texture, and flavor in high-volume foodservice operations. Holding cabinets and food warmers command the largest installed base, though induction-based warming systems represent the fastest-growing technology segment as operators seek precise temperature control and reduced energy consumption. Steam tables retain stable demand from institutional cafeteria contracts, where durability and low capital cost outweigh efficiency premiums.
The U.S. Food and Drug Administration's Food Code provisions on time-temperature control, combined with NSF International equipment standards and Department of Energy efficiency regulations, collectively mandate certified construction and measurable thermal performance. These frameworks elevate replacement demand as non-compliant legacy equipment faces enforcement pressure during health inspections and utility rebate qualification. Stakeholders must monitor evolving state-level energy efficiency mandates and emerging electrification incentives that will reshape equipment specification criteria and vendor qualification requirements.
Market Dynamics
The Food Holding Equipment Market is undergoing structural reconfiguration as cloud kitchen proliferation and DOE efficiency mandates compress replacement cycles while elevating certified equipment specifications.
Growth Catalysts
- Cloud Kitchen Infrastructure Buildout:Ghost kitchen operators in Texas and California are scaling thermal holding cabinet deployments to synchronize multi-brand production workflows. These facilities require redundant holding capacity to manage order batching across virtual restaurant portfolios.
- FDA Food Code Enforcement:State health departments are tightening time-temperature control violations during inspections, forcing institutional cafeterias to retire non-compliant legacy warmers. NSF-certified equipment replacement is accelerating in hospital and correctional foodservice contracts.
- Electrification Incentives:Utility rebate programs targeting commercial kitchen equipment are lowering effective acquisition costs for induction-based holding systems. California's energy efficiency mandates are creating template effects for other state-level incentive structures.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 stainless steel price swings compress fabricator margins and complicate project bidding for large institutional installations. Domestic mill capacity constraints amplify lead time uncertainty for cabinet enclosures.
- Supply Concentration in Control Systems:Precision temperature controllers and humidity sensors concentrate among a narrow base of specialized electronics suppliers. Semiconductor component allocation priorities favor automotive and consumer electronics over commercial food equipment.
- Refrigerant Transition Friction:EPA SNAP program phase-downs of hydrofluorocarbon refrigerants in refrigerated holding cabinets create retrofit complexity. Service technician certification gaps slow compliant system deployment in existing installed bases.
Strategic Opportunities
- Underpenetrated Southeast Asian Cloud Kitchens:Singapore and Indonesia ghost kitchen operators lack standardized holding equipment specifications, creating first-mover positioning for NSF-certified system integrators. Local regulatory frameworks for virtual foodservice remain in formative stages.
- Induction-Convection Convergence:Hybrid warming systems combining electromagnetic heating with forced-air circulation enable precise moisture management for extended holding periods. Premium hotel banquet operations are piloting these configurations for service flexibility.
- IRA Commercial Equipment Deductions:Inflation Reduction Act provisions for energy-efficient commercial building equipment reduce after-tax costs for qualifying holding cabinet installations. Tax equity structuring expertise creates advisory service opportunities for equipment distributors.
Industry Challenges
- Controls Integration Complexity:IoT-enabled holding cabinets must interface with fragmented kitchen display system protocols and enterprise resource planning platforms. Custom API development extends deployment timelines for multi-site chain rollouts.
- NSF Certification Backlogs:Testing laboratory capacity constraints delay new product introductions, particularly for novel heating technologies lacking established evaluation protocols. Manufacturers face revenue recognition delays pending certification completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Holding Equipment Market |
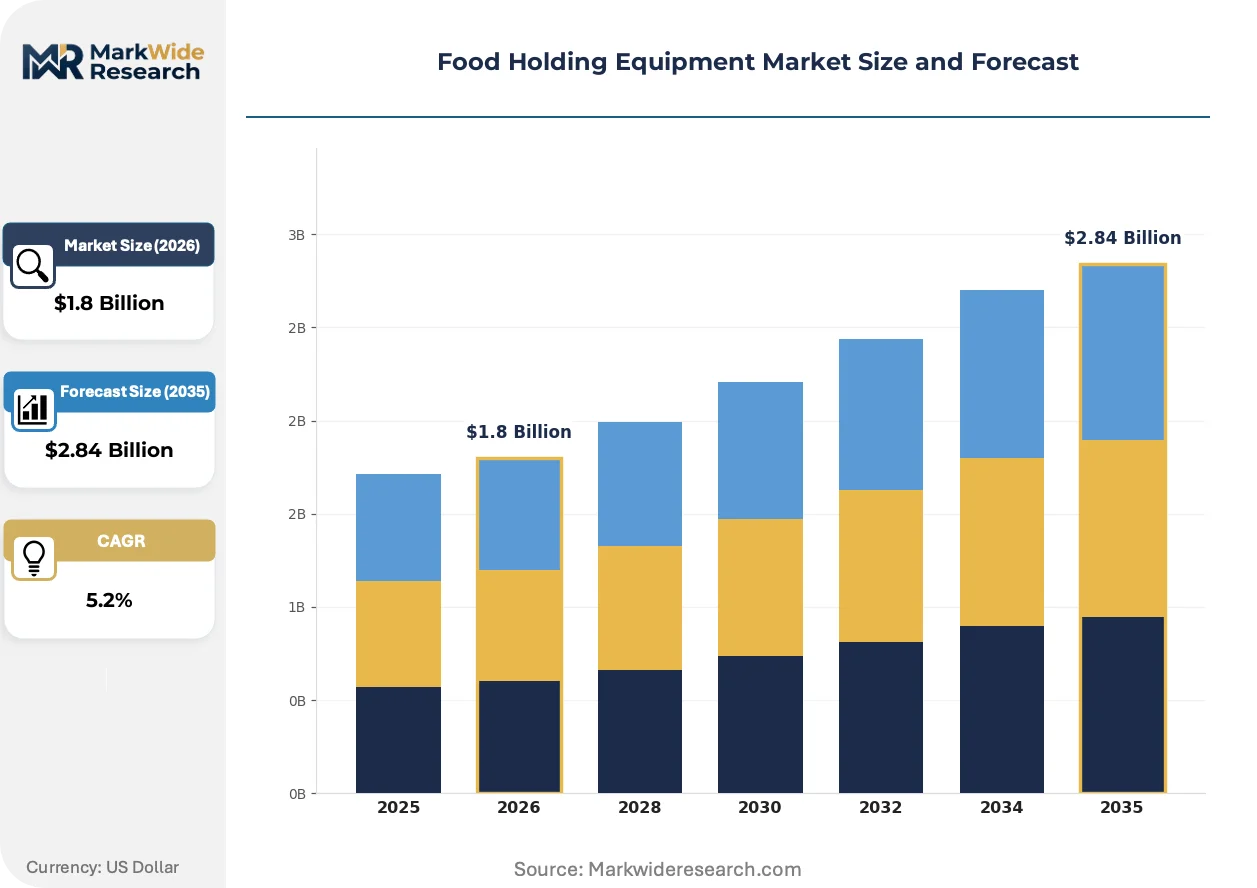
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.84 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Lamps, Food Warmers, Holding Cabinets, Steam Tables, Hot Boxes Technology: Electric, Gas, Infrared, Induction, Convection Application: Restaurants, Catering Services, Hotels, Cafeterias, Food Trucks End User: Quick Service Providers, Institutional Kitchens, Hospitality Chains, Event Management Companies |
| Companies Covered | Alto-Shaam, Inc., Welbilt Inc., Illinois Tool Works Inc., Hatco Corporation, Ali Group S.r.l., Duke Manufacturing, Winston Foodservice, Dover Corporation, The Middleby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Holding Equipment Market Shifts & Advancements
Active thermal management architectures and connected equipment ecosystems are redefining performance benchmarks while regulatory pressure on energy consumption accelerates technology substitution patterns.
Induction-based warming systems are fragmenting traditional convection and radiant heat market positions by delivering precise zone-level temperature control with measurable energy reduction. High-volume hospital cafeterias and corporate dining operations are adopting these systems fastest where utility cost accountability is strictest. The technology is fragmenting vendor competitive sets by rewarding electrical engineering capabilities over conventional metal fabrication scale.
EPA commercial kitchen equipment efficiency standards are mandating measurable thermal performance thresholds for heated holding cabinets and steam tables. These rules disqualify legacy equipment from utility rebate programs and accelerate replacement demand in institutional segments. School district foodservice directors in California and Texas are prioritizing compliant equipment to secure state-level efficiency funding.
Equipment-as-a-service contracting is displacing capital purchase models among multi-unit restaurant operators seeking to transfer obsolescence risk. Large franchise systems are bundling holding cabinet subscriptions with preventive maintenance and technology refresh guarantees. This model is concentrating most visibly in cloud kitchen portfolios where asset flexibility outweighs ownership preference.
Food Holding Equipment Market Segmentation
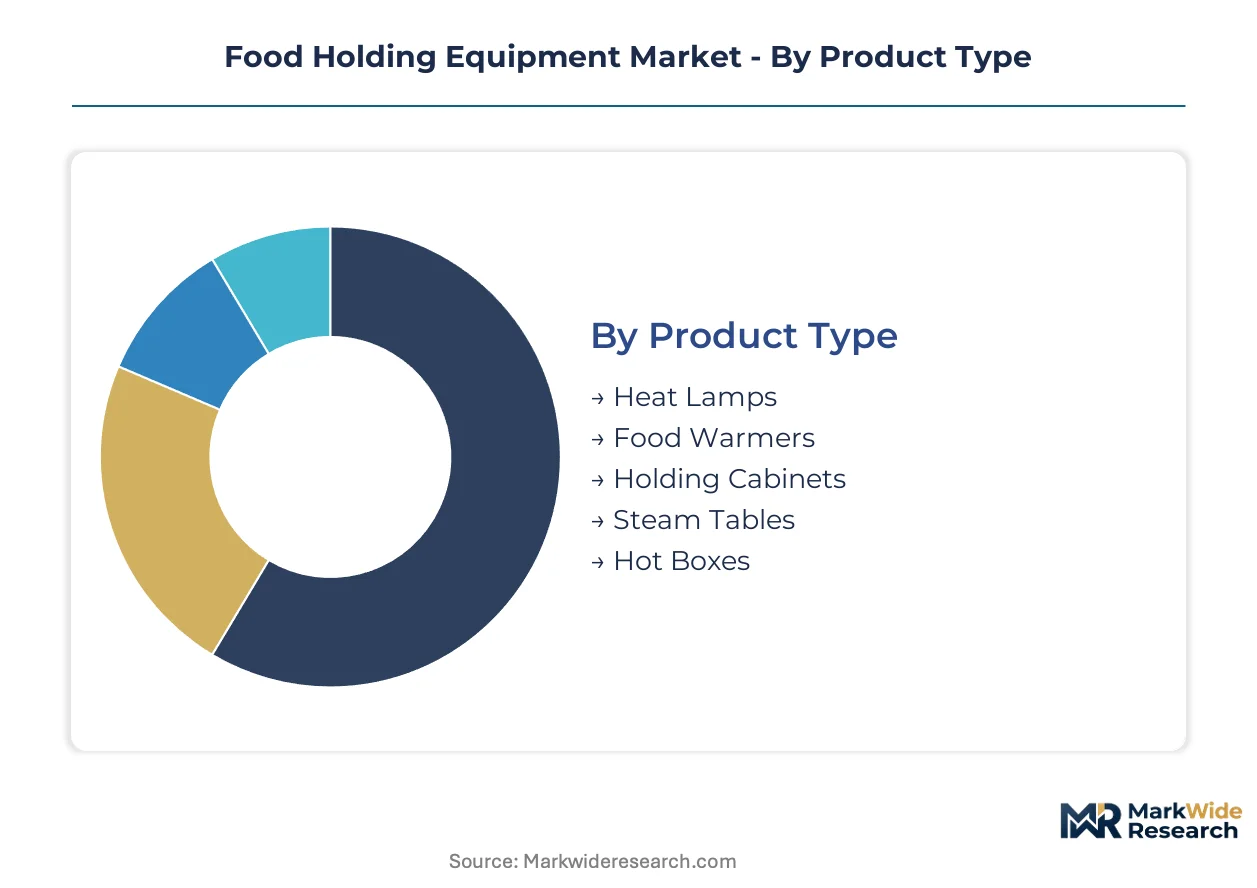
Equipment specification varies sharply across foodservice formats, with cloud kitchens demanding redundant holding capacity while institutional contracts prioritize NSF certification and durability metrics. Segmentation reveals how procurement patterns diverge between capital-purchase operators and subscription-model adopters.
Product Type:
Domestic demand concentrates in heated holding cabinets for hospital and hotel chains, while export orders favor compact food warmers for Southeast Asian cloud kitchen deployments.
- Holding Cabinets:Thermally insulated enclosures with humidity control systems maintain FDA-specified temperature zones between 135°F and 165°F. Texas and California healthcare systems are replacing legacy units to secure utility rebates and comply with tightened state energy mandates.
- Food Warmers:Countertop radiant and convection systems bridge production-to-service timing gaps in high-volume operations. Quick-service operators in California are scaling induction-based warming deployments to reduce electricity consumption and qualify for IRA commercial equipment deductions.
- Heat Lamps:Overhead infrared emitters for short-duration holding during plating and service.
- Steam Tables:Water-bath heated wells for buffet and cafeteria line service, favored where low capital cost outweighs efficiency premiums.
- Hot Boxes:Portable insulated carriers for off-site catering and mobile foodservice operations.
Holding cabinets command the largest installed base; induction-compatible food warmers are climbing the fastest as electrification incentives reshape specification criteria.
Technology:
Cost tier differentiation separates premium induction systems from standard electric and economy gas configurations, with rebate eligibility driving upgrade decisions.
- Induction:Electromagnetic field generation enables precise zone-level temperature control with measurable energy reduction. Hospital cafeterias in Texas are adopting these systems fastest where utility cost accountability is strictest.
- Electric:Resistance heating elements dominate mid-market installations through lower acquisition cost and simpler maintenance protocols.
- Infrared:Radiant heat transfer for rapid surface warming without convective air circulation.
- Convection:Forced-air circulation systems for uniform temperature distribution across cabinet cavities.
- Gas:Open-burner and pilot-light configurations retain share in regions with lower natural gas utility rates.
Electric technology retains volume leadership; induction is gaining share fastest as DOE efficiency standards disqualify legacy equipment from incentive programs.
Application:
Customer type segmentation shows cloud kitchen operators prioritizing flexible holding capacity while institutional buyers emphasize compliance documentation and service contracts.
- Restaurants:Full-service and limited-service operators deploy holding cabinets to synchronize kitchen production with variable dining room demand.
- Hotels:Banquet and room-service operations require extended-holding systems for event catering flexibility.
- Catering Services:Mobile and off-premise foodservice depends on portable hot boxes and transport-compatible warming equipment.
- Cafeterias:Institutional feeding operations specify steam tables and electric warmers for durability and low capital expenditure.
- Food Trucks:Compact footprint requirements favor countertop warmers and induction systems with generator-compatible power draws.
Restaurant applications generate the highest equipment throughput; hotel banquet operations are expanding most quickly as group dining rebounds.
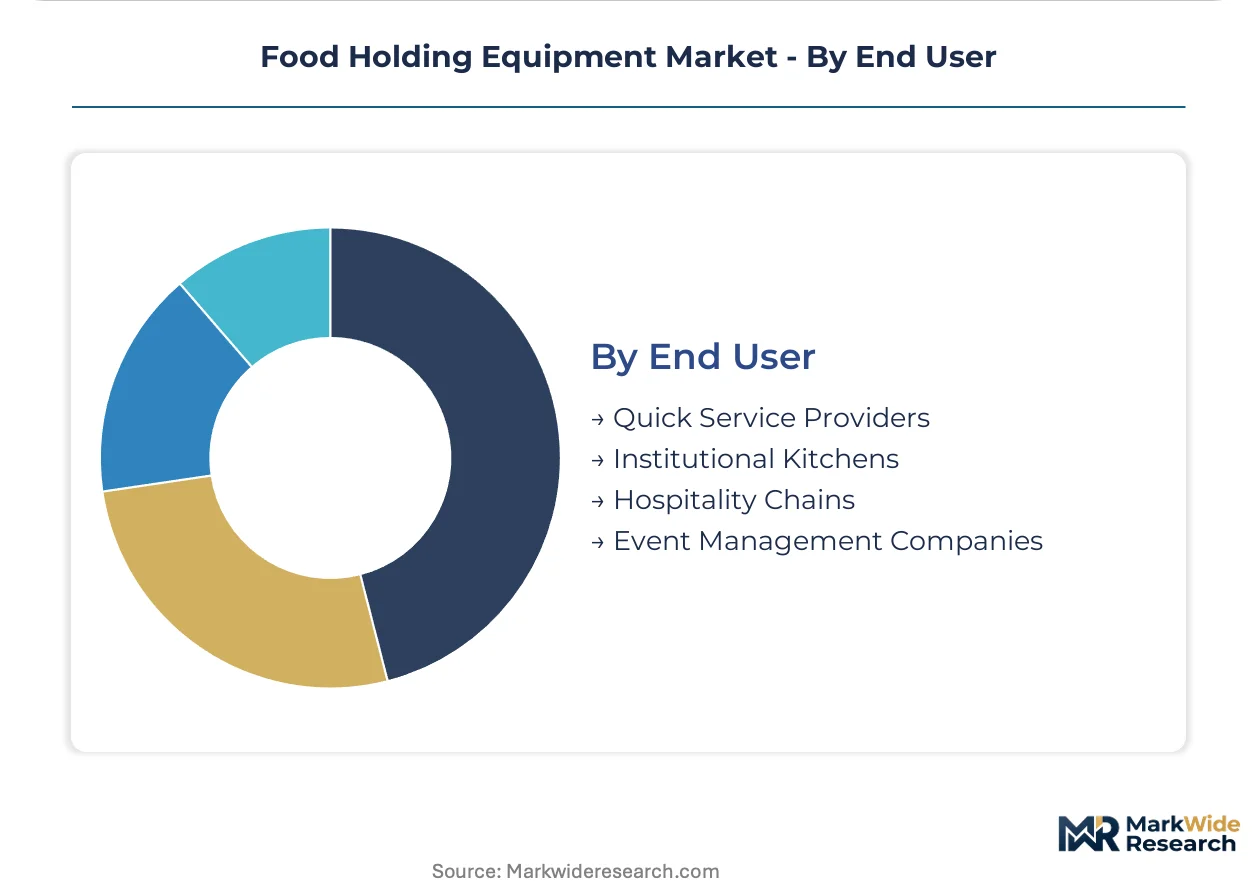
End User:
Maturity patterns distinguish established hospitality chains with predictable replacement cycles from emerging cloud kitchen operators making first-time capital commitments.
- Quick Service Providers:Drive-thru and fast-casual chains deploy redundant holding capacity to manage peak-hour throughput.
- Institutional Kitchens:Hospital, correctional, and school foodservice contracts mandate NSF-certified equipment with documented thermal performance.
- Hospitality Chains:Multi-property operators standardize on equipment-as-a-service contracts to transfer obsolescence risk.
- Event Management Companies:Temporary and seasonal foodservice operations favor rental and subscription-based equipment access.
Institutional kitchens represent the most stable demand base; hospitality chains are shifting fastest toward subscription procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility rebate programs and state-level energy efficiency mandates are accelerating equipment replacement cycles across major foodservice markets. Cloud kitchen infrastructure investment and institutional procurement standards are concentrating demand in specific metropolitan clusters.
United States
Texas and California healthcare systems are replacing legacy holding cabinets to secure state efficiency funding and comply with tightened DOE thermal performance standards. The FDA Food Code enforcement is pressuring institutional cafeterias toward NSF-certified equipment. Dallas and Houston hospital networks are deploying redundant holding capacity for multi-brand foodservice operations.
Germany
Commercial kitchen operators are adopting induction-based warming systems to meet EU Green Deal electrification targets and secure national efficiency incentives. The F-Gas Regulation is creating retrofit demand for refrigerated holding cabinets in institutional contracts. Bavarian hospital foodservice directors are standardizing on connected equipment platforms for thermal performance monitoring.
China
Cloud kitchen operators in Shanghai and Shenzhen are scaling thermal holding deployments to synchronize virtual restaurant production workflows. MIIT commercial equipment efficiency standards are elevating certified product specifications for domestic procurement. The Yangtze River Delta manufacturing base is expanding output for induction-compatible food warmers targeting Southeast Asian export markets.
Japan
Hotel banquet operations in Tokyo and Osaka are piloting hybrid warming configurations for extended-holding flexibility in group dining recovery. METI energy efficiency labeling programs are disqualifying legacy equipment from commercial rebate qualification. Kansai-region foodservice distributors are bundling equipment-as-a-service contracts with preventive maintenance guarantees.
Singapore
Ghost kitchen operators lack standardized holding equipment specifications, creating positioning opportunities for NSF-certified system integrators. The country's national food safety regulator is developing frameworks for virtual foodservice thermal control compliance. Jurong and Tampines industrial zones are attracting cloud kitchen infrastructure investment requiring redundant holding capacity.
Food Holding Equipment Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with foodservice equipment divisions alongside specialized thermal technology developers. Market structure shows moderate consolidation around brands with validated NSF credentials and established healthcare sector relationships. Two strategic archetypes dominate: diversified manufacturers leveraging cross-divisional scale and focused specialists competing on precision thermal control engineering. Competitive dynamics center on certification completion speed and strategic partnerships with cloud kitchen infrastructure developers.
Within the diversified conglomerate tier, Illinois Tool Works Inc. and Dover Corporation represent archetypes that anchor market positioning through multi-brand portfolio scale and cross-segment manufacturing integration. Among specialized thermal technology developers, Alto-Shaam, Inc. and Winston Foodservice exemplify players competing on proprietary heating architectures and premium-tier hospital and hotel chain relationships. These companies occupy positions where electrical engineering capabilities and certification documentation speed determine competitive outcomes.
| Leading Market Players |
|---|
| Alto-Shaam, Inc. |
| Welbilt Inc. |
| Illinois Tool Works Inc. |
| Hatco Corporation |
| Ali Group S.r.l. |
| Duke Manufacturing |
| Winston Foodservice |
| Dover Corporation |
| The Middleby Corporation |
| Others |
Supply & Pricing Matrix
NSF International certification gates supply qualification and price differentiation simultaneously, filtering out uncredentialed fabricators while commanding premiums for validated thermal performance documentation. Grade 304 and 316 stainless steel input costs cascade through fabrication quotes, compressing margins for non-specialized metalworkers and elevating procurement power for diversified conglomerates with captive supply arrangements.
Pricing Analysis
Certification level (NSF/FDA-grade) creates the primary spread between premium and standard equipment tiers, with three-tier pricing structure across premium, standard, and economy levels dominating transactional procurement. Brand premiums attach to documented hospital chain installations and utility rebate qualification history. Cost compression in economy electric warmers is intensifying because of raw material volatility and import competition from unbranded Asian fabricators. Institutional cafeterias exhibit highest price sensitivity due to capital budget constraints, while cloud kitchen operators prioritize flexible subscription terms over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-North America trade lanes complicate project scheduling for large institutional installations requiring coordinated multi-unit delivery. Manufacturing concentrates in China, the United States, and Italy, with Guangdong Province supplying induction component assemblies and Wisconsin anchoring heated cabinet fabrication for domestic healthcare contracts. Control systems draw from specialized electronics suppliers in Taiwan and South Korea, creating single-source vulnerability for precision temperature controllers. Distribution runs through broadline foodservice distributors and direct OEM sales teams to hospital procurement committees and cloud kitchen infrastructure developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with NSF certification timelines and healthcare sector relationships creating switching costs that protect incumbent positioning against price-based disruption.
For Market Incumbents: Secure certification backlog capacity by acquiring testing laboratory relationships or building in-house validation capabilities, insulating product launch timelines from external bottlenecks. Deepen backward integration into stainless steel enclosure fabrication to defend margin position against mill price volatility and import lead time uncertainty.
For New Entrants and Emerging Players: Equipment-as-a-service contract administration represents a service-layer gap where incumbents under-serve, particularly for multi-unit restaurant operators seeking to transfer obsolescence risk. Target Southeast Asian cloud kitchen operators in Singapore and Indonesia with NSF-certified system integration bundled with local maintenance partnerships, bypassing established distributor relationships in saturated North American markets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across induction-based warming systems as component costs decline and manufacturing scale economies emerge. Acquire specialized thermal technology developers with proprietary heating architectures and validated hospital chain relationships rather than diversified conglomerate foodservice divisions. Watch California utility rebate program expansion as the inflection indicator for electrification incentive template effects across other state-level jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Fast-Track Investment | Accelerates product launch timelines against testing laboratory capacity constraints. |
| Induction Component Backward Integration | Captures margin from electromagnetic heating systems displacing conventional radiant technology. |
| Cloud Kitchen Equipment-as-a-Service Launch | Transfers obsolescence risk while locking recurring revenue from virtual restaurant operators. |
| Southeast Asian Distribution Partnership | Establishes first-mover positioning in Singapore and Indonesia ghost kitchen infrastructure buildouts. |
| Utility Rebate Qualification Engineering | Secures DOE and state-level efficiency incentive eligibility for institutional contract bidding. |
Research Methodology
A standing panel of hospital foodservice directors, cloud kitchen operations managers, commercial equipment distributors, and NSF certification engineers provided ongoing calibration against market developments. Primary interviews with institutional procurement committees and ghost kitchen developers combined with secondary validation from FDA Food Code documentation, DOE efficiency standard filings, and utility rebate program disclosures. Bottom-up equipment shipment analysis and top-down foodservice capital expenditure estimates were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, technology, application, and end-user archetype, with additional dimensioning by certification tier and rebate eligibility status. CAGRs were derived from equipment replacement cycle compression rates and cloud kitchen infrastructure investment trajectories, incorporating electrification incentive adoption curves and stainless steel price elasticity assumptions.
Underlying assumptions cover regulatory enforcement intensity, utility incentive program continuity, and semiconductor component allocation priorities, with deviation risk concentrated in EPA refrigerant phase-down timelines and state-level energy mandate adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
Food Display Cabinet Market