
 Ice Maker Market | 2026-2036
Ice Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Maker Market Analysis
The capability gap between capital-heavy refrigeration specialists and smaller assembly operations is collapsing as modular manufacturing and shared component platforms lower entry barriers. Hoshizaki leverages vertical integration in compressor technology to sustain margin control across premium segments. Manitowoc anchors North American distribution through dedicated foodservice channels. Scotsman competes on specialized flake-ice systems for healthcare and seafood display applications.
An ice maker is a electromechanical refrigeration appliance that produces frozen water cubes, flakes, or nuggets through vapor-compression or thermoelectric cooling cycles, typically operating between 10°F and 32°F evaporator temperatures to achieve controlled ice formation for commercial or institutional use. Modular units dominate institutional kitchens where scalable daily output exceeds 500 pounds, while countertop configurations capture fastest growth in limited-service restaurants and compact bars. Smart technology integration is concentrating margin pools in connected diagnostics and predictive maintenance subscriptions rather than hardware alone.
The US Department of Energy appliance efficiency standards, EPA SNAP refrigerant phase-down rules, and EU F-Gas Regulation collectively reshape compressor specifications and refrigerant selections across major supply corridors. FDA food-contact surface requirements and NSF/ANSI sanitation certifications determine product eligibility for healthcare and foodservice procurement channels. Stakeholders must monitor refrigerant transition timelines and energy label tightening to avoid stranded inventory or locked-out market access.
Market Dynamics
The US Department of Energy's escalating efficiency mandates are compressing refrigerant choices and evaporator designs, forcing manufacturers to abandon water-cooled architectures and accelerate air-cooled system development across all commercial segments.
Growth Catalysts
- EPA SNAP refrigerant phase-down:The program accelerates hydrofluorocarbon transition toward hydrofluoro-olefin blends, creating replacement demand across installed bases in foodservice and healthcare facilities.
- Healthcare infrastructure expansion:Hospital construction in China and India drives flake-ice procurement for therapeutic cooling and laboratory applications at scale previously concentrated in North America and Western Europe.
- Smart diagnostics integration:IoT-enabled predictive maintenance modules transform capital equipment into recurring revenue streams, deepening manufacturer-customer relationships beyond hardware transactions.
Market Restraints
- Copper and aluminum price volatility:Evaporator coil materials face commodity market swings that compress assembly margins and destabilize quoted project pricing for institutional buyers.
- Compressor supply concentration:Production of variable-speed refrigeration compressors clusters among German and Japanese suppliers, exposing ice maker assemblers to allocation risk during demand surges.
- Thermoelectric cooling limitations:Peltier systems remain confined to sub-50-pound daily output due to energy efficiency constraints, capping addressable market share in commercial applications.
Strategic Opportunities
- India hospitality buildout:Mid-tier hotel chains in secondary cities lack reliable ice supply infrastructure, opening territory for compact modular units with localized service networks.
- EU F-Gas Regulation tightening:The 2027 refrigerant quota reduction creates forced-upgrade cycles for equipment purchased during the 2010-2015 installation wave.
- Direct-to-operator e-commerce:Parts distribution and smaller-capacity units bypass traditional foodservice equipment dealers through specialized B2B platforms serving independent restaurants.
Industry Challenges
- Refrigerant technician certification gaps:The transition to mildly flammable A2L refrigerants requires reskilling service networks that remain trained primarily on legacy R-404A and R-134a systems.
- NSF/ANSI 12 sanitation compliance timelines:Certification testing for new evaporator geometries extends product launch schedules by four to six months, delaying revenue recognition against competitor arrivals.
- Legacy control system integration:Smart-connected ice makers must interface with building management protocols spanning BACnet, Modbus, and proprietary formats without universal translation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Maker Market |
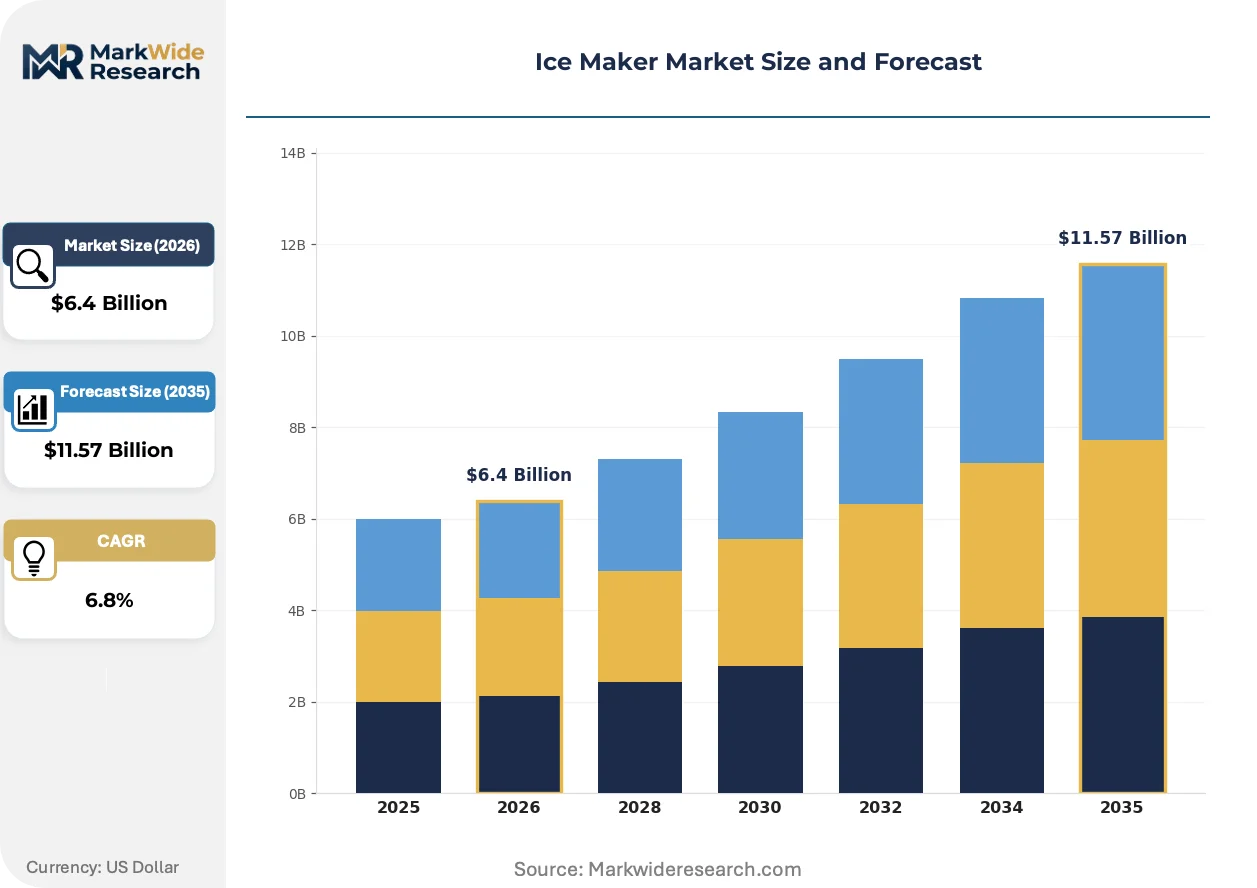
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Countertop, Under-counter, Flake End User: Restaurants, Bars, Hotels, Healthcare Technology: Air-cooled, Water-cooled, Ice Storage, Smart Sales Channel: Direct Sales, Distributors, Online Retail, Retail Stores |
| Companies Covered | Ice-O-Matic, Follett, Hoshizaki, Cornelius, Electrolux, Manitowoc, Brema Ice Makers, Kold-Draft, Scotsman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Maker Market Emerging Trajectories
Refrigeration architectures are diverging as efficiency mandates and connectivity requirements rewrite equipment specifications. Manufacturers now compete on energy performance metrics and data services rather than ice output alone.
Nugget ice production technology is fragmenting the premium segment through specialized extrusion and compression mechanisms that produce softer, more absorbent ice forms. Quick-service restaurants and healthcare cafeterias adopt these systems to differentiate beverage programs and patient hydration offerings. The technology is fragmenting traditional cube-ice dominance in segments previously resistant to format switching.
The EU F-Gas Regulation's phasedown schedule forces refrigerant portfolio consolidation across European manufacturing footprints. Equipment makers must qualify multiple compressor oils and expansion valve calibrations for low-global-warming-potential alternatives. Commercial kitchen operators in Germany and France face accelerated replacement timelines as service refrigerant costs exceed equipment depreciation thresholds.
Consolidated procurement by multi-unit restaurant chains compresses vendor lists and demands standardized specifications across national footprints. Independent equipment lessors and dealer networks lose volume to direct manufacturer relationships with corporate facilities teams. This concentration is most visible in the United States, where top-50 restaurant groups account for disproportionate ice maker specification authority.
Ice Maker Market Segmentation
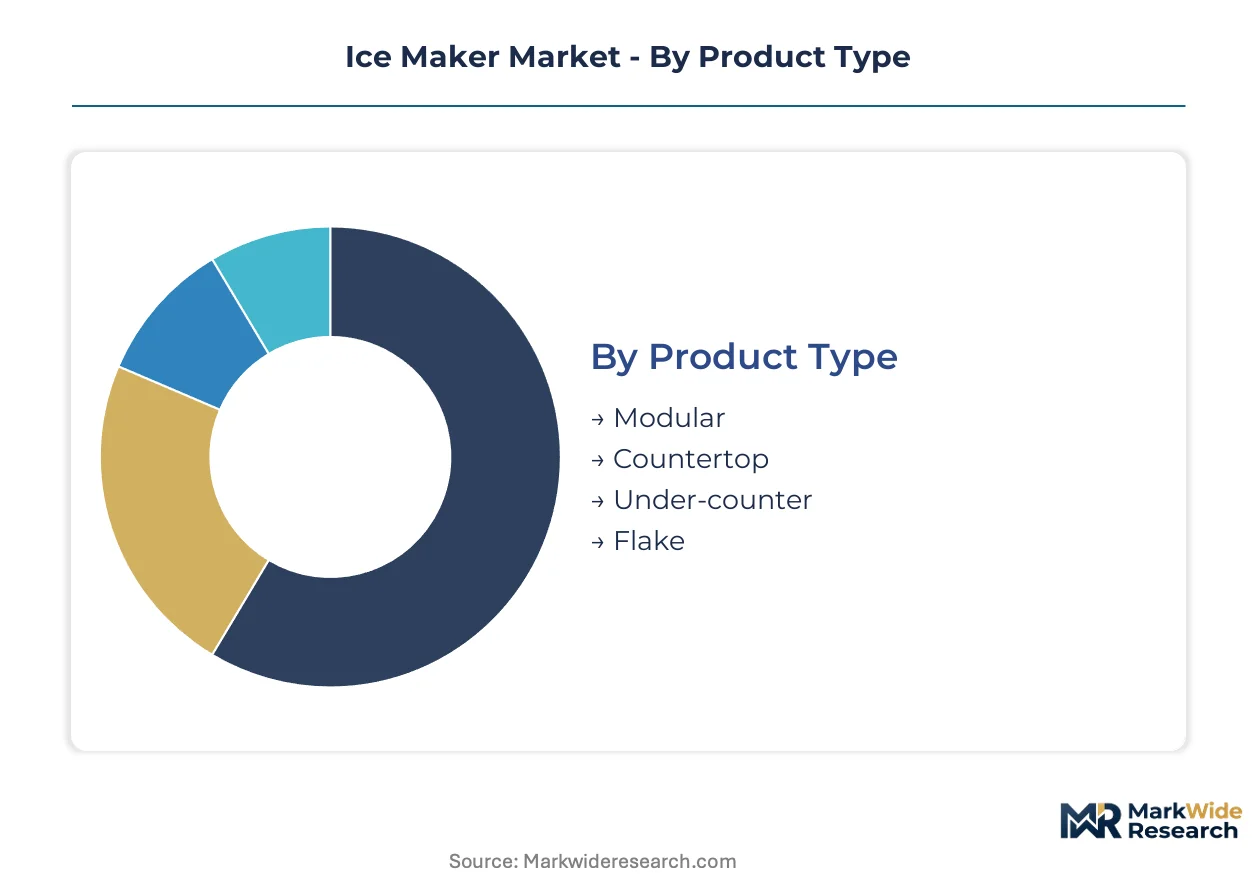
Ice maker procurement patterns diverge sharply across installation constraints, cooling architectures, and buyer sophistication. Segmentation reveals where margin pools concentrate versus where volume commoditization pressures assembly economics.
Product Type:
Modular units ship predominantly to domestic foodservice infrastructure projects, while flake and countertop configurations serve export-led healthcare and hospitality demand across emerging markets.
- Modular:These scalable units mount on separate storage bins to deliver outputs exceeding 500 pounds daily through remote condensing or self-contained refrigeration circuits. Demand clusters in institutional kitchens across the United States, where school districts and hospital cafeterias prioritize field-serviceable component access over compact footprints.
- Countertop:Self-contained units with integrated storage occupy under 24 inches of vertical space, making them deployable in limited-service restaurants and compact bars where floor space commands premium lease rates. Growth concentrates in India's secondary-city hospitality buildout, where mid-tier hotel chains lack reliable ice supply infrastructure.
- Under-counter:Front-breathing designs slip beneath existing countertops without side clearance requirements, serving small-footprint bars in Japan and South Korea where real estate efficiency dictates equipment selection.
- Flake:Extruded ice forms at sub-20°F temperatures produce malleable, rapid-cooling fragments for therapeutic applications and seafood display. Healthcare infrastructure expansion in China and India drives procurement at scale previously concentrated in North America and Western Europe.
Modular configurations command the established base across institutional foodservice. The steepest expansion runs through flake systems serving therapeutic cooling and laboratory applications.
End User:
Cost tier stratification separates specification authority: enterprise chains demand standardized national footprints while independent operators prioritize localized service responsiveness over capital efficiency.
- Restaurants:Full-service and quick-service operators specify ice makers by beverage program requirements, with nugget ice systems gaining share in burger and chicken chains seeking beverage differentiation. Consolidated procurement by multi-unit chains compresses vendor lists and demands standardized specifications across national footprints.
- Bars:Cocktail-focused establishments prioritize cube clarity and density for controlled dilution rates, driving specification toward premium evaporator geometries with extended freeze cycles.
- Hotels:Guest amenity requirements and back-of-house banquet capacity create dual-procurement patterns, with properties often specifying separate units for pool bars versus kitchen operations. Hotels and resorts are expanding ice maker procurement for guest amenities.
- Healthcare:FDA food-contact surface requirements and NSF/ANSI sanitation certifications determine product eligibility for hospital procurement channels, with flake ice dominating therapeutic cooling and laboratory preservation applications.
Restaurant chains concentrate volume purchasing power. Healthcare facilities generate the fastest margin expansion through specialized sanitation compliance and service contract attachment.
Technology:
Application maturity separates legacy architectures from connected systems: air-cooled dominance reflects regulatory enforcement, while smart modules transform capital equipment into recurring revenue streams.
- Air-cooled:Condensing units reject heat through forced-air exchange, eliminating water consumption and drainage infrastructure requirements. The US Department of Energy enforces efficiency standards that push manufacturers toward air-cooled development across all commercial segments.
- Water-cooled:Once-favored for high-ambient installations, these systems face accelerated phase-out as efficiency mandates compress refrigerant choices and evaporator designs, forcing abandonment of water-cooled architectures.
- Ice Storage:Remote bin configurations decouple production capacity from immediate consumption patterns, enabling demand buffering in venues with extreme peak loads such as stadium concessions and event catering.
- Smart:IoT-enabled predictive maintenance modules interface with building management protocols, deepening manufacturer-customer relationships beyond hardware transactions through subscription diagnostics and automated parts replenishment.
Air-cooled systems anchor installed capacity. Smart technology integration climbs fastest as operators seek operational visibility and reduced service dispatch frequency.
Sales Channel:
Customer type determines channel preference: enterprise accounts demand direct manufacturer relationships while fragmented independents rely on dealer networks for specification guidance and localized service.
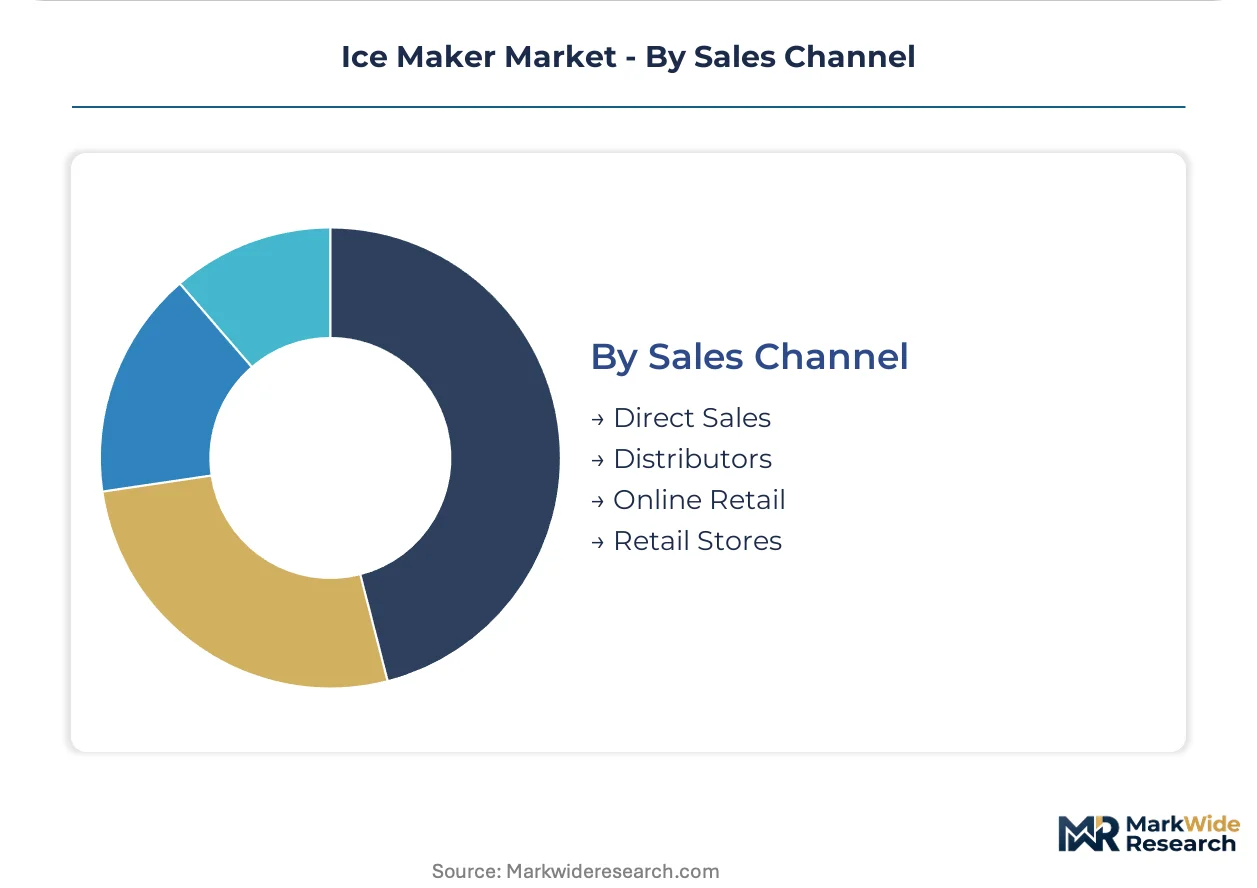
- Direct Sales:National account teams serve multi-unit restaurant chains and hospitality groups with standardized specifications, volume pricing, and dedicated facilities support. Independent equipment lessors and dealer networks lose volume to direct manufacturer relationships with corporate facilities teams.
- Distributors:Regional foodservice equipment dealers provide specification consulting, installation coordination, and aftermarket parts availability for independent restaurants lacking in-house engineering resources.
- Online Retail:Specialized B2B platforms serving independent restaurants enable parts distribution and smaller-capacity units to bypass traditional dealer networks, with direct-to-operator e-commerce gaining traction for replacement cycles.
- Retail Stores:Big-box and specialty appliance retailers capture residential and light-commercial demand, though commercial-grade specifications rarely route through consumer-facing channels.
Distributor networks command the established base through specification influence and service attachment. Online retail channels expand most quickly as independent operators seek price transparency and reduced procurement friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as efficiency mandates and sanitation compliance dominate procurement criteria, while operators in India and Southeast Asia remain acutely sensitive to capital outlay and localized service costs. This demand-elasticity contrast shapes regional vendor strategies and product positioning across major markets.
United States
Full-service restaurant chains and hospital cafeterias drive specification volume for modular air-cooled systems. The US Department of Energy enforces escalating efficiency standards that compress refrigerant choices and accelerate abandonment of water-cooled architectures. Equipment procurement concentrates in Texas and California, where foodservice infrastructure expansion and stringent state-level energy codes create dual compliance pressures.
Germany
Commercial kitchen operators face accelerated replacement timelines as EU F-Gas Regulation quotas drive service refrigerant costs above equipment depreciation thresholds. The 2027 refrigerant quota reduction creates forced-upgrade cycles for equipment purchased during the 2010-2015 installation wave. Manufacturing and specification authority clusters in Bavaria and North Rhine-Westphalia, where industrial food processing and hospitality supply chains intersect.
China
Hospital construction and healthcare infrastructure scaling generate flake-ice procurement at volumes previously concentrated in North America and Western Europe. NMPA and GB standards govern food-contact surface requirements and equipment safety certifications. Demand concentrates in the Yangtze River Delta and Pearl River Delta, where rapid hospitality buildout and biomedical laboratory expansion outpace domestic manufacturing capacity for premium sanitation-compliant units.
India
Mid-tier hotel chains in secondary cities lack reliable ice supply infrastructure, opening territory for compact modular units with localized service networks. BIS certification and FSSAI food safety requirements determine product eligibility for hospitality and healthcare procurement channels. Karnataka and Maharashtra host the fastest installation growth, where Bangalore and Mumbai hospitality clusters drive specification for countertop and under-counter configurations.
Japan
Front-breathing under-counter designs capture preference in Tokyo and Osaka, where real estate efficiency dictates equipment selection in compact bars and limited-service restaurants. METI energy efficiency standards and JIS certification requirements shape product development timelines. The Kanto and Kansai regions concentrate demand, where high-density urban foodservice operations prioritize footprint minimization and noise reduction over absolute output capacity.
Ice Maker Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the ice maker market, with consolidation pressures intensifying as smart technology and refrigerant transitions raise R&D barriers. The upper tier commands specification authority through captive compressor technology and national account relationships, while mid-scale assemblers compete on regional service responsiveness and specialized ice formats. Two strategic archetypes dominate: vertically integrated refrigeration specialists leveraging backward integration into compressor production, and modular fabricators optimizing shared component platforms for cost-positioned segments. Competitive moves center on smart diagnostics integration for recurring revenue attachment and refrigerant portfolio consolidation ahead of regulatory phase-down deadlines.
Among integrated refrigeration specialists, Hoshizaki and Manitowoc occupy positions exemplifying divergent geographic anchoring and channel strategies. Hoshizaki represents the Asia-Pacific-originated archetype with in-house compressor capabilities sustaining margin control across premium segments. Manitowoc anchors North American distribution through dedicated foodservice channels, illustrating the regional-leader model. Scotsman sits within the specialization tier, competing on flake-ice system expertise for healthcare and seafood display applications where format-specific engineering creates defensible positioning against generalist competitors.
| Leading Market Players |
|---|
| Ice-O-Matic |
| Follett |
| Hoshizaki |
| Cornelius |
| Electrolux |
| Manitowoc |
| Brema Ice Makers |
| Kold-Draft |
| Scotsman |
| Others |
Supply Flow & Price Mechanics
Compressor production scale in Japan and Germany anchors cost structures across premium ice maker tiers, concentrating supply-side leverage among refrigeration specialists while forcing smaller assemblers into price-competitive standard segments. This scale asymmetry elevates aftermarket service contracts as the primary margin reservoir, with predictive maintenance subscriptions commanding pricing power that hardware transactions cannot replicate.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions drive lifetime value differentiation across manufacturer portfolios. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and connected-feature bundling, with NSF/ANSI 12 compliance commanding substantial premiums in healthcare procurement channels. Cost compression in economy tiers intensifies because copper and aluminum commodity volatility destabilizes quoted project pricing for institutional buyers. Independent restaurants demonstrate acute price sensitivity, while hospital cafeterias and multi-unit chains prioritize sanitation compliance and national service networks over capital outlay minimization.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes fluctuate with container availability and port congestion at Shanghai and Shenzhen, compressing assembly margins for manufacturers dependent on imported compressor components. Variable-speed refrigeration compressor production concentrates in Germany and Japan, while evaporator coil fabrication draws from Chinese and Mexican metalworking centers. Single-source vulnerability in compressor allocation exposes ice maker assemblers to production disruption during demand surges. Distribution runs through dedicated foodservice equipment dealers for specification influence, with direct-to-operator e-commerce gaining share in replacement parts and smaller-capacity units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ice maker procurement is recovering from cyclical compression in hospitality construction, with hotel buildout in India and Southeast Asia providing the demand inflection. Equipment replacement cycles tied to refrigerant phase-down mandates reinforce replacement revenue visibility.
For Market Incumbents: Shield installed-base relationships through captive compressor technology and predictive maintenance subscription attachment. Consolidate refrigerant portfolio qualification ahead of EPA SNAP and EU F-Gas Regulation deadlines to prevent stranded inventory exposure. Deepen backward integration into compressor production to defend margin control against emerging modular assemblers.
For New Entrants and Emerging Players: Lead with compact countertop configurations targeting India's secondary-city hospitality buildout, where mid-tier hotel chains lack reliable ice supply infrastructure. Capture share in flake-ice systems for therapeutic cooling applications as healthcare infrastructure scales in China and India. Deploy direct-to-operator e-commerce platforms to bypass entrenched dealer networks and establish localized service partnerships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with IoT-enabled predictive maintenance modules and national account relationships with multi-unit restaurant chains. Five-to-ten-year viability favors specialists with refrigerant transition readiness and healthcare sanitation certification depth. Monitor EPA SNAP refrigerant phase-down enforcement velocity as the primary inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Diagnostics Integration | Transforms capital equipment into subscription revenue streams through IoT-enabled predictive maintenance modules. |
| Refrigerant Portfolio Consolidation | Qualifies compressor oils and expansion valves for low-global-warming-potential alternatives ahead of EPA and EU deadlines. |
| Healthcare Certification Investment | Secures NSF/ANSI 12 and FDA food-contact surface eligibility for hospital and laboratory procurement channels. |
| Direct-to-Operator E-Commerce | Bypasses traditional foodservice equipment dealers through specialized B2B platforms serving independent restaurants. |
| Localized Service Network Buildout | Establishes maintenance infrastructure in India's secondary cities to support mid-tier hospitality expansion. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs data, and equipment procurement databases. Interviews with foodservice equipment dealers, hospital facilities managers, restaurant chain procurement directors, and refrigeration compressor manufacturers informed demand-side and supply-side assessments. Secondary validation drew from EPA SNAP program documentation, EU F-Gas Regulation implementation reports, FDA food-contact surface requirements, and NSF/ANSI certification records. Bottom-up installation tracking across hospitality and healthcare infrastructure projects triangulates against top-down manufacturer shipment data.
Segmentation dimensions modeled include product type, cooling architecture, end-user vertical, technology tier, and sales channel across the projection horizon. Annual growth rates derive from equipment replacement cycle analysis, regulatory mandate timing, and hospitality construction pipeline assessment. Forecast inputs incorporate refrigerant transition timelines, copper and aluminum price trajectory assumptions, and smart technology adoption curves in commercial foodservice.
Forecasts assume regulatory continuity in EPA SNAP, EU F-Gas, and FDA enforcement regimes; material policy shifts would require re-modeling of replacement demand timing and certification compliance costs. Commodity price volatility and compressor supply allocation constraints represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Global Commercial Cooking Equipment Market