
 Food and Beverage Vending Machine Market | 2026-2036
Food and Beverage Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverage Vending Machine Market Analysis
Aluminum is expanding its share in vending machine chassis as manufacturers seek lighter, corrosion-resistant alternatives to legacy steel frames. Sanden Holdings leverages its refrigeration expertise to anchor premium cold-chain vending lines across East Asian corridors. Azkoyen Group competes on payment-system integration, sustaining R&D intensity in biometric and mobile-wallet interfaces. Fuji Electric dominates high-efficiency compressor modules, extending its position into refrigerated units for tropical climates.
Food and beverage vending machines are self-service automated retail systems designed to store, dispense, and in refrigerated variants preserve perishable goods through thermoelectric or compressor-based cooling, with capacities ranging from 200 to 800 SKUs and operating temperatures between 2°C and 8°C for fresh categories. These systems serve commercial and institutional environments where labor minimization, 24-hour availability, and controlled portion dispensing are operational priorities. Beverage vending machines lead installed base value due to higher throughput frequency and established cold-chain infrastructure, while healthy food vending machines represent the fastest-expanding segment as employers and universities replace legacy snack portfolios with refrigerated fresh and protein-focused offerings. Cashless payment systems now underpin replacement demand across mature markets, with IoT-enabled machines capturing margin pools through remote diagnostics and dynamic pricing capabilities that reduce service intervals and stockout rates.
The FDA governs food safety standards for machines distributing temperature-sensitive products in the United States, while the EU Green Deal and F-Gas Regulation mandate refrigerant transitions that reshape compressor specifications for European deployments. Japan's METI enforces energy-efficiency benchmarks that push manufacturers toward inverter-driven cooling and LED lighting retrofits. Stakeholders must monitor refrigerant-phaseout timelines against cashless-migration capex cycles to sequence capital deployment across regulatory jurisdictions with divergent compliance calendars.
Market Dynamics
Cashless payment mandates from the EU AI Act and parallel financial regulations are forcing machine retrofit cycles, compressing replacement timelines and reshaping competitive positioning toward payment-system integrators.
Growth Catalysts
- EU AI Act cashless mandates:European financial regulators require contactless payment compatibility, accelerating hardware replacement across legacy installed bases in Germany, France, and Italy.
- Corporate workplace automation:Rising labor costs in Japan and the United States drive employers to expand automated foodservice footprints in office campuses and logistics hubs.
- Inverter-driven cooling:METI energy-efficiency benchmarks in Japan push manufacturers toward compressor technologies that reduce power consumption in high-density vending corridors.
Market Restraints
- Aluminum chassis input costs:Volatility in lightweight metal pricing squeezes margins for manufacturers transitioning from steel frames to corrosion-resistant alternatives.
- Refrigerant supply concentration:F-Gas Regulation phaseout timelines in Europe create dependency on limited suppliers of low-GWP alternatives, constraining compressor availability.
- Biometric payment technical limitations:Fingerprint and facial recognition systems face accuracy degradation in high-humidity tropical climates, limiting deployment in Southeast Asian corridors.
Strategic Opportunities
- Healthy food vending white space:Universities and healthcare campuses in the United States represent underpenetrated demand for refrigerated protein-focused and fresh-portfolio machines.
- IoT-enabled dynamic pricing:Remote diagnostics and real-time inventory management converge to capture margin pools through reduced service intervals and stockout prevention.
- India urban corridor expansion:Metro rail networks and IT park clusters in Bangalore, Hyderabad, and Pune create new channel opportunities for automated retail deployment.
Industry Challenges
- Cold-chain technician scarcity:Specialized refrigeration maintenance skills are concentrating among aging workforces in Japan and Germany, constraining service network expansion.
- Legacy payment system integration:Retrofitting cashless modules into 15-20 year old mechanical vending estates requires custom firmware bridging, complicating deployment timelines.
- FDA food safety certification:Temperature-sensitive product distribution mandates create compliance complexity for operators expanding into fresh and perishable categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverage Vending Machine Market |
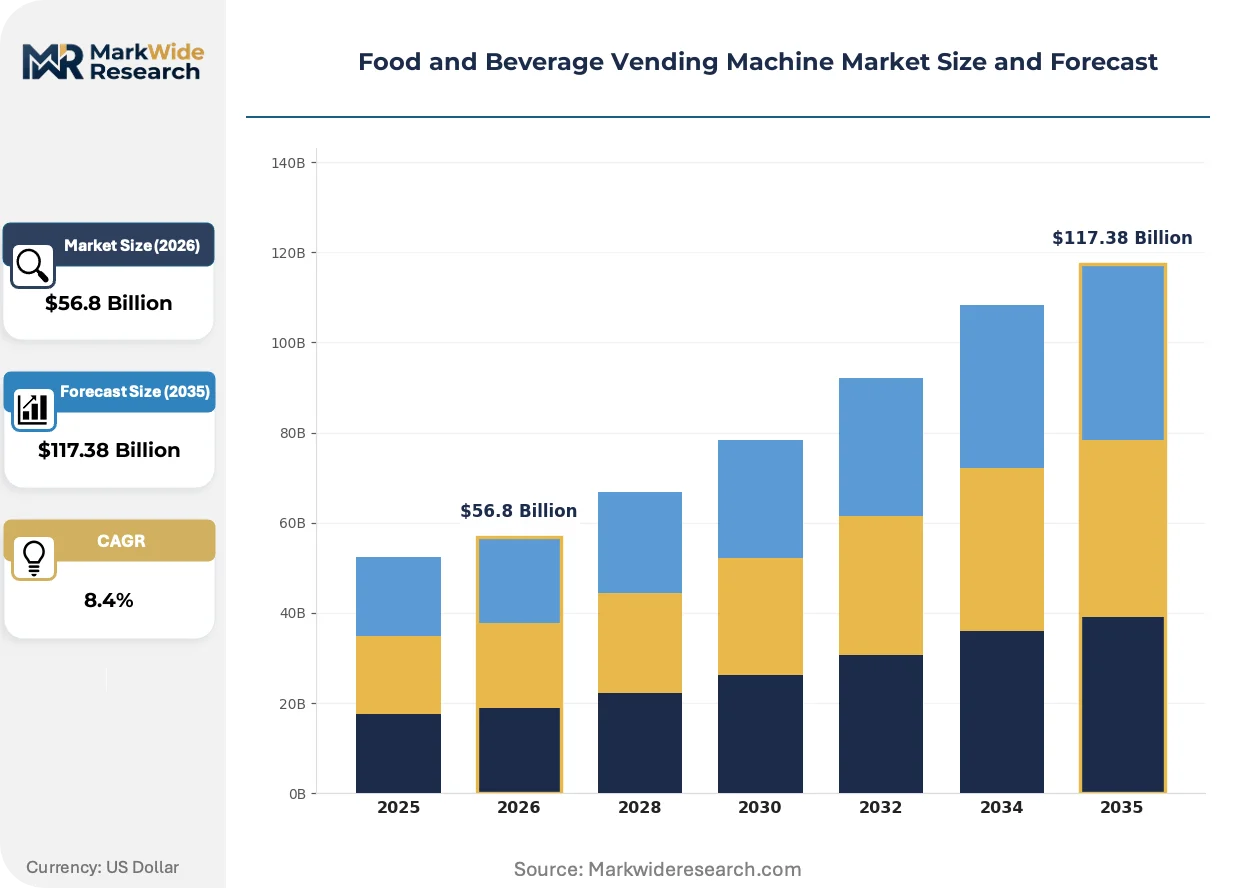
| Market Size in 2026 | $56.8 Billion |
| Market Size in 2035 | $117.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Vending Machines, Beverage Vending Machines, Combo Vending Machines, Healthy Food Vending Machines End User: Office Buildings, Educational Institutions, Hospitals, Public Spaces Technology: Cashless Payment Systems, IoT-Enabled Machines, Refrigerated Units, Solar-Powered Units Installation Type: Stand-Alone Units, Wall-Mounted Units, Mobile Vending Solutions, Custom Configurations |
| Companies Covered | Crane Payment Innovations, Azkoyen Group, Fuji Electric, Seaga Manufacturing, Bianchi Vending, Sanden Holdings, N&W Global Vending, Jofemar, Evoca Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverage Vending Machine Market Emerging Trajectories
Payment convergence, refrigerant transitions, and procurement model evolution are compressing technology cycles and redrawing competitive boundaries across automated foodservice systems.
Biometric authentication modules are unifying identity verification with transaction completion in premium workplace and airport deployments. Corporate facilities in Tokyo and Singapore are adopting palm-vein and facial recognition at pace, replacing card-based systems. This unifying architecture is compressing hardware vendor margins while elevating software and data-analytics providers in value chains.
The EU F-Gas Regulation mandates refrigerant transitions that reshape compressor specifications for European deployments. Manufacturers must redesign cooling systems around low-global-warming-potential alternatives, raising engineering costs. Refrigerated beverage and fresh-food machines in Germany, France, and the Netherlands face the steepest compliance timelines, with retrofit deadlines accelerating procurement decisions.
Employer and institutional procurement is consolidating vendor relationships around full-service vending management contracts. Traditional equipment-sale models are giving way to outcome-based partnerships where operators retain ownership and absorb maintenance risk. This shift is most visible in United States healthcare systems and Japanese corporate campuses, where facilities managers prioritize uptime guarantees over capital expenditure control.
Food and Beverage Vending Machine Market Segmentation
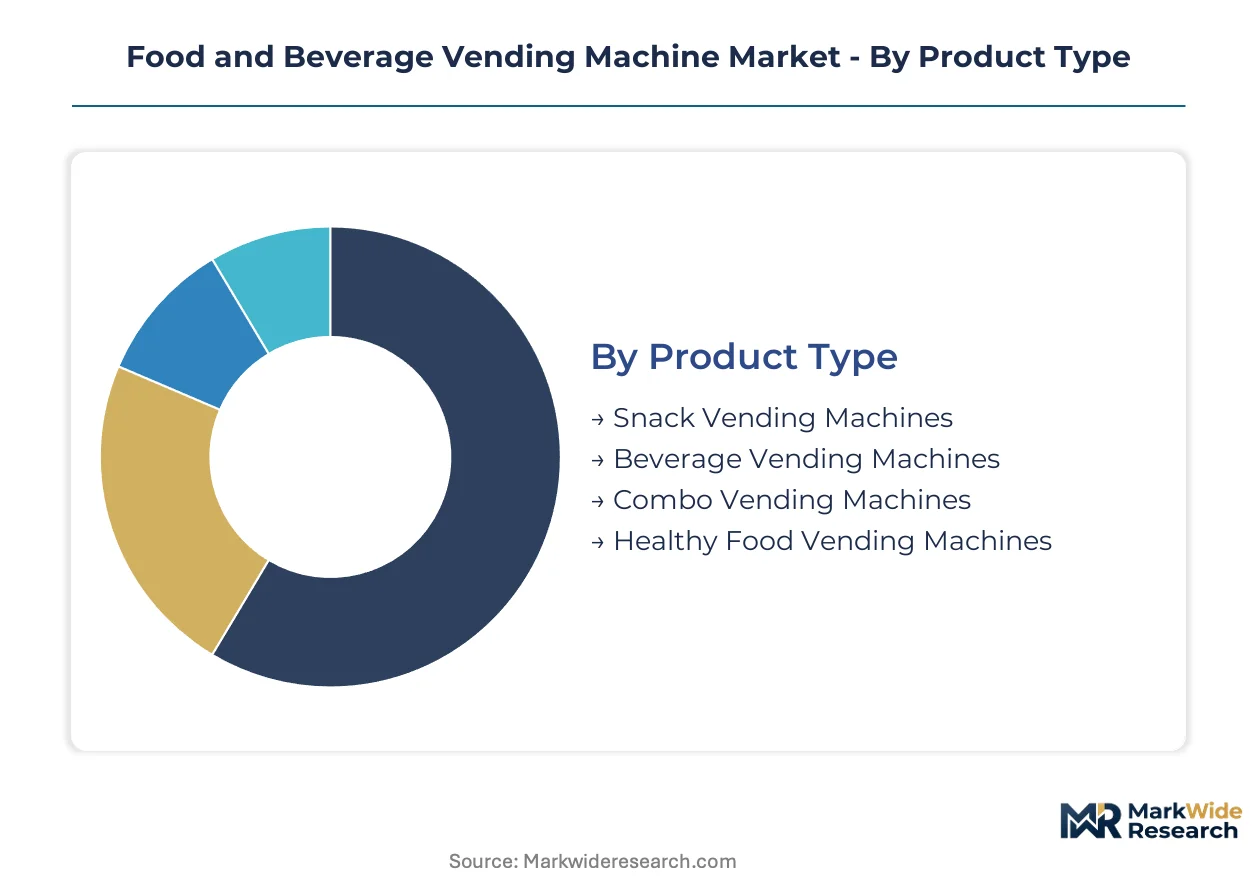
Vending machine procurement decisions hinge on throughput requirements, site constraints, and product perishability. Segmentation reveals how capital deployment and technology choices diverge across deployment environments.
Product Type:
Buyers prioritize SKU velocity and margin profile when selecting machine formats.
- Beverage Vending Machines:Compressor-based cooling systems handle carbonated, still, and functional drinks at 2°C to 8°C operating ranges. Japan's corporate campuses and Singapore's transit corridors sustain the highest installed density per capita, driven by tropical climate demand and 24-hour consumption patterns.
- Healthy Food Vending Machines:Refrigerated cabinets with precise humidity control preserve fresh salads, protein packs, and cut fruit. US universities and healthcare systems in California and Texas are replacing legacy snack portfolios fastest, responding to employer wellness mandates and student dietary preferences.
- Snack Vending Machines:Ambient-temperature spiral or conveyor dispensing dominates legacy office installations.
- Combo Vending Machines:Dual-zone refrigeration plus ambient storage accommodates mixed portfolios in space-constrained sites.
Volume sits with Beverage Vending Machines; growth tilts toward Healthy Food Vending Machines.
End User:
Site-specific traffic patterns and contract structures determine operator profitability.
- Office Buildings:Full-service management contracts dominate, with operators retaining ownership and absorbing maintenance risk. Japan's logistics hubs and US tech campuses in Seattle and Austin are expanding automated foodservice footprints as labor costs rise.
- Hospitals:FDA temperature-compliance requirements and 24-hour staffing needs create premium positioning for refrigerated units. US healthcare systems prioritize uptime guarantees over capital expenditure control.
- Educational Institutions:Student traffic spikes between classes favor high-capacity combo configurations.
- Public Spaces:Transit authorities in India and Brazil drive demand for ruggedized, vandal-resistant enclosures.
Contract value concentrates in Office Buildings; margin expansion favors Hospitals.
Technology:
Regulatory mandates and connectivity requirements are compressing replacement cycles.
- Cashless Payment Systems:Contactless readers and mobile-wallet integration satisfy EU AI Act mandates and parallel financial regulations in Germany, France, and Italy. Retrofit demand is accelerating hardware replacement across 15-20 year legacy installed bases.
- IoT-Enabled Machines:Remote diagnostics, dynamic pricing algorithms, and predictive inventory management reduce service intervals and stockout rates. Corporate facilities in Tokyo and Singapore are adopting palm-vein and facial recognition modules fastest.
- Refrigerated Units:F-Gas Regulation compliance is forcing compressor redesigns around low-global-warming-potential refrigerants.
- Solar-Powered Units:Off-grid deployments in rural India and sub-Saharan Africa bypass unreliable electrical infrastructure.
Replacement demand clusters in Cashless Payment Systems; capability differentiation centers on IoT-Enabled Machines.
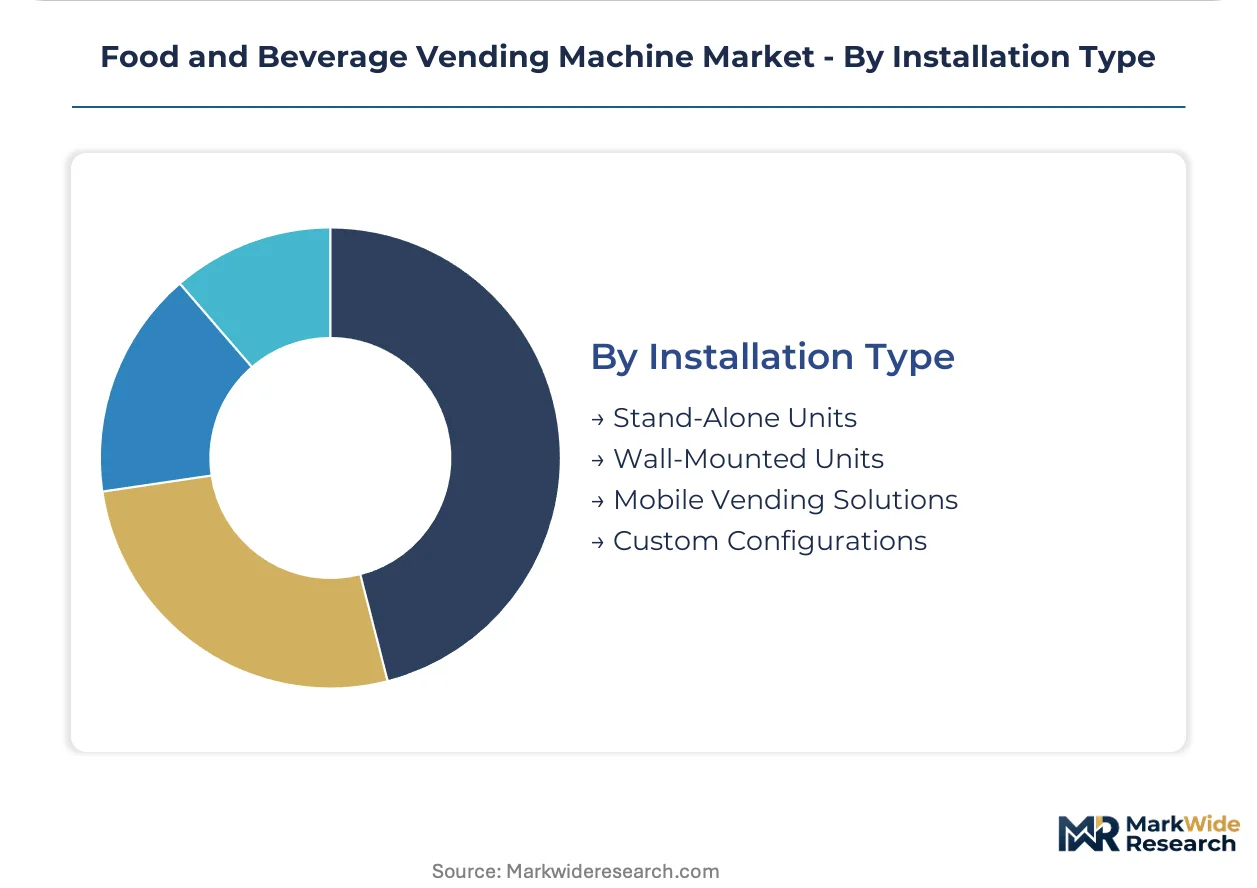
Installation Type:
Physical site constraints and mobility requirements shape chassis specifications.
- Stand-Alone Units:Floor-mounted steel or aluminum chassis accommodate 400-800 SKUs in high-traffic corridors. Japan's aging vending technician workforce is concentrating maintenance skills, constraining service network expansion for distributed estates.
- Mobile Vending Solutions:Trailer-mounted or vehicle-integrated systems serve construction sites, festivals, and emergency response. India's metro rail expansion in Bangalore, Hyderabad, and Pune is creating new channel opportunities.
- Wall-Mounted Units:Space-efficient configurations target narrow corridors and retrofit environments.
- Custom Configurations:Bespoke dimensions and branding serve luxury hospitality and corporate identity programs.
Installed base accumulates in Stand-Alone Units; deployment flexibility is expanding most quickly in Mobile Vending Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate component sourcing for vending machine refrigeration and payment modules. These manufacturing clusters feed assembly plants across East Asia and Europe. Demand patterns diverge sharply by regulatory environment and labor cost structure.
United States
Corporate campuses in Seattle and Austin are expanding automated foodservice footprints as labor costs rise. FDA temperature-compliance requirements for perishable distribution create certification complexity for operators entering fresh-food categories. Healthcare systems in Texas and California prioritize full-service management contracts with uptime guarantees over capital expenditure control.
Japan
Aging demographics and convenience culture sustain the highest vending density per capita globally. METI energy-efficiency benchmarks push manufacturers toward inverter-driven cooling and LED lighting retrofits across Kanto and Kansai corridors. Cold-chain technician scarcity concentrates maintenance skills among aging workforces, constraining service network expansion.
Germany
The EU AI Act and parallel financial regulations mandate contactless payment compatibility, accelerating hardware replacement across legacy installed bases. F-Gas Regulation phaseout timelines force compressor redesigns around low-global-warming-potential refrigerants. Industrial clusters in Bavaria and North Rhine-Westphalia face the steepest compliance deadlines.
India
Metro rail networks and IT park clusters in Bangalore, Hyderabad, and Pune create new channel opportunities for automated retail deployment. FSSAI food safety standards govern temperature-sensitive product distribution as operators expand into fresh categories. Solar-powered off-grid units bypass unreliable electrical infrastructure in rural corridors.
Singapore
Tropical climate demand and 24-hour consumption patterns drive premium positioning for refrigerated beverage units in transit corridors. Corporate facilities are adopting palm-vein and facial recognition modules fastest, replacing card-based payment systems. Changi Airport and central business district deployments set regional benchmarks for biometric authentication integration.
Food and Beverage Vending Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with payment-system integrators capturing margin pools in retrofit cycles while refrigeration specialists defend positions in cold-chain deployments. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive compressor technology, pure-play payment solution providers, and regional fabrication specialists serving price-sensitive emerging markets. Consolidation pressure concentrates among mid-scale European operators facing simultaneous refrigerant and cashless-migration capex cycles. Geographic expansion and technology licensing represent the dominant competitive moves as players sequence entry into India's urban corridors and Southeast Asian transit networks.
Among Japan-based industrial groups, Fuji Electric and Sanden Holdings exemplify the diversified conglomerate archetype, leveraging captive refrigeration expertise to anchor positions in compressor modules and cold-chain systems. Azkoyen Group represents the payment-system specialist vector, with its Spanish corporate structure situating it within the EU regulatory orbit where cashless mandates are compressing replacement timelines. These three companies occupy positions that illustrate how competitive advantage is fragmenting across hardware, software, and integrated service delivery models.
| Leading Market Players |
|---|
| Crane Payment Innovations |
| Azkoyen Group |
| Fuji Electric |
| Seaga Manufacturing |
| Bianchi Vending |
| Sanden Holdings |
| N&W Global Vending |
| Jofemar |
| Evoca Group |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up vending operators in Germany and Italy are consolidating fragmented service estates, compressing procurement timelines and forcing equipment suppliers into longer payment terms that squeeze working capital across aluminum and compressor sourcing tiers.
Pricing Analysis
Short lead-time premiums dominate European procurement, with F-Gas Regulation compliance deadlines compressing order cycles for low-GWP compressor retrofits. Three-tier pricing structure across premium IoT-enabled, standard cashless-retrofit, and economy mechanical legacy units separates payment-system integrators from basic fabricators. Cost compression in economy tiers intensifies because Chinese component imports face escalating EU customs scrutiny. University and healthcare buyers in the United States demonstrate lowest price sensitivity, prioritizing FDA-compliant temperature monitoring over unit economics.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing clusters to European assembly plants is reshaping inventory strategies among compressor and payment module suppliers. Component sourcing concentrates in China for thermoelectric cooling elements, Japan for inverter-driven compressors, and South Korea for touch-display interfaces. Aluminum chassis fabrication draws from Taiwanese sheet metal suppliers facing energy cost inflation. Single-source vulnerability in low-GWP refrigerant feedstock constrains European production scaling. Distribution runs through regional service integrators who bundle installation, maintenance, and cashless payment reconciliation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
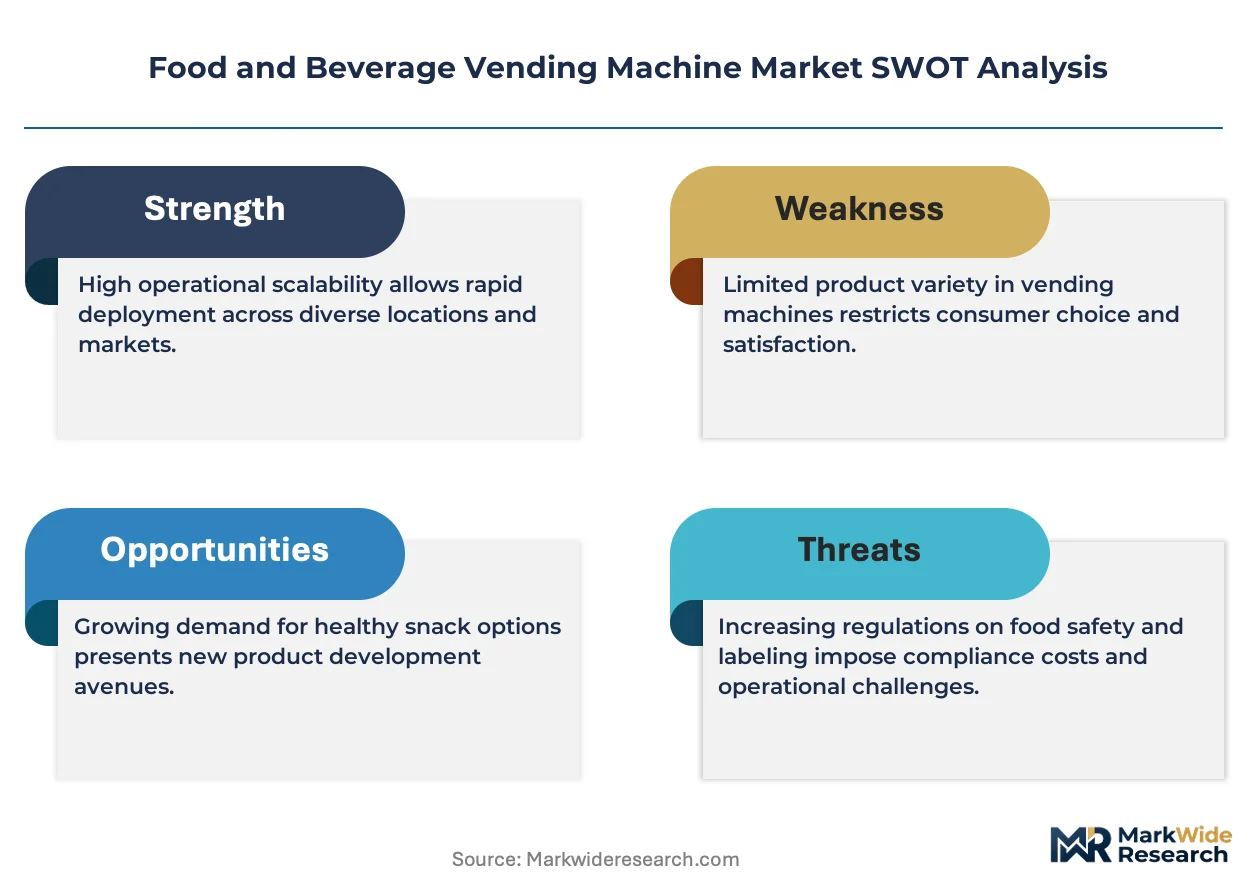
The Food and Beverage Vending Machine Market operates as a cost-of-compliance arena where EU AI Act cashless mandates and F-Gas refrigerant phaseouts erect capital barriers that favor incumbent operators with balance-sheet depth to absorb dual retrofit cycles.
For Market Incumbents: Extend service network density in Japan's Kanto corridor before cold-chain technician scarcity hardens into structural constraint. Acquire distressed payment-system integrators in Italy and Spain to consolidate EU retrofit demand. Compressor technology leadership at Fuji Electric and Sanden Holdings faces emerging threat from Chinese inverter suppliers penetrating Southeast Asian transit corridors; defend through captive R&D in tropical-climate efficiency benchmarking. For New Entrants and Emerging Players: Direct-to-operator SaaS platforms for dynamic pricing and inventory optimization offer the lowest customer-acquisition friction in US healthcare and university verticals. Target India's Bangalore-Hyderabad IT corridor with solar-powered mobile vending solutions before metro rail station concessions lock up. White-space penetration runs thickest in refrigerated protein-focused portfolios where FDA certification complexity deters commodity snack operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European operators with installed base scale but strained refrigerant-cashless dual capex schedules in Germany and France. Five-to-ten-year viability hinges on outcome-based contract conversion rates in US healthcare systems. Monitor METI energy-efficiency benchmark acceleration as signal for Japanese manufacturer consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Payment System Retrofit Acceleration | EU AI Act compliance deadlines in Germany compress hardware replacement timelines for legacy cash estates. |
| Refrigerant Technology Transition | F-Gas Regulation mandates in the Netherlands force compressor redesigns around low-GWP alternatives. |
| IoT Platform Integration | Remote diagnostics adoption in Tokyo corporate campuses reduces service interval frequency and stockout rates. |
| Outcome-Based Contract Conversion | Full-service management models in Texas healthcare systems shift capital risk from facilities to operators. |
| Biometric Authentication Deployment | Palm-vein modules at Singapore Changi Airport replace card systems and elevate software provider margins. |
Methodological Framework
Multi-period observation of installed base retirement rates, refrigerant-phaseout compliance calendars, and cashless-payment penetration curves anchored the trend analysis, supplemented by interviews with vending fleet operators, cold-chain maintenance technicians, foodservice procurement directors at US healthcare systems, and payment-system integration engineers. Secondary validation drew from EU F-Gas Regulation implementation reports, METI energy-efficiency benchmarking disclosures, FDA food safety guidance documents, and trade customs data for aluminum and compressor component flows. Bottom-up unit economics modeling triangulated against top-down market sizing across geographic regulatory clusters.
Input-output matrices mapped product-type segmentation against end-user procurement structures, technology replacement cycles, and installation-type mobility requirements over the projection horizon. CAGRs derived from regression analysis of historical retrofit spending correlated with regulatory deadline proximity and labor cost inflation indices. Forecast inputs incorporated inverter-driven cooling adoption rates in Japan and biometric payment module attach rates in Singapore transit deployments.
The model holds under steady regulatory enforcement timelines and aluminum price bands within historical volatility ranges; deviation in EU customs enforcement intensity or abrupt low-GWP refrigerant supply disruption would shift replacement demand curves. Stakeholders should weight assumptions against their own operating context and regional compliance calendar exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
UK Countertop Ice Makers Market