
 Kegerator Equipment Market | 2026-2036
Kegerator Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Kegerator Equipment Market Foresight
Energy Star certification requirements for commercial refrigeration equipment is expanding procurement criteria across foodservice and hospitality channels. True Manufacturing leverages its domestic manufacturing footprint to sustain rapid fulfillment for commercial accounts. Perlick Corporation specializes in premium built-in installations for high-end residential and hospitality projects. Danby Products competes in the mass-market residential tier through broad retail distribution and accessible price positioning.
Kegerator equipment comprises self-contained refrigeration systems engineered to maintain draft beverages at precise serving temperatures, typically between 32°F and 40°F, using forced-air or direct-draw cooling mechanisms with CO2 or nitrogen pressure regulation. The primary commercial purpose centers on preserving carbonation integrity, preventing spoilage, and enabling consistent pour quality in on-premise consumption environments. Full-size commercial kegerators dominate installed base value given their higher unit economics and replacement frequency in high-volume bars and breweries, while portable and mini formats represent the fastest-growing demand vector among home users seeking flexible entertainment solutions. Wi-Fi-enabled connectivity features are emerging as a margin concentration point as remote temperature monitoring and keg-level tracking justify premium positioning.
EPA Energy Star standards and DOE commercial refrigeration efficiency mandates shape product design requirements and qualification for utility rebate programs across the United States. NSF International sanitation certification governs market access for equipment deployed in licensed foodservice establishments, creating compliance barriers for unqualified imports. OSHA workplace safety regulations influence caster specifications, electrical grounding, and ventilation clearances in commercial installations. Stakeholders must monitor evolving refrigerant phase-down schedules under AIM Act provisions and assess supplier readiness for low-GWP alternative transitions.
Market Dynamics
The kegerator equipment sector is experiencing a fundamental shift as EPA Energy Star efficiency mandates and AIM Act refrigerant phase-downs force simultaneous redesign of cooling systems and supply chains. Equipment manufacturers must now engineer for hydrofluoroolefin transitions while maintaining NSF sanitation compliance.
Growth Catalysts
- AIM Act refrigerant mandates:The EPA's scheduled phase-down of high-GWP hydrofluorocarbons is compelling commercial foodservice operators to accelerate equipment replacement cycles ahead of 2025-2030 compliance deadlines.
- Craft brewery density:Independent brewery openings in the United States are expanding draft infrastructure investment as on-premise freshness becomes a competitive differentiator for regional beer producers.
- Residential outdoor entertainment:Backyard kitchen and patio renovation spending is elevating demand for built-in and portable kegerator formats among suburban homeowners seeking draft-quality beverage service.
Market Restraints
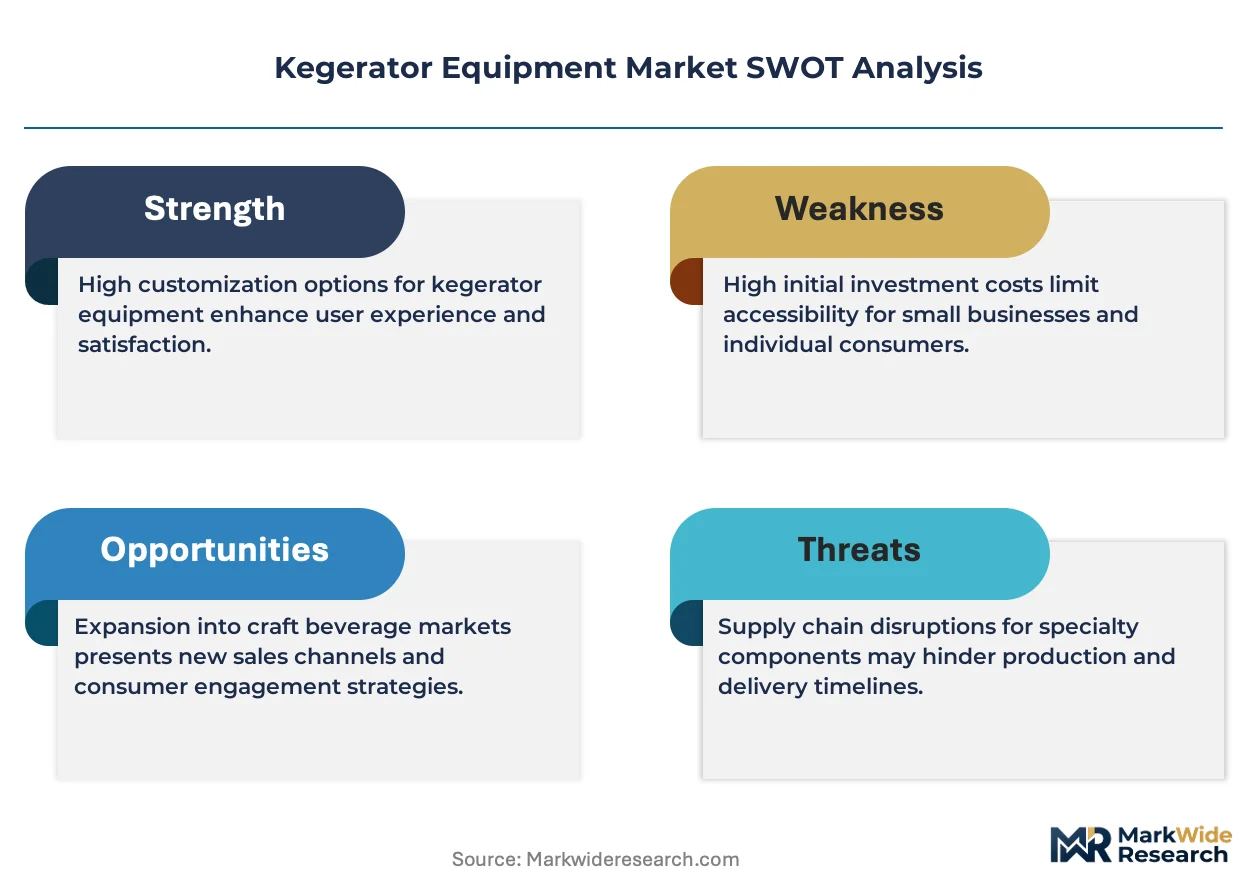
- Copper and aluminum input volatility:Refrigeration coil and compressor housing materials face commodity price swings that compress manufacturer margins and destabilize contract pricing.
- Compressor supply concentration:Domestic production of fractional horsepower hermetic compressors clusters among a limited supplier base, creating vulnerability for mid-tier equipment assemblers.
- NSF certification timeline friction:Sanitation testing protocols for food-contact surfaces extend product launch windows by four to six months, delaying revenue recognition for new model introductions.
Strategic Opportunities
- Underpenetrated hospitality in secondary US metros:Smaller metropolitan statistical areas exhibit lower kegerator penetration per licensed drinking establishment than major coastal markets, presenting whitespace for distributor expansion.
- IoT-enabled predictive maintenance:Convergence of Wi-Fi connectivity with temperature logging and keg-level sensors is enabling subscription-based monitoring services that generate recurring revenue streams.
- Utility rebate program alignment:DOE-qualified commercial refrigeration equipment unlocks state-level efficiency incentives that reduce net acquisition cost for foodservice buyers and accelerate sales velocity.
Industry Challenges
- Refrigerant technician certification gaps:The transition to A2L-classified mildly flammable hydrofluoroolefins requires specialized handling credentials that remain scarce in HVAC service networks.
- Legacy control system integration:Building management system protocols in aged commercial kitchens often lack digital interfaces, complicating deployment of connected kegerator monitoring solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kegerator Equipment Market |
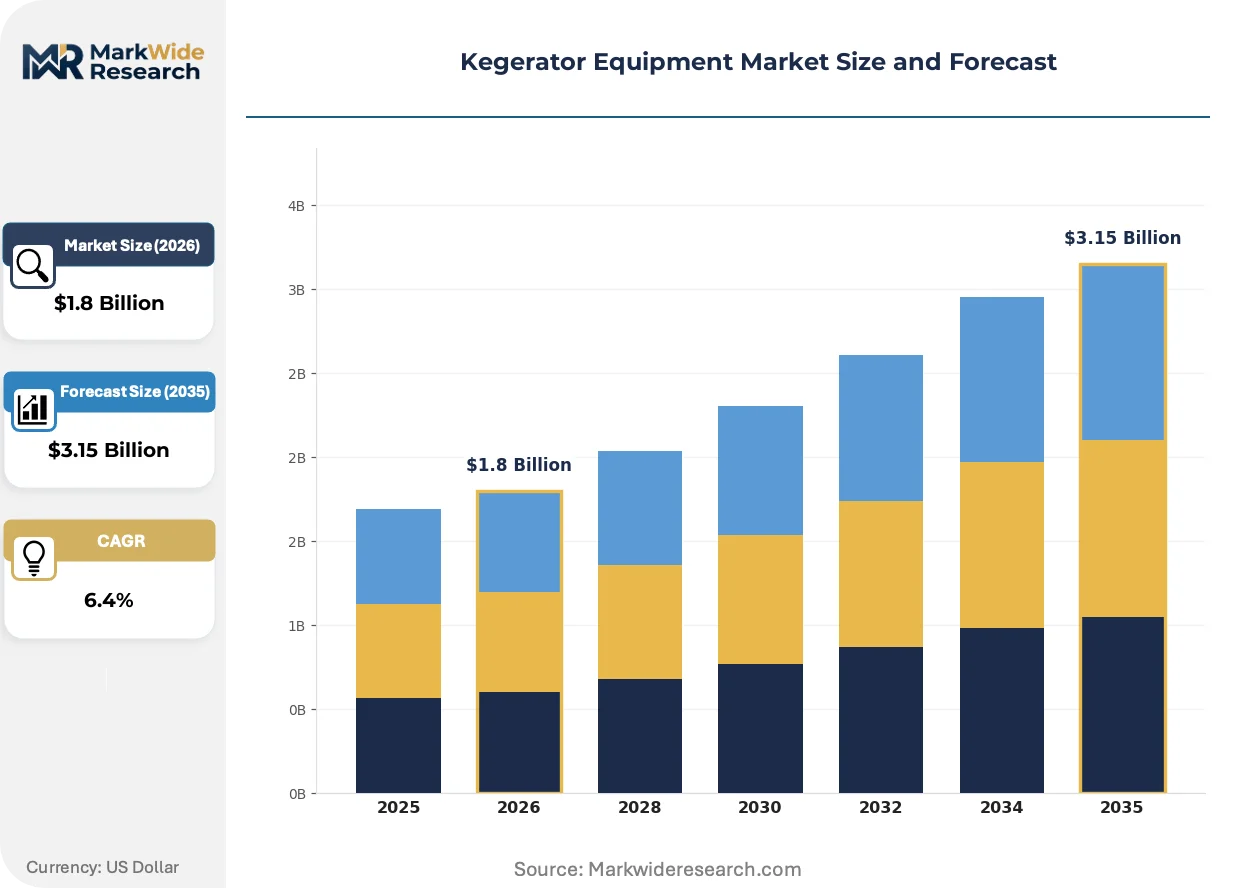
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Kegerators, Full-Size Kegerators, Commercial Kegerators, Portable Kegerators End User: Restaurants, Bars, Breweries, Home Users Installation Type: Freestanding, Built-In, Countertop, Outdoor Connectivity: Wi-Fi Enabled, Bluetooth, Wired, None |
| Companies Covered | True Manufacturing, Danby Products, Haier Group Corporation, Perlick Corporation, Micro Matic, Kegco, Versonel, DCS by Fisher and Paykel Appliances, Nostalgia Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kegerator Equipment Market Shifts & Advancements
Equipment intelligence and refrigerant chemistry are converging to redefine kegerator architecture. Manufacturers are racing to embed connectivity while navigating the most significant cooling-system transition in two decades.
Variable-speed compressor technology is electrifying efficiency benchmarks in commercial kegerator design. These electronically commutated motor systems modulate cooling output against thermal load rather than cycling on-off, reducing energy draw by twenty to thirty percent in high-volume bar installations. Draft system integrators are specifying variable-speed units for new-build brewery taprooms where utility costs dominate operating economics.
The EPA's phasedown of hydrofluorocarbon refrigerants under AIM Act authority is restructuring equipment qualification requirements. Manufacturers must now validate alternative refrigerant performance in sub-40°F holding applications while maintaining NSF sanitation standards. Commercial refrigeration OEMs are prioritizing R-290 propane and R-600a isobutane formulations for their negligible global warming potential, though flammability classifications demand redesigned electrical enclosures.
Specification authority is migrating from facilities managers to procurement departments with total-cost-of-ownership mandates. Foodservice chain buyers now weight energy consumption, warranty duration, and IoT compatibility equally with upfront capital cost, compressing margins for equipment lacking connected feature sets. This behavioral shift is most pronounced in multi-unit restaurant operators with centralized beverage programs spanning fifty or more locations.
Kegerator Equipment Market Segmentation
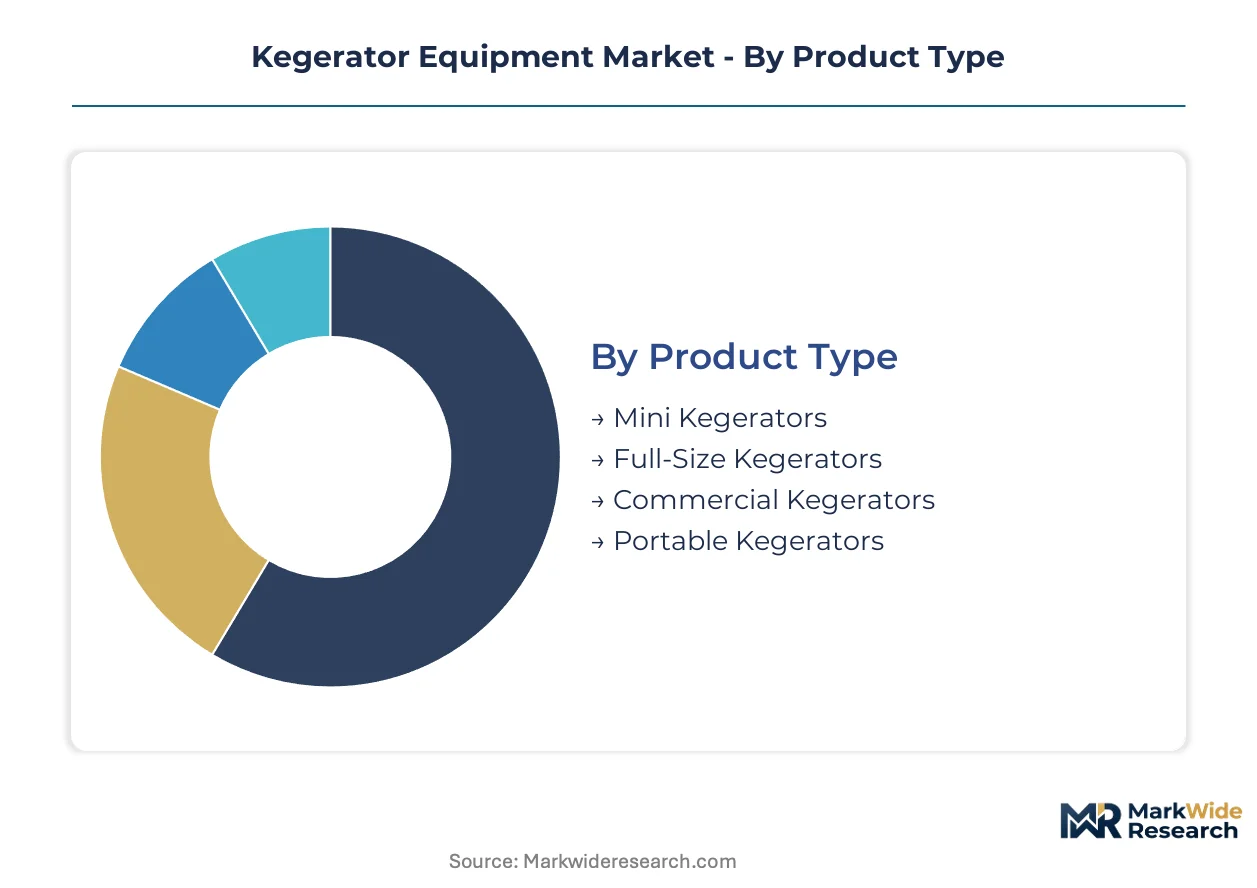
Segmentation in the kegerator equipment market reveals divergent upgrade cycles across commercial and residential channels. Product specifications, installation constraints, and connectivity requirements create distinct procurement patterns that manufacturers must address through differentiated engineering and distribution strategies.
Product Type:
Replacement cycles vary sharply by product format, with commercial-grade systems facing accelerated turnover due to refrigerant compliance deadlines while residential formats extend lifespans through modular component swaps.
- Commercial Kegerators:Engineered for continuous-duty operation with stainless steel interiors, forced-air cooling, and dual-pressure CO2/nitrogen regulation. Demand clusters in brewery taprooms across the United States where independent producers invest in on-premise draft infrastructure to differentiate freshness. EPA Energy Star mandates and AIM Act refrigerant phase-downs compress replacement windows for aging installed bases.
- Full-Size Kegerators:Mid-capacity units typically accommodating single half-barrel or multiple sixth-barrel configurations, bridging residential entertainment and light commercial use. Sales concentrate in suburban backyard kitchen renovations where homeowners prioritize draft quality for entertaining. These units carry higher average selling prices than mini formats but face pressure from portable alternatives.
- Mini Kegerators:Compact countertop systems designed for 5-liter mini-kegs, appealing to apartment dwellers and casual users with space constraints.
- Portable Kegerators:Battery or DC-powered mobile units with insulated dispensing towers, targeting tailgating and outdoor event applications.
Volume placements concentrate in full-size residential and commercial formats; the steepest expansion trajectory belongs to portable configurations as outdoor entertainment investments climb.
End User:
Customer type dictates specification authority, with chain restaurant procurement departments wielding total-cost-of-ownership criteria against independent operators prioritizing upfront capital efficiency.
- Breweries:Regional and independent beer producers deploying on-premise taprooms as margin-protective distribution channels. These operators specify NSF-certified equipment with variable-speed compressors to minimize utility exposure. The United States craft brewery density sustains premium equipment demand despite input cost volatility.
- Bars:High-volume licensed drinking establishments requiring durable refrigeration with rapid recovery performance during peak service windows. Urban bar operators in major metropolitan markets drive replacement demand as legacy equipment ages past efficiency thresholds.
- Restaurants:Foodservice chains with centralized beverage programs specifying connected equipment for remote monitoring compliance.
- Home Users:Residential purchasers ranging from casual entertainers to dedicated hobbyists, with specification sensitivity varying by renovation investment level.
Procurement scale favors brewery and bar channels; home user expansion is gaining share fastest as outdoor kitchen investments penetrate secondary metros.
Installation Type:
Physical integration requirements determine margin structure, with built-in and outdoor formats commanding specification complexity premiums over commodity freestanding units.
- Built-In:Front-venting systems designed for cabinetry integration with zero-clearance sides, requiring precise dimensional coordination and custom panel compatibility. Demand concentrates in high-end residential renovations and hospitality new-builds where aesthetic continuity commands premium positioning. These installations carry extended lead times and specialized service requirements.
- Outdoor:Weatherized enclosures with enhanced insulation, sealed electrical components, and corrosion-resistant finishes for patio and backyard deployment. Sales accelerate in Sun Belt suburban markets where year-round outdoor entertaining extends usable seasonality. Units must maintain holding temperatures across ambient temperature swings that stress standard refrigeration circuits.
- Freestanding:Self-contained mobile units with caster mounting, dominating entry-level commercial and mass-market residential segments.
- Countertop:Ultra-compact mini-keg systems requiring no floor space, appealing to constrained urban residential environments.
Freestanding units dominate unit volume; outdoor configurations are climbing fastest as backyard kitchen investments sustain momentum.
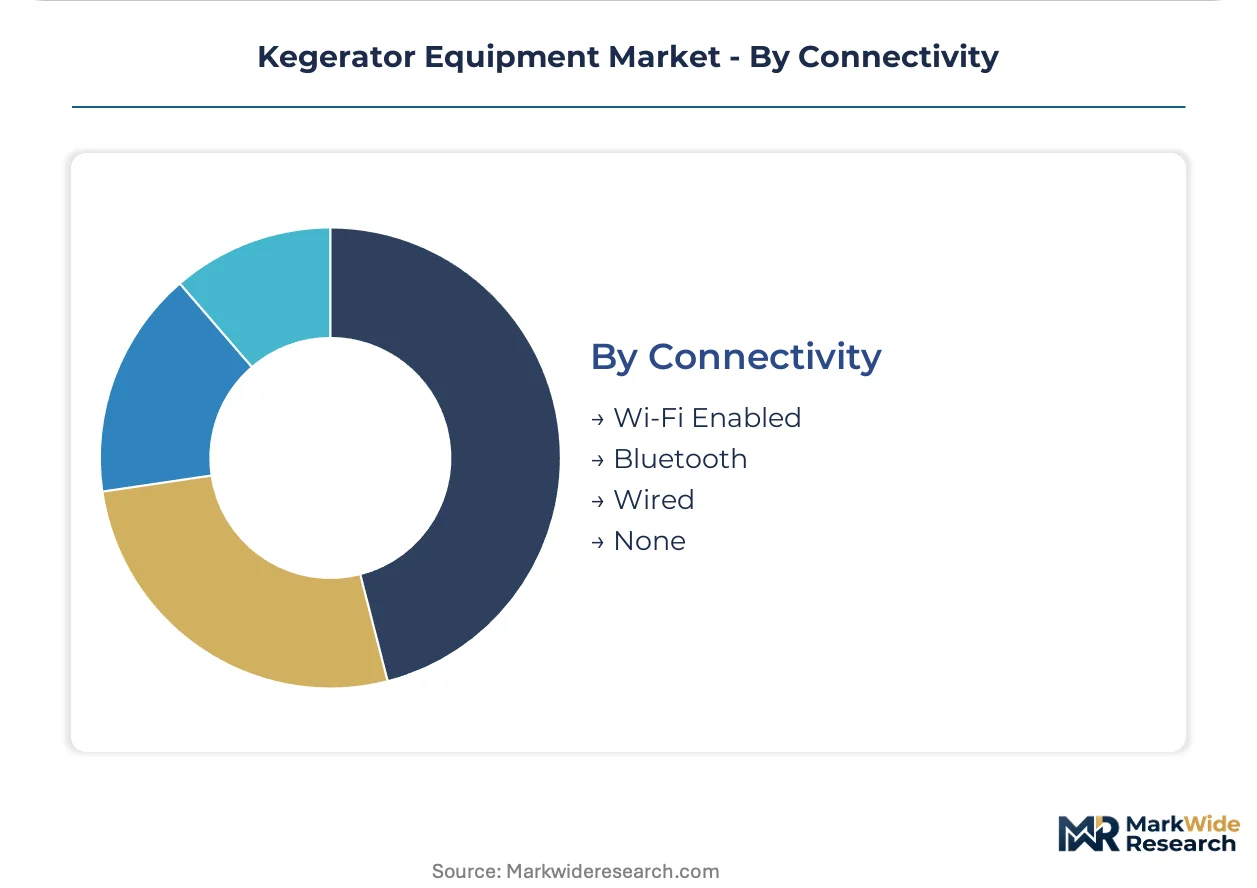
Connectivity:
Intelligence tiering creates pricing stratification, with connected functionality migrating from novelty to procurement requirement in multi-unit commercial deployments.
- Wi-Fi Enabled:Cloud-connected systems supporting remote temperature monitoring, keg-level telemetry, and predictive maintenance alerts via mobile application interfaces. Chain restaurant operators with fifty-plus locations now specify Wi-Fi capability as standard for centralized beverage program oversight. These features unlock subscription service revenue streams for equipment vendors.
- Bluetooth:Short-range wireless connectivity for local device pairing, enabling temperature adjustment and status monitoring without cloud dependency. Appeals to independent operators and residential users seeking connectivity without recurring service fees or network security exposure.
- Wired:Ethernet or serial-connected systems for building management system integration in institutional and hospitality deployments.
- None:Basic electromechanical control systems without digital interfaces, retaining share in cost-sensitive replacement markets.
Non-connected equipment retains volume dominance in replacement channels; Wi-Fi configurations are expanding most quickly as procurement specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors North American kegerator demand density through its concentration of craft brewery taprooms and independent beer production facilities. The metropolitan corridor between Boulder and Colorado Springs sustains premium equipment procurement as regional brewers invest in on-premise draft infrastructure.
United States
Independent brewery openings across the Pacific Northwest and Southeast drive commercial kegerator deployment as freshness becomes a competitive differentiator. EPA Energy Star mandates and AIM Act refrigerant phase-downs compress replacement cycles for aging installed bases in high-volume bars. The Chicago metropolitan area concentrates foodservice chain procurement activity where centralized beverage programs specify connected equipment.
Germany
Traditional beer hall culture sustains demand for durable commercial refrigeration with dual-pressure CO2 and nitrogen regulation systems. The EU F-Gas Regulation accelerates transitions to low-GWP refrigerant formulations in licensed drinking establishments. Bavaria's Munich-Regensburg industrial corridor hosts precision fabrication clusters supplying stainless steel interiors to equipment assemblers.
China
Rising disposable incomes in tier-one cities elevate residential outdoor entertainment investments including patio kegerator installations. The country's national standards body enforces energy efficiency labeling requirements for commercial refrigeration equipment. The Yangtze River Delta manufacturing belt around Shanghai concentrates compressor component production serving domestic and export markets.
United Kingdom
Pub sector consolidation drives standardization of draft infrastructure specifications across multi-site operators. The UK's departure from EU regulatory frameworks creates parallel certification requirements for NSF-equivalent sanitation standards. London's craft beer revival in Bermondsey and Hackney sustains premium equipment demand among independent taproom operators.
Kegerator Equipment Market Competitive Landscape
The competitive structure tilts toward domestic manufacturing specialists with rapid fulfillment capabilities for commercial accounts. Equipment assemblers cluster around three strategic tiers: premium built-in specialists commanding specification authority in hospitality new-builds, mass-market residential players leveraging broad retail distribution, and commercial-grade fabricators optimizing for NSF certification compliance. Dominant competitive moves include geographic expansion into underpenetrated secondary metropolitan markets and technology licensing for IoT-enabled connectivity modules.
Among North American equipment fabricators, True Manufacturing and Perlick Corporation exemplify divergent specialization archetypes. True Manufacturing occupies a position as a domestic manufacturing anchor with rapid fulfillment infrastructure for commercial foodservice accounts. Perlick Corporation sits within the premium-tier built-in segment where aesthetic integration commands specification authority in high-end residential and hospitality projects. Danby Products represents the mass-market residential archetype through accessible price positioning and broad retail channel presence. Haier Group Corporation anchors the Asia-Pacific manufacturing base with scale-driven component supply capabilities.
| Leading Market Players |
|---|
| True Manufacturing |
| Danby Products |
| Haier Group Corporation |
| Perlick Corporation |
| Micro Matic |
| Kegco |
| Versonel |
| DCS by Fisher and Paykel Appliances |
| Nostalgia Products |
| Others |
Supply & Pricing Matrix
EPA Energy Star certification and AIM Act refrigerant compliance gates qualified supply access and premium-tier pricing power. Equipment lacking NSF sanitation validation or low-GWP refrigerant compatibility faces margin compression as foodservice buyers consolidate procurement around qualified vendors.
Pricing Analysis
Throughput-based uptime guarantees anchor value-based pricing for commercial kegerator deployments. Pricing stratifies across premium built-in, standard commercial-grade, and economy freestanding tiers, with differentiation driven by NSF certification level and IoT connectivity bundling. Cost compression in the residential tier is intensifying because mass-market retailers are squeezing contract terms. Home users in suburban renovation markets show highest price sensitivity, while brewery taproom operators prioritize total-cost-of-ownership over upfront capital.
Supply Chain Analysis
NSF sanitation certification and EPA refrigerant qualification requirements gate component sourcing and final assembly location decisions. Compressor production concentrates in China, the United States, and Germany, while stainless steel fabrication draws from domestic metalworking clusters. Raw material dependencies include copper refrigeration coils, aluminum compressor housings, and specialized refrigerant formulations. Single-source vulnerability in fractional horsepower hermetic compressors creates supply risk for mid-tier assemblers. Distribution runs through foodservice equipment distributors, direct brewery sales teams, and mass-market retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kegerator equipment sector is consolidating as refrigerant compliance costs and certification timelines force sub-scale fabricators toward exit. AIM Act mandates and NSF testing friction disproportionately burden smaller players lacking capital reserves.
For Market Incumbents: Extend variable-speed compressor R&D partnerships to secure efficiency leadership ahead of Energy Star tier upgrades. Deepen backward integration into stainless steel fabrication to insulate margins from commodity volatility. The threat of IoT-native entrants with subscription-first business models demands defensive connectivity module development.
For New Entrants and Emerging Players: Launch via direct-to-brewery sales models targeting secondary US metropolitan areas with lower incumbent penetration density. White-space exists in portable outdoor configurations for tailgating and event rental applications. Secondary metro brewery taprooms represent the most penetrable segment, with specification authority residing in owner-operators rather than centralized procurement.
For Investors and Strategic Acquirers: EPA refrigerant phase-down deadline acceleration is the leading indicator that replacement cycle velocity will compress industry margins before concentrating share among qualified survivors. Long-term viability favors fabricators with captive NSF testing relationships and domestic manufacturing footprints. Target acquisition archetype: mid-cap commercial specialists with established brewery channel relationships and pending low-GWP refrigerant certifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | AIM Act compliance unlocks utility rebate eligibility and EPA qualification for commercial foodservice accounts. |
| IoT Module Integration | Wi-Fi connectivity enables recurring subscription revenue from chain restaurant beverage program operators. |
| Secondary Metro Distribution Expansion | Denver-Boulder corridor density proves replicable in underpenetrated Sun Belt metropolitan markets. |
| NSF Certification Acceleration | Reduced testing timeline friction captures replacement demand ahead of competitor product launches. |
| Outdoor Product Line Extension | Weatherized enclosures address backyard kitchen renovation spending in suburban residential segments. |
Research Methodology
SEC filings, EPA regulatory dockets, and foodservice equipment customs records formed the secondary backbone of this analysis. Primary interviews with brewery operations directors, commercial refrigeration procurement managers, NSF certification specialists, and HVAC service contractors validated demand assumptions. Bottom-up unit economics from individual brewery taproom deployments were triangulated against top-down category spending estimates from foodservice chain capital expenditure disclosures.
Historical trendline analysis of replacement cycle timing and refrigerant transition deadlines informed the projection framework. Segmentation modeling spanned product format, installation type, connectivity tier, and end-user channel across the analysis window. CAGRs were derived from equipment shipment velocity patterns and brewery opening density correlations. Forecast inputs included Energy Star qualification timelines and AIM Act phase-down schedules without year-specific anchoring.
Refrigerant chemistry transition delays, commodity price spikes in copper and aluminum, and brewery taproom investment pullbacks are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around regulatory deadline adherence and supply chain qualification pacing. A model refresh is warranted upon material change in EPA enforcement posture or compressor supplier consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
Commercial Microwaves Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Food and Beverage Vending Machine Market