
 Instrument Landing System (ILS) Market | 2026-2036
Instrument Landing System (ILS) Market Size, Share, and Industry Trends Forecast 2026-2036
Instrument Landing System (ILS) Market Analysis
The EU Green Deal's airport decarbonization benchmarks are shifting procurement criteria toward energy-efficient ground infrastructure across European aviation hubs. Thales leverages its integrated air traffic management portfolio to sustain long-term service contracts with major airport authorities. ENGIE Ineo competes on civil engineering-electrical integration, anchoring its position in runway construction packages that bundle ILS installation with airfield lighting.
An Instrument Landing System is a ground-based radio navigation apparatus comprising localizer, glide slope, and marker beacon subsystems that transmit precisely modulated VHF and UHF signals to guide aircraft during final approach in reduced visibility conditions. ILS Category III systems dominate margin pools due to the complexity of fail-safe architectures required for zero-decision-height operations, while ILS Category I installations represent the largest installed base undergoing incremental upgrades. Commercial Aviation applications lead absolute demand as legacy systems at primary hubs reach end-of-design-life, though Military Aviation procurement is accelerating in regions prioritizing sovereign airfield resilience.
The FAA mandates ILS integrity standards under 14 CFR Part 171, while ICAO Annex 10 governs international interoperability and signal tolerances that manufacturers must satisfy for market access. EASA's certification requirements under CS-ETS and the EU AI Act's emerging provisions for autonomous landing systems are tightening compliance thresholds for next-generation equipment. Stakeholders must monitor divergence between FAA NextGen and SESAR deployment timelines when allocating R&D resources across transatlantic certification pathways.
Market Dynamics
FAA NextGen and SESAR deployment timelines are forcing synchronized replacement cycles at major hub airports, compressing procurement windows and concentrating vendor qualification requirements around dual-certification capability.
Growth Catalysts
- NextGen Modernization Mandate:The FAA's ground infrastructure refresh is compelling Category III upgrades at primary US hubs to support zero-visibility operations.
- EU Green Deal Airport Benchmarks:European decarbonization targets are redirecting capital toward energy-efficient localizer and glide slope architectures.
- Hub Traffic Density:Simultaneous runway construction at congested airports in China, Germany, and the United States is bundling ILS procurement with airfield electrical work.
Market Restraints
- Specialized RF Component Supply:Precision localizer antenna arrays depend on a concentrated base of microwave subsystem suppliers in Germany and the United States.
- GBAS Substitution Threat:GPS-augmented landing systems are displacing Category I ILS at greenfield airports with lower infrastructure footprints.
- Dual Certification Burden:Divergent FAA Part 171 and EASA CS-ETS testing protocols are extending qualification timelines for transatlantic vendors.
Strategic Opportunities
- Remote Tower Convergence:Integration of ILS monitoring with centralized digital tower platforms is opening service contract expansion at Scandinavian and Baltic airports.
- Military Sovereign Airfield Programs:Defense ministries in Poland, South Korea, and Australia are funding independent precision approach capability.
- Retrofit Digital Overlay Kits:Signal processing upgrades to existing antenna infrastructure offer margin recovery without full site reconstruction.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in VHF/UHF signal propagation and modulation analysis is concentrating among aging practitioner cohorts.
- Legacy System Interoperability:Hybrid architectures combining 1980s-era localizer foundations with modern monitor processors create fault-tree complexity.
- Extended Type Certification Cycles:ICAO Annex 10 signal integrity validation requires multi-season environmental testing at operational airports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrument Landing System (ILS) Market |
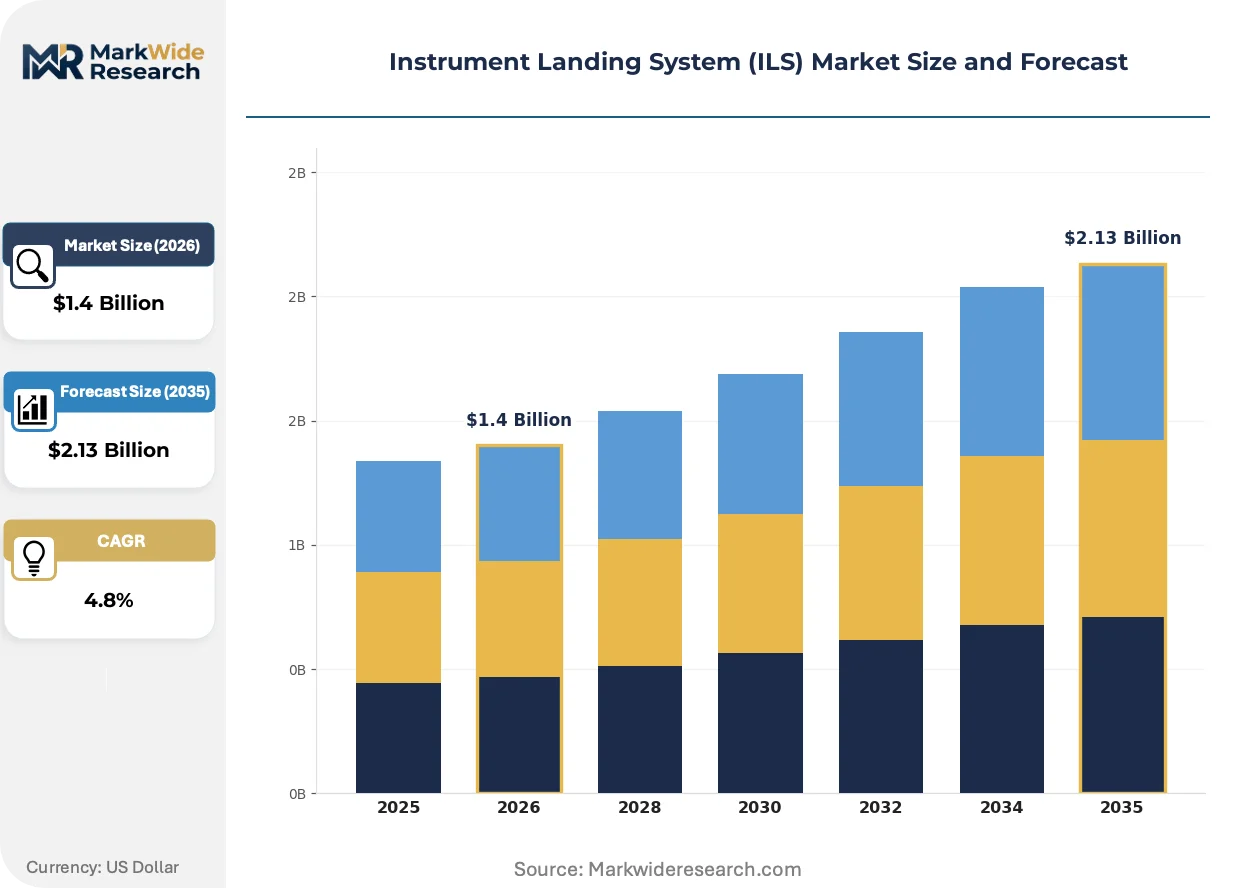
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: ILS Category I, ILS Category II, ILS Category III, ILS Category III Enhanced Application: Commercial Aviation, General Aviation, Military Aviation, Training End User: Airport Authorities, Airlines, Defense Forces, Private Operators Component: Localizer, Glide Slope, Marker Beacons, Control Equipment |
| Companies Covered | ATDI, ENGIE Ineo, Thales, IAVNA, FUCHS Europoles GFK GmbH, Indra, Cyrrus, Rohde & Schwarz, Leonardo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrument Landing System (ILS) Market Emerging Trajectories
Digital signal processing architectures are displacing analog RF chains, enabling software-defined reconfiguration of localizer beam patterns without hardware swaps. This shift is compressing upgrade cycles and unbundling hardware from service contracts.
Software-defined localizer transmitters are modularizing the traditional monolithic RF architecture into interchangeable digital exciter and amplifier blocks. Major hub operators in Germany and the United States are piloting these configurations for reduced spares inventory. The technology is modularizing vendor relationships, allowing airports to mix subsystem suppliers rather than sole-source procurement.
EASA's emerging provisions under the EU AI Act for autonomous landing system validation are tightening algorithmic transparency requirements for next-generation monitor processors. Manufacturers must now document decision logic for automatic switching between redundant signal paths. Category III system suppliers serving European airports are restructuring quality management systems to satisfy these audit protocols.
After-sales service unbundling is accelerating as airport authorities separate installation warranties from multi-decade maintenance agreements. Direct procurement of spare exciters and antenna elements through specialized RF distributors is displacing bundled OEM service contracts. This pattern is most visible at mid-tier US airports seeking to break vendor lock-in on legacy 1990s installations.
Instrument Landing System (ILS) Market Segmentation
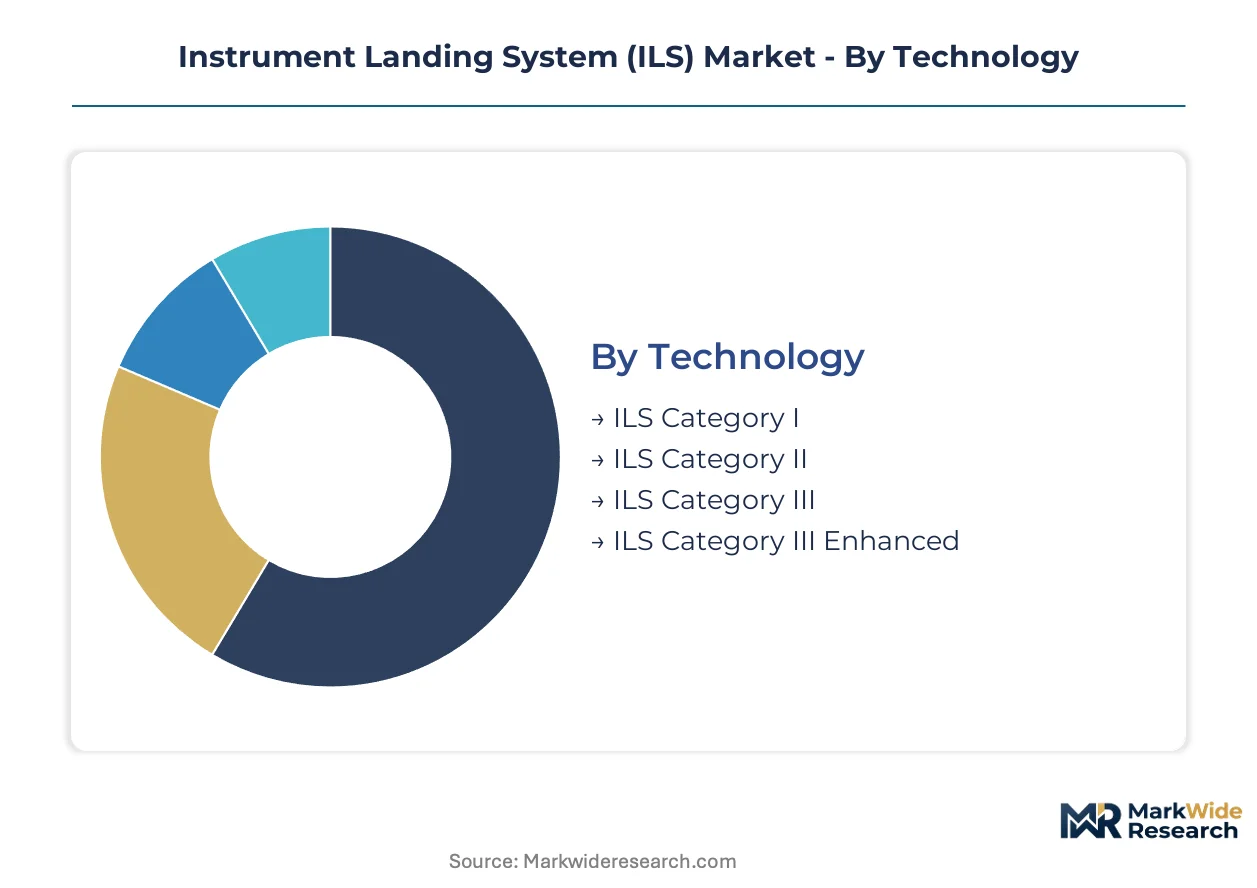
ILS procurement patterns diverge sharply across operational contexts, with certification tier and end-user risk tolerance dictating architecture complexity and vendor selection criteria. Understanding these segment boundaries clarifies where upgrade cycles concentrate versus where greenfield installations predominate.
Technology:
Capital intensity escalates dramatically with certification tier, as fail-safe redundancy requirements multiply component counts and site preparation costs.
- ILS Category I:Basic precision approach system supporting decision heights of 200 feet and runway visual range of 1,800 feet. Demand concentrates at regional airports in the United States and Germany undergoing FAA NextGen-aligned refreshes, constrained by GBAS substitution at new airfield developments.
- ILS Category II:Intermediate system permitting 100-foot decision heights and 1,200-foot runway visual range. Procurement clusters at secondary hubs in China expanding capacity without full Category III infrastructure commitment, driven by moderate traffic growth and capital budget limitations.
- ILS Category III:Fail-safe architecture enabling zero-decision-height operations through redundant localizer and glide slope arrays. Absorbs disproportionate engineering resources due to ICAO Annex 10 integrity validation requirements.
- ILS Category III Enhanced:Most stringent variant with additional monitor density and automatic switchover protocols. Deployed exclusively at primary European hubs under EASA CS-ETS certification pressure.
ILS Category I absorbs the bulk of installed capacity; ILS Category III Enhanced is expanding most quickly.
Application:
Operational tempo and regulatory exposure determine replacement urgency, with high-cycle environments demanding earlier technology refresh.
- Commercial Aviation:Scheduled passenger and cargo operations at certificated air carrier facilities. Dominates absolute demand at congested hubs in Germany, the United States, and China where legacy systems reach end-of-design-life simultaneously.
- Military Aviation:Sovereign airfield operations requiring independent precision approach capability independent of civilian infrastructure. Accelerating in Poland, South Korea, and Australia under defense ministry resilience programs.
- General Aviation:Non-scheduled private and business aircraft operations. Fragmented procurement across municipal airfields with limited capital reserves.
- Training:Flight school and simulator facility installations. Concentrated at specialized academies in Florida and Arizona with high approach repetition rates.
Commercial Aviation commands the dominant revenue share; Military Aviation is climbing the fastest.
End User:
Procurement autonomy and maintenance capability shape contract structures, distinguishing bundled long-term service from component-level purchasing.
- Airport Authorities:Municipal and regional airfield operators responsible for ground infrastructure. Drive bundled procurement combining ILS installation with airfield lighting and electrical work at runway construction sites.
- Defense Forces:National military establishments operating independent airfield networks. Prioritize sovereign supply chains and domestic maintenance training.
- Airlines:Commercial air carriers with proprietary ground infrastructure at hub bases. Limited direct procurement, concentrated at major network carriers with captive maintenance divisions.
- Private Operators:Corporate flight departments and fractional ownership programs. Minimal direct ILS procurement, typically relying on host airport infrastructure.
Airport Authorities manage the largest installed base; Defense Forces are gaining share fastest.
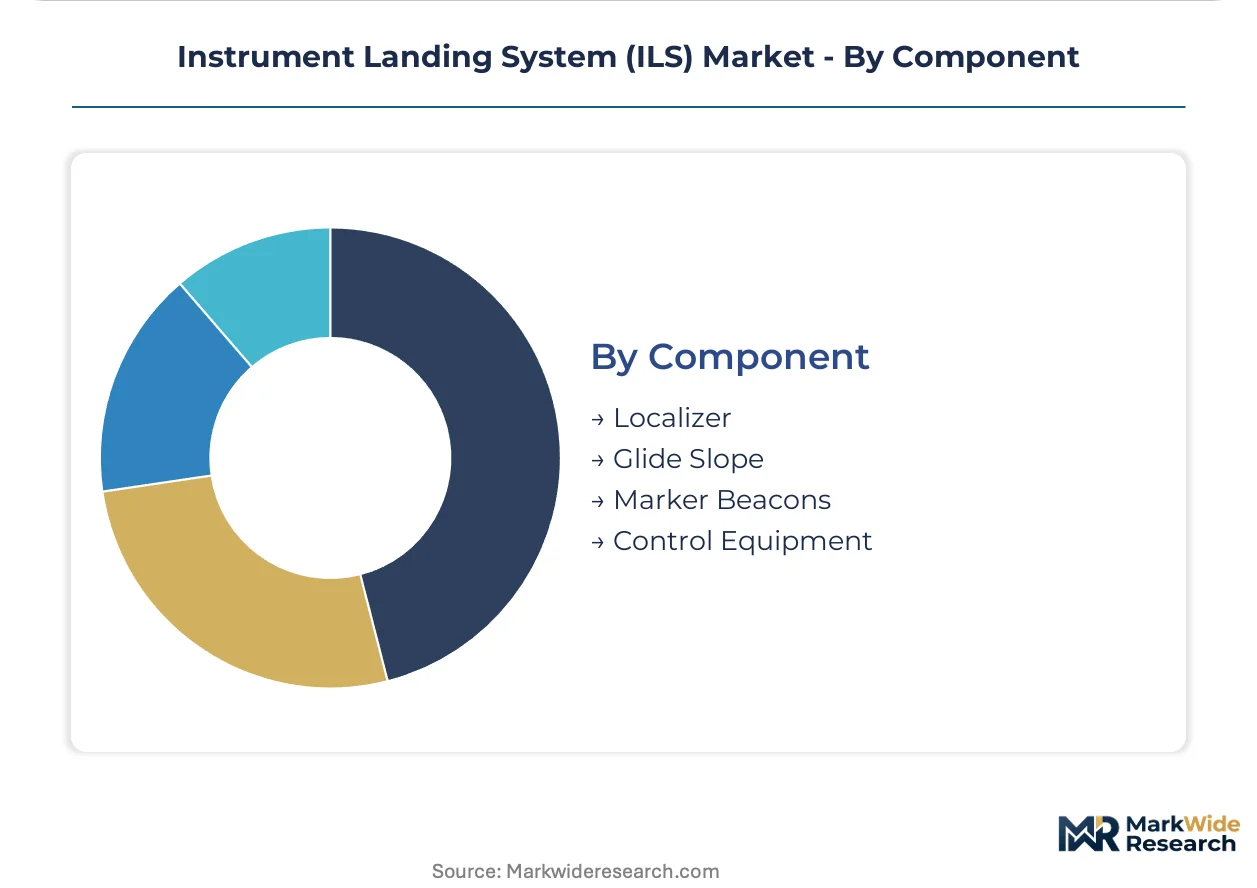
Component:
Subsystem replacement economics favor modular upgrades over full system reconstruction where antenna infrastructure remains serviceable.
- Localizer:VHF transmitter array establishing runway centerline guidance. Precision antenna configurations from German and United States suppliers concentrate margin pools.
- Glide Slope:UHF subsystem defining descent angle reference. Digital exciter retrofits displacing full antenna replacement at mid-tier United States airports.
- Marker Beacons:Distance reference transmitters at fixed approach points. Declining installation rates as GPS waypoint substitution advances.
- Control Equipment:Monitor processors and automatic switching logic. Software-defined architectures unbundling hardware from vendor service contracts.
Localizer arrays represent the most extensive installed footprint; Control Equipment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Airport anchors European ILS modernization activity, with simultaneous runway upgrades driving concentrated procurement across Germany's aviation infrastructure corridor.
United States
Chicago O'Hare and Atlanta Hartsfield-Jackson are executing synchronized Category III upgrades under FAA NextGen timelines. The FAA's 14 CFR Part 171 mandates are compressing vendor qualification windows. Dallas-Fort Worth International is bundling ILS procurement with airfield electrical reconstruction contracts.
Germany
Munich and Frankfurt hubs are deploying ILS Category III Enhanced systems under EASA CS-ETS certification pressure. The EU Green Deal's airport decarbonization benchmarks are redirecting capital toward energy-efficient glide slope architectures. Thales maintains integrated service contracts with major airport authorities across the Rhine-Main region.
China
Beijing Capital and Shanghai Pudong are expanding precision approach capacity to accommodate hub traffic density. The Civil Aviation Administration of China is aligning certification protocols with ICAO Annex 10 standards. Guangzhou Baiyun International is undertaking simultaneous runway construction bundling ILS installation with airfield lighting packages.
Poland
Warsaw Chopin Airport is modernizing legacy Soviet-era installations under defense ministry sovereign airfield resilience programs. The country's national aviation regulator is tightening signal integrity standards for NATO interoperability. Kraków John Paul II International is piloting digital localizer transmitter configurations.
Australia
Sydney Kingsford Smith and Melbourne Tullamarine are replacing end-of-design-life systems from the 1990s. The country's national aviation safety authority is harmonizing certification with ICAO Annex 10 amendments. Perth Airport is evaluating remote tower convergence for ILS monitoring integration.
Instrument Landing System (ILS) Market Vendor Landscape
The competitive structure tilts toward integrated system providers with long-term service capabilities. Vendor relationships concentrate around firms offering bundled installation and multi-decade maintenance agreements. Two strategic archetypes dominate: diversified aerospace-electronics conglomerates with air traffic management portfolios, and specialized RF engineering houses with precision antenna expertise. Competitive moves center on digital signal processing licensing and civil engineering-electrical integration partnerships for runway construction packages.
Among European integrated providers, Thales and ENGIE Ineo exemplify contrasting positioning archetypes. Thales leverages its air traffic management portfolio to anchor long-term service relationships with major airport authorities. ENGIE Ineo competes through civil engineering-electrical integration, securing runway construction packages that bundle ILS installation with airfield lighting. Rohde & Schwarz represents the specialized RF engineering tier, drawing on precision microwave subsystem expertise concentrated in German industrial clusters.
| Leading Market Players |
|---|
| ATDI |
| ENGIE Ineo |
| Thales |
| IAVNA |
| FUCHS Europoles GFK GmbH |
| Indra |
| Cyrrus |
| Rohde & Schwarz |
| Leonardo |
| Others |
Supply Flow & Price Mechanics
Digital signal processing architectures are compressing upgrade cycles and unbundling hardware from service contracts, simultaneously eroding legacy vendor pricing power and fragmenting procurement across specialized RF component suppliers. This technology shift redirects margin capture toward software-defined exciter manufacturers while concentrating antenna array production in established German and United States industrial clusters.
Pricing Analysis
Certification-tier anchoring governs contract values, with ILS Category III systems commanding substantial premiums over Category I installations due to fail-safe redundancy requirements and extended validation protocols. Price differentiation separates bundled installation-maintenance packages from component-only procurement, with airport authorities in Germany and the United States exhibiting highest sensitivity to unbundled spare part sourcing. Cost compression in Category I segments is intensifying because GBAS substitution threat limits greenfield demand, while Category III pricing holds firmer due to regulatory mandates from the FAA and EASA.
Supply Chain Analysis
Domestic-content mandates in Poland, South Korea, and Australia are reshaping sourcing patterns for military sovereign airfield programs, compelling vendors to establish local assembly partnerships or license production. Precision localizer antenna arrays draw from concentrated microwave subsystem suppliers in Germany and the United States, with specialized VHF/UHF signal propagation expertise resting on aging practitioner cohorts. Single-source vulnerability concentrates in precision RF component fabrication, while distribution runs through civil engineering-electrical integration contractors bundling ILS installation with runway construction packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with control over software-defined exciter technology and specialized RF engineering talent serving as the decisive upstream lever. Players are pursuing captive maintenance training capabilities and in-house signal processing development to defend margin position.
For Market Incumbents: Deepen software-defined architecture penetration to lock in long-term service contract renewal at major hub airports, while acquiring specialized RF engineering capabilities to counter talent scarcity. The GBAS substitution threat demands accelerated Category III certification investment to maintain relevance at primary hubs. Backward integration into precision antenna manufacturing secures supply continuity against German and United States supplier concentration. For New Entrants and Emerging Players: Digital exciter retrofit kits offer a technology-first wedge into mid-tier United States airports seeking to break vendor lock-in on legacy 1990s installations. Military sovereign airfield programs in Poland, Australia, and South Korea present the most penetrable white-space, with defense ministries prioritizing domestic maintenance training partnerships. A software-only go-to-market angle bypasses capital-intensive antenna manufacturing while capturing recurring monitor processor upgrade revenue. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified aerospace-electronics conglomerates seeking air traffic management portfolio expansion. Long-term viability hinges on software-defined reconfiguration capabilities and EASA CS-ETS certification access across the analysis window. Acquisition targets should display specialized RF engineering talent depth and established relationships with airport authorities in Germany or the United States. The signal to monitor is divergence between FAA NextGen and SESAR deployment timelines, which would strain dual-certification capabilities and favor regionally focused vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Exciter Development | Enables modular procurement unbundling hardware from vendor service contracts at United States mid-tier airports. |
| Dual Certification Investment | Satisfies simultaneous FAA Part 171 and EASA CS-ETS requirements for transatlantic vendor qualification. |
| Military Sovereign Airfield Partnership | Captures defense ministry resilience funding in Poland, South Korea, and Australia with domestic content compliance. |
| RF Engineering Talent Acquisition | Secures scarce VHF/UHF signal propagation expertise concentrated among aging practitioner cohorts in Germany. |
| Remote Tower Integration | Opens service contract expansion at Scandinavian and Baltic airports through centralized ILS monitoring platforms. |
Methodological Framework
Multi-period observation of ILS installation cycles, certification protocol amendments, and vendor contract structures anchored the trend analysis, supplemented by interviews with airport authority engineering directors, air traffic management procurement officers, defense ministry aviation program managers, RF subsystem manufacturing executives, and civil engineering-electrical integration contractors. Secondary validation drew from FAA 14 CFR Part 171 filings, EASA CS-ETS certification databases, ICAO Annex 10 amendment records, and airport capital expenditure disclosures. Bottom-up procurement tracking across Germany, the United States, China, Poland, and Australia was triangulated against top-down market sizing from infrastructure investment flows.
Segment-weighting approaches applied differential growth assumptions across certification tiers, with ILS Category III systems assigned higher expansion coefficients reflecting FAA NextGen and EASA CS-ETS mandate intensity. The analytical framework modeled technology substitution effects, end-user procurement autonomy variations, and component-level replacement economics throughout the forecast period. CAGRs were derived from runway construction pipeline analysis, legacy system age distribution, and regulatory deadline clustering. Industry-specific inputs included GBAS displacement rates at greenfield developments and military sovereign airfield program budget allocations.
Several conditions sit outside the modeled scope, including unannounced regulatory deadline extensions, breakthrough autonomous landing technologies bypassing ground-based infrastructure entirely, and geopolitical disruptions to German or United States RF component supply. Forecasts reflect assumptions regarding synchronized replacement cycle execution and sustained defense ministry resilience funding. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market