
 Oil & Gas Lubricants Market | 2026-2036
Oil & Gas Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Oil & Gas Lubricants Market Insights
The EU Green Deal's F-Gas Regulation is realigning lubricant specifications for offshore refrigeration and gas compression systems in European waters. Shell plc leverages its PAO manufacturing network in the Netherlands to supply extended-drain formulations for floating production units. Exxon Mobil Corporation anchors its North Sea position through direct technical service contracts with drilling contractors requiring low-toxicity hydraulic fluids. TotalEnergies SE differentiates via biodegradable ester base stocks certified for sensitive marine environments.
Oil and gas lubricants are formulated mixtures of base oils and functional additives engineered to reduce friction, dissipate heat, and prevent corrosion in hydrocarbon extraction and processing equipment, with viscosities typically ranging from ISO VG 32 to 680 for industrial applications and pour points below minus thirty degrees Celsius for arctic service. Their primary purpose is ensuring mechanical reliability across drilling rigs, pipelines, and refineries operating under high pressure, temperature extremes, and saline contamination. Synthetic lubricants command premium positioning due to extended drain intervals and thermal stability in deepwater wellheads, while mineral oil formulations retain volume leadership in onshore conventional production where cost sensitivity dominates procurement decisions. Engine oils for gas compression represent a concentrated margin pool as power-generation specifications tighten across European offshore platforms.
OSPAR conventions, REACH registration requirements, and EU MDR-equivalent offshore equipment directives collectively mandate reduced environmental toxicity and full chemical disclosure for lubricants discharged in marine environments. Norway's Petroleum Safety Authority enforces additional national standards for subsea equipment fluids that exceed baseline EU requirements. Buyers must monitor regulatory divergence between EU-wide frameworks and emerging national standards in prospective licensing rounds.
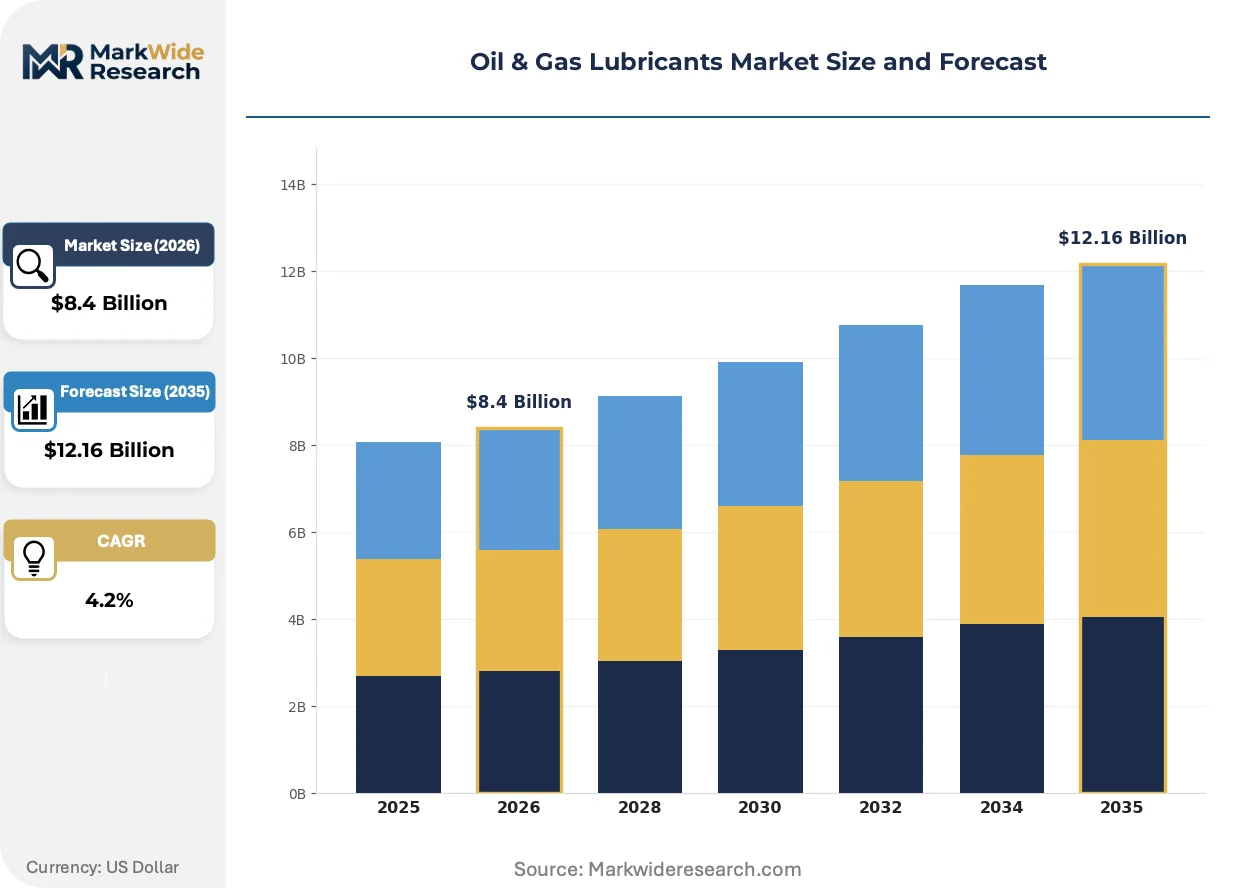
Market Dynamics
OSPAR discharge limits are compressing mineral oil market share across North Atlantic offshore operations, forcing contractors to absorb synthetic lubricant premiums or face operational suspension in Norwegian and UK waters.
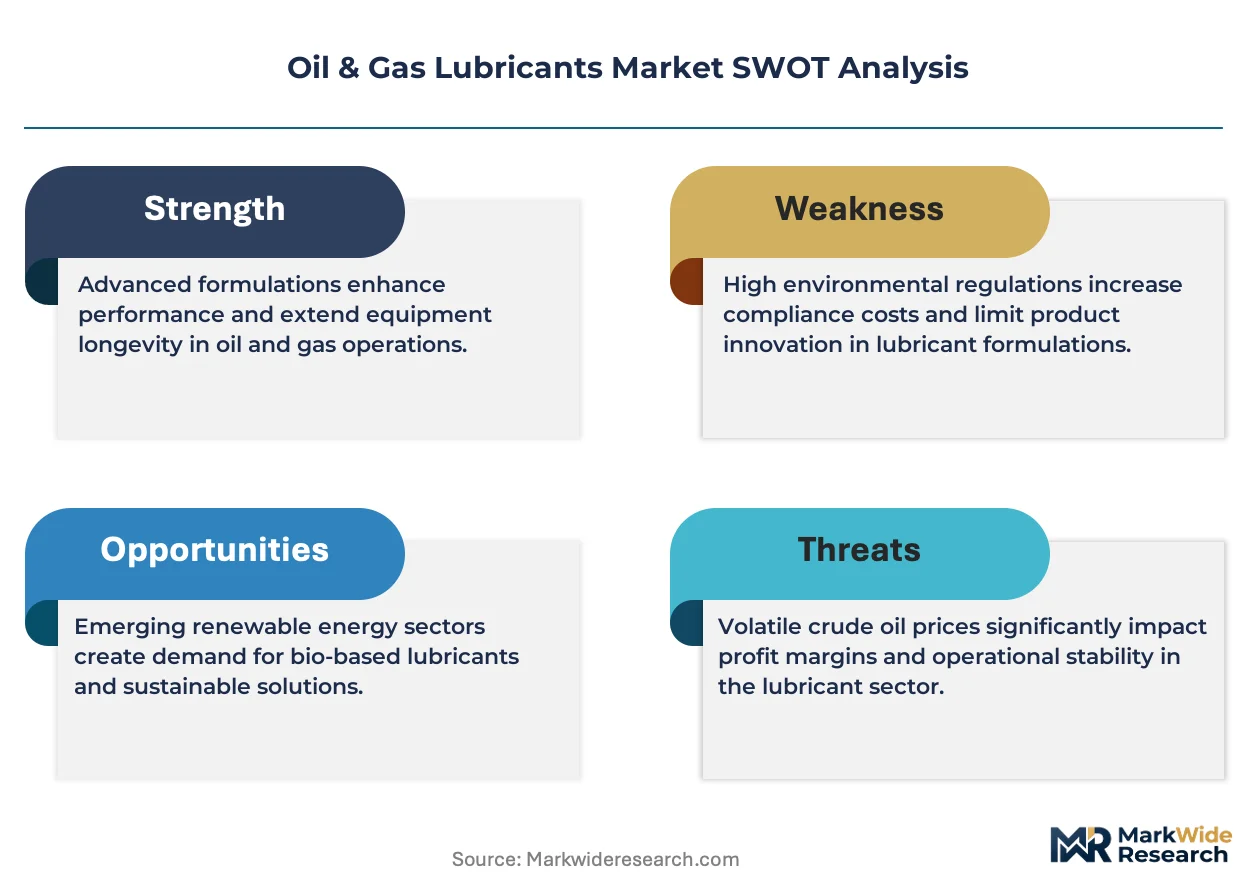
Growth Catalysts
- OSPAR Convention stringency:Tighter environmental discharge thresholds in the North Sea are mandating synthetic and biodegradable formulations for subsea equipment, eliminating lower-cost mineral alternatives from contractor procurement lists.
- Deepwater wellhead complexity:Extended-reach drilling in the Norwegian Continental Shelf demands PAO-based hydraulic fluids with thermal stability beyond 150°C, creating specification premiums that compound through supply chains.
- Arctic service expansion:Pour point requirements below minus forty degrees Celsius for Barents Sea operations are accelerating demand for synthetic base stocks in Norwegian and Russian Far East licensing rounds.
Market Restraints
- Base oil supply concentration:Polyalphaolefin feedstock production clusters in Rotterdam and Houston, exposing European offshore contractors to freight cost volatility and currency fluctuation risks.
- REACH registration burdens:Full chemical disclosure requirements for lubricant additives are extending product development timelines by eighteen to twenty-four months for new formulations entering EU waters.
- Mineral oil price anchoring:Onshore conventional production in the Permian Basin and Middle East continues procuring Group I and Group II base stocks, creating a price floor that compresses synthetic margins in cost-sensitive segments.
Strategic Opportunities
- Carbon capture compression:Post-combustion CO2 handling systems require specialized lubricants compatible with supercritical gas phases, opening formulation development for equipment OEMs and oil majors diversifying into emissions reduction infrastructure.
- Biodegradable ester certification:EU Green Deal procurement preferences for marine-sensitive operations are creating tiered specification pathways that reward early movers with multi-year technical service contracts.
- Remote monitoring integration:IoT-enabled condition monitoring of subsea compressor lubricant degradation is enabling predictive drain interval extension, converting product sales into subscription-based fluid management services.
Industry Challenges
- Tribology specialization scarcity:Formulation chemists with combined expertise in high-pressure rheology and marine toxicity testing are concentrated among a handful of European technical centers, constraining R&D throughput for mid-tier suppliers.
- Subsea equipment qualification timelines:Norwegian Petroleum Safety Authority certification for new lubricant chemistries in blowout preventer systems requires twelve to eighteen months of field validation, delaying commercialization of next-generation formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil & Gas Lubricants Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Lubricants, Biodegradable Lubricants, Additives Application: Drilling, Hydraulic Systems, Gear Oils, Engine Oils End User: Exploration Companies, Production Firms, Service Providers, Refineries Distribution Channel: Direct Sales, Dealers, Retail, E-Commerce |
| Companies Covered | Shell plc, Exxon Mobil Corporation, Chevron Corporation, BP p.l.c., TotalEnergies SE, PetroChina Company Limited, LUKOIL, Phillips 66, Eni S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil & Gas Lubricants Market Trends and Innovations
Digital fluid condition monitoring is converging with synthetic chemistry advances to redefine how offshore operators manage lubricant lifecycle costs and regulatory compliance in parallel.
Polyalphaolefin-ester hybrid base stocks are electrifying thermal performance benchmarks for subsea gas compression. Operators on Norway's Johan Sverdrup field are specifying these formulations for twenty-thousand-hour drain intervals, compressing maintenance vessel deployment frequency and associated carbon emissions from offshore logistics. The technology is electrifying competitive differentiation among suppliers capable of blending PAO with biodegradable esters without viscosity index degradation.
EU F-Gas Regulation phase-down schedules are forcing refrigeration lubricant reformulation across North Sea floating production units. Hydrofluorocarbon restrictions are mandating compatibility testing with lower-global-warming-potential refrigerants, compressing product qualification windows for incumbent suppliers. UK and Norwegian platform operators are responding by consolidating procurement around lubricant portfolios with pre-certified HFO and natural refrigerant compatibility.
Integrated fluid management contracts are displacing spot procurement for major drilling contractors. Technical service agreements bundling lubricant supply, condition monitoring, and waste fluid recovery are capturing preference among North Sea drillship operators seeking to transfer environmental liability to suppliers. This model is most visible in Norwegian sector contracts where OSPAR compliance documentation requirements favor single-source accountability over multi-vendor fragmentation.
Oil & Gas Lubricants Market Segmentation
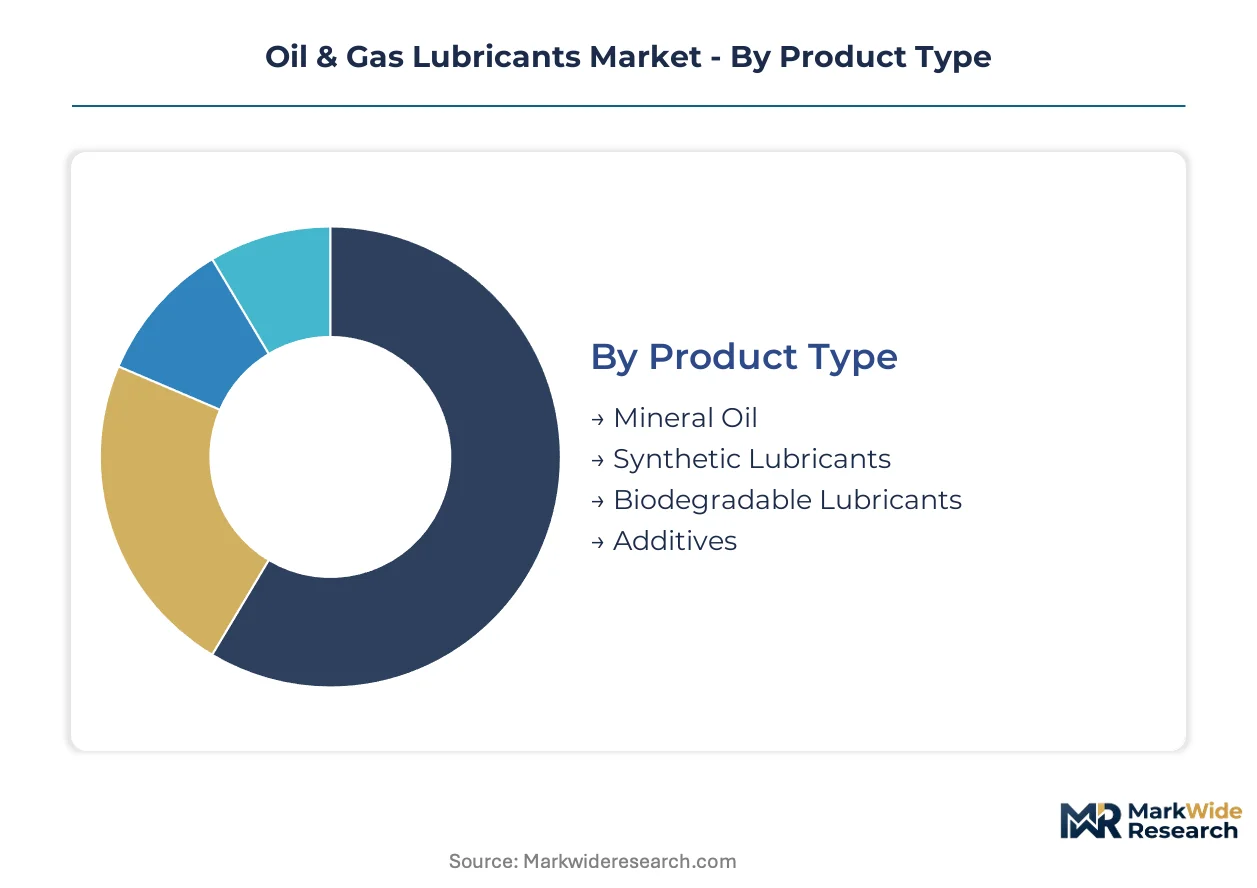
Segmentation in the Oil & Gas Lubricants Market reveals how regulatory burden and application severity fragment procurement patterns across the value chain. Each dimension carries distinct certification requirements that reshape supplier economics and buyer decision frameworks.
Product Type:
REACH registration and OSPAR discharge certification create tiered compliance burdens that separate premium synthetic formulations from commodity mineral alternatives in European waters.
- Mineral Oil:Group I and Group II base stocks dominate onshore conventional production where cost sensitivity outweighs thermal performance requirements. Procurement concentrates in Permian Basin and Middle East operations where discharge regulations remain less stringent than North Sea standards.
- Synthetic Lubricants:Polyalphaolefin and polyalkylene glycol formulations command specification premiums for subsea compressors and extended-reach drilling. Demand clusters in Norwegian Continental Shelf fields where Equinor's Johan Sverdrup standards cascade through contractor procurement lists.
- Biodegradable Lubricants:Ester base stocks certified for sensitive marine environments under EU Green Deal procurement preferences.
- Additives:Functional chemistry packages requiring eighteen-to-twenty-four-month REACH disclosure timelines for new formulations.
Leading the category by volume: Mineral Oil. Expanding most quickly: Synthetic Lubricants.
Application:
Equipment criticality and operating environment severity determine lubricant specification tiers across upstream and midstream operations.
- Drilling:Mud pump and top drive systems demand high-pressure, high-temperature formulations with contamination tolerance for saline and solids ingress. Norwegian and UK offshore contractors are consolidating procurement around synthetic-based drilling fluids to meet OSPAR discharge thresholds.
- Hydraulic Systems:Blowout preventer and subsea control systems require fire-resistant, low-toxicity fluids with pour points below minus forty degrees Celsius for Barents Sea service. Norwegian Petroleum Safety Authority certification timelines of twelve to eighteen months constrain supplier entry.
- Gear Oils:Wind turbine and platform crane drivetrains specify EP-additive packages for boundary lubrication conditions.
- Engine Oils:Gas compression and power generation applications face tightening emissions specifications across European offshore platforms.
Drilling commands the largest volume share. Hydraulic Systems faces the steepest specification escalation.
End User:
Procurement sophistication and technical service requirements diverge sharply between integrated majors and fragmented service contractors.
- Exploration Companies:Wildcat drilling operators prioritize spot procurement flexibility and rapid specification switching across frontier basins. Cost discipline dominates over long-term technical service relationships in emerging licensing rounds.
- Production Firms:Mature field operators with stable asset bases favor integrated fluid management contracts bundling supply, monitoring, and waste recovery. Norwegian sector contracts show strongest preference for single-source accountability to transfer environmental liability.
- Service Providers:Drilling contractors and completion specialists face compressed margins that limit synthetic lubricant uptake despite regulatory pressure.
- Refineries:Downstream process units require specialized turbine and compressor oils with thermal stability beyond 150°C.
Production Firms generate the highest revenue per barrel equivalent. Service Providers represent the most price-elastic demand segment.
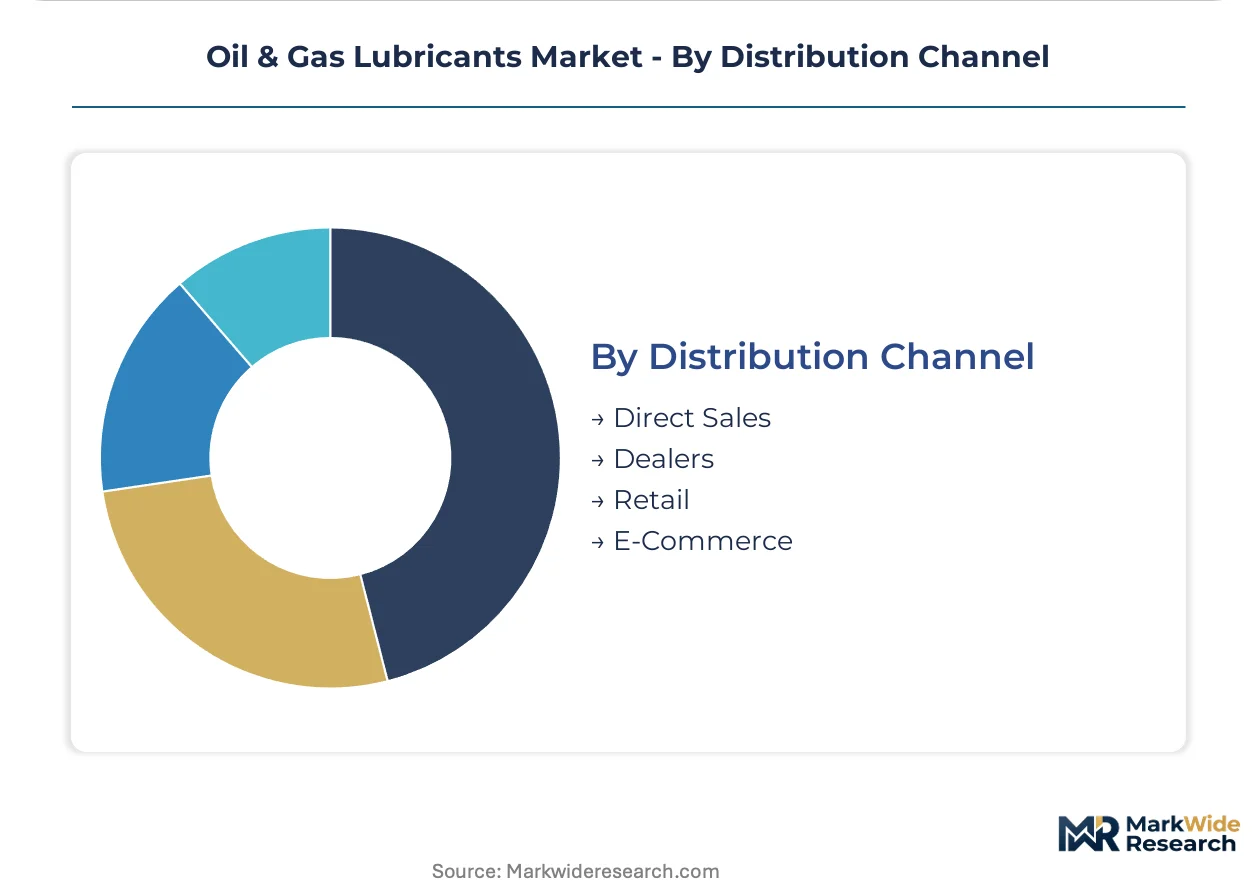
Distribution Channel:
Channel selection tracks operational scale, geographic concentration, and inventory carrying cost tolerance across the customer base.
- Direct Sales:Technical service agreements with major operators and drilling contractors capture preference in Norwegian and UK offshore sectors. Shell and Exxon Mobil anchor positions through direct technical service contracts requiring low-toxicity hydraulic fluids and extended-drain PAO formulations.
- Dealers:Regional distributors serve mid-tier exploration companies and onshore conventional producers with standardized product portfolios and local inventory availability.
- Retail:Spot procurement for maintenance, repair, and operations supplies in remote field locations.
- E-Commerce:Emerging channel for consumables and standard grades with predictable specifications and lower technical service content.
Direct Sales dominates value capture. E-Commerce shows fastest penetration in onshore North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of synthetic base stocks clusters in the Netherlands and Belgium, while consumption concentrates in Norwegian offshore fields and US shale basins. This geographic split creates freight exposure for North Sea contractors and margin compression for Permian operators. Rotterdam's PAO manufacturing hub supplies extended-drain formulations across European waters.
Norway
Equinor's Johan Sverdrup field specifications cascade through North Atlantic supply chains, mandating PAO-based hydraulic fluids for subsea compressors. The Petroleum Safety Authority enforces twelve-to-eighteen-month certification timelines for blowout preventer lubricants. Bergen and Stavanger anchor technical service networks serving the Norwegian Continental Shelf's extended-reach drilling campaigns.
United States
Permian Basin conventional production sustains Group I and Group II mineral oil procurement despite synthetic advances in offshore markets. EPA discharge regulations for onshore operations remain less stringent than OSPAR thresholds, preserving cost-driven procurement patterns. Houston hosts polyalphaolefin feedstock production serving both domestic shale and export markets.
United Kingdom
North Sea decommissioning schedules are compressing lubricant demand volumes even as specification stringency rises under post-Brexit environmental frameworks. OSPAR conventions continue binding UK offshore operators to synthetic and biodegradable formulations. Aberdeen maintains its position as the primary logistics hub for drilling contractor procurement across the UK sector.
Germany
Industrial gear oil demand from Ruhr Valley manufacturing clusters supports mid-tier lubricant blending capacity. REACH registration requirements for additive packages extend product development timelines for formulations entering German industrial markets. Hamburg's port infrastructure handles base oil imports supplying Central European refineries and blenders.
China
State-controlled oil majors are consolidating domestic lubricant procurement around captive supply chains for offshore drilling in the South China Sea. MIIT standards for equipment reliability are tightening compressor oil specifications for gas transmission infrastructure. Shanghai and Tianjin host blending facilities serving both domestic upstream operations and export markets.
Oil & Gas Lubricants Market Competitive Landscape
The competitive structure tilts toward integrated energy majors with captive base oil production and technical service networks. Market concentration is pronounced in North Sea offshore sectors where direct supply agreements bundle lubricant provision with condition monitoring and waste recovery. Three archetypes dominate: vertically integrated oil majors controlling PAO manufacturing, specialized lubricant blenders serving cost-sensitive onshore segments, and regional state enterprises with protected domestic markets. Capacity expansion in synthetic base stocks and strategic partnerships for biodegradable ester certification represent the primary competitive vectors.
Among the integrated majors, Shell plc anchors its position through Rotterdam-based PAO manufacturing and direct technical service contracts with floating production operators. Exxon Mobil Corporation exemplifies the technical-service-driven archetype through low-toxicity hydraulic fluid specifications for North Sea drilling contractors. TotalEnergies SE occupies a differentiated position via biodegradable ester base stocks certified for sensitive marine environments under EU Green Deal frameworks.
| Leading Market Players |
|---|
| Shell plc |
| Exxon Mobil Corporation |
| Chevron Corporation |
| BP p.l.c. |
| TotalEnergies SE |
| PetroChina Company Limited |
| LUKOIL |
| Phillips 66 |
| Eni S.p.A |
| Others |
Pricing and Supply Chain Analysis
PAO-mineral bifurcation in offshore procurement creates divergent margin structures that reshape supplier economics across the North Atlantic. Synthetic formulations certified for OSPAR compliance command technical service premiums that commodity mineral suppliers cannot replicate, while Rotterdam base oil concentration forces freight absorption into contract pricing for Norwegian contractors.
Pricing Analysis
Margin tightening in mineral oil tiers reflects Permian Basin cost discipline that anchors spot procurement floors. Three-tier pricing structure across premium synthetic, mid-grade PAO blends, and economy mineral separates buyers by certification burden and drain interval requirements. Price differentiation hinges on REACH disclosure completeness and Norwegian Petroleum Safety Authority validation timelines. Service providers exhibit highest price elasticity as compressed drilling margins limit synthetic uptake despite regulatory pressure.
Supply Chain Analysis
Direct-to-operator channels handle Norwegian and UK offshore demand through technical service agreements bundling supply with condition monitoring. Polyalphaolefin feedstock production clusters in the Netherlands, Belgium, and Houston, exposing European contractors to currency fluctuation and freight cost volatility. Formulation chemistry draws from ethylene oligomerization, catalyst packages, and ester base stocks. Single-source vulnerability concentrates in Rotterdam PAO manufacturing. Distribution runs through Aberdeen and Stavanger logistics hubs serving North Sea platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSPAR stringency and REACH registration burdens are consolidating supplier tiers as mid-tier blenders exit unprofitable offshore segments. Technical service capability and certification timelines now determine survival.
For Market Incumbents: Lock in multi-year integrated fluid management contracts with Norwegian production firms to transfer environmental liability and block challenger access. Secure backward integration into PAO manufacturing or ester base stock partnerships to defend margin position against Rotterdam supply volatility. Prioritize IoT-enabled condition monitoring subscriptions that convert product sales into recurring revenue streams resistant to spot price pressure. For New Entrants and Emerging Players: E-commerce channels for standardized mineral grades offer lowest barrier entry in Permian Basin onshore markets where technical service requirements remain minimal. Target biodegradable ester certification for EU Green Deal procurement preferences in marine-sensitive operations as the most penetrable white-space. Pursue carbon capture compression lubricant development for equipment OEMs diversifying into emissions reduction infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated majors seeking PAO manufacturing capacity and Norwegian technical service networks. Long-term viability favors suppliers with captive base oil production and validated subsea equipment qualifications. Watch for divergence between EU-wide REACH frameworks and emerging national standards in prospective licensing rounds as the critical inflection signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAO Manufacturing | Shell's Rotterdam network demonstrates how captive base oil production secures margin control against feedstock volatility. |
| Biodegradable Ester Certification | EU Green Deal procurement preferences reward early movers with multi-year technical service contracts in marine-sensitive operations. |
| IoT-Enabled Condition Monitoring | Predictive drain interval extension converts product sales into subscription-based fluid management services with recurring revenue. |
| Long-term Supply Agreement with Drilling Contractors | Integrated contracts bundling lubricant provision with waste recovery transfer environmental liability and capture single-source preference. |
| Carbon Capture Compression Formulation Development | Post-combustion CO2 handling systems require specialized lubricants compatible with supercritical gas phases. |
Research Methodology
Document review covered OSPAR convention amendments, REACH registration databases, and Norwegian Petroleum Safety Authority directives, complemented by interviews with lubricant formulation chemists, offshore drilling procurement managers, and base oil trading specialists. Secondary sources included customs trade data, SEC filings from integrated energy majors, and industry association reports from ACEA and ATIEL. Bottom-up segment sizing triangulated against top-down energy production forecasts across the analysis window.
Cross-referencing historical procurement patterns with expert panel input anchored volume projections. Segmentation modeling spanned product type tiers, application severity classes, end-user procurement sophistication levels, and regional regulatory clusters. CAGRs derived from elasticity-adjusted demand curves incorporating synthetic substitution rates and certification timeline delays. Forecast inputs included Barents Sea licensing round schedules and EU F-Gas Regulation phase-down compliance deadlines.
The model holds under stable OSPAR enforcement and REACH disclosure timelines; deviation in national standard divergence or base oil supply disruption would shift synthetic adoption curves. Forecasts reflect documented assumptions about regulatory stringency and offshore capital expenditure continuity. Periodic stress-testing of base assumptions against Norwegian field development announcements and Rotterdam capacity utilization is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Canada Bunker Fuel Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Gas Pooling Mechanism Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Europe Firewood Market
Fuels
Marine Fuel Optimization Market
Fuels
Compressed Natural Gas Market
Fuels
Fuel Oil Market
Fuels
Global Fuel Ethanol Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Solid Recovered Fuel Market