
 Chafing Fuel Market | 2026-2036
Chafing Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Chafing Fuel Market Outlook
A shift from single-source to multi-source raw material procurement is broadening supply resilience among established manufacturers. Sterno Products leverages captive production of ethanol-based formulations to sustain margin stability across North American foodservice channels. G.S. Industries anchors its position through vertical integration into metal canister fabrication, controlling packaging cost volatility. Yangzhou Zhongtian Tourist Products competes on manufacturing scale, operating dedicated facilities for export-oriented gel fuel output.
Chafing fuel denotes a portable combustion medium, typically formulated from ethanol, methanol, or diethylene glycol, engineered to maintain food temperatures between 140°F and 180°F through controlled flame output in stainless steel or aluminum canisters. The product serves commercial food warming applications where electrical heating proves impractical. Gel formulations dominate current volume owing to spill resistance and extended burn duration, while liquid variants capture faster growth in high-throughput catering environments where rapid ignition and adjustable heat output command premium positioning. Application segmentation shows restaurants and institutional buffets as mature demand pools, with outdoor events representing the fastest-expanding use case driven by mobile foodservice proliferation.
FDA oversight of indoor air quality standards and EPA volatile organic compound regulations constrain formulation chemistry and labeling requirements across the United States, while REACH compliance in Europe mandates detailed substance disclosure for methanol-containing products. China's GB standards and SAMR product safety certifications shape export eligibility for Asian manufacturers supplying international hospitality chains. Stakeholders must monitor evolving combustion emission thresholds and bio-based feedstock qualification criteria to align product portfolios with tightening regulatory trajectories.
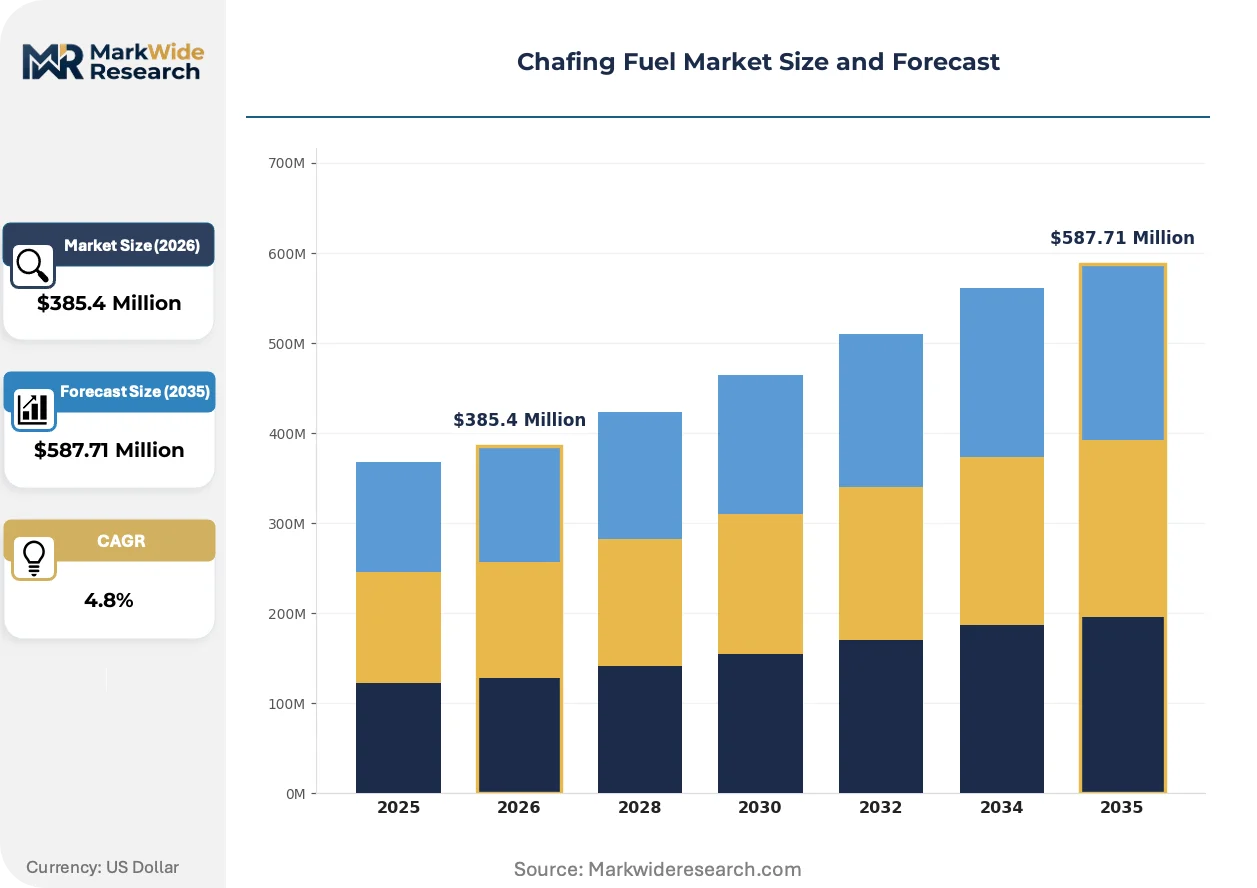
Market Dynamics
Formulation chemistry constraints from the EPA and FDA are compressing product development cycles while forcing manufacturers to requalify ethanol and methanol blends for indoor air quality compliance. This regulatory pressure sits atop volatile feedstock costs and shifting procurement patterns across foodservice distributors.
Growth Catalysts
- Outdoor event catering expansion:Mobile foodservice operations at festivals, weddings, and corporate gatherings are absorbing higher volumes of quick-ignition liquid chafing fuel variants.
- REACH substance disclosure mandates:European hospitality chains now require detailed methanol content documentation, favoring suppliers with pre-certified formulation libraries.
- Bio-based ethanol qualification:USDA bio-preferred procurement standards for federal foodservice contracts are opening dedicated supply channels for renewable feedstock-derived fuels.
Market Restraints
- Feedstock cost volatility:Corn and sugarcane ethanol prices fluctuate with agricultural commodity cycles, squeezing margin stability for non-integrated blenders.
- Canister supply concentration:Aluminum sheet and drawn-steel canister fabrication clusters in specific manufacturing zones create single-source vulnerability for mid-size fuel packagers.
- Electric warming substitution:Induction warming stations and cordless heated serving bases are capturing share in fixed-installation buffet environments where power access permits.
Strategic Opportunities
- India hospitality infrastructure buildout:Hotel and banquet hall construction in tier-2 and tier-3 cities under FSSAI food safety standards is creating first-time demand for compliant chafing fuel distribution.
- E-commerce direct procurement:Amazon Business and specialized foodservice platforms are enabling smaller caterers to bypass traditional distributor markups on bulk fuel purchases.
- GB standard export alignment:Chinese manufacturers certifying to SAMR product safety and GB combustion emission benchmarks are unlocking chain procurement approvals across Southeast Asian markets.
Industry Challenges
- Combustion chemist talent scarcity:Formulation expertise spanning volatile organic compound compliance and burn-rate engineering is concentrated among a narrow cohort of specialty chemical professionals.
- Multi-jurisdiction labeling complexity:Simultaneous FDA, EPA, REACH, and GB standard compliance requires parallel packaging runs and inventory segmentation, elevating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chafing Fuel Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Liquid, Solid, Canisters Application: Catering, Buffets, Outdoor Events, Restaurants End User: Foodservice Providers, Event Planners, Hotels, Home Users Packaging Type: Pouches, Tins, Jars, Bottles |
| Companies Covered | Chef Link, G.S. Industries, Sterno Products, Yangzhou Zhongtian Tourist Products, Scientific Utility, BLAZE, Hollowick, CiboWares, Lumea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chafing Fuel Market Strategic Shifts
Automation of quality assurance and precision blending is compressing batch-to-batch variation while enabling real-time emission monitoring. These advances intersect with tightening combustion chemistry standards and direct-to-caterer distribution channels.
Closed-loop ethanol blending systems with inline spectroscopic verification are automating quality control across high-volume production lines. Large contract foodservice distributors are adopting these systems to guarantee burn-duration consistency for chain account specifications. The technology is automating the elimination of manual sampling protocols that previously delayed shipment release by 24-48 hours.
REACH Annex XVII restrictions on methanol concentration in consumer products are forcing reformulation of legacy gel fuels across European Union member states. Manufacturers must now substitute diethylene glycol or higher-purity ethanol bases to maintain shelf stability and flame characteristics. Institutional caterers in Germany and France are absorbing modest price premiums for compliant formulations to avoid supply interruption.
Caterers are consolidating purchases through integrated foodservice platforms that bundle chafing fuel with disposable serviceware and equipment rentals. This pattern displaces standalone fuel distributors who lack adjacent product breadth. The shift is most pronounced in United States metropolitan markets where third-party event logistics coordinators manage procurement for corporate clients.
Chafing Fuel Market Segmentation
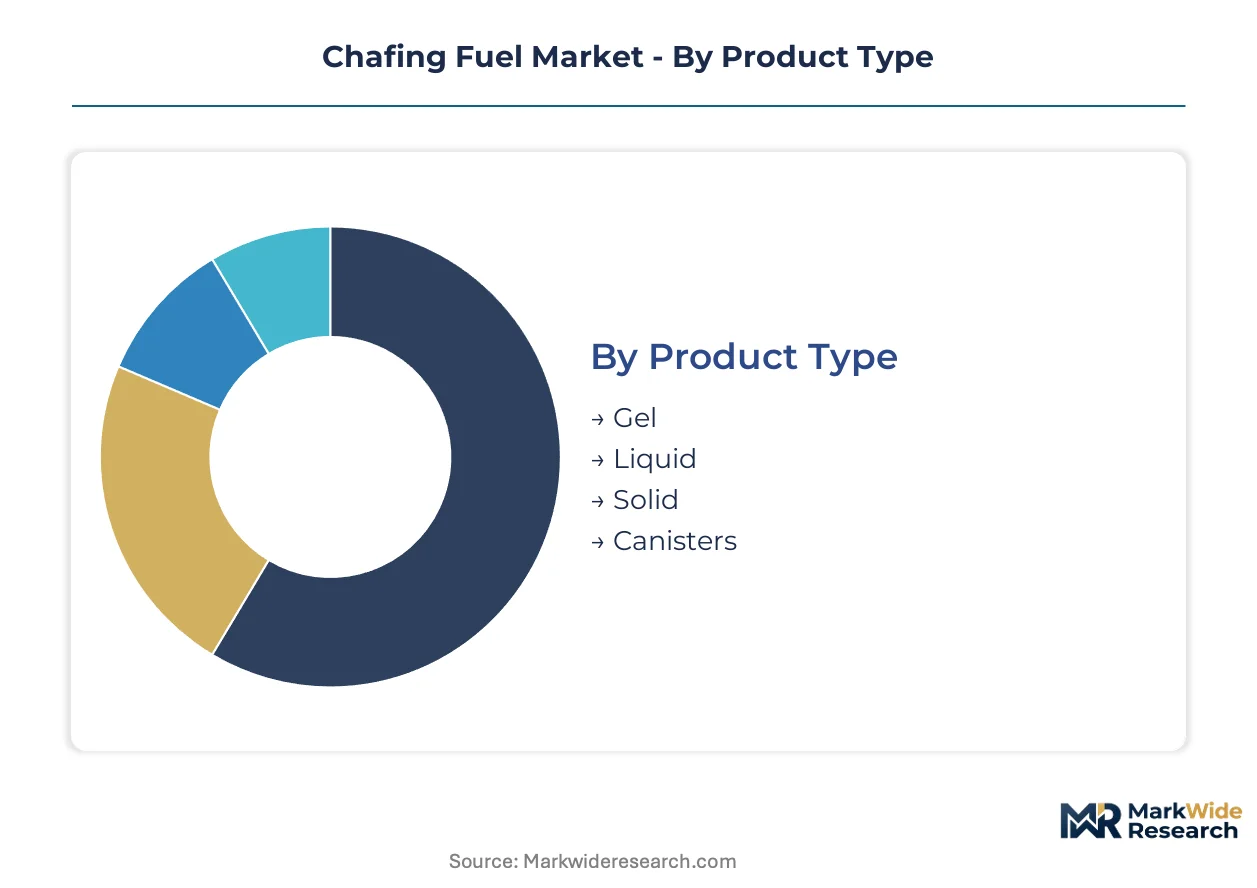
Chafing fuel manufacturers must align formulation chemistry with jurisdiction-specific combustion standards. Segmentation choices directly determine which FDA, EPA, REACH, or GB compliance pathways apply.
Product Type:
FDA indoor air quality thresholds and EPA volatile organic compound limits apply differentially across formulation states, with gel and liquid variants facing distinct testing protocols.
- Gel:Viscous ethanol or diethylene glycol suspensions with thickening agents provide spill resistance and controlled burn rates. Hotel banquet operations in the United States absorb the majority of volume, driven by insurance liability requirements for open-flame service. Leading the category by volume: Gel. Growing fastest: Liquid.
- Liquid:Lower-viscosity ethanol or methanol solutions enable rapid ignition and adjustable heat output through wick mechanisms. High-throughput catering environments in Germany favor this format for quick turnaround between service periods.
- Solid:Compressed fuel tablets with paraffin or urea-formaldehyde bases offer extended shelf stability for emergency preparedness kits.
- Canisters:Pre-filled disposable containers with integrated wick systems simplify procurement for small-scale event operators.
Margin compression is sharpest in solid formats where commodity paraffin pricing dominates cost structure.
Application:
Catering segment procurement concentrates through integrated foodservice platforms, while outdoor events fragment across direct e-commerce channels.
- Catering:Mobile foodservice operations at weddings and corporate functions require quick-ignition formats with consistent burn duration. United States metropolitan markets show strongest demand concentration through third-party event logistics coordinators.
- Buffets:Fixed-installation warming stations in hotels and institutional dining facilities absorb steady volumes of gel formulations. France and Germany enforce REACH Annex XVII methanol disclosure mandates that filter supplier eligibility.
- Outdoor Events:Festival and stadium foodservice operations favor wind-resistant liquid variants with adjustable flame control.
- Restaurants:Full-service dining establishments with tableside presentation needs prioritize odorless ethanol bases for guest experience.
Outdoor events climb fastest as mobile foodservice proliferates; buffets hold the installed base.
End User:
Procurement scale and compliance documentation requirements separate institutional buyers from consumer segments.
- Foodservice Providers:Contract catering companies with multi-site operations mandate batch-traceable formulations with EPA emission certification. USDA bio-preferred procurement standards open dedicated supply channels for federal contracts.
- Event Planners:Independent coordinators source through Amazon Business and specialized platforms, bypassing traditional distributor markups. China-based manufacturers with SAMR product safety certification capture this price-sensitive tier.
- Hotels:Global hospitality chains enforce unified formulation standards across properties, favoring suppliers with multi-jurisdiction labeling capabilities.
- Home Users:Small-volume purchasers through retail channels face minimal regulatory scrutiny but drive innovation in compact packaging formats.
Foodservice providers dominate procurement volume; event planners expand most quickly through platform consolidation.
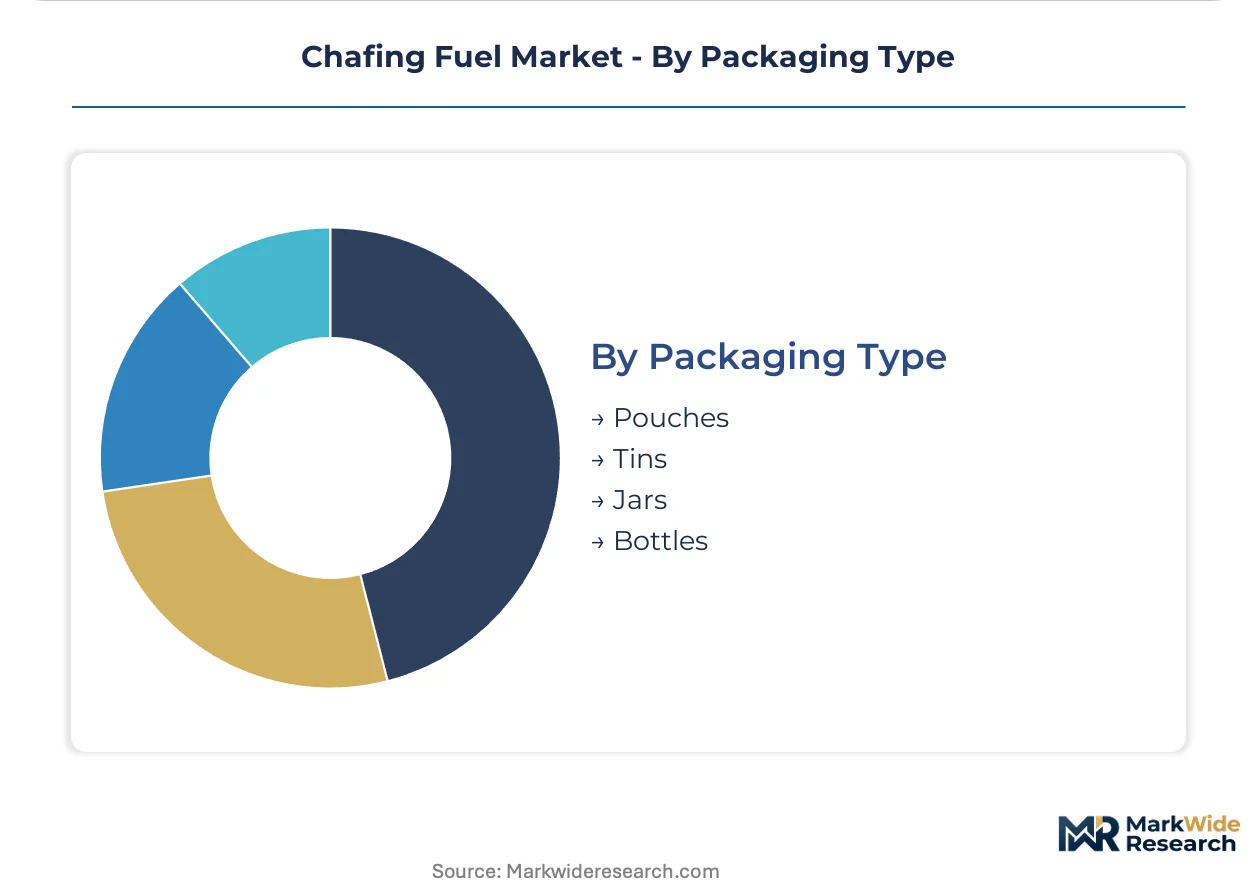
Packaging Type:
Canister fabrication cost volatility and aluminum sheet supply concentration shape packaging economics.
- Pouches:Flexible laminate structures with spout dispensing reduce shipping cube for liquid formulations. Southeast Asian export manufacturers favor this format for container efficiency.
- Tins:Drawn-steel or aluminum canisters with crimped lids dominate gel fuel presentation. G.S. Industries anchors supply through captive metal fabrication in India.
- Jars:Wide-mouth polyethylene containers serve solid fuel tablets and reusable gel formats.
- Bottles:HDPE or PET containers with child-resistant closures address liquid fuel safety requirements for retail distribution.
Tins command the volume position; pouches gain share fastest in export-oriented supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn belt ethanol production in the United States Midwest anchors feedstock supply for North American chafing fuel manufacturing. This agricultural chemistry base supports formulation operations across multiple regulatory jurisdictions.
United States
Hotel banquet operations and third-party event logistics coordinators absorb the majority of gel fuel volume, driven by insurance liability requirements for open-flame service. FDA indoor air quality thresholds and EPA volatile organic compound limits constrain formulation chemistry and labeling requirements. Chicago and Dallas-Fort Worth metropolitan clusters concentrate distribution infrastructure for contract foodservice distributors.
Germany
Institutional caterers in Frankfurt and Munich favor quick-ignition liquid variants for rapid turnaround between service periods. REACH Annex XVII restrictions on methanol concentration force reformulation of legacy gel fuels across European Union member states. The Ruhr industrial corridor hosts metal canister fabrication facilities supplying drawn-steel containers.
China
Export-oriented manufacturing of gel fuel output concentrates in Yangzhou and surrounding Jiangsu province facilities. GB standards and SAMR product safety certifications shape eligibility for international hospitality chain procurement. Pearl River Delta logistics hubs containerize pouch-format liquid fuels for Southeast Asian markets.
India
Hotel and banquet hall construction in tier-2 and tier-3 cities under FSSAI food safety standards creates first-time demand for compliant distribution. The country's national food safety regulator mandates product registration for commercial food warming applications. Maharashtra and Gujarat industrial zones attract metal packaging investments from domestic fabricators.
France
Fixed-installation warming stations in Paris and Lyon hotels absorb steady volumes of REACH-compliant gel formulations. ECHA substance disclosure mandates filter supplier eligibility for institutional procurement contracts. Auvergne-Rhône-Alpes chemical clusters supply diethylene glycol bases for methanol-substitute reformulations.
Chafing Fuel Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers automate quality assurance and precision blending systems. The vendor base separates into three tiers: integrated chemical-metals conglomerates with captive feedstock and packaging operations; specialized combustion medium blenders serving regional distributor networks; and export-focused manufacturers competing on scale and certification breadth. Strategic archetypes include backward-integrated formulators controlling ethanol supply chains, and platform-integrated suppliers bundling fuel with adjacent foodservice equipment. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players pursuing multi-jurisdiction labeling capabilities and e-commerce direct channels.
Among North American integrated suppliers, Sterno Products occupies a position exemplifying captive production of ethanol-based formulations for margin stability across foodservice channels. G.S. Industries anchors the metals-integrated archetype through in-house control over canister fabrication cost structures. Yangzhou Zhongtian Tourist Products represents the export-scale manufacturer archetype, with dedicated facilities positioning for international hospitality chain approvals. These three patterns illustrate how competitive positioning stratifies across supply chain control, manufacturing scale, and regulatory certification breadth.
| Leading Market Players |
|---|
| Chef Link |
| G.S. Industries |
| Sterno Products |
| Yangzhou Zhongtian Tourist Products |
| Scientific Utility |
| BLAZE |
| Hollowick |
| CiboWares |
| Lumea |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap metal fabricators in India and China anchor canister supply, creating pricing discipline through captive production that buffers ethanol cost volatility for integrated formulators while squeezing margin for non-integrated blenders dependent on spot aluminum markets.
Pricing Analysis
Warranty-backed burn-duration guarantees separate premium formulations from unbundled commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with REACH Annex XVII-compliant methanol substitutes commanding modest premiums in Germany and France. Cost compression in standard-tier gel fuels intensifies as corn ethanol prices fluctuate with agricultural cycles. Event planners sourcing through Amazon Business exhibit highest price sensitivity; global hospitality chains with unified formulation standards absorb premium positioning for multi-jurisdiction labeling compliance.
Supply Chain Analysis
Dual-sourcing requirements from contract foodservice distributors mandate multi-supplier qualification for both ethanol feedstock and canister fabrication. Supply concentrates in the United States Midwest for corn-based ethanol, India for drawn-steel canister production, and China for aluminum sheet fabrication. Formulation chemistry draws from agricultural ethanol, diethylene glycol substitutes, and thickening agent inputs. Single-source vulnerability in aluminum sheet supply clusters creates exposure when Pearl River Delta logistics face disruption. Distribution runs through integrated foodservice platforms bundling fuel with serviceware and equipment rentals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combustion chemist talent scarcity props pricing power for qualified formulators, as EPA and FDA indoor air quality compliance forces requalification cycles that constrain effective capacity expansion.
For Market Incumbents: Lock in backward integration into ethanol supply chains or captive canister fabrication to defend margin stability against feedstock volatility. Add automated quality assurance capacity in United States metropolitan distribution clusters to guarantee batch-traceable formulations for contract foodservice accounts. Electric warming substitution in fixed-installation buffets threatens gel fuel volume; counter through quick-ignition liquid variant development for mobile catering. For New Entrants and Emerging Players: Integrated foodservice platforms represent the most penetrable channel for unbundled fuel procurement, as third-party event logistics coordinators consolidate purchases. Target tier-2 and tier-3 Indian cities under FSSAI buildout where first-time compliant distribution infrastructure creates white-space opportunity. Pursue SAMR and GB standard certification to unlock Southeast Asian hospitality chain approvals through direct e-commerce channels. For Investors and Strategic Acquirers: USDA bio-preferred procurement standard adoption for federal foodservice contracts is the leading indicator that renewable feedstock-derived fuel supply channels will capture dedicated volume pools. Five-to-ten year viability favors backward-integrated formulators with captive ethanol production and multi-jurisdiction labeling capabilities. Watch for EPA volatile organic compound threshold tightening as the signal for accelerated industry consolidation around compliant formulation libraries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Supply | Captive corn-belt production insulates margin from agricultural commodity cycles. |
| Multi-Jurisdiction Labeling Investment | Parallel FDA, EPA, REACH, and GB compliance unlocks global hospitality chain procurement. |
| Automated Quality Assurance Deployment | Inline spectroscopic verification compresses batch release timelines for contract distributors. |
| Direct E-Commerce Channel Development | Amazon Business bypass eliminates traditional distributor markups for price-sensitive event planners. |
| Bio-Based Feedstock Qualification | USDA bio-preferred certification opens dedicated federal foodservice contract supply channels. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across plant managers at ethanol blending facilities, procurement leads at contract foodservice distributors, distribution channel partners, and technical R&D directors specializing in combustion chemistry. FDA indoor air quality standards, EPA volatile organic compound regulations, REACH Annex XVII submissions, and SAMR product safety certifications provided regulatory boundary conditions. Bottom-up volume modeling across formulation types and applications triangulated against top-down market sizing from customs export records and foodservice equipment shipment data.
Granularity-level modeling operated at product type, application, end user, and packaging format dimensions, with geographic regulatory clusters treated as distinct supply-demand zones. CAGRs were derived from trend extrapolation of historical volume patterns adjusted for regulatory inflection points and feedstock cost trajectories across the analysis window. Burn-duration specification compliance rates and hospitality chain procurement approval timelines served as industry-specific forecast inputs.
Caveats apply where EPA emission threshold revisions, REACH substance restriction expansions, or agricultural commodity price spikes could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and ethanol feedstock supply continuity. A model refresh is warranted upon material change in FDA indoor air quality standard stringency or USDA bio-preferred procurement adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
UAE Chemical Logistics Market
Fuels
South America Bunker Fuel Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
India Coal Market
Fuels
Gas to Liquid (GTL) Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Solid Recovered Fuel Market
Fuels
Brazil LNG Market
Fuels
Global Turbine Oil Market
Fuels
Global Wood Gas Generator Market
Fuels
Marine Fuel Filter Market
Fuels
Global Charcoal Market
Fuels
United States Bunker Fuel Market
Fuels
North America Wood Pellet Market
Fuels
Oil Dispenser Market