
 Australia and New Zealand Plastic Packaging Film Market | 2026-2036
Australia and New Zealand Plastic Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Plastic Packaging Film Market Insights
Advanced multi-layer coextrusion technology is reconfiguring film performance benchmarks across the Australia and New Zealand Plastic Packaging Film Market. Amcor Group GmbH leverages vertical integration from resin sourcing to converter relationships, sustaining pricing power in barrier film categories. Integrated Packaging Group anchors its position in stretch film through manufacturing scale and direct distribution networks across Australian industrial corridors.
Australia and New Zealand plastic packaging film encompasses flexible polymer substrates engineered from polyethylene, polypropylene, or multi-layer laminates, typically ranging from 12 to 150 microns in gauge, manufactured via blown or cast extrusion processes to provide moisture barrier, puncture resistance, and seal integrity for perishable goods. The material dimension reveals polyethylene sustaining dominant volume share due to cost efficiency and recyclability infrastructure, while biodegradable alternatives occupy niche premium positioning amid stewardship compliance pressures. Barrier film leads value contribution as meat and dairy processors demand extended shelf-life performance, with shrink film registering fastest growth from e-commerce fulfillment expansion.
Australia's National Plastics Plan and New Zealand's Waste Minimisation Act, enforced by the Australian Packaging Covenant Organisation and the country's national environmental regulator, mandate recycled content thresholds and design-for-recycling standards that reshape converter procurement specifications. The Australian Competition and Consumer Commission monitors greenwashing claims, tightening market access for uncertified environmental assertions. Stakeholders must monitor evolving extended producer responsibility frameworks and pre-emptively certify film portfolios against emerging Australasian recycling protocol harmonisation.
Market Dynamics
Multi-layer coextrusion technology is compressing performance thresholds across the Australia and New Zealand Plastic Packaging Film Market, forcing converters to recalibrate barrier specifications while Australia's National Plastics Plan tightens material compliance deadlines.
Growth Catalysts
- New Zealand's Plastic Packaging Product Stewardship Scheme:Mandatory design-for-recycling standards accelerate certified film adoption across Auckland food processing clusters.
- Stretch hood technology:Pallet stabilization demands from Victorian logistics hubs drive high-performance linear low-density polyethylene consumption.
- Queensland agricultural exports:Extended shelf-life requirements for beef and dairy shipments sustain barrier film procurement volumes.
Market Restraints
- Ethylene feedstock volatility:Naphtha-derived polyethylene resin costs fluctuate with Singapore refining margins, squeezing converter margins.
- Recycling infrastructure gaps:Soft plastics collection remains concentrated in Melbourne and Sydney metropolitan zones, limiting circular material availability.
- Biodegradable film performance ceiling:PLA-based alternatives fail moisture barrier tests required by red meat processors, blocking premium substitution.
Strategic Opportunities
- Tasmanian underpenetration:Apple and cherry packing operations lack localized film converting capacity, creating distribution whitespace.
- Digital watermark integration:AI-powered sortation alignment with Australasian Recycling Label standards enables automated material identification.
- Direct-to-farm stretch film distribution:Bypassing traditional packaging distributors cuts lead times for New South Wales dairy cooperatives.
Industry Challenges
- Coextrusion technician scarcity:Seven-layer blown film expertise concentrates with aging workforces in Melbourne's northern suburbs.
- APCO compliance timeline compression:Australian Packaging Covenant Organisation recycled content targets outpace certified feedstock scaling.
- Legacy gravure printing integration:Water-based ink transitions stall on press modification backlogs at Sydney flexible packaging converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Plastic Packaging Film Market |
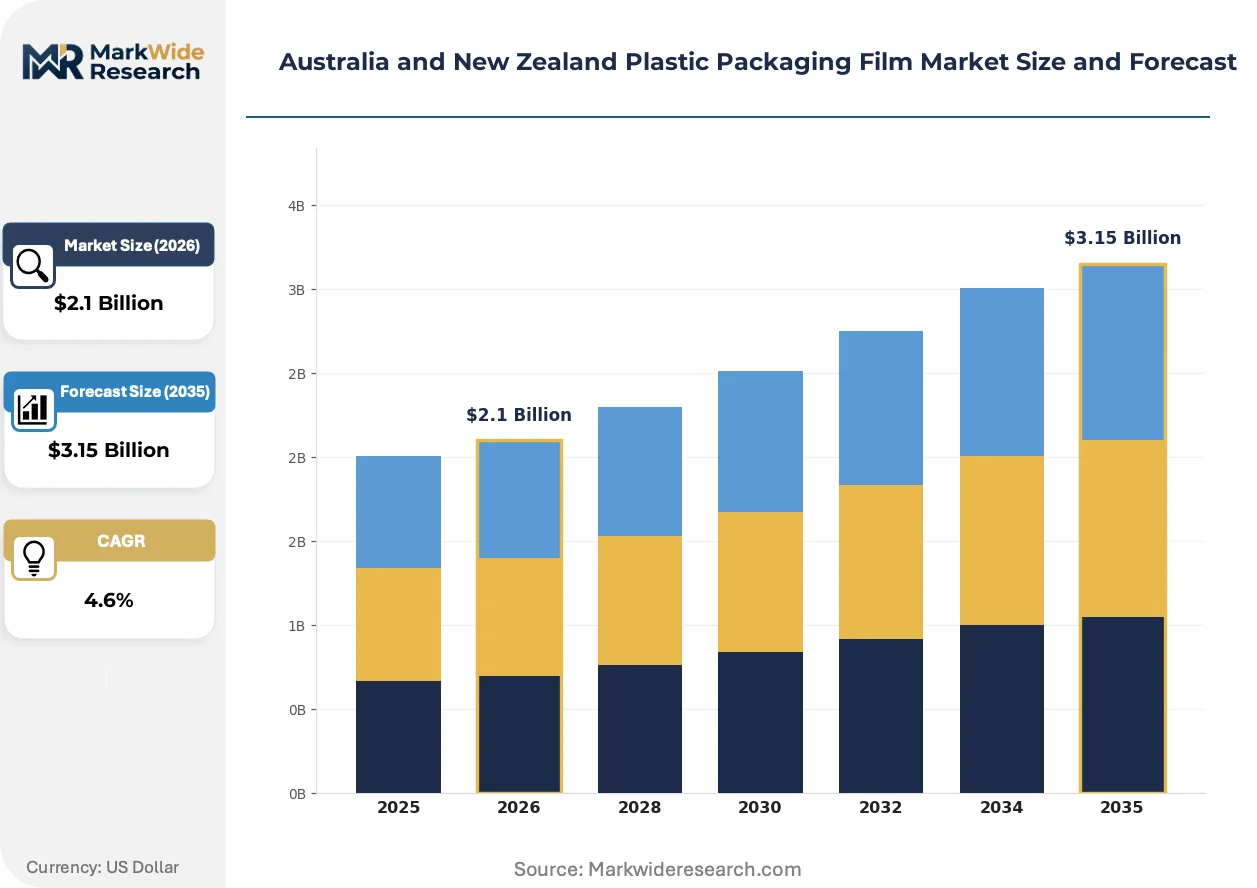
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Multi-Layer Film Material: Polyethylene, Polypropylene, PVC, Biodegradable End User: Food & Beverage, Healthcare, Consumer Goods, Industrial Packaging Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Amcor Group GmbH, Surepak Pty Ltd, Richdale Plastics Pty Ltd, Wales Industries Pty Ltd, POLIFILM PROTECTION AUSTRALIA PTY LIMITED, Integrated Packaging Group, Polywrap (Australia), Dolphin Plastics, Sealed Air Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Plastic Packaging Film Market Trends and Innovations
Material science convergence with digital traceability systems is restructuring how film specifications are negotiated between converters and Australian supermarket chains. Performance verification now extends beyond laboratory testing into blockchain-enabled provenance documentation.
Mono-material polyethylene barrier films are migrating from experimental trials to commercial scale across Australian meat processing facilities. Coles and Woolworths procurement teams mandate single-substrate designs to align with kerbside recycling streams. This migration from multi-layer laminates collapses converter technical service requirements while demanding new sealant layer formulations.
Australia's National Plastics Plan 2021 targets trigger enforced recycled content minimums through APCO reporting frameworks. Converters must certify post-consumer resin percentages or face exclusion from preferred supplier lists. Fresh produce packaging categories bear the steepest compliance burden as lightweighting conflicts with mechanical property thresholds.
Supermarket private-label consolidation compresses supplier rosters while elevating technical specification bargaining power. Victorian and New South Wales food retailers now centralize film procurement through category management teams rather than decentralized store operations. This concentration shifts volume toward integrated converters with in-house resin compounding capabilities.
Australia and New Zealand Plastic Packaging Film Market Segmentation
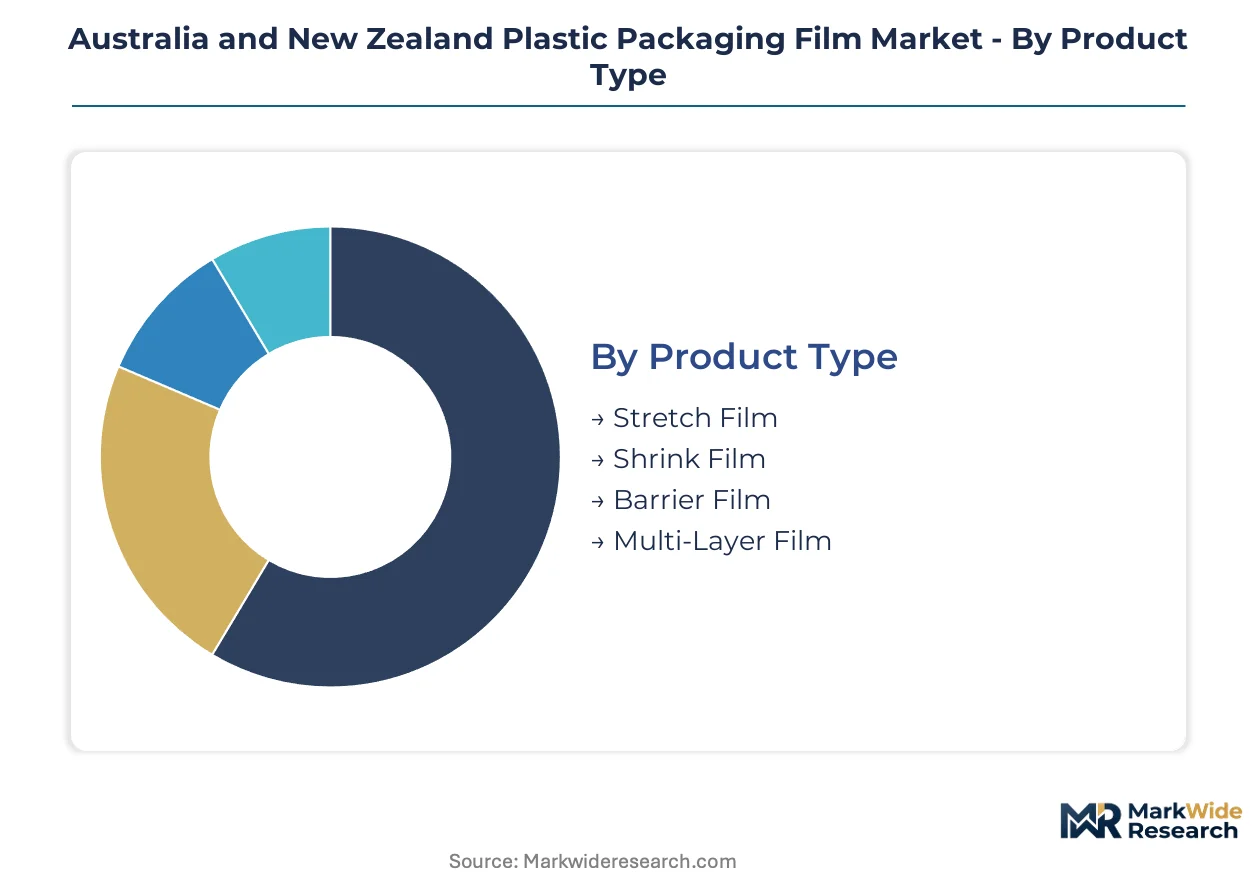
Segmentation reveals how technical service intensity and recycling compliance reshape procurement patterns across Australian and New Zealand film markets. Converter relationships and stewardship certification now determine category winners as supermarket chains consolidate supplier rosters.
Product Type:
After-sales service intensity varies sharply by film complexity, with multi-layer structures demanding ongoing technical support while commodity films require minimal converter engagement.
- Stretch Film:Linear low-density polyethylene formulations dominate pallet stabilization for Victorian logistics corridors. New South Wales dairy cooperatives drive procurement volumes through direct-to-farm distribution models that bypass traditional packaging intermediaries.
- Barrier Film:Multi-layer coextrusion structures incorporating EVOH or nylon deliver oxygen and moisture protection for red meat and dairy processors. Queensland beef exporters sustain demand as extended shelf-life specifications tighten for premium export grades.
- Shrink Film:Polyolefin formulations serve secondary packaging for e-commerce fulfillment centers expanding across Sydney and Melbourne metropolitan zones.
- Multi-Layer Film:Complex laminates combining polyethylene, polypropylene and barrier resins address specialized pharmaceutical and fresh produce applications requiring puncture resistance and seal integrity.
Barrier Film holds the largest share; momentum sits with Shrink Film.
Material:
Cost tier stratification separates commodity resins from certified circular alternatives, with price premiums widening for post-consumer recycled content.
- Polyethylene:Low-density and linear low-density grades sustain dominant volume position through cost efficiency and established kerbside recycling infrastructure. Australia's National Plastics Plan mandates accelerate procurement shifts toward certified recyclable polyethylene streams.
- Polypropylene:Cast and oriented films deliver clarity and stiffness for snack food and confectionery packaging across Australian supermarket private-label programs.
- PVC:Shrink sleeve applications persist in beverage labeling despite environmental pressure and substitution toward polyolefin alternatives.
- Biodegradable:PLA and starch-based formulations occupy niche positioning for compostable fresh produce bags, though moisture barrier limitations block penetration into red meat segments.
Polyethylene commands volume leadership; Biodegradable climbs the fastest on stewardship compliance premiums.
End User:
Application-specific performance requirements dictate film specification complexity, with food safety standards imposing the steepest compliance burdens.
- Food & Beverage:Fresh produce, meat, dairy and processed food applications generate the bulk of demand across Coles and Woolworths supply chains. APCO recycled content targets and design-for-recycling standards reshape converter procurement specifications.
- Healthcare:Sterile barrier films for medical device packaging require validated seal integrity and particulate control, with TGA compliance adding regulatory layers.
- Consumer Goods:Personal care and household product wrapping demands printability and shelf appeal through gravure and flexographic decoration.
- Industrial Packaging:Heavy-duty stretch and shrink applications serve manufacturing and construction material distribution with lower technical service intensity.
Food & Beverage dominates value contribution; Healthcare shows steepest expansion trajectory on regulatory barrier tightening.
Distribution Channel:
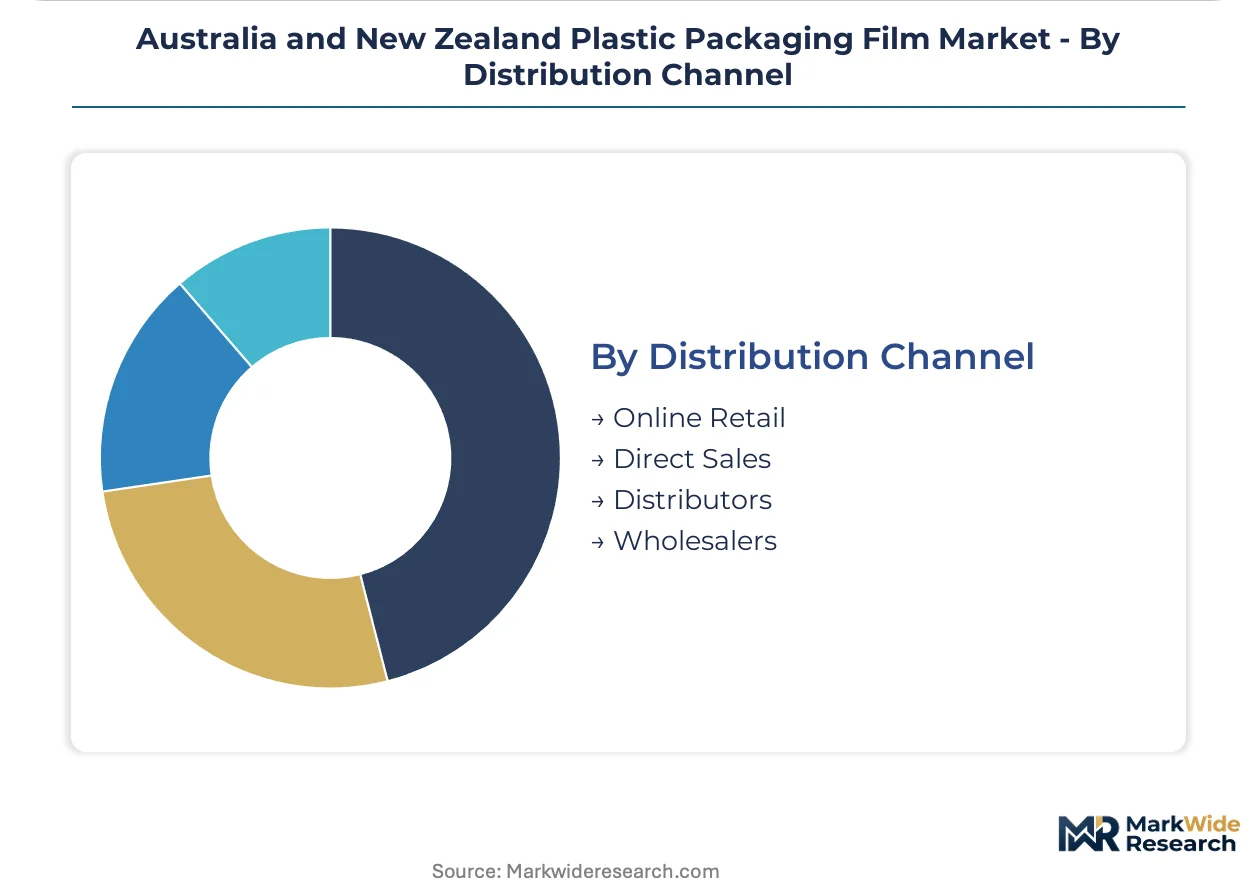
Customer type and purchase scale determine channel selection, with large volume buyers bypassing intermediaries while smaller operators rely on distributor technical support.
- Direct Sales:Integrated converters with in-house resin compounding capabilities serve major supermarket chains and national food processors through dedicated account management. Victorian and New South Wales food retailers centralize procurement through category management teams.
- Distributors:Regional packaging distributors provide inventory buffering and technical service for mid-tier food processors and agricultural packers lacking direct converter relationships.
- Online Retail:E-commerce platforms capture small-volume orders from specialty food producers and craft beverage operators seeking rapid turnaround on standardized specifications.
- Wholesalers:Bulk film reselling operations serve price-sensitive industrial users with commodity stretch and shrink grades requiring minimal specification customization.
Direct Sales captures the largest share; Online Retail gains share fastest on digital procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian beef and dairy exports to Asian markets sustain film demand across Queensland processing corridors, while New Zealand's horticultural shipments to China and Southeast Asia drive specialized packaging requirements in Auckland and Hawke's Bay.
New South Wales
Sydney's logistics hubs generate stretch film consumption for pallet stabilization across e-commerce fulfillment networks. The Australian Packaging Covenant Organisation enforces recycled content reporting that converters must satisfy to maintain supermarket supplier status. Food processing clusters in western Sydney sustain barrier film procurement for meat and dairy applications.
Victoria
Melbourne's northern suburbs concentrate seven-layer blown film manufacturing expertise for complex barrier specifications. Australia's National Plastics Plan mandates accelerate design-for-recycling compliance timelines for Victorian converters. The Port of Melbourne's container throughput sustains export-oriented packaging demand from Gippsland food processors.
Queensland
Beef processing facilities in Rockhampton and Toowoomba require extended shelf-life films for premium export grades to Japan and Korea. State-level plastic bag bans complement federal stewardship frameworks. Brisbane's distribution infrastructure anchors stretch hood consumption for agricultural chemical and machinery distribution.
Western Australia
Perth's isolation drives localized film converting for mining supply chains and remote agricultural operations. The Waste Avoidance and Resource Recovery Act imposes product stewardship obligations on packaging suppliers. Wheatbelt grain handling operations sustain bulk agricultural film demand despite limited local manufacturing scale.
New Zealand
Auckland's food processing clusters drive certified recyclable film adoption under the Plastic Packaging Product Stewardship Scheme. Hawke's Bay apple and kiwifruit packers demand puncture-resistant films for export shipments to Asian markets. Christchurch converters service South Island dairy cooperatives with specialized barrier specifications for extended shelf-life products.
Australia and New Zealand Plastic Packaging Film Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into integrated resin-to-film operators, regional converting specialists, and imported product distributors. Three archetypes dominate: vertically integrated multinationals with captive resin supply, mid-scale domestic converters with direct retail relationships, and niche specialists in biodegradable or certified circular grades. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships with supermarket private-label programs.
Within the integrated multinational tier, Amcor Group GmbH exemplifies channel control through resin sourcing leverage and converter network relationships. Among Australia-based specialists, Integrated Packaging Group anchors industrial stretch film supply through manufacturing scale and distribution density across Victorian logistics corridors. Surepak Pty Ltd occupies a position within the mid-scale converting segment serving food processing and agricultural packaging requirements with localized technical service capabilities.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Surepak Pty Ltd |
| Richdale Plastics Pty Ltd |
| Wales Industries Pty Ltd |
| POLIFILM PROTECTION AUSTRALIA PTY LIMITED |
| Integrated Packaging Group |
| Polywrap (Australia) |
| Dolphin Plastics |
| Sealed Air Australia |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Victorian blown film extrusion lines is compressing spot pricing for commodity polyethylene grades while simultaneously pushing converters toward long-term contract structures that lock in resin volumes. This utilization imbalance rewards integrated operators with captive resin compounding capabilities while squeezing standalone converters dependent on merchant polyethylene supply.
Pricing Analysis
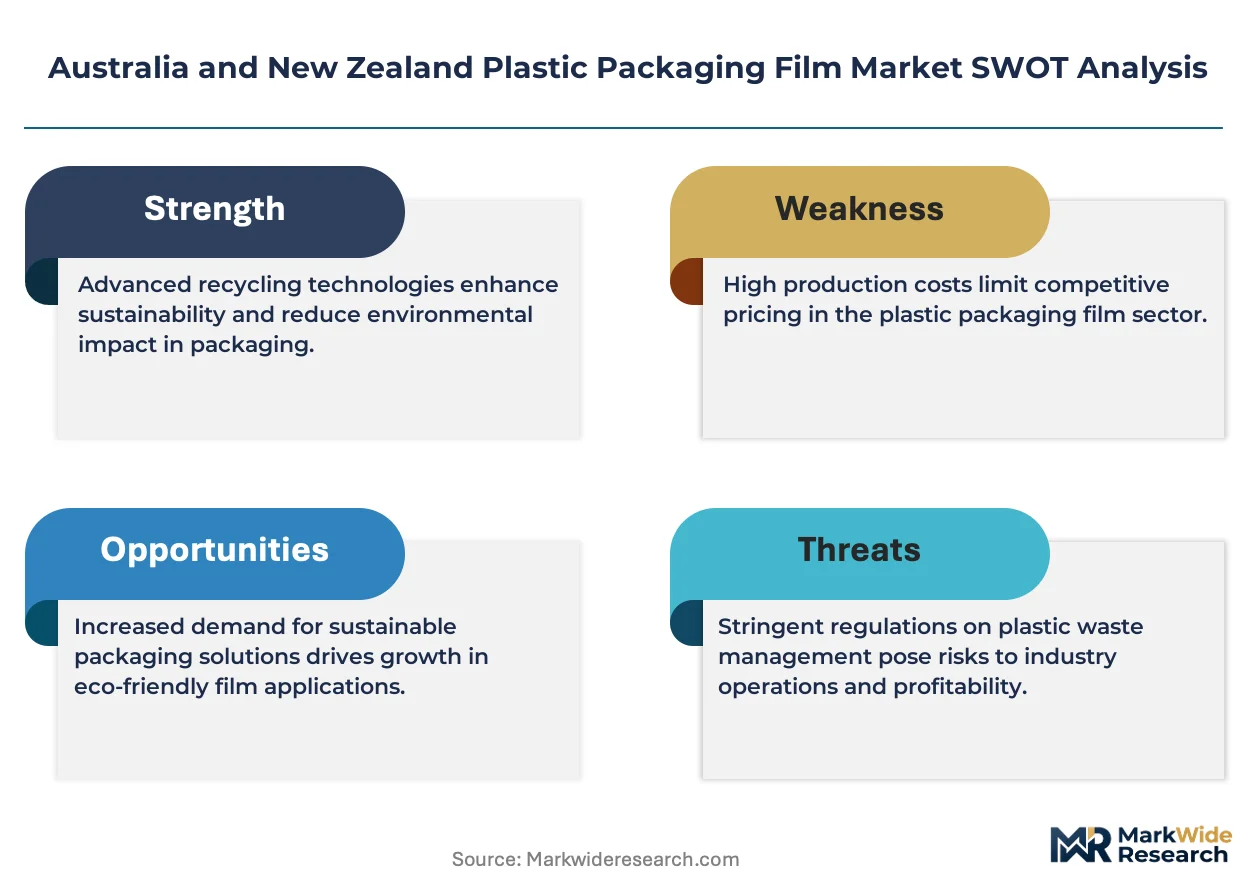
The technology-generation pricing gap separates legacy multi-layer laminates from next-generation mono-material barrier films, with Coles and Woolworths procurement teams extracting premiums for certified recyclable designs. Three-tier pricing structure across premium certified-circular, standard recyclable, and economy non-certified levels reflects APCO compliance grade and volume scale. Pricing pressure stems from Singapore naphtha refining margin volatility feeding into polyethylene resin costs. Small-scale agricultural packers exhibit highest price sensitivity, while national supermarket chains prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days at major Australian supermarket chains are straining converter working capital, accelerating supply-chain finance facility adoption among mid-scale operators. Raw material sourcing draws from Singapore refining complexes for polyethylene resin, with additive and masterbatch inputs anchored in Chinese specialty chemical production. Single-source vulnerability concentrates in seven-layer coextrusion equipment supply from European and Japanese machinery builders. Distribution runs through direct converter relationships for national accounts and regional packaging distributors for mid-tier food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough driven by Australia's National Plastics Plan compliance deadlines forcing capital deployment toward certified circular capacity. The recovery trajectory hinges on resin price stabilization and supermarket private-label consolidation patterns.
For Market Incumbents: Build regulatory compliance moats through APCO certification pre-positioning ahead of recycled content threshold enforcement. Secure backward integration into post-consumer resin compounding to defend margin structure against merchant feedstock volatility. Channel control through direct supermarket relationships represents the critical defensive lever against emerging biodegradable film specialists.
For New Entrants and Emerging Players: Tasmanian apple and cherry packing operations present geographic underpenetration with limited localized converting capacity and reliance on mainland supply chains. Direct-to-farm stretch film distribution models bypass entrenched packaging distributor networks while capturing dairy cooperative procurement consolidation. Target certified circular film niches where APCO compliance premiums offset scale disadvantages against integrated incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with locked supermarket private-label supply agreements and multi-year resin pass-through contracts. Long-term viability over the next decade favors operators with demonstrated APCO compliance certification and established kerbside recycling stream alignment. Acquisition targets should demonstrate digital watermark integration capabilities aligned with Australasian Recycling Label standards. The signal to watch is supermarket category management team consolidation of supplier rosters toward preferred partner lists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive post-consumer recycled feedstock supply insulates margin from Singapore naphtha volatility. |
| Digital Watermark Integration | AI-powered sortation alignment with Australasian Recycling Label standards enables automated material identification. |
| Direct-to-Farm Distribution Model | Bypassing traditional packaging distributors cuts lead times for New South Wales dairy cooperatives. |
| APCO Certification Pre-Positioning | Early compliance with Australian Packaging Covenant Organisation recycled content targets secures preferred supplier status. |
| Mono-Material Barrier Film Scale-Up | Single-substrate designs align with Coles and Woolworths kerbside recycling procurement mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Australian Bureau of Statistics trade data, APCO annual reporting disclosures, and resin producer pricing bulletins. Primary interviews encompassed film converting plant managers, supermarket category procurement leads, food processing packaging engineers, and logistics distribution directors. Secondary validation drew from Australian Packaging Covenant Organisation compliance filings, customs import records for extrusion equipment, and TGA medical device packaging guidance. Bottom-up volume modeling triangulated against top-down market sizing from identified converter capacity.
Forecast inputs include segmented modeling across product type, material grade, end-use application, and distribution channel dimensions. The analytical framework projects value and volume trajectories over the projection horizon through elasticity-adjusted demand curves and capacity utilization assumptions. CAGRs were derived from regression analysis against historical resin price cycles and supermarket procurement consolidation patterns. Industry-specific inputs incorporate Australia's National Plastics Plan enforcement timelines and New Zealand's Plastic Packaging Product Stewardship Scheme adoption curves.
Practitioners should monitor Singapore refining margin volatility, APCO compliance deadline acceleration, and supermarket supplier roster consolidation for early signals of forecast deviation. Forecasts reflect documented assumptions regarding resin price normalization and recycling infrastructure scaling. Macroeconomic contraction, regulatory timeline extension, or breakthrough biodegradable barrier performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polypropylene Packaging Films Market
Poly film
Multi-Layer Blown Films Market
Poly film
PE Foam Films Market
Poly film
Blown Film Extruder Market
Poly film
Global Polyethylene Packaging Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Global Specialty Films Polymer Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Thermoforming Films Market
Poly film
Colourless Polyimide Films Market
Poly film
North America BOPP Films Market
Poly film
Vinyl Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
PVC Films Market
Poly film
Global BOPET Packaging Films Market