
 Semiconductor O-Rings Market | 2026-2036
Semiconductor O-Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor O-Rings Market Insights
REACH compliance is recalibrating the cost-of-entry calculus for European suppliers of fluorocarbon and silicone sealing solutions. DuPont leverages its materials science heritage to sustain leadership in perfluoroelastomer formulations for vacuum chamber applications. Trelleborg Group anchors its position through backward integration into compound development, while Greene Tweed competes via specialization in low-outgassing grades for EUV lithography systems.
Semiconductor O-Rings are toroidal elastomer seals engineered to maintain vacuum integrity and chemical resistance in wafer processing equipment, typically manufactured from perfluoroelastomers or high-purity silicones with compression set values below 15 percent after 70 hours at 200°C. Their primary purpose is preventing contamination and gas leakage in sub-atmospheric process chambers where particle counts must stay below Class 1 thresholds. Fluorocarbon materials dominate current revenue owing to their plasma resistance in etch and deposition tools, while low-outgassing O-Rings represent the fastest-expanding category as EUV adoption intensifies. Custom geometries command premium positioning due to tool-specific groove designs and rapid prototyping requirements from equipment OEMs.
FDA, EPA, and REACH collectively govern material composition, emissions profiles, and chemical safety documentation for sealing components entering semiconductor supply chains. ISO 14644 cleanroom standards and SEMI guidelines further constrain particle generation limits, effectively filtering out uncertified compounders from qualified vendor lists. Stakeholders must monitor regulatory divergence between Washington and Brussels on per- and polyfluoroalkyl substance restrictions, as this will determine which material platforms retain long-term qualification status.
Market Dynamics
EUV lithography rollout is compressing qualification timelines for fluorocarbon sealing solutions as equipment OEMs demand sub-ppb outgassing performance at 193nm wavelengths. This technical threshold is restructuring supplier tiers and accelerating compounder consolidation around certified cleanroom manufacturing.
Growth Catalysts
- Advanced node expansion:Taiwan's Hsinchu Science Park cluster is driving concentrated demand for vacuum-compatible O-Rings as foundries deploy 3nm and 2nm process tools.
- REACH material mandates:ECHA compliance deadlines are forcing wafer fabrication facilities to replace legacy sealing compounds with certified low-VOC formulations.
- Plasma etch intensity:Atomic layer etch tools require perfluoroelastomer seals capable of resisting fluorine radical exposure above 200°C operating temperatures.
Market Restraints
- Fluoropolymer feedstock concentration:Virgin PTFE and FKM resin supply concentrates among Japanese and Chinese chemical producers, exposing compounders to price volatility.
- Cleanroom certification bottlenecks:ISO 14644 Class 1 qualification requires 18-24 month validation cycles that lock out new market entrants.
- Silicone substitution in non-critical joints:High-purity liquid silicone rubber is displacing fluorocarbons in atmospheric pressure applications below 150°C.
Strategic Opportunities
- India's semiconductor subsidy pipeline:PLI scheme disbursements for fab construction in Gujarat and Karnataka will create demand for qualified sealing vendors.
- EUV pellicle integration:Convergence of membrane handling systems with vacuum chamber sealing is opening specification windows for multi-function gasket designs.
- Direct OEM contracting:ASML and Nikon lithography equipment builders are bypassing distributors to source custom groove geometries from compounders.
Industry Challenges
- Perfluoroelastomer compounding expertise scarcity:Formulation chemists with vacuum bake-out and plasma exposure testing experience command premium compensation.
- Dual-use export control alignment:Coordinating BIS and EU dual-use technology classifications for fluorocarbon seals adds administrative overhead to cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor O-Rings Market |
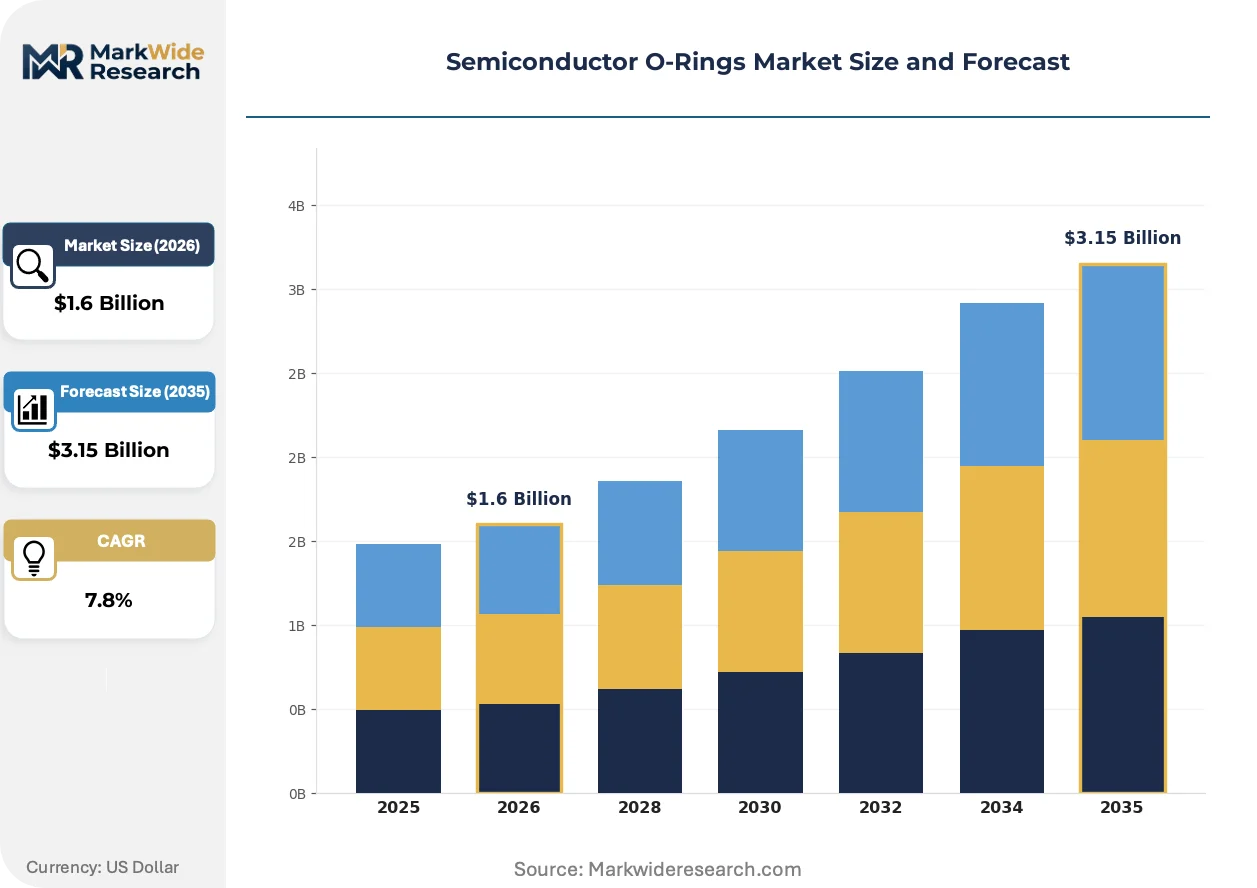
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard O-Rings, custom O-Rings, reinforced O-Rings, low-outgassing O-Rings Material: Silicone, Fluorocarbon, Ethylene Propylene, Nitrile Industry Vertical: Consumer Electronics, Telecommunications, Automotive, Aerospace Application: Sealing, Insulating, Cushioning, Fluid Management |
| Companies Covered | DuPont, VALQUA, Precision Polymer Engineering, Boyd Corporation, Greene Tweed, Trelleborg Group, NOK Corporation, Freudenberg, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor O-Rings Market Trends and Innovations
Material science advances and regulatory stringency are converging to redefine performance benchmarks for semiconductor sealing components. Three developments are restructuring competitive positioning.
Perfluoroelastomer nanocomposite formulations incorporating ceramic fillers are electrifying vacuum integrity standards for EUV source chambers. ASML and its subsystem suppliers are adopting these compounds within 12-month qualification windows. The technology is compressing acceptable outgassing thresholds from parts-per-million to parts-per-billion levels.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing European compounders to submit comprehensive safety dossiers to ECHA by 2025 deadlines. Wafer fabrication facilities in Germany and France must document chemical safety across their qualified vendor lists. Low-molecular-weight fluorocarbon seal categories face the highest substitution pressure.
Equipment OEMs are consolidating vendor relationships around full-lifecycle service agreements that bundle seal replacement with predictive maintenance analytics. Distributors serving secondary fab equipment markets are losing share to manufacturer-direct channels. This pattern is most pronounced in South Korea's Pyeongtaek and Yongin manufacturing corridors.
Semiconductor O-Rings Market Segmentation
Semiconductor O-Ring procurement decisions pivot on certification alignment with specific process environments. Equipment OEMs and fab operators segment demand across material purity grades, geometric precision requirements, and thermal-chemical exposure profiles to match sealing solutions with tool specifications.
Product Type:
REACH compliance and SEMI qualification requirements vary sharply across product categories, with EUV-grade seals demanding 18-24 month validation cycles versus standard catalog items.
- Standard O-Rings:Catalog-grade fluorocarbon and silicone seals manufactured to AS568 dimensional tolerances for atmospheric pressure applications below 150°C. Procurement concentrates among legacy 200mm fab operators in Taiwan's Tainan Science Park seeking cost-optimized replacement cycles.
- Custom O-Rings:Tool-specific groove geometries produced via rapid prototyping for lithography and etch chamber retrofits. ASML and Nikon equipment builders in Veldhoven and Kumagaya are bypassing distributors to source these directly from compounders with cleanroom molding capabilities.
- Reinforced O-Rings:Metal or fabric-inserted designs for high-pressure chemical delivery systems.
- Low-outgassing O-Rings:Perfluoroelastomer formulations with sub-ppb volatile organic compound emissions for EUV source chambers.
Leading the category by volume: Standard O-Rings. Expanding most quickly: Low-outgassing O-Rings.
Material:
Price tiers stratify according to plasma resistance thresholds and cleanroom certification grade, with perfluoroelastomer derivatives commanding premiums over commodity silicones.
- Silicone:High-purity liquid silicone rubber with platinum-cured chemistry for atmospheric bonding and gasket applications. Samsung's Pyeongtaek complex and Intel's Leixlip facility are displacing fluorocarbons with these in non-critical joints below 150°C to reduce material costs.
- Fluorocarbon:FKM and FFKM polymers delivering fluorine radical resistance above 200°C for plasma etch and deposition tools. Taiwan's Hsinchu Science Park cluster generates concentrated demand as foundries deploy 3nm and 2nm atomic layer processing equipment.
- Ethylene Propylene:EPDM compounds for aqueous chemical handling with limited thermal range.
- Nitrile:NBR formulations for general-purpose sealing in maintenance and secondary equipment.
Volume concentration: Fluorocarbon. Steepest expansion trajectory: Silicone in atmospheric applications.
Industry Vertical:
End-use concentration patterns reflect geographic fab construction cycles, with foundry investments in Taiwan and South Korea outpacing IDM spending in Europe and North America.
- Consumer Electronics:Smartphone and tablet processor fabrication driving demand for sub-5nm node compatibility. Apple's A-series and Qualcomm's Snapdragon foundry partners in Taiwan account for the dominant share of EUV-grade seal procurement.
- Telecommunications:5G baseband and RF component manufacturing with moderate vacuum requirements. China's SMIC and Hua Hong Semiconductor are expanding 28nm capacity in Shanghai and Wuxi, creating demand for standard fluorocarbon seals.
- Automotive:Power semiconductor and sensor packaging for electric vehicle traction inverters.
- Aerospace:Radiation-hardened chip production for satellite and defense applications with extended qualification protocols.
Demand leadership: Consumer Electronics. Gaining share fastest: Telecommunications on 5G infrastructure buildouts.
Application:
Functional segmentation maps directly to chamber pressure regimes, with vacuum integrity applications requiring the most stringent material certification.
- Sealing:Vacuum chamber integrity maintenance through perfluoroelastomer compression seals in sub-atmospheric process environments. ASML's EUV systems in Veldhoven demand these with compression set values below 15 percent after 70 hours at 200°C.
- Insulating:Thermal and electrical isolation in plasma generation subsystems. Lam Research etch tools in Fremont specify ceramic-filled nanocomposite formulations for source chamber applications.
- Cushioning:Vibration dampening in wafer handling robotics.
- Fluid Management:Chemical delivery system containment for acids, solvents, and slurries.
Procurement volume leader: Sealing. Climbing the fastest: Insulating on EUV source chamber complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park's tax-incentive framework concentrates Taiwan's foundry capacity expansion, while comparable zones in South Korea, the United States, Japan, and Germany anchor equipment procurement clusters for advanced node manufacturing.
Taiwan
TSMC's 3nm and 2nm fab ramps in Hsinchu and Tainan Science Parks drive concentrated demand for EUV-grade perfluoroelastomer seals. The National Development Council's chip industry subsidies extend through 2030. Kaohsiung's emerging 7nm capacity adds secondary procurement volume for standard fluorocarbon O-Rings.
South Korea
Samsung Electronics and SK Hynix expand Pyeongtaek and Yongin complexes with atomic layer deposition tools requiring plasma-resistant sealing. The Ministry of Trade, Industry and Energy's K-Chips Act provides 25% tax credits for domestic equipment sourcing. Seongnam's R&D corridor houses multiple compounder qualification laboratories serving local foundries.
United States
Intel's Ohio and Arizona fab construction triggers demand for vacuum chamber seals across etch and lithography tool installations. The CHIPS and Science Act's $52 billion appropriation funds domestic supply chain qualification. Phoenix's emerging semiconductor cluster attracts compounder cleanroom investments from established suppliers.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor Yokohama-Kawasaki demand for high-purity fluorocarbon formulations. METI's semiconductor revitalization strategy prioritizes material sovereignty for critical sealing components. Kyoto's precision equipment corridor maintains specialized compounding expertise for 193nm lithography systems.
Germany
Infineon and Bosch expand Dresden and Reutlingen capacity for automotive-grade power semiconductors. ECHA's REACH Annex XVII compliance deadlines force wafer fabrication facilities to replace legacy sealing compounds by 2025. Munich's equipment supplier ecosystem sources certified low-VOC formulations for EUV subsystem integration.
Semiconductor O-Rings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Materials science conglomerates leverage backward integration into polymer resin production to control formulation IP. Regional compounders with captive cleanroom molding capabilities capture equipment OEM direct contracts. Catalog distributors serving maintenance markets face margin compression as lithography builders consolidate vendor relationships. Dominant competitive moves include compounder consolidation around certified manufacturing and strategic partnerships for EUV qualification acceleration.
Within the materials science tier, DuPont and Trelleborg Group exemplify archetypes with polymer heritage and integrated compounding operations. Greene Tweed occupies a specialist position emphasizing low-outgassing grades for EUV lithography systems. These three anchors represent distinct strategic postures: diversified chemical conglomerate, engineered solutions integrator, and application-focused compounder.
| Leading Market Players |
|---|
| DuPont |
| VALQUA |
| Precision Polymer Engineering |
| Boyd Corporation |
| Greene Tweed |
| Trelleborg Group |
| NOK Corporation |
| Freudenberg |
| Parker Hannifin |
| Others |
Pricing and Supply Chain Analysis
Formulation chemists with vacuum bake-out and plasma exposure testing experience concentrate in Japan's Kyoto-Osaka corridor and Germany's Munich-Stuttgart axis, creating labor-cost differentials that widen pricing spreads between EUV-grade perfluoroelastomer seals and standard fluorocarbon catalog items. This workforce scarcity compresses margins for compounders attempting to serve both premium lithography OEMs and cost-sensitive legacy fab operators.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as ASML and Nikon lithography equipment builders compress qualification windows from 24 months to 12 months for EUV source chamber seals. Three-tier pricing structure across premium, standard, and economy levels separates custom groove geometries with cleanroom molding certification from catalog AS568 items and spot-market silicone substitutes. Price differentiation hinges on SEMI qualification grade and ISO 14644 Class 1 certification status. Cost compression in standard fluorocarbon tiers is intensifying because Samsung's Pyeongtaek complex and Intel's Leixlip facility are displacing premium seals with high-purity liquid silicone rubber in atmospheric applications below 150°C. Spot buyers in Taiwan's Tainan Science Park exhibit the highest price sensitivity, while lithography OEMs direct-contracting for EUV-grade formulations demonstrate minimal elasticity.
Supply Chain Analysis
Reverse-logistics flows for refurbished etch chamber seals are gaining traction in South Korea's Yongin manufacturing corridor as equipment OEMs bundle predictive maintenance analytics with seal replacement cycles. Virgin PTFE and FFKM resin production concentrates in Japan, China, and the United States, with Shin-Etsu Chemical and Daikin anchoring upstream supply. Compounders draw from fluoropolymer feedstock, ceramic filler nanocomposites, and platinum-cured silicone precursors. Single-source vulnerability pervades the perfluoroelastomer resin tier, where three chemical conglomerates control formulation IP for plasma-resistant grades. Distribution runs through manufacturer-direct channels for EUV-grade seals, while catalog distributors serve secondary fab equipment maintenance markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into polymer resin production and forward integration into full-lifecycle service agreements represent the decisive levers separating consolidators from margin-compressed distributors.
For Market Incumbents: Hedge against silicone substitution by accelerating EUV pellicle integration projects that bundle membrane handling with vacuum chamber sealing specifications. Deepen backward integration into fluoropolymer resin production to offset feedstock price volatility from Japanese and Chinese chemical suppliers. Defend against emerging Indian compounders by pre-qualifying cleanroom molding capacity in Gujarat and Karnataka ahead of PLI scheme fab construction.
For New Entrants and Emerging Players: Direct-to-OEM digital procurement platforms offer the most penetrable route for bypassing entrenched distributor relationships in South Korea's Pyeongtaek and Yongin corridors. Target India's semiconductor subsidy pipeline before qualified vendor list consolidation hardens around incumbent compounders. Pursue EUV subsystem qualification partnerships with Nikon in Kumagaya rather than competing head-to-head for ASML's compressed vendor base.
For Investors and Strategic Acquirers: Re-rating potential sits with regional compounders possessing captive cleanroom molding capabilities given the 18-24 month ISO 14644 Class 1 validation bottleneck locking out new market entrants. Five-to-ten-year viability favors specialists with demonstrated plasma exposure testing expertise rather than diversified industrial seal manufacturers. Monitor ECHA REACH Annex XVII enforcement actions against per- and polyfluoroalkyl substances as the critical inflection signal for material platform substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Shin-Etsu Chemical's captive supply of virgin PTFE insulates compounders from feedstock volatility. |
| EUV Qualification Acceleration Partnership | ASML's 12-month compressed validation windows reward compounders with existing cleanroom infrastructure. |
| Full-Lifecycle Service Agreement Bundling | Lam Research etch tool operators in Fremont prefer predictive maintenance analytics with seal replacement cycles. |
| India PLI Scheme Geographic Positioning | Gujarat and Karnataka fab construction creates first-mover advantage for qualified sealing vendors. |
| REACH-Compliant Low-VOC Formulation Development | ECHA deadlines force German and French wafer fabrication facilities to replace legacy sealing compounds. |
Research Methodology
SEC 10-K filings, ECHA REACH registration databases, and SEMI equipment market data formed the secondary backbone for this analysis. Primary interviews with vacuum chamber design engineers, fab procurement managers at TSMC and Samsung, compounder R&D directors, and lithography equipment OEM sourcing leads validated demand assumptions across the projection horizon. Bottom-up and top-down triangulation reconciled equipment installation forecasts with seal replacement cycle data.
Bottom-up modeling segmented volume and value outputs across material purity grades, geometric precision requirements, and thermal-chemical exposure profiles throughout the forecast period. The analytical framework incorporated perfluoroelastomer versus silicone substitution rates, EUV lithography tool deployment trajectories, and REACH compliance substitution timelines. CAGRs were derived from regression analysis of historical equipment procurement against seal content-per-tool metrics.
The model holds under stable fluoropolymer feedstock availability and continued EUV lithography rollout; deviation in ECHA per- and polyfluoroalkyl substance restrictions or Japanese resin export controls would shift material platform viability and compounder competitive positioning. Practitioners should monitor dual-use export control alignment between BIS and EU classifications for early signals of cross-border shipment friction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Specialty Coating Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
India Collagen Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Specialty and High Performance Films Market
Specialty Materials
Engineered Quartz Surface Market