
 Silicone Film Market | 2026-2036
Silicone Film Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Film Market Analysis
Buyer concentration among medical device OEMs is expanding as procurement consolidates around suppliers with validated biocompatibility dossiers. Dow Inc. leverages its integrated silicone polymer backbone to secure long-term supply agreements with tier-one healthcare manufacturers. Shin-Etsu Chemical Co., Ltd. anchors Asian supply through captive monomer production and precision casting capabilities. Wacker Chemie AG competes on custom formulation breadth across European electronics and automotive accounts.
Silicone film comprises cross-linked polydimethylsiloxane (PDMS) layers typically ranging from 25 micrometers to 500 micrometers, manufactured via solvent casting or extrusion calendering for dielectric insulation, biocompatible barriers, and controlled-release membranes. Self-adhesive film dominates value pools in medical and electronics bonding applications where peel strength and residue-free removal command premium positioning. Ultra-thin film represents the fastest-expanding thickness category as semiconductor packaging and flexible sensor architectures demand sub-50-micrometer dielectric layers with thermal stability exceeding 200 degrees Celsius.
FDA enforces ISO 10993 biocompatibility testing for silicone films entering implantable and skin-contact medical devices, while REACH restricts certain platinum catalyst residues in European-manufactured films. EMA's evolving guidance on extractables and leachables pushes suppliers toward tighter volatility controls and batch-level traceability systems. Stakeholders must monitor regulatory divergence between US and European purity standards when configuring regional production footprints and qualification protocols.
Market Dynamics
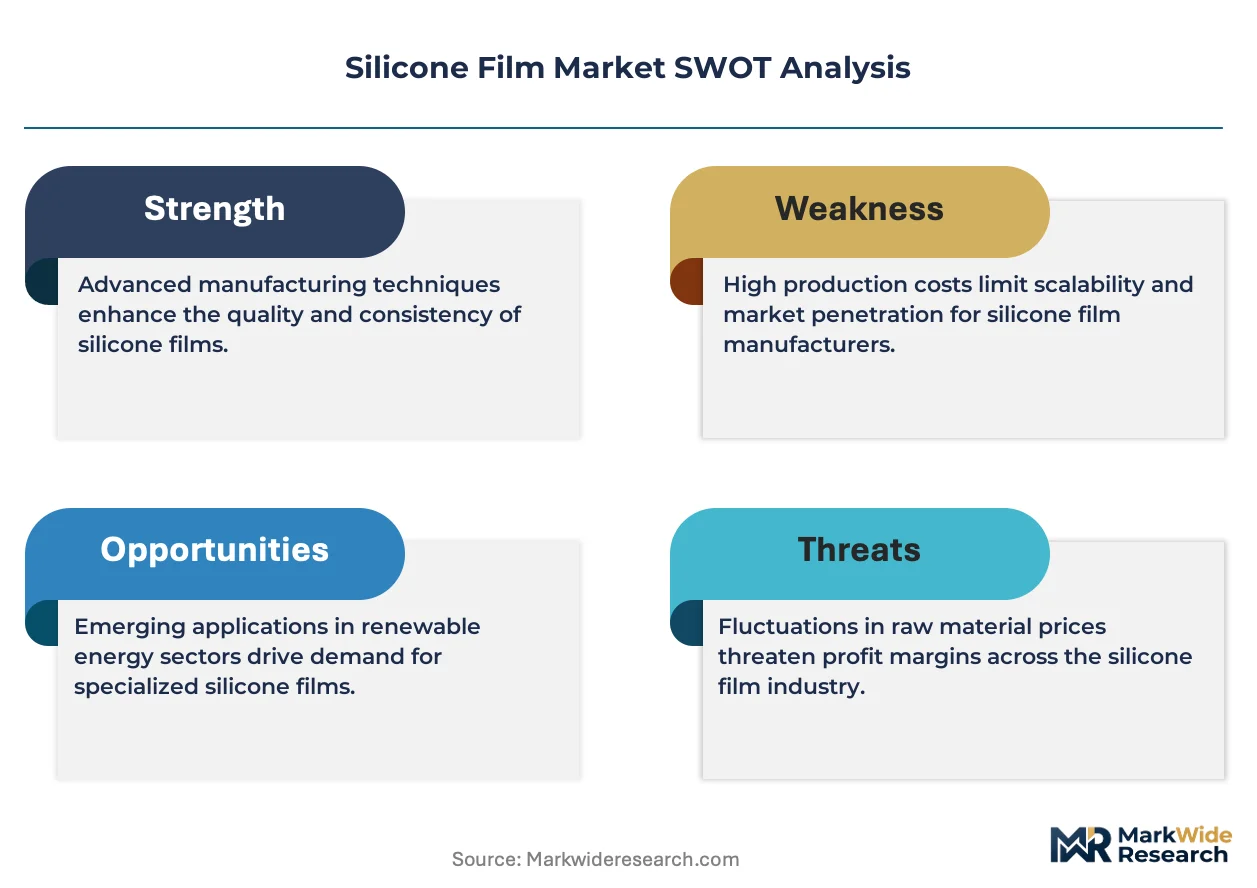
Medical device OEM procurement consolidation is concentrating demand around suppliers with validated ISO 10993 biocompatibility dossiers, compressing qualification timelines and raising barriers for new entrants lacking established regulatory track records.
Growth Catalysts
- Wound care expansion:Chronic wound prevalence is accelerating silicone film adoption in advanced dressings across Germany, Japan, and the United States as healthcare systems prioritize outpatient healing protocols.
- REACH catalyst residue restrictions:ECHA's tightening platinum catalyst limits are pushing European manufacturers toward cleaner polymerization chemistries that yield higher-purity films for implantable applications.
- Flexible sensor architectures:Semiconductor packaging demand for sub-50-micrometer dielectric layers with thermal stability exceeding 200 degrees Celsius is pulling ultra-thin film capacity expansion.
Market Restraints
- Siloxane monomer concentration:Captive production of dimethylsiloxane feedstock concentrates among integrated chemical conglomerates, limiting independent film processor margin autonomy.
- Biocompatibility testing burden:FDA's ISO 10993 testing requirements for implantable films impose 18-24 month qualification cycles that freeze supplier switching decisions.
- Polyimide substitution in high-heat electronics:Aerospace and automotive module manufacturers are migrating select dielectric applications to polyimide films where temperature extremes exceed silicone thermal boundaries.
Strategic Opportunities
- India medical device manufacturing:CDSCO's streamlined medical device rules and production-linked incentive schemes are attracting silicone film qualification investments for export-oriented wound care manufacturing.
- Drug-eluting transdermal patches:Controlled-release membrane specifications for hormone and pain management therapies are opening specialized film formulation contracts with pharmaceutical contract manufacturers.
- EU Green Deal chemistry mandates:Solvent casting process modifications to eliminate volatile organic compound emissions are creating first-mover advantages for European coating facilities with closed-loop recovery systems.
Industry Challenges
- Cross-linked PDMS process engineering talent:Precision casting technicians capable of maintaining sub-micrometer thickness tolerances across 25-500 micrometer ranges remain scarce relative to expansion plans.
- Batch-level extractables traceability:EMA's evolving leachables guidance demands pharmaceutical-grade documentation systems that smaller film converters lack capital to deploy.
- Multi-regulatory dossier maintenance:Simultaneous FDA, REACH, and PMDA compliance requires dedicated regulatory affairs functions that strain mid-scale supplier organizational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Film Market |
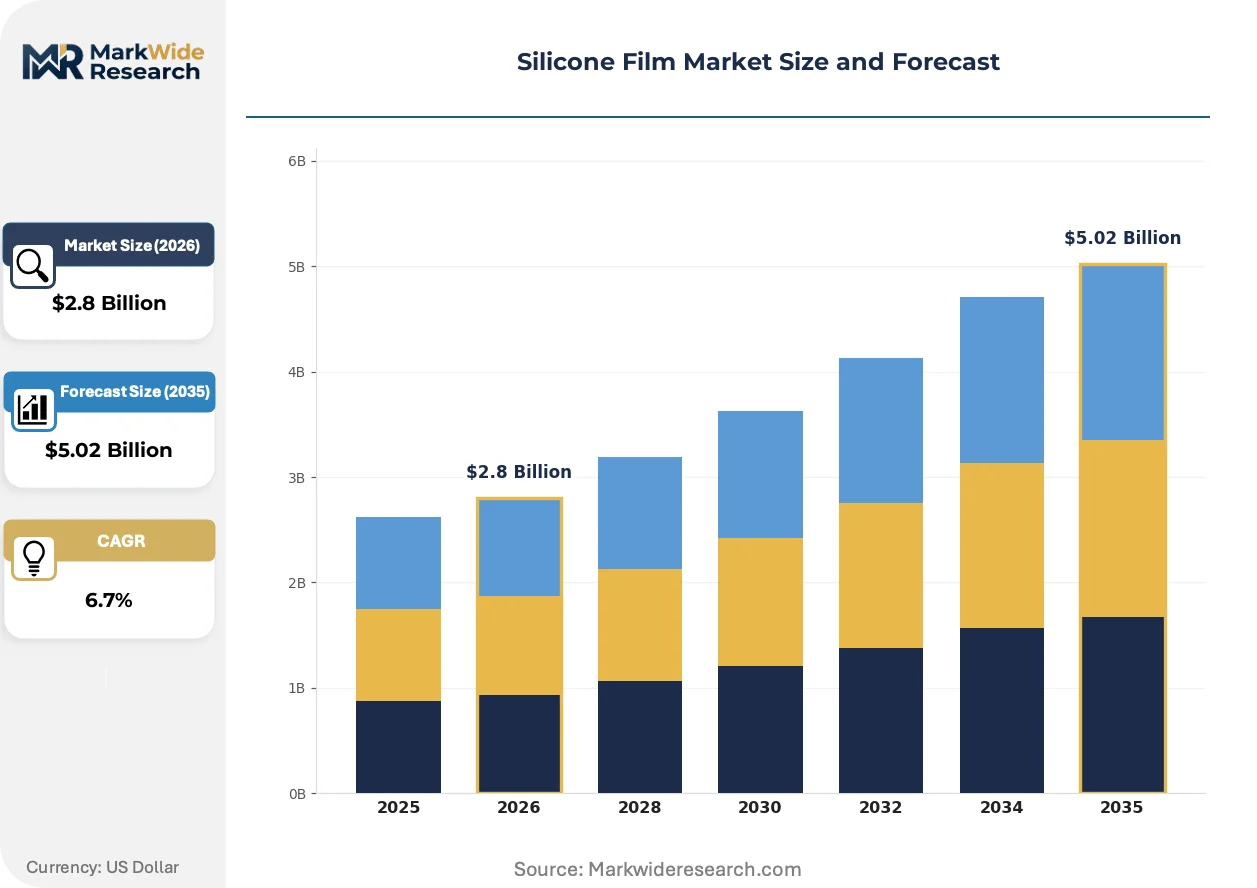
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive Film, Non-Adhesive Film, Reinforced Film, Release Liner Application: Medical Devices, Electronics, Automotive, Construction End User: Manufacturers, Distributors, Retailers, OEMs Thickness: Thin Film, Medium Film, Thick Film, Ultra-Thin Film |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Dow Inc., Wacker Chemie AG, Momentive Performance Materials Inc., Nitto Denko Corporation, Elkem ASA, Mitsubishi Chemical Corporation, Polyplex Corporation Limited, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Film Market Emerging Trajectories
Silicone film manufacturing is pivoting toward solvent-free extrusion methods and in-line metrology systems that compress thickness variation bands. These shifts are reshaping capital deployment patterns and supplier qualification protocols across medical and electronics verticals.
Plasma-enhanced chemical vapor deposition of organosilicon precursors is electrifying the formation of pinhole-free barrier layers at sub-25 micrometer thicknesses. Medical device OEMs in Germany and Switzerland are qualifying these films for implantable drug reservoirs. The technology is electrifying competitive positioning by enabling single-step coating replacement of multi-layer lamination processes.
EMA's 2023 extractables and leachables guidance revision is tightening volatility thresholds for silicone films entering pharmaceutical contact applications. European manufacturers are retrofitting curing ovens with nitrogen purge systems to reduce low-molecular-weight siloxane residuals. Implantable device suppliers in Ireland and the Netherlands are demanding batch-specific migration testing documentation that exceeds prior certification standards.
Automotive electronics buyers are consolidating silicone film procurement through tier-one module suppliers rather than direct material sourcing. This channel compression is displacing spot-market transactions with multi-year supply agreements indexed to siloxane monomer pricing. The shift is most pronounced in Germany and Japan where automotive OEMs have integrated flexible circuit specifications into platform-level design mandates.
Silicone Film Market Segmentation
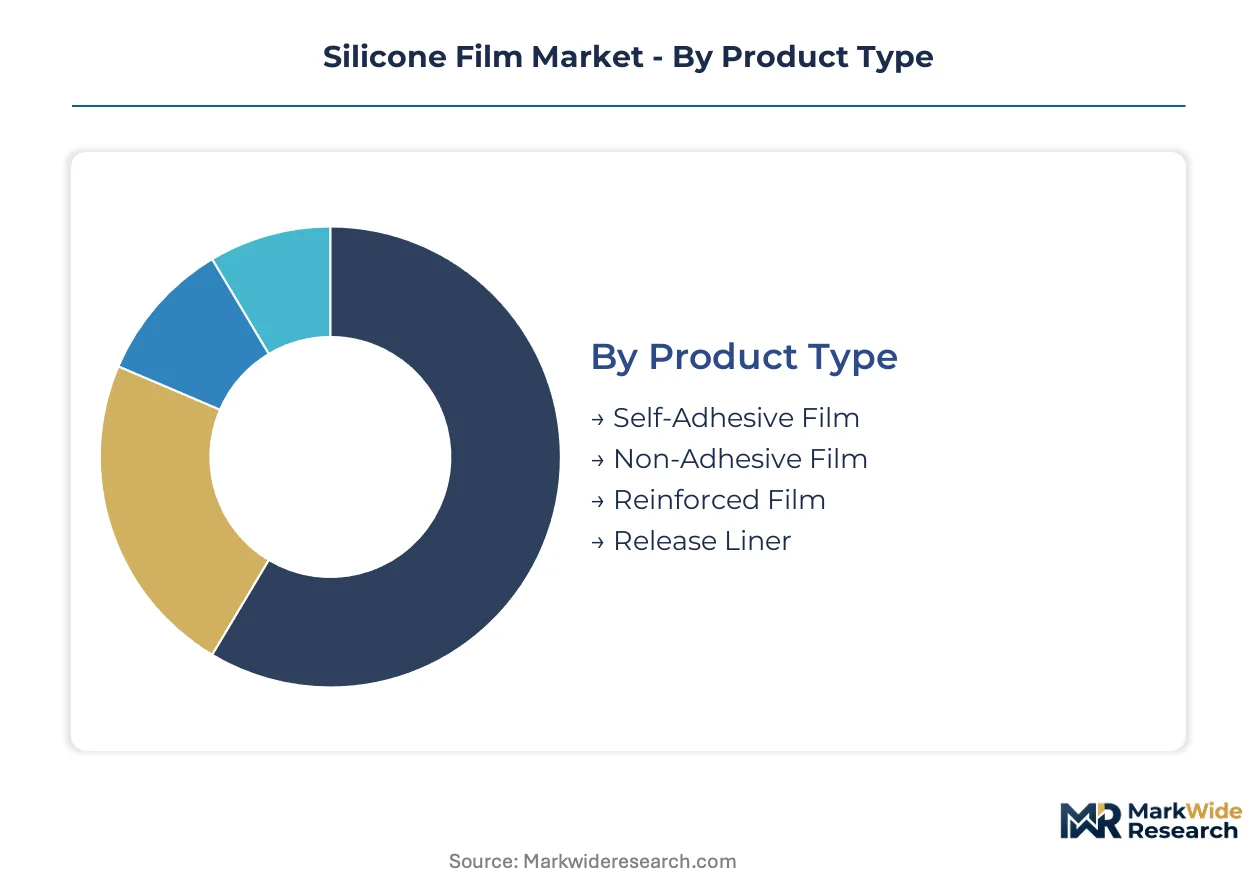
Silicone film segmentation reflects divergent certification burdens across medical, electronics, and automotive verticals. Thickness specifications and adhesive functionality determine which regulatory frameworks apply, creating distinct supplier qualification pathways.
Product Type:
FDA ISO 10993 biocompatibility testing burdens self-adhesive and non-adhesive films entering implantable and wound-contact applications, while REACH platinum catalyst restrictions apply uniformly to all European-manufactured product types.
- Self-Adhesive Film:Pressure-sensitive silicone adhesive layers laminated to PDMS substrates deliver peel strengths optimized for medical dressing fixation and electronics bonding. Demand concentrates among German wound care OEMs and Japanese flexible circuit manufacturers where residue-free removal commands formulation premiums.
- Non-Adhesive Film:Pure cross-linked PDMS layers without surface tack serve dielectric insulation and implantable barrier functions requiring inert contact surfaces. Medical device manufacturers in Switzerland and the Netherlands specify these films for drug reservoir encapsulation where adhesive contamination risks device failure.
- Reinforced Film:Woven or non-woven substrates embedded within silicone matrices enhance dimensional stability for automotive gasketing.
- Release Liner:Low-surface-energy silicone coatings on paper or film backings enable clean separation from aggressive adhesives.
Leading the category by volume: Self-Adhesive Film. Growing fastest: Ultra-thin variants across all product types.
Application:
Application segmentation tracks cost tier stratification, with medical devices commanding premium pricing for validated biocompatibility dossiers and construction representing the most price-sensitive volume tier.
- Medical Devices:Wound dressings, implantable barriers, and transdermal patch substrates demand sub-50-micrometer films with ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization clearance. CDSCO's streamlined medical device rules in India are attracting qualification investments for export-oriented manufacturing.
- Electronics:Dielectric insulation for flexible circuits and semiconductor packaging requires thermal stability exceeding 200 degrees Celsius. German automotive module suppliers specify these films for power inverter insulation where voltage breakdown resistance is critical.
- Automotive:Gasketing and vibration damping applications specify medium-thickness reinforced films.
- Construction:Weatherproofing membranes and sealant backer rods consume commodity-grade non-adhesive films.
Medical Devices generates the highest margin pool. Electronics represents the steepest expansion trajectory as flexible sensor architectures proliferate.
End User:
End user segmentation maps to supply chain position, with OEMs and manufacturers capturing direct material relationships while distributors intermediate spot-market volumes.
- Manufacturers:Film converters and laminators purchase bulk silicone film for value-added processing into medical dressings and electronic components. Japanese precision coating clusters in Gunma and Shizuoka prefectures maintain captive slitting and die-cutting operations.
- OEMs:Tier-one medical device and automotive module suppliers negotiate multi-year supply agreements indexed to siloxane monomer pricing. German automotive electronics buyers have consolidated procurement through Continental and Bosch, displacing spot-market transactions.
- Distributors:Regional stocking intermediaries serve mid-scale converters lacking direct supplier relationships.
- Retailers:Limited to consumer-grade adhesive tape and weatherstripping products.
OEMs dominate value capture through contract consolidation. Manufacturers retain volume leadership in medical and electronics verticals.
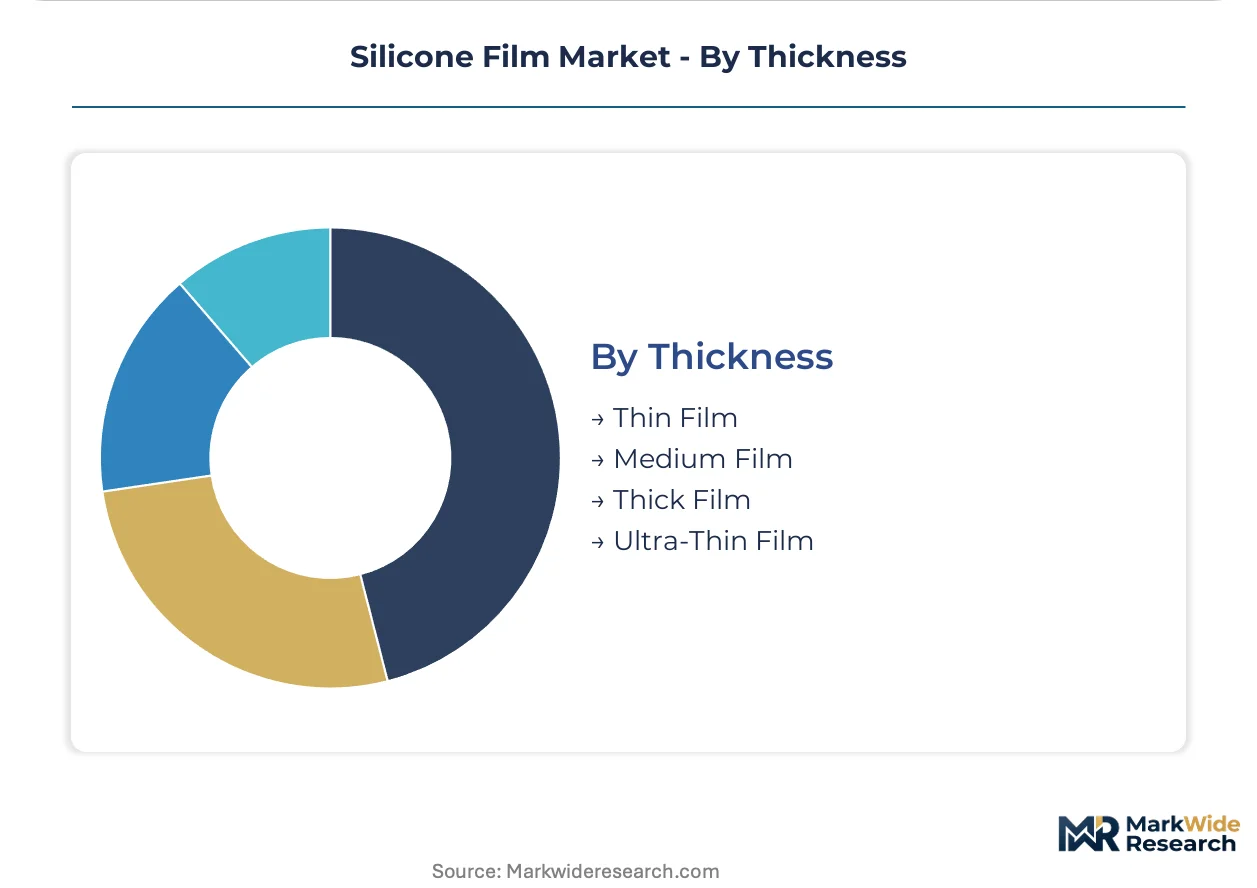
Thickness:
Thickness segmentation correlates with application maturity, with thin and medium films representing established specification ranges and ultra-thin films emerging from semiconductor packaging innovation.
- Ultra-Thin Film:Sub-25-micrometer dielectric layers manufactured via plasma-enhanced chemical vapor deposition enable pinhole-free barriers for implantable drug reservoirs and flexible sensor substrates. Swiss medical device OEMs in Basel and Zurich are qualifying these films for next-generation transdermal delivery systems.
- Thin Film:25-100 micrometer specifications balance flexibility with handling durability for wound care dressings and flexible circuit insulation. US and German healthcare systems prioritize these thicknesses for outpatient chronic wound protocols.
- Medium Film:100-300 micrometer range serves automotive gasketing and general industrial sealing.
- Thick Film:300-500 micrometer constructions provide structural cushioning and heavy-duty barrier functions.
Thin Film maintains volume dominance across medical and electronics applications. Ultra-Thin Film is climbing the fastest as semiconductor packaging demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device OEM procurement concentrates in Germany, Japan, and the United States, where precision coating clusters and biocompatibility validation infrastructure anchor silicone film demand. Electronics and automotive verticals pull capacity toward semiconductor packaging hubs and automotive module manufacturing zones.
United States
FDA's ISO 10993 biocompatibility enforcement drives qualification investments for implantable and wound-contact film applications. The agency's 18-24 month testing cycles freeze supplier switching decisions among tier-one healthcare manufacturers. Boston and Minneapolis medical device clusters specify sub-50-micrometer films for chronic wound protocols and transdermal delivery systems.
Germany
REACH platinum catalyst residue restrictions push manufacturers toward cleaner polymerization chemistries for higher-purity implantable films. ECHA's tightening limits favor integrated producers with captive monomer control and closed-loop solvent recovery. Stuttgart and Munich precision coating facilities serve Continental and Bosch with automotive electronics insulation meeting 200-degree Celsius thermal stability.
Japan
PMDA's evolving extractables guidance demands batch-level traceability systems for silicone films entering pharmaceutical contact applications. METI's semiconductor packaging initiatives accelerate ultra-thin film adoption for flexible sensor architectures. Gunma and Shizuoka prefectures maintain captive slitting and die-cutting operations for electronics converters.
India
CDSCO's streamlined medical device rules and production-linked incentive schemes attract qualification investments for export-oriented wound care manufacturing. The regulator's 2023 framework reduces import dependency timelines for critical raw materials. Gujarat and Maharashtra coating facilities are expanding cleanroom capacity to serve European and North American OEM audit requirements.
Switzerland
Swissmedic's pharmaceutical-grade documentation standards exceed prior certification thresholds for implantable device suppliers. Basel and Zurich medical technology OEMs qualify plasma-enhanced chemical vapor deposition films for next-generation drug reservoirs. The country's precision polymer processing heritage anchors specialized formulation contracts with global pharmaceutical contract manufacturers.
Silicone Film Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue solvent-free extrusion methods and in-line metrology capabilities. The market structures around integrated chemical conglomerates with captive siloxane monomer production and independent film converters dependent on spot-market feedstock. Three archetypes dominate: backward-integrated polymer giants, precision coating specialists, and regional laminators serving spot-market demand. Competitive moves concentrate on multi-year supply agreements indexed to monomer pricing and M&A targeting formulation breadth.
Within the integrated chemical tier, Dow Inc. and Shin-Etsu Chemical Co., Ltd. anchor supply security through in-house monomer production and long-term healthcare manufacturing contracts. Wacker Chemie AG exemplifies the European precision formulation archetype, competing on custom breadth across electronics and automotive accounts. These three entities represent the dominant supply-side concentration shaping procurement consolidation among medical device and automotive OEMs.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Dow Inc. |
| Wacker Chemie AG |
| Momentive Performance Materials Inc. |
| Nitto Denko Corporation |
| Elkem ASA |
| Mitsubishi Chemical Corporation |
| Polyplex Corporation Limited |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Plasma-enhanced chemical vapor deposition adoption is compressing thickness variation bands while concentrating capital deployment among integrated producers with captive siloxane monomer control, simultaneously reshaping cost economics and supplier tier concentration across medical and electronics verticals.
Pricing Analysis
Volume-mass construction applications trade at commodity margins while medical-grade films with ISO 10993-5 cytotoxicity clearance command substantial premiums. Pricing stratifies across premium, standard, and economy tiers based on certification grade and customization level. Cost compression in construction-grade non-adhesive films is intensifying because polyimide substitution in high-heat electronics is displacing silicone in select dielectric applications. Construction buyers exhibit highest price sensitivity; Swiss implantable device OEMs show lowest.
Supply Chain Analysis
Dimethylsiloxane feedstock rests on integrated chemical conglomerates in Germany, Japan, and the United States with captive monomer production. Precursor chemicals draw from specialty silicone polymer manufacturers and platinum catalyst suppliers. Single-source vulnerability concentrates in dimethylsiloxane monomer where independent film processors lack margin autonomy. Distribution runs through tier-one module suppliers rather than direct material sourcing for automotive electronics buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone film supply is tightening around qualified biocompatibility dossiers, with platinum catalyst purification capacity acting as the binding constraint propping medical-grade pricing premiums.
For Market Incumbents: Anchor long-term supply agreements with tier-one healthcare manufacturers through validated ISO 10993 track records. Expand captive monomer control or secure fixed-price dimethylsiloxane offtake to defend against feedstock volatility. Invest in nitrogen purge curing systems ahead of EMA extractables guidance enforcement to preempt regulatory disqualification. For New Entrants and Emerging Players: Direct-to-pharma contract manufacturing relationships offer the most penetrable route for specialized film formulation capabilities. Target CDSCO-qualifying production in Gujarat and Maharashtra for export-oriented wound care manufacturing. Pursue solvent-free extrusion technology partnerships to bypass incumbent capital advantages in conventional casting capacity. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking biocompatibility certification infrastructure. Long-term viability favors precision coating specialists with pharmaceutical-grade documentation systems deployable across multiple regulatory jurisdictions. Watch EMA batch-level leachables enforcement as the inflection indicator for documentation-capability valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer | Captive dimethylsiloxane supply secures margin autonomy against feedstock volatility for German and Japanese producers. |
| Long-term Supply Agreement with Healthcare OEMs | Multi-year contracts indexed to monomer pricing lock in volume commitments from Boston and Minneapolis medical device clusters. |
| Green Manufacturing Transition | Solvent-free extrusion methods with closed-loop recovery systems create first-mover positioning under EU Green Deal mandates. |
| Joint Venture for Regional Production | Cleanroom capacity partnerships in Gujarat serve CDSCO-qualifying export manufacturing for European and North American OEM audits. |
| Capacity Expansion in Ultra-Thin Film | Sub-25-micrometer dielectric layer production captures semiconductor packaging demand from METI-backed flexible sensor initiatives. |
Methodological Framework
Independent corroboration across regulatory filing databases, trade flow records, and capital expenditure disclosures underwrites the qualitative findings. Primary interviews with medical device procurement managers, silicone film plant engineers, pharmaceutical contract manufacturing executives, and automotive electronics sourcing leads combined with secondary validation from FDA 510(k) filings, ECHA REACH registration dossiers, CDSCO medical device approvals, and SEC 10-K supply chain disclosures. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application vertical, thickness specification, and regional regulatory cluster. CAGRs derive from regression analysis against semiconductor packaging investment cycles, chronic wound prevalence trajectories, and automotive electronics platform standardization timelines. Forecast inputs incorporate platinum catalyst purity requirements and extractables testing documentation burdens.
The model holds under stable regulatory divergence between FDA and EMA frameworks; deviation in REACH catalyst residue limits or ISO 10993 testing protocol revisions would shift qualification timelines and capacity allocation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Carrageenan Film Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Barium Borate Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Organic Scintillators Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Recyclable Thermosets Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
India Collagen Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Teschemacherite Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Special Graphite Market