
 Refrigeration Packaging Market | 2026-2036
Refrigeration Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigeration Packaging Market Analytics
Multi-source procurement for temperature-controlled packaging materials is expanding as pharmaceutical and food service buyers diversify supplier portfolios. Sealed Air Corporation leverages its film technology leadership to anchor North American pharmaceutical contracts. Sofrigam competes through specialized passive system design for European vaccine lanes. Cold Chain Technologies dominates in gel pack customization for clinical trial logistics.
Refrigeration packaging encompasses engineered thermal protection systems that maintain specified temperature ranges, typically employing polyurethane or expanded polystyrene insulation layers with phase-change coolants to preserve product integrity from manufacture through last-mile delivery. Its primary commercial purpose centers on eliminating temperature excursions for biologics, perishables, and sensitive cosmetics across extended transit durations. Insulated boxes and gel packs lead product type revenue due to standardized pharmaceutical qualification protocols, while cold chain monitoring technology represents the fastest-expanding segment as real-time IoT tracking becomes a contractual requirement. Passive systems retain the largest installed base, though active systems command premium margins in ultra-cold biologics applications.
The EPA regulates refrigerant emissions under SNAP and AIM Act frameworks, restricting hydrofluorocarbon content in insulated packaging components and accelerating demand for low-global-warming-potential alternatives. The EU F-Gas Regulation and REACH chemical standards further constrain material formulations, compelling manufacturers to requalify supply chains for European market access. Stakeholders must monitor evolving SAMR standards in China and anticipate convergence between national refrigerant phase-down schedules and cold chain packaging certification requirements.
Market Dynamics
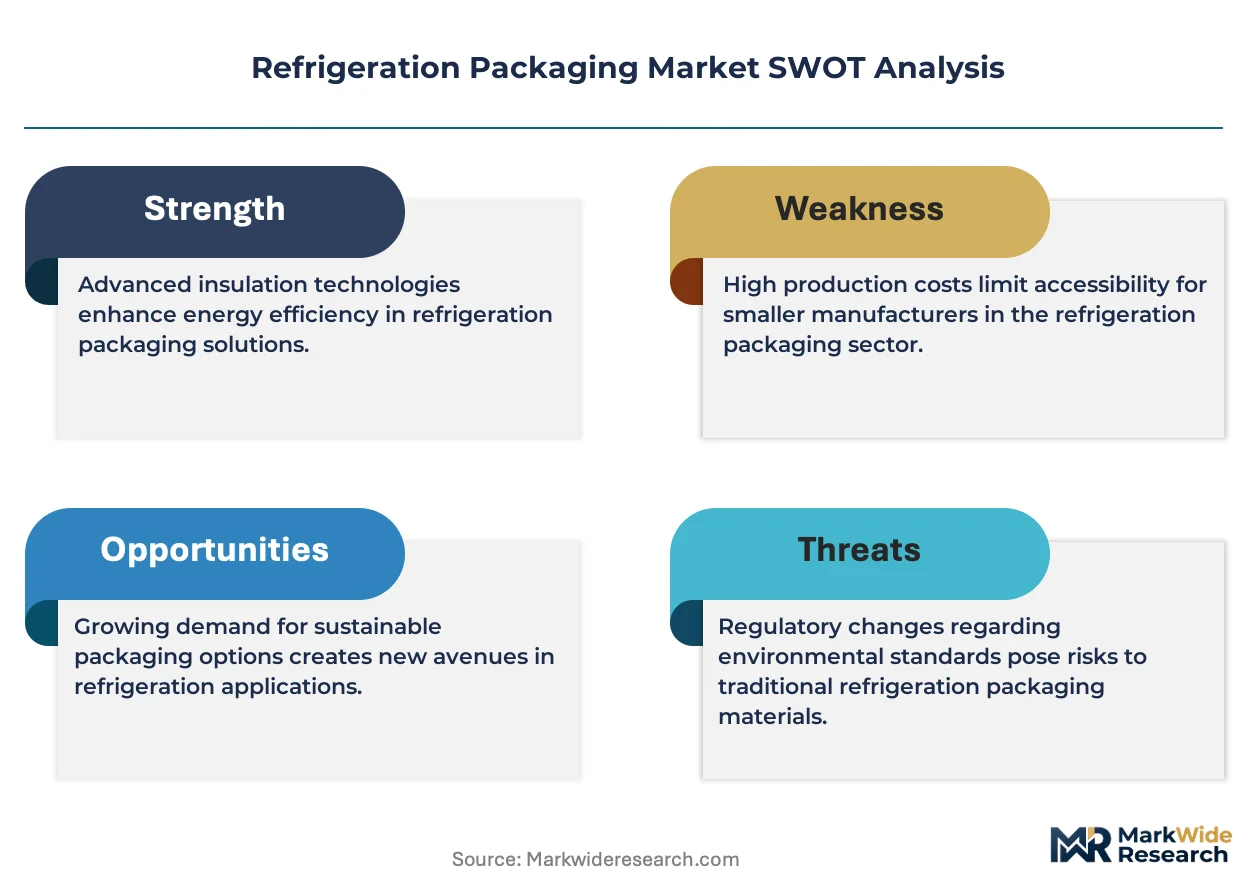
The EPA's AIM Act refrigerant phase-down schedule and the EU F-Gas Regulation are forcing simultaneous reformulation of insulation materials across pharmaceutical and food cold chains, compressing supplier qualification timelines while expanding compliance costs.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapies requiring ultra-cold storage between minus 60°C and minus 150°C are multiplying clinical trial volumes. Cryogenic shippers with liquid nitrogen retention layers are capturing qualification mandates from CDSCO in India and FDA in the United States.
- EU F-Gas Regulation:The 2024 ban on high-GWP blowing agents in polyurethane insulation is accelerating demand for pentane and hydro-olefin formulations. German pharmaceutical corridors are retrofitting passive packaging fleets to maintain REACH compliance.
- Phase-change material innovation:Eutectic salt hydrates with tighter melting point tolerances are displacing water-based gel packs in vaccine distribution. India's Universal Immunization Program is standardizing these formulations for last-mile rural delivery.
Market Restraints
- Petrochemical input volatility:Isocyanate and polyol feedstock costs for polyurethane insulation fluctuate with crude oil benchmarks. Asian packaging manufacturers face margin compression when hedge coverage expires.
- Specialized resin supply concentration:Expanded polystyrene bead production for molded coolers concentrates in Northeast Asian petrochemical complexes. Buyers face allocation risk during regional turnaround seasons.
- Active system energy density limits:Compressor-based portable units for ultra-cold biologics require lithium battery packs that face IATA dangerous goods restrictions. Air freight acceptance delays constrain emergency response deployment.
Strategic Opportunities
- Sub-Saharan Africa vaccine networks:Gavi and UNICEF cold chain expansion programs are creating demand for passive systems with 120-hour autonomy. Local assembly partnerships bypass import duty structures in Nigeria and Kenya.
- Reusable shipper models:Return logistics infrastructure for qualified thermal packaging is maturing in European pharmaceutical hubs. Deposit-based circular systems reduce per-shipment material costs for high-frequency biologics lanes.
- IoT sensor integration:Real-time temperature loggers with cellular connectivity are becoming contractual requirements from FDA-regulated biopharma sponsors. Hardware-software bundles command recurring revenue streams.
Industry Challenges
- Thermal engineer scarcity:Computational fluid dynamics modeling for custom shipper design requires specialized heat transfer expertise. Contract manufacturers compete for talent against automotive and aerospace sectors.
- Qualification protocol duration:ISTA 7E and WHO PQS thermal testing cycles extend 8-14 weeks. Product launch timelines compress when sponsor protocols demand seasonal lane studies across multiple climate zones.
- Legacy ERP integration:Cold chain monitoring platforms must interface with established pharmaceutical track-and-trace systems. API standardization gaps between sensor vendors and enterprise software create deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigeration Packaging Market |
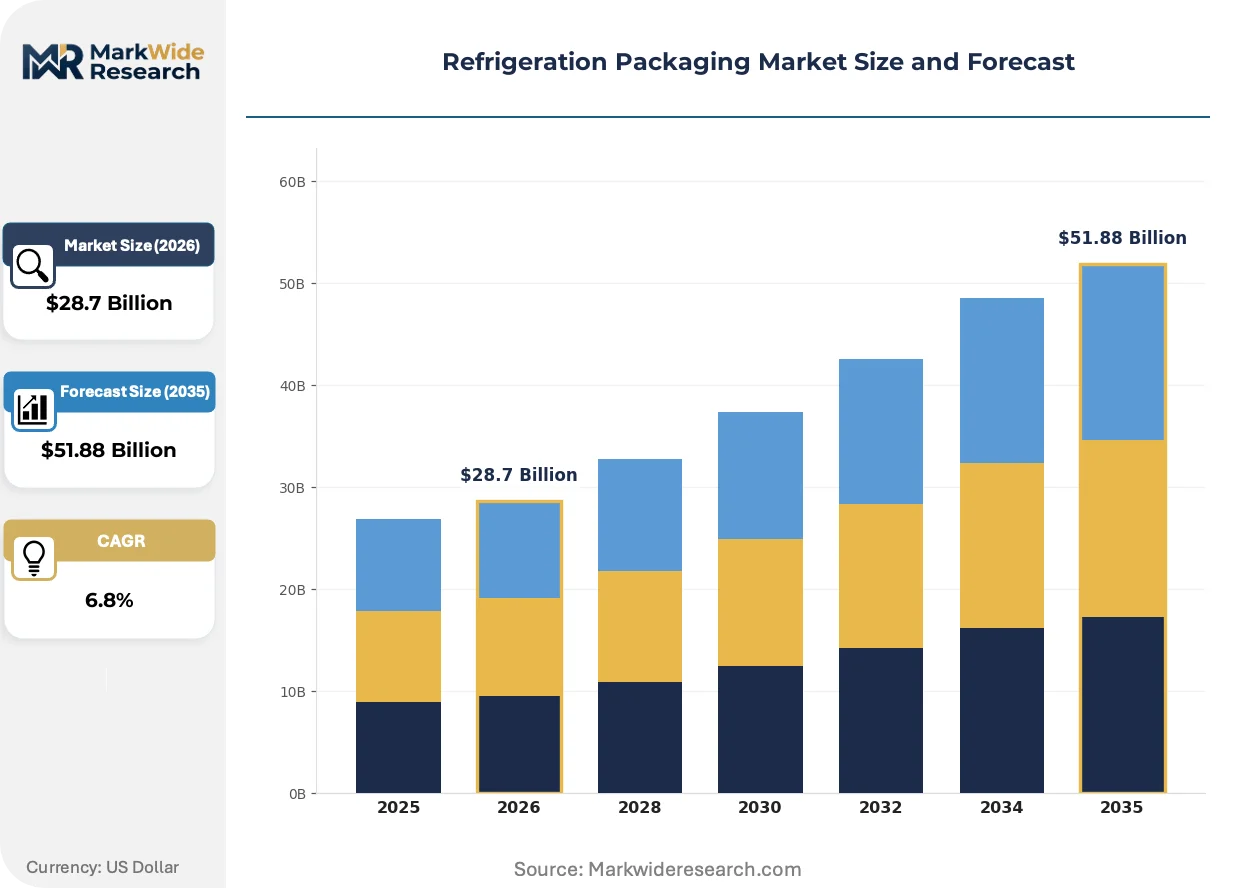
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Boxes, Gel Packs, Thermal Pallets, Coolants End User: Food Service, Pharmaceuticals, Cosmetics, E-Commerce Material: Polyurethane, Expanded Polystyrene, Polyethylene, Film Technology: Active Systems, Passive Systems, Refrigerated Transport, Cold Chain Monitoring |
| Companies Covered | Cold Chain Technologies, Sonoco Products Company, Sealed Air Corporation, Peli BioThermal, Sofrigam, Softbox Systems Ltd, Cryopak, Nordic Cold Chain Solutions, Pactiv LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigeration Packaging Market Evolving Landscape
Real-time visibility infrastructure and sustainable material substitution are converging to redefine performance benchmarks. Pharmaceutical sponsors now specify both thermal protection duration and carbon footprint metrics in procurement criteria.
Machine learning algorithms embedded in cloud-connected temperature loggers are automating excursion prediction and proactive intervention routing. Large biopharma sponsors with centralized distribution operations are deploying these systems across international clinical trial depots. The technology is automating manual monitoring workflows and compressing quality assurance staffing ratios.
REACH chemical restrictions and the EU Green Deal carbon border adjustment mechanism are tightening specifications for insulation blowing agents and film laminates. Manufacturers serving European pharmaceutical buyers must document supply chain emissions and material recyclability. Small and mid-sized passive system suppliers face requalification costs that favor integrated producers with in-house polymer compounding.
Biopharma procurement teams are consolidating vendor panels and demanding outcome-based thermal performance guarantees rather than component specifications. Third-party logistics providers with captive packaging engineering capabilities are displacing standalone material suppliers in sponsor RFP processes. This consolidation is most visible in United States and German pharmaceutical corridors where qualification history carries premium weight in contract awards.
Refrigeration Packaging Market Segmentation
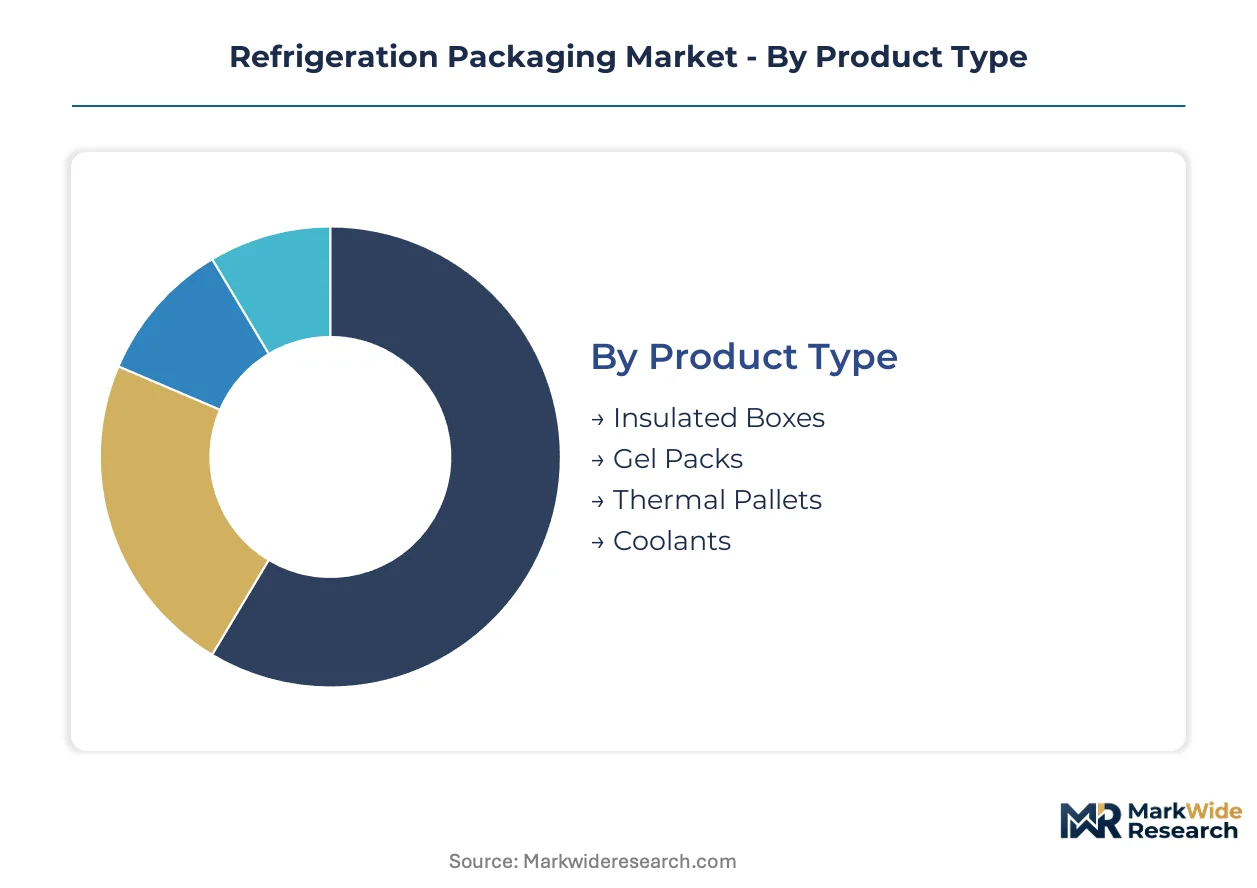
Refrigeration packaging segmentation reflects divergent performance requirements across temperature ranges, transit durations, and regulatory jurisdictions. Procurement teams prioritize segments with established qualification protocols while emerging technologies reshape competitive boundaries.
Product Type:
Upgrade cycles accelerate as pharmaceutical sponsors demand longer thermal protection durations and lighter shipper weights for air freight optimization.
- Insulated Boxes:Multi-layer polyurethane or expanded polystyrene enclosures with precision-molded cavities for vial and syringe configurations. German pharmaceutical corridors specify these for intercontinental biologics lanes requiring 96-120 hour autonomy.
- Gel Packs:Phase-change materials encased in puncture-resistant polymer films, calibrated to specific melting points for vaccine cold chains. India's Universal Immunization Program standardizes eutectic salt hydrate formulations for last-mile rural distribution where electricity is intermittent.
- Thermal Pallets:Large-format insulated platforms for bulk pharmaceutical shipments and consolidated food service deliveries.
- Coolants:Dry ice, liquid nitrogen, and engineered phase-change materials for ultra-cold biologics requiring minus 60°C to minus 150°C maintenance.
Volume placements concentrate in Insulated Boxes; the faster expansion belongs to Gel Packs.
End User:
Application-specific qualification protocols create divergent margin profiles and supplier consolidation patterns across customer categories.
- Pharmaceuticals:Temperature-sensitive biologics, vaccines, and cell therapies demanding ISTA 7E and WHO PQS thermal validation. FDA-regulated sponsors now specify real-time IoT monitoring as a contractual requirement for international clinical trial logistics.
- Food Service:Prepared meal delivery and perishable ingredient protection with shorter duration requirements. E-commerce subscription models drive demand for lightweight, recyclable passive systems.
- Cosmetics:Sensitive skincare and probiotic formulations requiring stable temperature bands.
- E-Commerce:Cross-border perishable fulfillment with variable last-mile conditions.
Procurement concentration sits with Pharmaceuticals; Cosmetics exhibits the steepest expansion trajectory as premium skincare brands enter direct-to-consumer cold chain distribution.
Material:
Regulatory phase-down schedules for high-global-warming-potential blowing agents force simultaneous reformulation across insulation categories.
- Polyurethane:Spray or molded foam systems with isocyanate-polyol chemistry, dominant in pharmaceutical shippers for superior R-value per unit thickness. EU F-Gas Regulation mandates transition from HFC to pentane and hydro-olefin blowing agents.
- Expanded Polystyrene:Bead-molded insulation for cost-sensitive food service and short-duration pharmaceutical applications. Production concentrates in Northeast Asian petrochemical complexes, creating allocation risk during regional turnaround seasons.
- Polyethylene:Rotomolded or foam sheet configurations for reusable shipper programs.
- Film:Multi-layer laminates for gel pack enclosures and vapor barrier protection.
Polyurethane commands premium placement in pharmaceutical qualification; Polyethylene expands most quickly through reusable circular economy models.
Technology:
Customer procurement patterns bifurcate between capital-intensive active systems and operational-expense-focused passive alternatives.
- Passive Systems:Insulated containers with phase-change coolants requiring no external power, dominant in vaccine distribution and clinical trial logistics. Gavi and UNICEF programs in Sub-Saharan Africa specify 120-hour autonomous designs for unreliable infrastructure environments.
- Cold Chain Monitoring:Real-time temperature loggers with cellular connectivity and cloud-based excursion alerting. Large biopharma sponsors deploy these across international depot networks, automating quality assurance workflows.
- Active Systems:Compressor-based or thermoelectric portable units with precise temperature control for ultra-cold biologics.
- Refrigerated Transport:Vehicle-integrated cooling for trunk logistics and distribution center transfers.
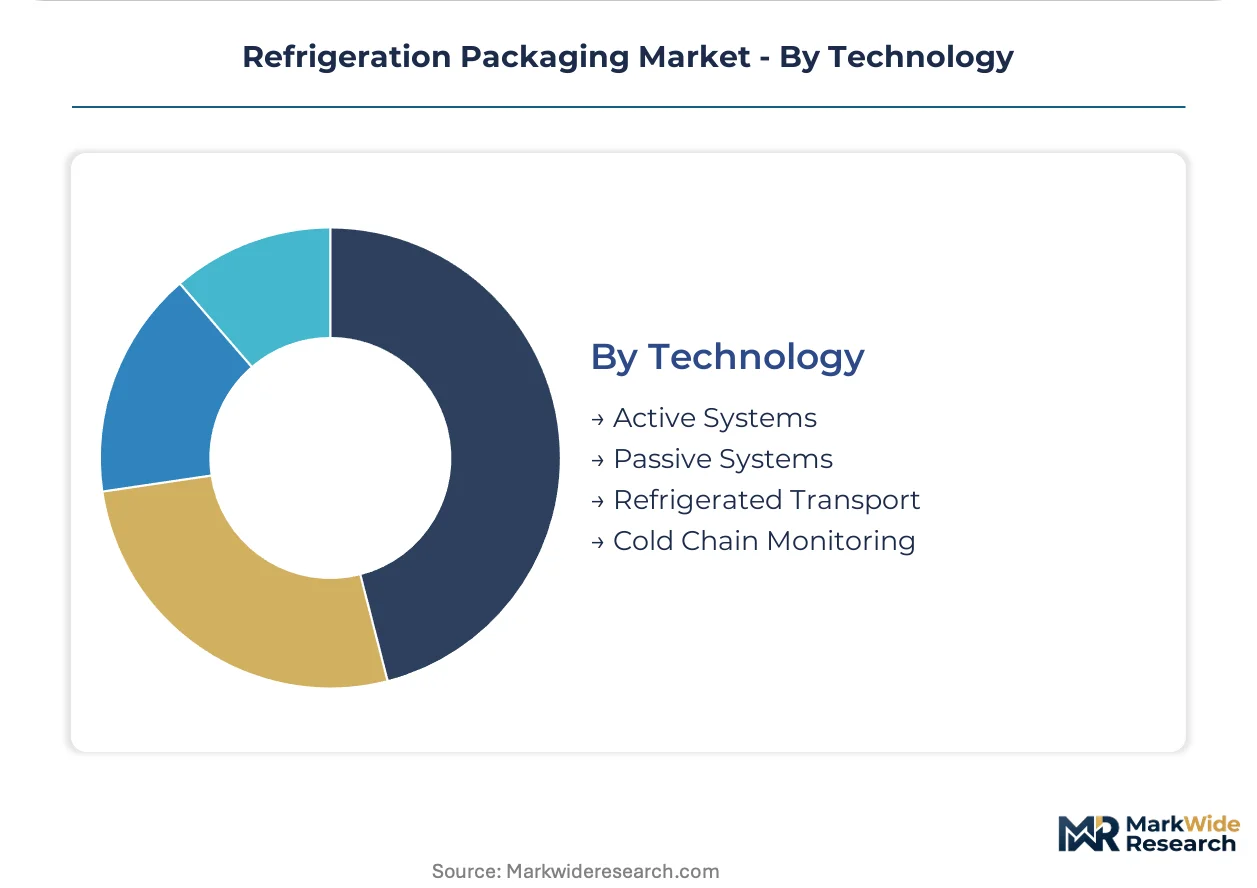
Passive Systems anchor installed base volume; Cold Chain Monitoring climbs the fastest as IoT hardware-software bundles capture recurring revenue streams from FDA-regulated sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane feedstock concentration in Northeast Asian petrochemical corridors shapes manufacturing economics across temperature-controlled packaging supply chains. Isocyanate and polyol availability from South Korean and Japanese chemical complexes influences regional production costs and export competitiveness.
United States
Biologics manufacturing expansion in Massachusetts and North Carolina drives demand for qualified thermal shippers. The EPA's AIM Act refrigerant phase-down schedule accelerates reformulation of polyurethane insulation blowing agents. Greater Boston pharmaceutical clusters now specify real-time IoT monitoring as standard for international clinical trial logistics.
Germany
Rhein-Main and Rhine-Ruhr pharmaceutical corridors anchor European demand for passive cold chain systems. The EU F-Gas Regulation mandates transition from HFC to pentane and hydro-olefin formulations in molded insulation. Baden-Württemberg packaging engineering firms are retrofitting qualification protocols to maintain REACH compliance for biologics exports.
India
Universal Immunization Program scale-up and CDSCO regulatory alignment create demand for 120-hour autonomous passive systems. Eutectic salt hydrate phase-change materials are standardizing for last-mile rural vaccine distribution. Hyderabad and Bengaluru pharmaceutical manufacturing hubs are qualifying thermal packaging for temperature-sensitive biologics exports.
China
SAMR evolving standards on refrigerant emissions and cold chain packaging certification drive material requalification cycles. Yangtze River Delta biologics manufacturing expansion requires qualified ultra-cold shippers for cell therapy exports. Shanghai-based logistics providers are integrating domestic temperature monitoring platforms with international sponsor track-and-trace systems.
Brazil
ANVISA pharmaceutical distribution regulations and tropical climate conditions necessitate extended-duration thermal protection systems. São Paulo state pharmaceutical manufacturing growth imports qualified passive packaging for temperature-sensitive exports. Local assembly partnerships are emerging to bypass import duty structures for Gavi-supported vaccine distribution programs.
Refrigeration Packaging Market Competitive Landscape
Global majors compete with regional champions across qualification history and geographic proximity to pharmaceutical manufacturing clusters. The vendor base stratifies between integrated material compounders, specialized passive system designers, and technology-enabled monitoring platforms. Three archetypes dominate: film technology leaders anchoring North American contracts, European passive system specialists, and gel pack customization experts serving clinical trial logistics. Competitive dynamics center on M&A for qualification asset accumulation and strategic partnerships for circular economy return logistics infrastructure.
Within the integrated material technology tier, Sealed Air Corporation and Sonoco Products Company exemplify packaging conglomerates with captive polymer capabilities. Cold Chain Technologies and Sofrigam occupy distinct specialization positions—one in gel pack customization for trial logistics, the other in European vaccine lane passive design. These four names represent the competitive spectrum from scale-driven material integration to geography-focused engineering expertise.
| Leading Market Players |
|---|
| Cold Chain Technologies |
| Sonoco Products Company |
| Sealed Air Corporation |
| Peli BioThermal |
| Sofrigam |
| Softbox Systems Ltd |
| Cryopak |
| Nordic Cold Chain Solutions |
| Pactiv LLC |
| Others |
Value Network & Pricing Analysis
Thermal engineering talent scarcity in Baden-Württemberg and Greater Boston compresses supplier margins on complex custom shipper designs, widening the spread between premium qualified systems and commodity passive packaging. Labor-cost differentials between European engineering hubs and Asian manufacturing centers stratify pricing tiers, with REACH-compliant polyurethane formulations commanding sustained premiums over standard EPS alternatives.
Pricing Analysis
Warranty and qualification-bundling separate premium pharmaceutical-grade systems from unbundled food-service packaging, with ISTA 7E validation and WHO PQS certification embedded in contracted rates rather than line-item add-ons. Three-tier pricing structure across premium qualified, standard validated, and economy unvalidated levels reflects certification depth and thermal autonomy duration. Pricing pressure stems from petrochemical feedstock volatility in isocyanate and polyol markets, squeezing margins on fixed-price annual contracts. Food service buyers exhibit highest price sensitivity, while FDA-regulated biopharma sponsors prioritize performance guarantees over unit cost.
Supply Chain Analysis
Reverse logistics infrastructure for reusable shipper refurbishment concentrates in Rhine-Ruhr and Greater Boston pharmaceutical hubs, with deposit-based circular systems capturing high-frequency biologics lanes. Polyurethane feedstock production centers on South Korea, Japan, and Germany, drawing from isocyanate and polyol supply chains tethered to regional petrochemical complexes. Single-source vulnerability concentrates in Northeast Asian expanded polystyrene bead manufacturing, exposing buyers to allocation risk during turnaround seasons. Distribution runs through third-party logistics providers with captive packaging engineering capabilities, displacing standalone material suppliers in sponsor procurement processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refrigeration packaging market functions as a cost-of-compliance arena where EU F-Gas Regulation phase-down schedules erect substantial barrier-to-entry moats. REACH chemical standards and refrigerant emission mandates favor incumbent players with established requalification histories and in-house polymer compounding capabilities.
For Market Incumbents: Anticipate margin compression from emerging Asian manufacturers by deepening backward integration into polyurethane blowing agent formulations and securing multi-year REACH-compliant raw material offtakes. Consolidate qualification assets through targeted acquisition of regional passive system designers with established WHO PQS portfolios. Prioritize circular economy infrastructure investment in European pharmaceutical corridors to defend against reusable shipper competitors. For New Entrants and Emerging Players: Enter via local assembly partnerships in Sub-Saharan Africa vaccine networks, where Gavi and UNICEF program specifications create demand for 120-hour autonomous passive systems with reduced import duty exposure. Target India's Universal Immunization Program expansion as the most penetrable geography, leveraging CDSCO regulatory alignment requirements to establish qualification credentials. Pursue hardware-software bundling strategies with domestic temperature monitoring platforms to differentiate from commodity gel pack suppliers. For Investors and Strategic Acquirers: The window for entry favors integrated material compounders with captive polymer capabilities and established pharmaceutical qualification histories over standalone passive system assemblers. Long-term viability hinges on regulatory compliance asset accumulation rather than manufacturing scale alone. Monitor SAMR refrigerant emission standard evolution in China as the critical inflection signal for supply chain reconfiguration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Formulations | EU F-Gas Regulation compliance secures premium pharmaceutical contract access against reformulation-lagged competitors. |
| Circular Economy Return Logistics Infrastructure | Deposit-based reusable shipper systems reduce per-shipment costs for high-frequency biologics lanes in European hubs. |
| IoT Sensor Hardware-Software Bundling | Real-time cellular temperature loggers capture recurring revenue streams from FDA-regulated clinical trial sponsors. |
| Local Assembly Partnerships in Sub-Saharan Africa | Gavi-supported vaccine networks bypass import duty structures while meeting 120-hour autonomy specifications. |
| REACH-Compliant Material Requalification | Preemptive polyurethane formulation transitions maintain European market access under tightening chemical standards. |
Research Methodology
Independent corroboration across thermal packaging engineering directors, pharmaceutical supply chain executives, and cold chain logistics operators underwrites the qualitative findings in this study. Primary interviews with plant managers at polyurethane compounding facilities, procurement leads at CDSCO-regulated Indian manufacturers, and qualification specialists at ISTA-certified testing laboratories combined with secondary validation from EPA AIM Act filings, EU ECHA regulatory databases, and WHO PQS prequalified product listings. Bottom-up demand modeling across temperature range segments and top-down supply-side capacity assessments triangulate volume estimates.
Comparable-period anchoring to historical pharmaceutical cold chain investment cycles and biologics pipeline expansion patterns structured the forecast window across the analysis window. Segmentation modeling incorporated product type, end-use application, material chemistry, and technology architecture dimensions, with thermal autonomy duration and regulatory jurisdiction clusters as industry-specific stratifiers. CAGRs derived from curve-fitting historical qualification protocol adoption rates against projected biologics manufacturing capacity additions, with isocyanate feedstock cost indices and refrigerant phase-down schedules as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petrochemical price spikes or accelerated refrigerant regulation timelines. Practitioners should monitor SAMR standard evolution, EU carbon border adjustment mechanism implementation, and cell therapy ultra-cold storage protocol proliferation for early signals of demand inflection or supply chain reconfiguration requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
North America Passive Temperature Controlled Packaging Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
China Cold Chain Market