
 Cold Chain Market | 2026-2036
Cold Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Market Intelligence
IoT-enabled real-time temperature monitoring is narrowing the gap between warehouse intelligence and in-transit visibility across pharmaceutical corridors. Lineage Logistics leverages automated cold storage robotics to sustain throughput advantages in high-velocity frozen food hubs. Americold Logistics anchors North American capacity through controlled rail and intermodal networks.
Cold chain denotes the integrated supply chain system maintaining precise thermal conditions—typically between -80°C and +25°C depending on product sensitivity—through refrigerated transport, climate-controlled warehousing, and validated packaging to preserve potency, safety, and shelf life of temperature-labile goods. The frozen temperature segment dominates volume throughput in food logistics, while biologics within product type command premium margin pools due to stringent stability windows and qualification protocols. Pallet shippers in packaging type are gaining share in lane-specific pharmaceutical distribution where lane-risk mapping drives thermal packaging selection.
The FDA enforces Current Good Manufacturing Practice and Good Distribution Practice standards that mandate continuous temperature documentation for drug shipments, while the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants and forces cold storage operators toward natural refrigerant retrofits. Health Canada and the EU's EMA maintain mutual recognition frameworks that harmonize validation protocols but create compliance complexity for multi-jurisdiction operators. Stakeholders must weigh refrigerant transition timelines against warehouse retrofit cycles when committing capital to new storage facilities.
Market Dynamics
Biologics manufacturing expansion is forcing pharmaceutical distributors to rebuild warehouse networks around ultra-low temperature corridors, compressing investment cycles from ten years to five.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants accelerates natural refrigerant retrofits in cold storage facilities, creating replacement demand for ammonia and CO2-based systems.
- Cell and gene therapies:Personalized medicine pipelines require cryogenic logistics infrastructure that did not exist at commercial scale a decade ago.
- Direct-to-consumer frozen delivery:Food retail consolidation in the United States drives automation investments in last-mile refrigerated fulfillment centers.
Market Restraints
- Copper and aluminum input volatility:Refrigeration equipment manufacturers face margin compression from base metal price swings that track energy commodity cycles.
- Specialized compressor supply concentration:Precision cooling systems for pharmaceutical applications depend on a narrow supplier base concentrated in Germany and Japan.
- Natural refrigerant toxicity constraints:Ammonia-based systems face siting restrictions near population centers, limiting urban warehouse retrofit options.
Strategic Opportunities
- India's pharmaceutical export corridors:Vaccine manufacturing hubs in Hyderabad and Pune lack sufficient validated cold chain infrastructure for temperature-sensitive biologic exports.
- Passive thermal packaging convergence:Phase-change materials combined with vacuum-insulated panels enable lane-specific qualification protocols that reduce active refrigeration dependency.
- US Inflation Reduction Act biomanufacturing incentives:Domestic production subsidies for advanced therapies create demand for regional cryogenic distribution nodes.
Industry Challenges
- Qualified personnel scarcity:Thermal validation engineers and refrigeration technicians with pharmaceutical GDP certification command premium wages that strain facility operating budgets.
- Legacy warehouse management system integration:IoT sensor networks require middleware layers to communicate with decades-old inventory platforms still dominant in third-party logistics.
- Multi-jurisdiction qualification timelines:Simultaneous FDA, EMA, and Health Canada validation protocols extend facility commissioning by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Chain Market |
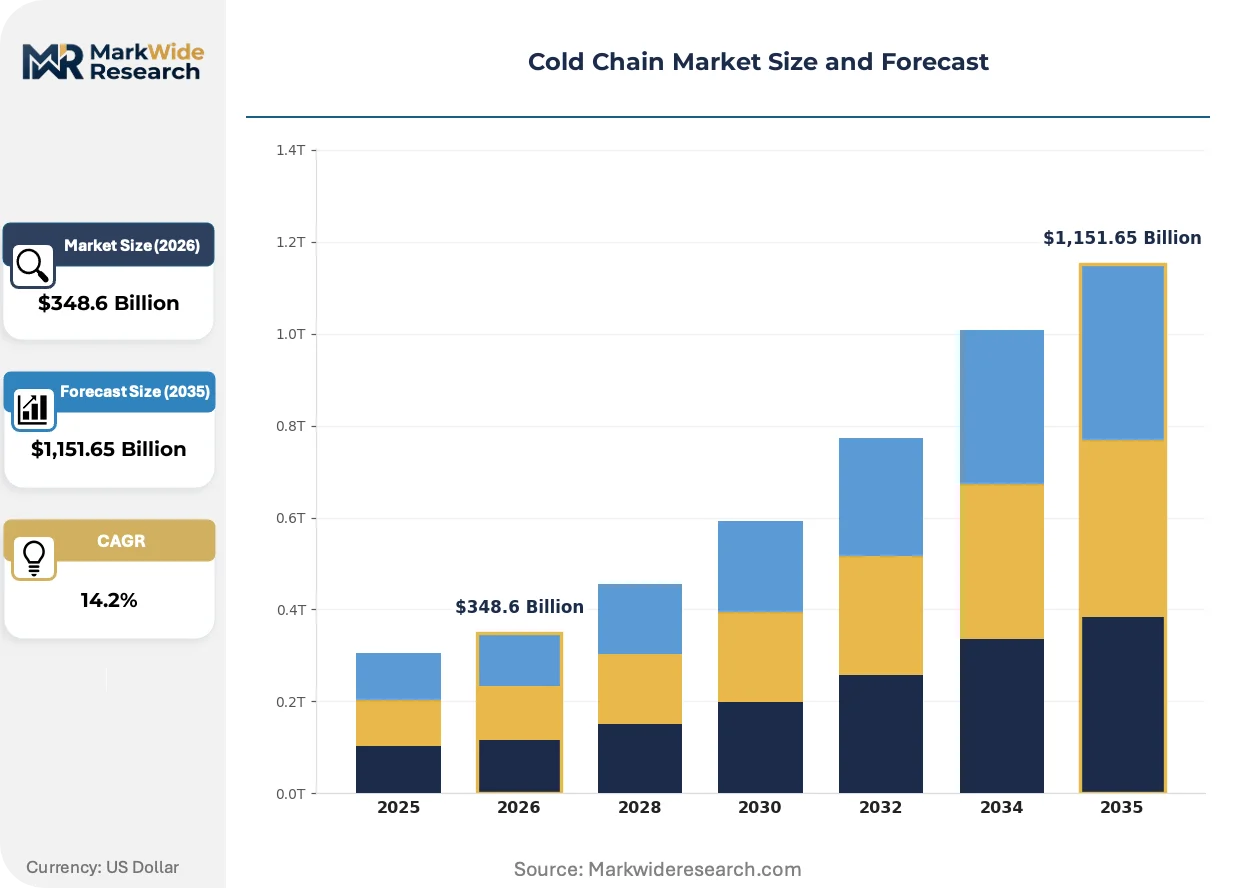
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $1,151.65 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Temperature Type: Chilled, Frozen, Ambient, Warm Product Type: Pharmaceuticals, Food & Beverages, Biologics, Chemicals Packaging Type: Containers, Pallet Shippers, Insulated Boxes, Refrigerated Trucks Storage Facility Type: Cold Storage Warehouses, Refrigerated Distribution Centers, Blast Freezers, Ice Cream Plants |
| Companies Covered | Americold Logistics, Lineage Logistics, Nichirei Corporation, Burris Logistics, A.P. Moller - Maersk, United States Cold Storage, Tippmann Group, NewCold, Constellation Cold Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Market Strategic Shifts & Innovations
Digital twin modeling of thermal performance is compressing packaging qualification cycles from months to weeks, while refrigerant chemistry shifts and procurement restructuring redraw competitive boundaries.
Phase-change material formulations is hybridizing around eutectic salt hydrates and bio-based paraffins that maintain tighter temperature bands than gel packs. Pharmaceutical shippers in high-lane-risk corridors are adopting these systems for international distribution. The technology is hybridizing active and passive cooling approaches, enabling longer transit windows without dry ice.
The EU F-Gas Regulation mandates an eighty percent reduction in hydrofluorocarbon emissions by 2030, forcing cold storage operators toward ammonia, CO2, and hydrocarbon alternatives. Equipment manufacturers face redesign cycles that invalidate prior certification frameworks. Frozen food logistics in Germany and the Netherlands is responding fastest, driven by national building codes that anticipate the EU timeline.
Consolidated buying by national pharmacy chains and group purchasing organizations is compressing contract renewal cycles from three years to annual negotiations. Third-party logistics providers face margin pressure as procurement teams unbundle transportation from storage and demand real-time visibility guarantees. This pattern is most visible in the United States, where CVS Health and Walgreens account for disproportionate pharmaceutical distribution volume.
Cold Chain Market Segmentation
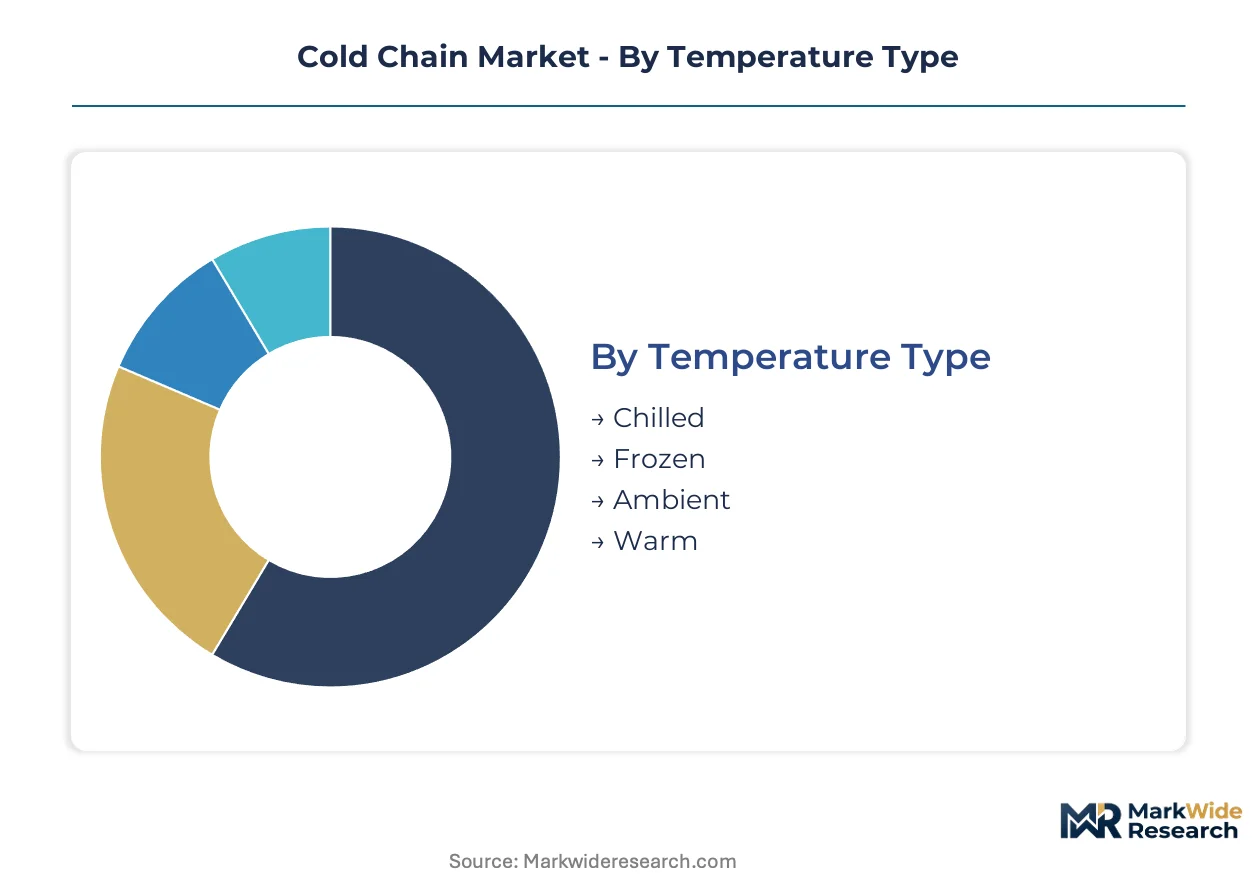
Cold chain segmentation reflects the tension between commodity food logistics and precision pharmaceutical handling. Temperature corridors, product sensitivity, and packaging validation requirements create distinct operational profiles that reshape capital allocation across facility networks.
Temperature Type:
Mature frozen infrastructure dominates volume throughput, while emerging ultra-low temperature corridors attract premium investment for biologics handling.
- Chilled:Maintains 0°C to 10°C through multi-zone refrigeration systems for dairy, fresh produce, and short-shelf-life pharmaceuticals. Demand concentrates in US retail consolidation, where Kroger and Albertsons operate dense chilled distribution networks serving direct-to-consumer delivery platforms.
- Frozen:Sustains -18°C to -25°C via ammonia-based industrial refrigeration for meat, seafood, and prepared foods. Lineage Logistics and Americold anchor North American capacity through automated high-bay warehouses near major protein processing clusters in Nebraska and Iowa.
- Ambient:Controls 15°C to 25°C for stable pharmaceuticals and non-perishables requiring protection from heat spikes. Indian vaccine export corridors from Hyderabad deploy ambient-conditioned staging areas pending validated cold packaging.
- Warm:Maintains 20°C to 25°C with tight variance bands for tropical climate distribution of heat-sensitive biologics. African and Southeast Asian last-mile networks adopt these specifications for insulin and vaccine outreach programs.
Frozen handles the majority of throughput; chilled is the fastest mover on share as fresh-format retail expands.
Product Type:
Cost tiers separate commodity food handling from certified pharmaceutical operations that command infrastructure premiums.
- Pharmaceuticals:Encompasses small-molecule drugs requiring 2°C to 8°C stability with continuous GDP documentation. FDA enforcement of DSCSA traceability mandates drives serialization investments across US wholesale distributors.
- Food & Beverages:Spans frozen proteins, dairy, and prepared meals with temperature tolerance wider than pharmaceutical bands. German and Dutch cold storage operators retrofit ammonia systems fastest under EU F-Gas Regulation timelines.
- Biologics:Monoclonal antibodies, vaccines, and cell therapies demand -80°C to -196°C cryogenic corridors with validated qualification protocols. US Inflation Reduction Act domestic manufacturing incentives accelerate regional cryogenic node development.
- Chemicals:Temperature-sensitive industrial precursors and reagents requiring controlled storage to prevent degradation or hazardous reactions. Specialty chemical clusters in Germany's Rhine-Ruhr region anchor European capacity.
Food and beverages handles the majority of throughput; biologics is climbing the fastest on margin contribution.
Packaging Type:
Application requirements drive selection between reusable infrastructure and single-use validated systems.
- Containers:Reusable active temperature-controlled units with integrated compressor systems for high-value pharmaceutical lanes. Phase-change material hybridization extends transit windows without dry ice dependency.
- Pallet Shippers:Lane-specific passive thermal packaging combining vacuum-insulated panels with eutectic salt hydrates. Pharmaceutical distributors adopt these for international risk-mapped corridors where active refrigeration fails.
- Insulated Boxes:Expanded polystyrene or polyurethane containers with gel packs for short-duration last-mile delivery. Direct-to-consumer frozen meal services in US metropolitan markets drive volume.
- Refrigerated Trucks:Diesel or electric-powered transport refrigeration units with telematics-linked temperature logging. California Air Resources Board zero-emission mandates accelerate electric fleet trials in Los Angeles and San Francisco corridors.
Refrigerated trucks handles the majority of throughput; pallet shippers is gaining share fastest on pharmaceutical lane expansion.
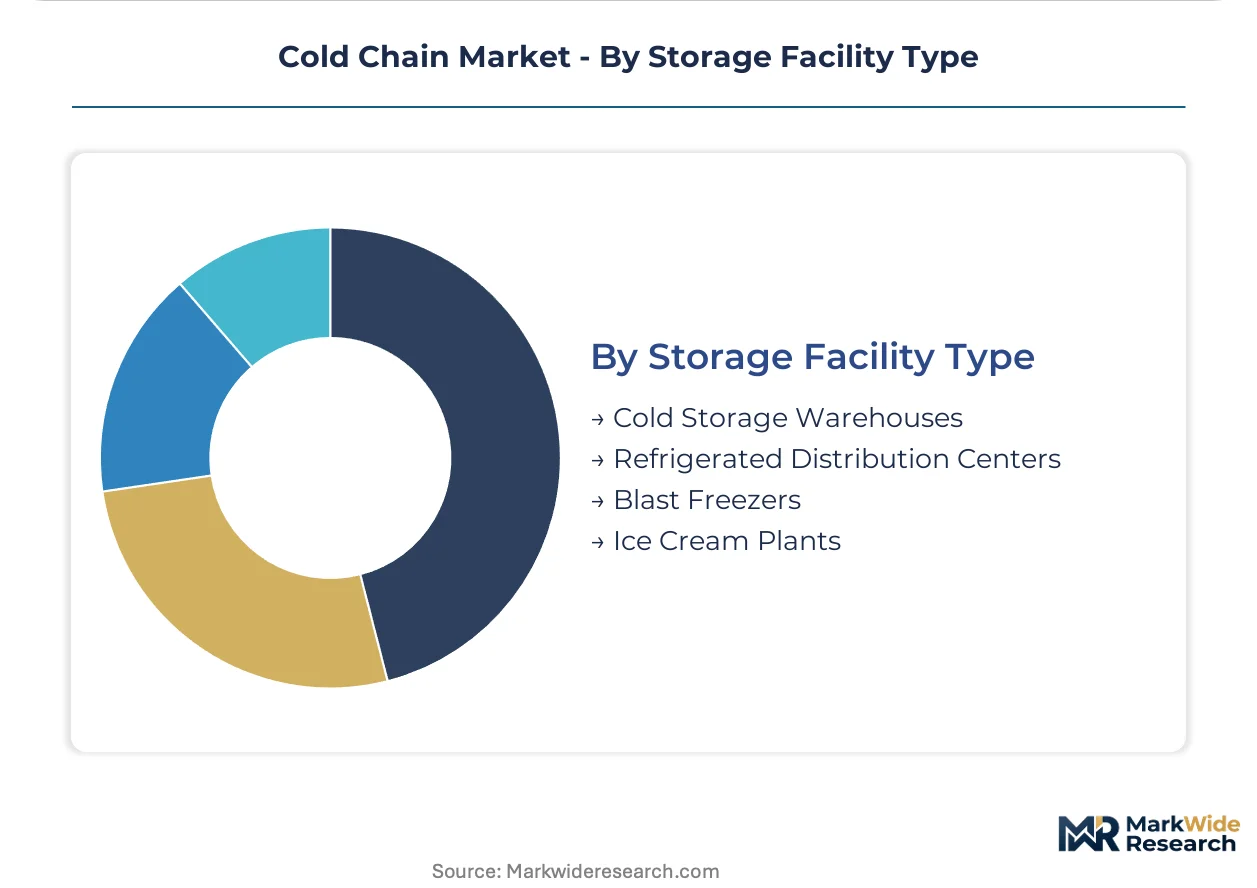
Storage Facility Type:
Volume concentration in legacy warehouses contrasts with greenfield automation investments in distribution centers.
- Cold Storage Warehouses:Large-scale ambient and frozen facilities with pallet-based storage and manual or semi-automated retrieval. ammonia toxicity constraints limit urban retrofit options near population centers.
- Refrigerated Distribution Centers:High-velocity automated facilities with robotics, AS/RS systems, and direct-to-consumer fulfillment capabilities. US food retail consolidation drives capital deployment in Chicago, Dallas, and Atlanta metro areas.
- Blast Freezers:Rapid temperature reduction systems for field-fresh produce and post-slaughter protein processing. Poultry and seafood processors in Thailand and Vietnam anchor Southeast Asian capacity.
- Ice Cream Plants:Dedicated -30°C to -40°C facilities for frozen dessert manufacturing with integrated hardening tunnels. Unilever and Nestlé operate captive networks with third-party overflow contracting.
Cold storage warehouses handles the majority of throughput; refrigerated distribution centers is expanding most quickly on e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical exports to the United States and European Union are driving validated cold chain corridor investments across temperature-sensitive biologics distribution.
United States
Food retail consolidation and direct-to-consumer frozen delivery are accelerating warehouse automation investments in Chicago, Dallas, and Atlanta metro areas. The FDA enforces Drug Supply Chain Security Act traceability mandates that drive serialization investments across wholesale distributors. Americold Logistics and Lineage Logistics anchor North American capacity through controlled rail and intermodal networks serving protein processing clusters in Nebraska and Iowa.
Germany
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants and forces cold storage operators toward natural refrigerant retrofits. National building codes anticipate the EU timeline, accelerating ammonia and CO2-based system replacement demand. Cold storage operators in the Rhine-Ruhr region retrofit fastest, driven by specialty chemical cluster requirements for temperature-sensitive industrial precursor handling.
India
Vaccine manufacturing hubs in Hyderabad and Pune lack sufficient validated cold chain infrastructure for temperature-sensitive biologic exports to regulated markets. The CDSCO maintains harmonized validation protocols with FDA and EMA frameworks that create compliance complexity for multi-jurisdiction operators. Export corridors deploy ambient-conditioned staging areas pending validated cold packaging for international pharmaceutical distribution.
Netherlands
Frozen food logistics responds fastest to EU F-Gas Regulation timelines, with national codes driving natural refrigerant adoption ahead of the 2030 mandate. Automated high-bay warehouses near Rotterdam and Amsterdam serve as European distribution gateways for temperature-controlled goods. Intermodal connectivity through the port complex enables lane-specific pharmaceutical distribution across continental corridors.
Japan
Precision cooling systems for pharmaceutical applications depend on specialized compressor supply concentrated domestically and in Germany. The PMDA maintains stringent stability window requirements for biologics that compress warehouse network investment cycles. Tokyo and Osaka metropolitan areas face ammonia toxicity siting restrictions that limit urban warehouse retrofit options near population centers.
Cold Chain Market Key Industry Players
On the supply side, the industry is consolidating around automated cold storage networks and intermodal transportation capabilities. Tiered competitive positioning separates scale-driven warehouse operators from specialized pharmaceutical logistics providers. Two dominant strategic archetypes define the landscape: integrated temperature-controlled infrastructure owners and third-party logistics providers with GDP-certified pharmaceutical capabilities. Capacity expansion through greenfield automated facilities and strategic partnerships for last-mile refrigerated fulfillment represent the primary competitive moves.
Within the integrated infrastructure tier, Americold Logistics and Lineage Logistics occupy positions as North American capacity anchors, while Nichirei Corporation exemplifies the Asia-Pacific cold storage specialist archetype. These entities represent divergent geographic concentrations and operational scale profiles that shape competitive dynamics across temperature-controlled logistics corridors.
| Leading Market Players |
|---|
| Americold Logistics |
| Lineage Logistics |
| Nichirei Corporation |
| Burris Logistics |
| A.P. Moller - Maersk |
| United States Cold Storage |
| Tippmann Group |
| NewCold |
| Constellation Cold Logistics |
| Others |
Cost & Logistics Intelligence
Undercapacity in India's vaccine export corridors is compressing contract margins for international pharmaceutical lanes while simultaneously accelerating automation investments in US food retail consolidation zones. This utilization asymmetry between mature and emerging cold chain networks creates divergent pricing power across temperature-controlled logistics corridors.
Pricing Analysis
Next-generation ammonia and CO2-based natural refrigerant systems command premium lease rates against legacy hydrofluorocarbon infrastructure facing EU F-Gas Regulation phaseout deadlines. Three-tier pricing structure across GDP-certified pharmaceutical handling, food-grade frozen storage, and ambient-conditioned staging separates margin pools by validation intensity. Cost compression in food logistics is intensifying because national pharmacy chains unbundle transportation from storage and demand annual contract renegotiations. Group purchasing organizations exhibit the highest price sensitivity; biologics manufacturers with cell therapy pipelines show the least.
Supply Chain Analysis
Export-control regimes on precision cooling compressors from Germany and Japan constrain cryogenic logistics capacity expansion in pharmaceutical corridors. Manufacturing concentration in China for phase-change materials, the United States for automated warehouse robotics, and Germany for industrial refrigeration equipment creates multi-node dependency. Supply chain risk centers on single-source vulnerability for specialized compressor systems with twelve-to-eighteen-month qualification timelines. Distribution runs through controlled rail and intermodal networks anchored by automated high-bay facilities near protein processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold chain infrastructure sits in early-cycle expansion as cell and gene therapy pipelines force five-year investment compression cycles that did not exist a decade ago. Biologics manufacturing expansion represents the dominant penetration tailwind across temperature-controlled logistics.
For Market Incumbents: Insulate pharmaceutical GDP certification advantages by accelerating natural refrigerant retrofits ahead of EU F-Gas Regulation deadlines. Defend against margin compression from unbundled procurement by integrating last-mile fulfillment capabilities in Chicago, Dallas, and Atlanta metro areas. Prioritize ammonia system siting in exurban zones to bypass urban toxicity restrictions.
For New Entrants and Emerging Players: Establish a beachhead in India's Hyderabad and Pune vaccine export corridors where validated cold chain infrastructure remains underdeveloped for biologic shipments to regulated markets. Target passive thermal packaging convergence combining vacuum-insulated panels with eutectic salt hydrates for lane-specific pharmaceutical distribution. Pursue qualification protocol partnerships with CDSCO-harmonized validation frameworks as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryogenic logistics infrastructure driven by cell therapy pipeline requirements. Long-term viability over the next decade rests on automated cold storage networks with intermodal transportation capabilities rather than manual warehouse operations. Acquisition targets should demonstrate GDP certification across FDA, EMA, and Health Canada jurisdictions. Watch ammonia toxicity siting restrictions near population centers as the signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Retrofit | EU F-Gas Regulation compliance secures facility operating licenses ahead of 2030 mandates. |
| GDP Certification Investment | FDA, EMA, and Health Canada validation protocols enable biologics corridor access. |
| Automated Warehouse Robotics | AS/RS systems sustain throughput advantages in high-velocity frozen food hubs. |
| Passive Thermal Packaging Development | Phase-change material hybridization reduces active refrigeration dependency for international lanes. |
| Cryogenic Distribution Node Expansion | Regional ultra-low temperature infrastructure captures cell therapy logistics demand. |
Research Approach
A standing panel of cold storage facility operators, pharmaceutical logistics directors, refrigeration equipment procurement managers, and thermal validation engineers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with warehouse automation specialists and GDP compliance officers with secondary validation from FDA DSCSA guidance documents, EU Good Distribution Practice guidelines, CDSCO harmonization frameworks, and customs trade data on temperature-controlled equipment imports. Bottom-up facility capacity assessments triangulated against top-down pharmaceutical export volume projections.
Scenario bracketing around refrigerant transition timelines, biologics pipeline advancement rates, and food retail consolidation patterns anchored the analytical framework across the projection horizon. Segmentation modeling incorporated temperature corridors, product sensitivity tiers, packaging validation requirements, and storage facility automation levels. CAGRs derived from capacity expansion announcements, contract renewal velocity, and equipment manufacturer order backlogs. Industry-specific inputs included ammonia retrofit cycle durations and multi-jurisdiction qualification timelines.
Stress conditions across copper and aluminum input volatility, specialized compressor supply concentration, and qualified personnel scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU F-Gas Regulation enforcement consistency and US Inflation Reduction Act biomanufacturing incentive continuity. Material shifts in cell therapy regulatory approval velocity or natural refrigerant toxicity siting restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market