
 Cold Storage Insulated Market | 2026-2036
Cold Storage Insulated Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Storage Insulated Market Analytics
The EU Green Deal is restructuring procurement criteria for cold storage infrastructure across European food retail and pharmaceutical distribution. Lineage Logistics Holdings, LLC leverages its network scale to dominate temperature-controlled warehousing in key logistics corridors. Americold Logistics, Inc. anchors its position through in-house production of insulated panel systems for custom installations. Nichirei Corporation specializes in precision-controlled environments for pharmaceutical clients across East Asian markets.
Cold storage insulated systems comprise engineered thermal enclosures utilizing polyurethane foam, vacuum-insulated panels, or mineral wool with specified R-values exceeding 32 to maintain temperatures between minus 30 degrees Celsius and plus 15 degrees Celsius for perishable goods and temperature-sensitive materials. Walk-in freezers and insulated panels represent the most mature product categories with established margin pools, while refrigerated containers are gaining traction in intermodal pharmaceutical logistics where portability intersects with stringent stability requirements. Permanent installations still occupy the largest share of deployment value, though modular systems are attracting healthcare and retail end users seeking scalable capacity without long-term capital lock-in.
The EPA enforces SNAP program restrictions on high-GWP foams used in cold storage fabrication, while REACH governs chemical safety in insulation materials circulating within European supply chains. FDA guidelines on pharmaceutical cold chain validation create compliance thresholds that filter out non-specialized fabricators. Stakeholders must monitor evolving refrigerant-phaseout schedules and building energy codes to anticipate which insulation chemistries and panel geometries will retain market access across major economies.
Market Dynamics
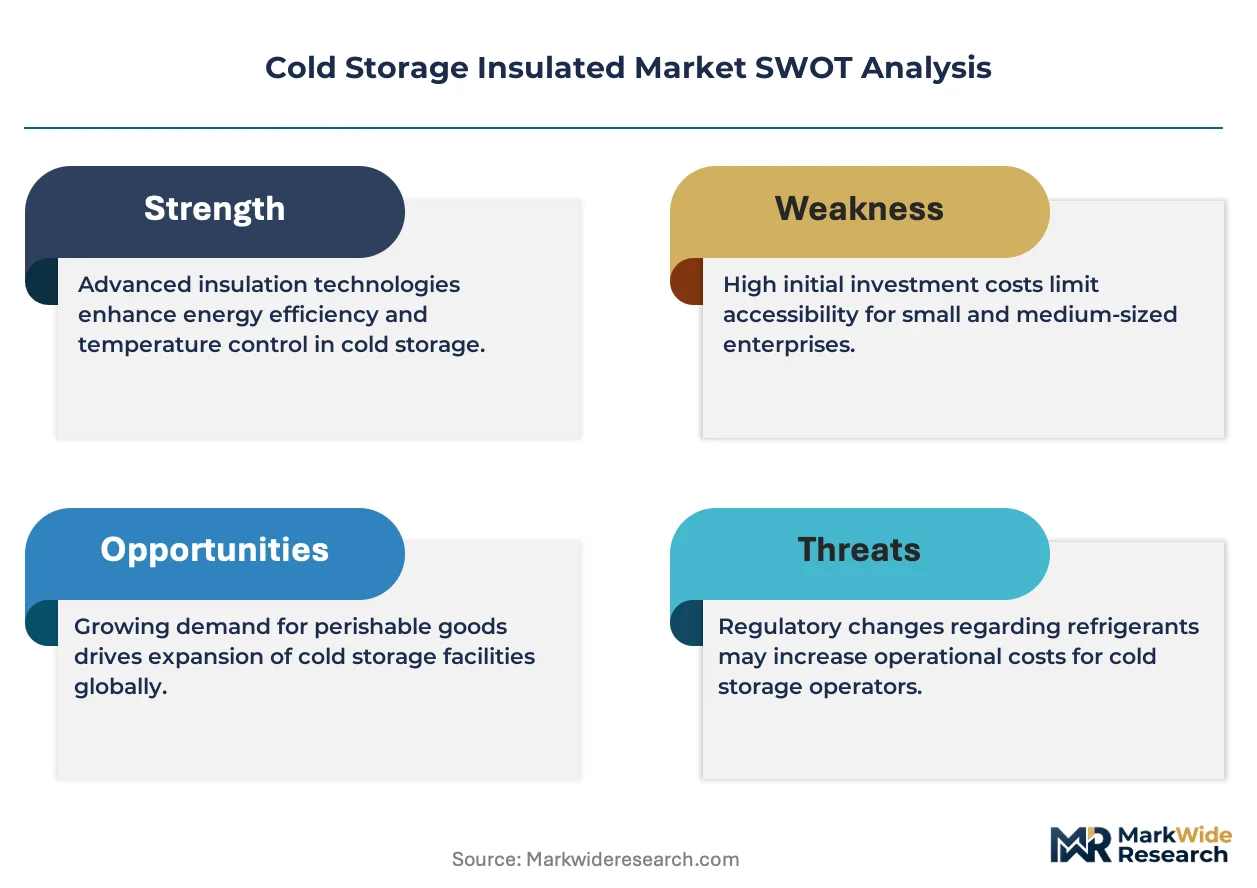
The EU F-Gas Regulation is compressing hydrofluorocarbon blowing agent availability, forcing polyurethane insulation formulators to retool production lines toward lower-GWP alternatives before phaseout deadlines hit.
Growth Catalysts
- Biologics cold chain expansion:Pharmaceutical distributors are building redundant storage nodes to meet FDA validation requirements for temperature-sensitive therapeutics.
- REACH compliance upgrades:European fabricators are replacing legacy foam chemistries to maintain market access across EU member states.
- German logistics modernization:Precision medicine hubs in Frankfurt and Hamburg are driving panel system replacement cycles.
Market Restraints
- Polyol feedstock volatility:Crude-linked input costs swing panel margins unpredictably for non-integrated manufacturers.
- Chinese VIP supply concentration:Vacuum-insulated panel core materials rely on a narrow supplier base in East Asia.
- Refrigerant-phaseout timeline compression:The EPA SNAP program restricts foam-blowing agent options faster than R&D cycles can adapt.
Strategic Opportunities
- Modular healthcare deployment:Hospital systems in the US are leasing scalable cold rooms rather than committing to permanent construction.
- EU Green Deal procurement mandates:Public sector cold storage tenders now require embodied carbon disclosures, favoring domestic panel producers with verified supply chains.
- Phase-change material integration:Thermal battery systems are converging with conventional insulation to extend passive cooling duration in last-mile vaccine distribution.
Industry Challenges
- Thermal bridge engineering expertise:Panel installation crews with certified passive-house detailing skills command premium wages and extend project timelines.
- Multi-certification stacking:Pharmaceutical clients demand simultaneous FDA, EMA, and WHO prequalification documentation, stretching quality assurance bandwidth.
- Legacy control system integration:New insulated enclosures must interface with existing building management protocols without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Storage Insulated Market |
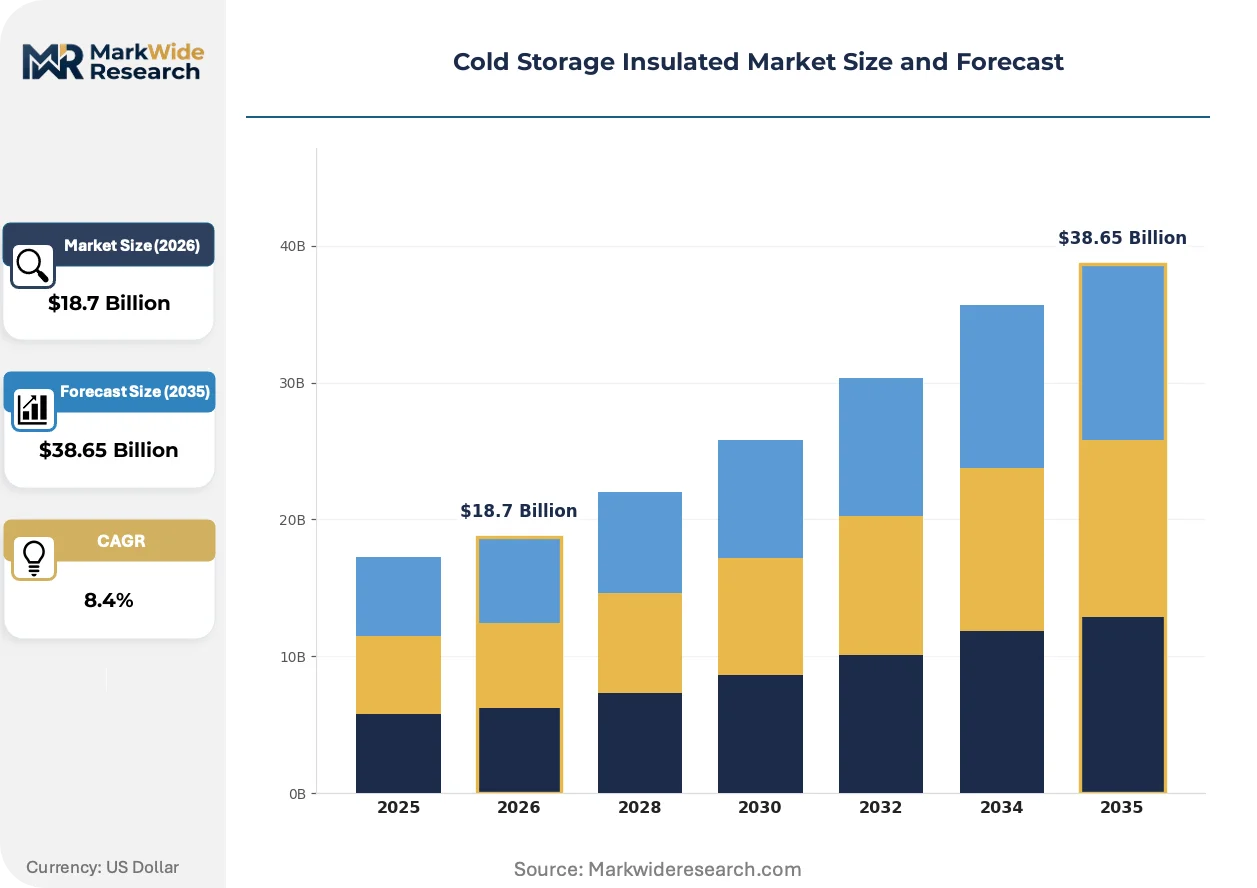
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-In Freezers, Refrigerated Containers, Insulated Panels, Temperature-Controlled Trucks Application: Food Preservation, Pharmaceutical Storage, Chemical Storage, Floral Storage End User: Hospitality, Healthcare, Retail, Logistics Installation Type: Modular Systems, Permanent Installations, Rental Solutions, Customized Solutions |
| Companies Covered | Lineage Logistics Holdings, LLC, Americold Logistics, Inc., United States Cold Storage, Inc., Nichirei Corporation, Burris Logistics, NewCold Advanced Cold Logistics, Conestoga Cold Storage, VersaCold Logistics Services, Tippmann Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Storage Insulated Market Evolving Landscape
Sensor-embedded insulation systems are transforming how operators monitor thermal envelope integrity, shifting maintenance from scheduled to condition-based protocols across pharmaceutical and food retail installations.
Smart panel arrays with integrated IoT temperature logging are automating compliance documentation for FDA-regulated storage facilities. Biopharma distributors in the US Northeast are deploying these systems fastest, cutting manual audit labor while compressing deviation response times from hours to minutes. The technology is automating the boundary between physical infrastructure and digital quality systems.
The EU F-Gas Regulation is mandating stepped reductions in HFC-based blowing agents through 2030. Foam producers serving European cold storage OEMs are accelerating trials of hydrofluoroolefin and hydrocarbon alternatives. Walk-in freezer panels face the steepest reformulation pressure, as their thick foam cores consume the highest volumes of restricted chemistries.
Consolidated procurement by third-party logistics operators is displacing fragmented buyer networks that historically sourced panels through regional distributors. Temperature-controlled warehouse specialists now negotiate direct with insulation system fabricators, unbundling installation from hardware supply. This concentration is most visible in the US, where Lineage Logistics and Americold account for an outsized share of new cold storage square footage.
Cold Storage Insulated Market Segmentation
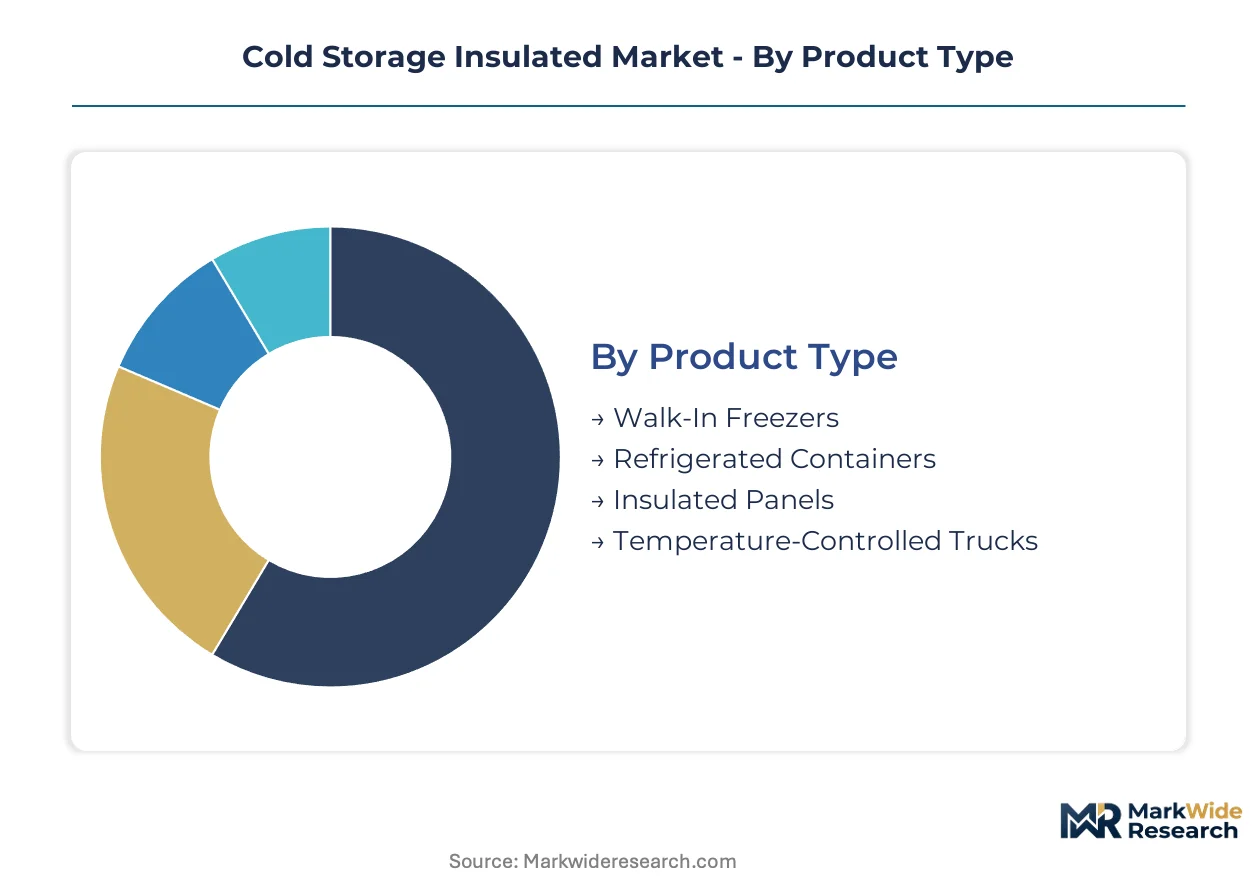
Cold storage insulated infrastructure fragments across four distinct classification axes that shape procurement behavior and margin capture. Product type determines capital intensity and thermal performance ceilings. Application verticals impose divergent regulatory compliance burdens. Installation modality governs customer switching costs and vendor relationship durability.
Product Type:
Standardized walk-in enclosures dominate volume sales while custom-engineered panel systems command premium pricing for specialized thermal envelopes.
- Walk-In Freezers:Rigid polyurethane foam cores bonded to metal facings deliver R-values exceeding 32 for sustained minus-30-degree operation. Food retail chains in Germany specify these for central distribution hubs where throughput volume justifies permanent infrastructure investment against energy code tightening.
- Insulated Panels:Interlocking modular sections with cam-lock edges enable rapid field assembly without thermal bridge formation. Precision medicine facilities in Frankfurt and Hamburg favor these for cleanroom-adjacent storage where panel-to-panel gasket integrity determines regulatory compliance.
- Refrigerated Containers:Intermodal units with integrated refrigeration machinery serve pharmaceutical last-mile distribution where portability intersects with GDP compliance requirements.
- Temperature-Controlled Trucks:Vehicle-mounted insulated bodies with phase-change material backup systems protect perishables during transit gaps in multimodal cold chains.
Leading the category by volume: Walk-In Freezers. Expanding most quickly: Insulated Panels.
Application:
Regulatory stringency varies dramatically across use cases, with pharmaceutical validation protocols filtering out generalist fabricators.
- Pharmaceutical Storage:FDA and EMA-mandated temperature mapping and qualification documentation add 40-60% cost premiums over food-grade equivalents. Biologics distributors building redundant storage nodes drive specification intensity for validated thermal envelopes.
- Food Preservation:Fresh produce and protein cold chains prioritize energy efficiency and rapid door-cycle recovery over precision stability. EU Green Deal procurement criteria now require embodied carbon disclosures for public sector food logistics tenders.
- Chemical Storage:Hazardous material containment specifications mandate fire-rated panel cores and secondary spill containment integration.
- Floral Storage:Ethylene-sensitive commodity handling requires precise humidity control alongside temperature management in shorter-duration storage cycles.
Dominating current deployment value: Food Preservation. Steepest expansion trajectory: Pharmaceutical Storage.
End User:
Customer scale and technical sophistication determine whether procurement flows through distributors or direct to fabricators.
- Logistics:Third-party cold chain operators with multi-site networks negotiate centralized panel supply contracts unbundled from installation services. Lineage Logistics and Americold procurement concentration in the US exemplifies this buying pattern.
- Healthcare:Hospital systems increasingly lease modular cold rooms through equipment finance arrangements rather than committing to permanent construction capital.
- Retail:Grocery chains balance standardization for new-build distribution centers against legacy facility retrofit complexity.
- Hospitality:Restaurant and hotel operators rely on regional distributor networks for smaller-scale walk-in replacement cycles.
Capturing largest share of panel system value: Logistics. Gaining share fastest: Healthcare.
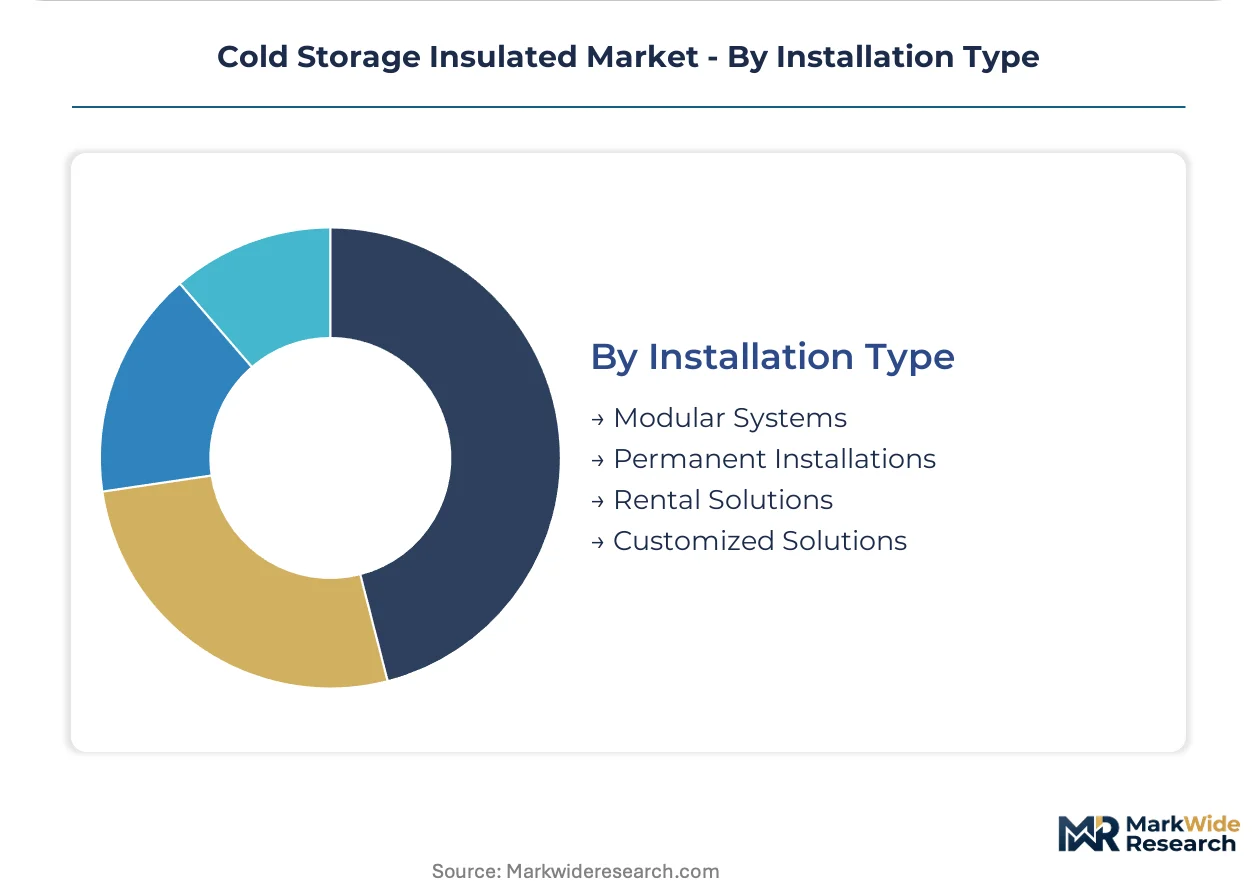
Installation Type:
Capital deployment flexibility separates customers seeking asset-light capacity from those prioritizing long-term operational control.
- Permanent Installations:Conventional built-in cold rooms with poured concrete floors and fixed refrigeration plant anchor food manufacturing and central distribution infrastructure. These retain the largest share of deployment value despite longer project timelines.
- Modular Systems:Prefabricated panel assemblies with plug-and-play refrigeration connections enable rapid capacity scaling without construction permits. Healthcare systems in the US Northeast deploy these fastest for vaccine storage surge capacity.
- Rental Solutions:Short-term lease arrangements for refrigerated containers and mobile cold rooms serve seasonal agricultural peaks and emergency pharmaceutical distribution.
- Customized Solutions:Engineered-to-order thermal envelopes address atypical dimensional constraints or extreme temperature ranges beyond standard product catalogs.
Holding majority position: Permanent Installations. Climbing the fastest: Modular Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Hamburg precision medicine hubs anchor European cold storage insulated infrastructure investment, with German logistics modernization compressing panel system replacement cycles across pharmaceutical distribution corridors.
United States
FDA validation requirements for biologics cold chains drive redundant storage node construction across the Northeast and Southeast. EPA SNAP program restrictions on high-GWP foams filter out non-specialized fabricators from pharmaceutical-grade panel supply. Greater Boston biopharma clusters deploy sensor-embedded insulation fastest for automated compliance documentation.
Germany
EU F-Gas Regulation phaseout timelines accelerate polyurethane reformulation toward hydrofluoroolefin alternatives in walk-in freezer production. EU Green Deal procurement mandates now require embodied carbon disclosures for public sector food logistics tenders. Precision medicine facilities in Frankfurt specify interlocking insulated panels for cleanroom-adjacent storage where gasket integrity determines regulatory compliance.
Japan
PMDA pharmaceutical storage guidelines create multi-certification stacking requirements that stretch quality assurance bandwidth for panel fabricators. METI industrial standards govern thermal performance specifications for temperature-sensitive material handling. Kansai pharmaceutical distribution corridors concentrate demand for vacuum-insulated panel systems in space-constrained urban facilities.
China
NMPA biologics distribution regulations tighten thermal envelope validation protocols for vaccine storage infrastructure. MEE environmental standards restrict legacy foam chemistries in cold storage manufacturing. Yangtze River Delta logistics zones attract modular cold room deployments for rapid capacity scaling without construction permits.
India
CDSCO cold chain guidelines for temperature-sensitive therapeutics expand validated storage requirements beyond metropolitan hospital networks. PLI scheme incentives support domestic panel production capacity for pharmaceutical logistics. Maharashtra pharmaceutical manufacturing clusters drive specification intensity for redundant thermal envelope systems.
Cold Storage Insulated Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity, with FDA-validated pharmaceutical-grade panel systems commanding 40-60% cost premiums over food-grade equivalents. The vendor base organizes around three strategic archetypes: integrated logistics operators with captive fabrication, specialized insulation system manufacturers, and diversified construction material conglomerates. Consolidated procurement by third-party logistics operators displaces fragmented regional distributor networks. Direct negotiation between warehouse specialists and panel fabricators unbundles installation from hardware supply.
Among US-based logistics operators, Lineage Logistics Holdings, LLC and Americold Logistics, Inc. represent the scale-driven archetype, anchoring concentrated procurement power in temperature-controlled warehousing corridors. Nichirei Corporation exemplifies the regional specialist model, occupying a position within East Asian pharmaceutical precision environments. These three entities sit within distinct competitive vectors—network scale, in-house production integration, and geographic specialization—rather than direct product-market overlap.
| Leading Market Players |
|---|
| Lineage Logistics Holdings, LLC |
| Americold Logistics, Inc. |
| United States Cold Storage, Inc. |
| Nichirei Corporation |
| Burris Logistics |
| NewCold Advanced Cold Logistics |
| Conestoga Cold Storage |
| VersaCold Logistics Services |
| Tippmann Group |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation mandates for low-GWP blowing agents are compressing input availability, forcing polyurethane formulators toward hydrofluoroolefin alternatives that carry 15-25% cost premiums and reshaping margin structures across panel system tiers.
Pricing Analysis
FDA-validated thermal envelope performance anchors value-based pricing, with pharmaceutical-grade panel systems commanding substantial premiums over food-grade equivalents due to simultaneous multi-certification documentation requirements. Pricing stratifies across premium validation tiers, standard commercial grades, and economy food-retail specifications, with certification intensity and volume scale as primary differentiation drivers. Cost compression in mid-tier segments is intensifying because REACH compliance upgrades and polyol feedstock volatility squeeze non-integrated manufacturers. Food retail chains exhibit highest price sensitivity, while biologics distributors prioritize thermal envelope reliability over unit cost.
Supply Chain Analysis
Refurbishment flows for refrigerated containers and modular panel systems are extending asset lifecycles and creating secondary supply channels that compete with new fabrication. Vacuum-insulated panel core materials concentrate in China, South Korea, and Japan, while polyurethane foam chemicals flow from Germany, the United States, and Belgium. Raw material dependencies rest on crude-linked polyol feedstocks, specialized blowing agents, and metallized barrier films. Single-source vulnerability in East Asian VIP supply creates structural risk for precision medicine facilities requiring space-constrained thermal envelopes. Distribution runs through direct contracts between third-party logistics operators and panel fabricators, displacing historical regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with captive production of insulated panel systems and in-house blowing agent formulation emerging as the decisive margin-control levers.
For Market Incumbents: Cement market position by acquiring certified installation crews with passive-house detailing expertise, as thermal bridge engineering talent scarcity extends project timelines and inflates labor costs. Secure long-term offtake agreements for low-GWP blowing agents before EU phaseout deadlines eliminate hydrofluorocarbon availability. Backward integration into polyol feedstock hedging or regional chemical production mitigates crude-linked margin volatility. For New Entrants and Emerging Players: Digital-channel routes for modular cold room leasing bypass capital-intensive permanent construction sales cycles and target hospital systems seeking asset-light vaccine storage capacity. White-space exists in pharmaceutical last-mile distribution infrastructure across India and Southeast Asia, where CDSCO and national regulator guidelines are expanding validated storage requirements beyond metropolitan networks. Pursue equipment finance partnerships with healthcare systems as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with specialized insulation system manufacturers possessing simultaneous FDA, EMA, and WHO prequalification documentation capabilities, given biologics cold chain expansion as the demand catalyst. Long-term viability favors fabricators with verified embodied carbon supply chains aligned to EU Green Deal procurement mandates. Monitor EPA SNAP program enforcement intensity and refrigerant-phaseout timeline acceleration as inflection indicators for chemistry-dependent margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Production | Captive low-GWP chemistry supply secures margin control against EU F-Gas Regulation phaseout timelines. |
| Modular Healthcare Deployment Partnerships | Equipment finance arrangements with US Northeast hospital systems accelerate vaccine storage capacity scaling. |
| Multi-Certification Documentation Investment | Simultaneous FDA, EMA, and WHO prequalification filters out generalist competitors from pharmaceutical-grade supply. |
| Sensor-Embedded Panel System Development | IoT temperature logging automates FDA compliance documentation and compresses deviation response times. |
| Regional Production Footprint Expansion | Domestic German panel fabrication satisfies EU Green Deal embodied carbon disclosure requirements for public tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across cold storage OEM procurement directors, pharmaceutical distribution quality assurance leads, polyurethane foam chemical plant managers, thermal installation contractors, and third-party logistics facility planners. Secondary sources incorporated EPA SNAP program dockets, ECHA REACH substance registrations, FDA guidance documents on pharmaceutical cold chain validation, EU F-Gas Regulation implementation reports, and customs trade flow databases. Bottom-up panel system volume estimates and top-down cold chain infrastructure investment flows were triangulated for convergence.
Data-stream reconciliation across shipment volumes, installation permits, and end-user capital expenditure disclosures informed the analytical framework. Segmentation dimensions modeled include product type, application vertical, end-user scale, and installation modality across the projection horizon. CAGRs were derived from slope analysis of annualized investment flows and replacement cycle frequencies. Industry-specific forecast inputs encompassed refrigerant-phaseout schedule compliance costs and precision medicine hub construction pipelines.
The model holds under stable regulatory phaseout timelines and continued biologics distribution network expansion; deviation in blowing agent chemistry substitution rates or pharmaceutical cold chain validation intensity would shift volume and value trajectories. Practitioners should monitor EPA enforcement actions and EU Green Deal procurement mandate adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market