
 North America Cold Chain Market | 2026-2036
North America Cold Chain Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cold Chain Market Intelligence
The North America cold chain is shifting toward a clear split between premium temperature-assured services and commodity refrigerated capacity. Americold Logistics leverages its extensive warehouse network to dominate ambient-to-frozen transitions across the Southeast and Southwest. Lineage Logistics sustains leadership through deep freezer specialization and automated high-bay facilities. United States Cold Storage anchors its position in protein corridors, particularly near major poultry and beef processing zones.
The North America cold chain encompasses the integrated network of temperature-controlled storage, transport, and monitoring infrastructure required to preserve perishable goods within specified thermal bands, typically ranging from -30°C frozen to 2-8°C pharmaceutical cold chain standards. Refrigerated transport and freezer storage constitute the backbone infrastructure, while temperature monitoring systems increasingly embed IoT sensors for real-time compliance documentation. Pharmaceutical applications within the end-user segment command premium margins due to stringent FDA validation requirements, whereas retail chains and food distributors drive volume throughput across road transport modes. E-commerce channels represent the fastest-expanding delivery mode intersection, demanding last-mile insulated packaging solutions that differ structurally from bulk freight economics.
The FDA enforces Current Good Manufacturing Practice and Drug Supply Chain Security Act mandates that compel pharmaceutical cold chain participants to maintain validated temperature records and traceability documentation. The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing capital retooling across existing freezer storage assets, while OSHA warehouse safety standards shape labor automation investments. Stakeholders must monitor regulatory divergence between US federal standards and emerging provincial frameworks in Canada, as harmonization gaps could fragment cross-border lane economics.
Market Dynamics
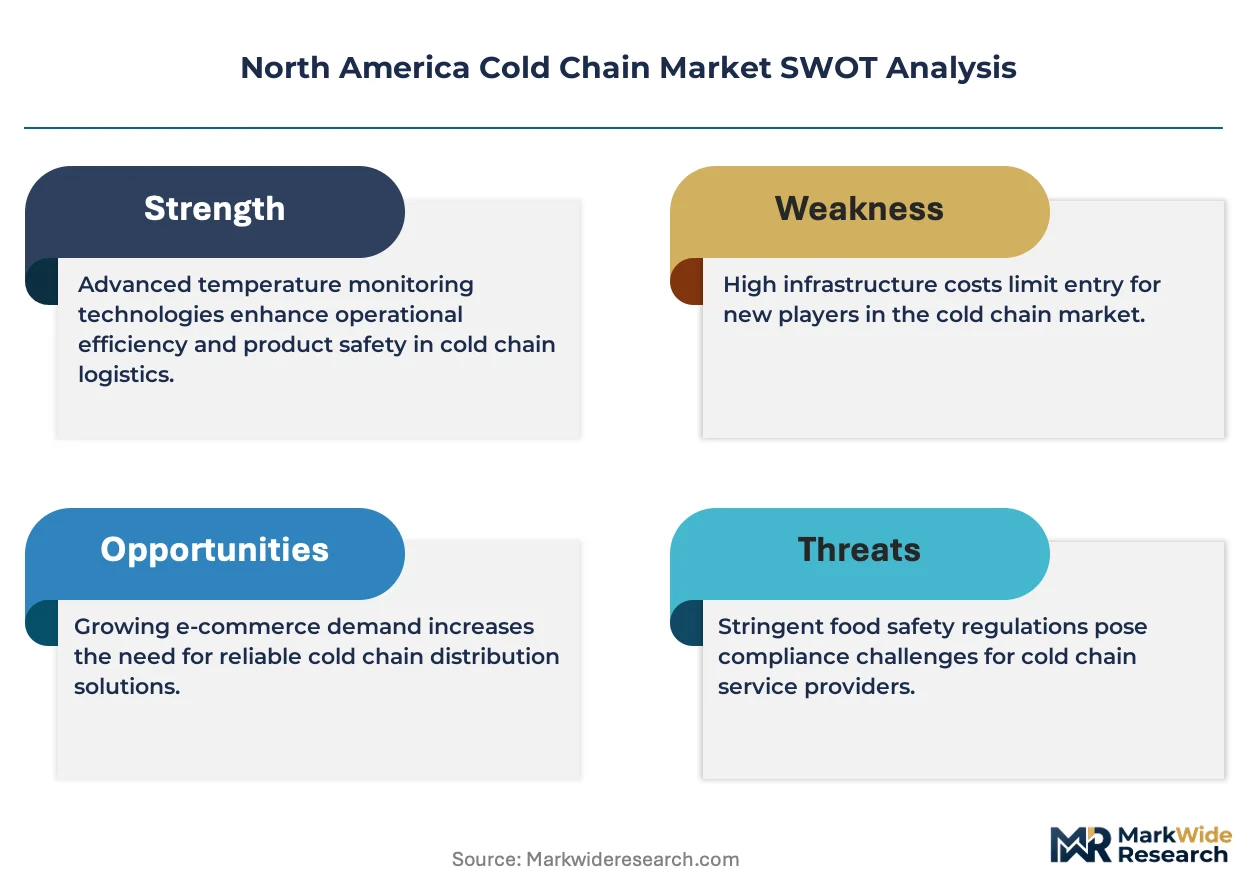
The North America cold chain is fracturing into two distinct service tiers: validated pharmaceutical-grade networks commanding audit-ready traceability, and commodity frozen storage competing on cubic-foot pricing. This bifurcation is compressing margins in the middle tier while rewarding operators who commit capital to either extreme.
Growth Catalysts
- FDA Drug Supply Chain Security Act mandates:Serialized track-and-trace requirements for pharmaceutical distribution are forcing wholesale infrastructure upgrades across United States distribution corridors.
- Cell and gene therapy commercialization:Cryogenic logistics below -150°C for CAR-T and viral vector products is creating demand for ultra-cold infrastructure previously confined to research settings.
- Midwest refrigerated warehousing clusters:Chicago, Indianapolis, and Kansas City anchor intermodal cold storage concentration that reduces drayage costs for temperature-controlled container flows.
Market Restraints
- Hydrofluorocarbon refrigerant phaseout:EPA AIM Act schedules are forcing capital-intensive retooling of existing freezer assets before natural replacement cycles.
- Specialized compressor manufacturing concentration:Supply of industrial refrigeration equipment depends on a concentrated base of European and Asian component suppliers, exposing North American operators to extended lead times.
- Last-mile thermal packaging substitution:Reusable insulated container programs and phase-change material advances threaten single-use parcel shipping economics in pharmaceutical direct-to-patient channels.
Strategic Opportunities
- Canadian provincial regulatory divergence:Harmonization gaps between Health Canada guidance and FDA validation protocols create arbitrage potential for dual-certified logistics providers serving cross-border lanes.
- Autonomous mobile robots in high-bay frozen warehouses:Convergence of cold-tolerant robotics and warehouse management systems enables dark-frozen operations that reduce labor exposure to sub-zero environments.
- Biologics manufacturing reshoring:United States federal production incentives under the Inflation Reduction Act are pulling active pharmaceutical ingredient synthesis back to domestic facilities, requiring adjacent cold chain capacity.
Industry Challenges
- Refrigeration technician shortage:Aging workforce in industrial ammonia and CO2 system maintenance is constraining facility expansion timelines across the United States heartland.
- Validation protocol complexity:FDA 21 CFR Part 11 electronic record requirements extend commissioning timelines for new pharmaceutical-qualified warehouses by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cold Chain Market |
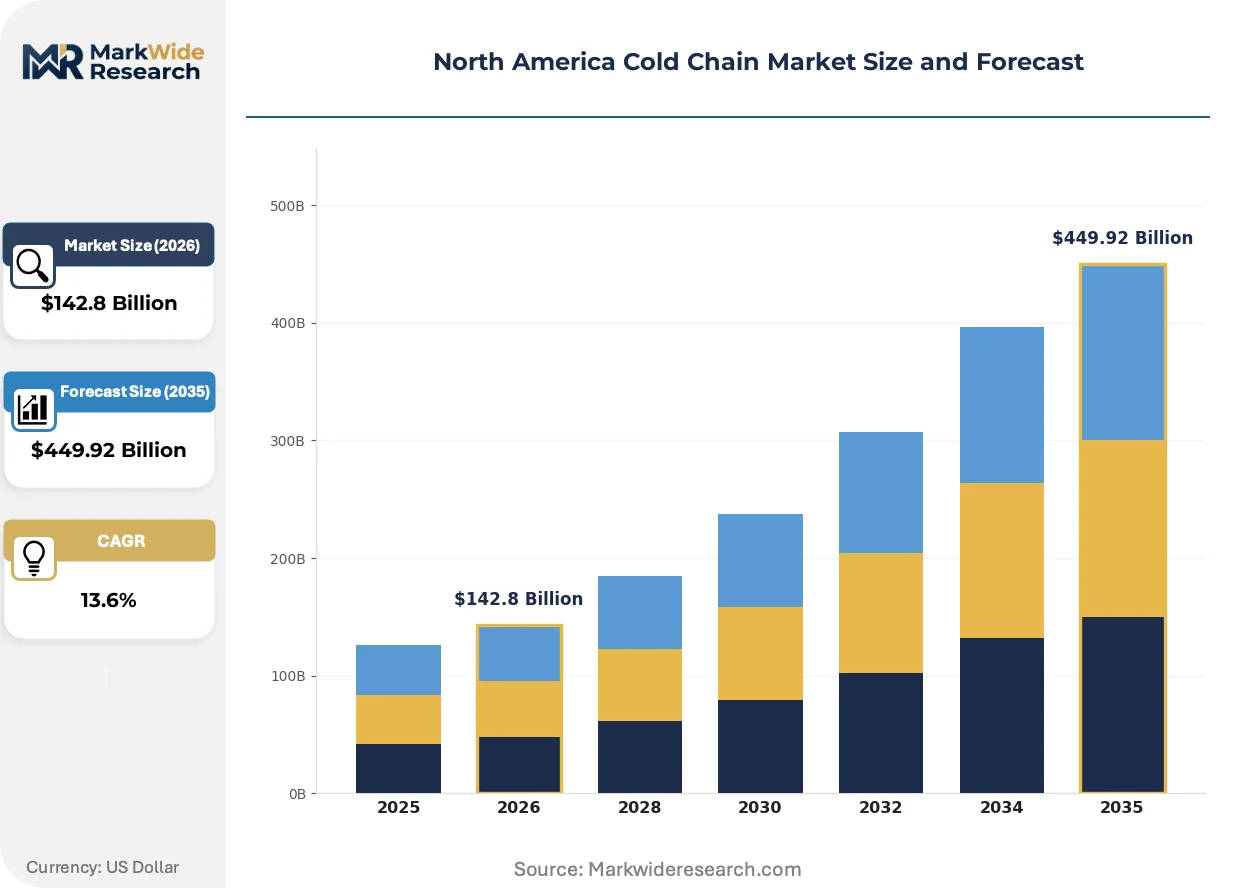
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $449.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Meat, Dairy, Pharmaceuticals Technology: Refrigerated Transport, Freezer Storage, Temperature Monitoring, Insulated Packaging End User: Retail Chains, Food Distributors, Healthcare Providers, E-commerce Delivery Mode: Road Transport, Air Freight, Rail Transport, Sea Freight |
| Companies Covered | Americold Logistics, Lineage Logistics, United States Cold Storage, VersaCold Logistics Services, Burris Logistics, AGRO Merchants Group, Interstate Warehousing, Conestoga Cold Storage, NewCold, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cold Chain Market Strategic Shifts & Innovations
Digital infrastructure is displacing manual temperature logging as the primary compliance mechanism, embedding continuous monitoring into contractual service-level agreements. This shift is elevating data architecture from operational support to core product definition.
IoT-enabled sensor networks with cellular or satellite backhaul is rewriting how pharmaceutical shippers enforce custody documentation. Biologics manufacturers now require minute-level temperature excursion alerts as standard contract terms. The technology is compressing acceptable response windows for supply chain intervention from hours to minutes.
EPA AIM Act hydrofluorocarbon phasedown schedules are accelerating adoption of transcritical CO2 and ammonia-based refrigeration systems in new warehouse construction. Existing asset owners face stranded-equipment risk as state-level building codes tighten ahead of federal deadlines. California and New York environmental regulators are imposing the most aggressive retrofit timelines.
Direct-to-consumer frozen food subscription models are fragmenting order profiles away from pallet-scale distribution toward parcel-level thermal protection. Meal kit fulfillment centers in Texas and Florida are investing in automated sortation for insulated packaging lines. This channel shift is most visible in Sun Belt metropolitan areas where e-commerce penetration in perishables lags national averages.
North America Cold Chain Market Segmentation
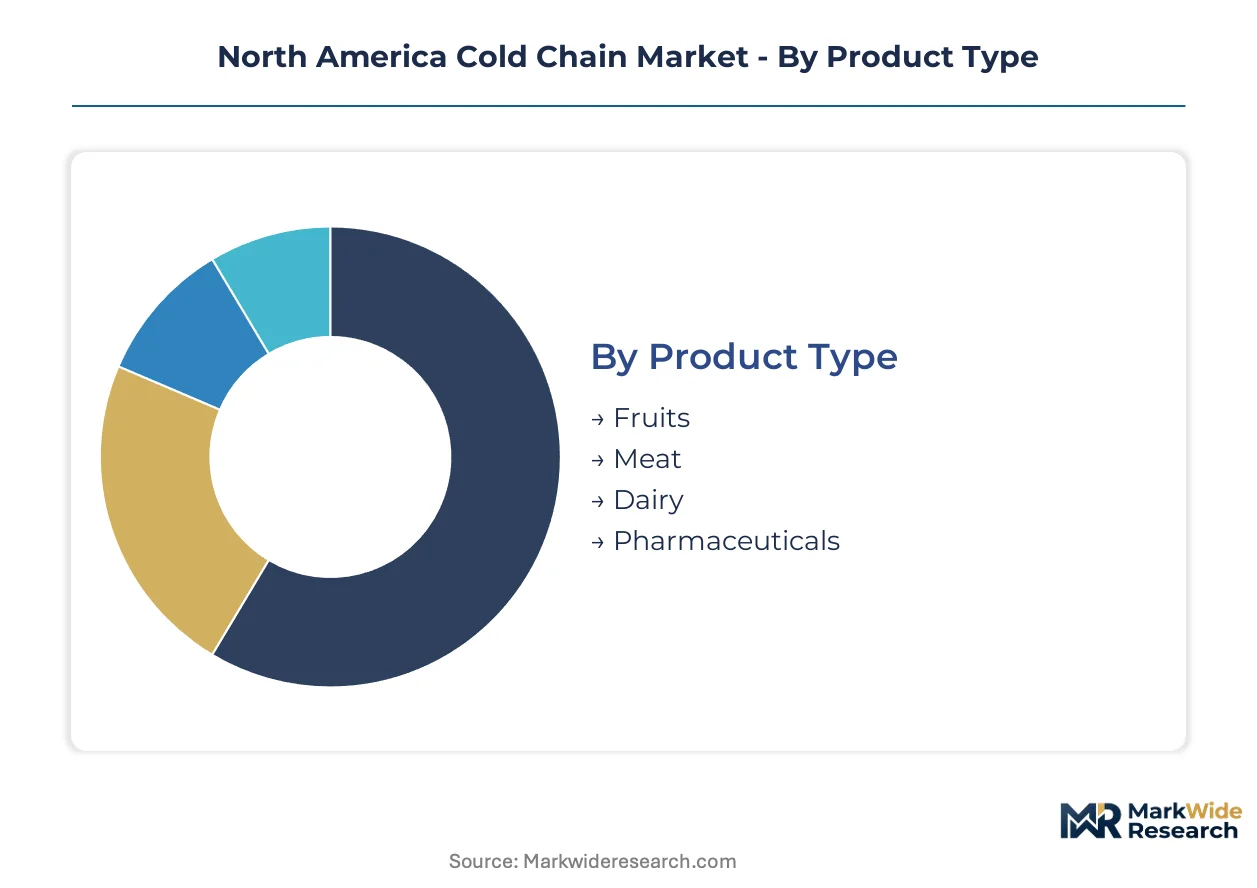
Cold chain segmentation in North America reflects divergent compliance burdens across product categories. Pharmaceutical lanes demand FDA-validated infrastructure, while food segments compete on cubic-foot economics and transit speed.
Product Type:
FDA validation requirements split this category between pharmaceutical-grade networks and commodity food corridors. Certification intensity determines pricing power and facility investment thresholds.
- Pharmaceuticals:Temperature bands of 2-8°C for biologics and -150°C cryogenic for cell therapies mandate serialized track-and-trace documentation under DSCSA. Demand concentrates in Boston-Cambridge and Research Triangle Park corridors, where gene therapy manufacturing clusters drive ultra-cold infrastructure investment.
- Meat:Protein corridors from Nebraska, Iowa, and Texas processing zones require -18°C frozen continuity through intermodal handoffs. USDA inspection protocols and HACCP documentation shape facility design in Kansas City and Omaha warehousing clusters.
- Dairy:Fluid milk and cheese categories operate on 0-4°C chilled chains with compressed shelf-life windows driving regional radius constraints.
- Fruits:Seasonal harvest patterns from California Central Valley and Florida create surge capacity demands at Pacific and Gulf port cold stores.
Leading the category by volume: Meat. Growing fastest: Pharmaceuticals.
Technology:
Capital deployment across technology layers follows margin stratification, with monitoring systems capturing software-like returns against hardware-heavy transport assets.
- Temperature Monitoring:IoT sensor networks with cellular backhaul now embed directly into pharmaceutical service-level agreements. Minute-level excursion alerts compress response windows and elevate data architecture to core product definition in biologics distribution.
- Refrigerated Transport:Road fleets dominate food distribution with diesel-powered reefer units, while pharmaceutical lanes increasingly specify redundant compressor systems and real-time GPS-thermal integration for custody documentation.
- Freezer Storage:Automated high-bay facilities in Chicago and Indianapolis achieve pallet-density economics through AS/RS systems operating at -25°C.
- Insulated Packaging:Phase-change materials and vacuum-insulated panels serve direct-to-patient pharmaceutical delivery, with reusable container programs threatening single-use economics in urban corridors.
Highest margin capture: Temperature Monitoring. Steepest expansion trajectory: Insulated Packaging.
End User:
Customer-type segmentation reveals a split between centralized procurement by retail conglomerates and fragmented ordering patterns in healthcare direct-to-patient channels.
- E-commerce:Frozen meal subscriptions and pharmaceutical home delivery fragment order profiles toward parcel-scale thermal protection. Automated sortation investments in Dallas-Fort Worth and Miami fulfillment centers address insulated packaging line throughput.
- Healthcare Providers:Hospital systems and specialty pharmacies require validated receiving infrastructure with 24/7 temperature logging, concentrating demand near major metropolitan medical districts.
- Retail Chains:National grocers drive pallet-scale throughput with private fleet backhaul optimization and centralized distribution center networks.
- Food Distributors:Broadline operators aggregate multi-temperature loads for independent restaurants, relying on cross-dock consolidation at Midwest refrigerated terminals.
Dominant procurement volume: Retail Chains. Gaining share fastest: E-commerce.
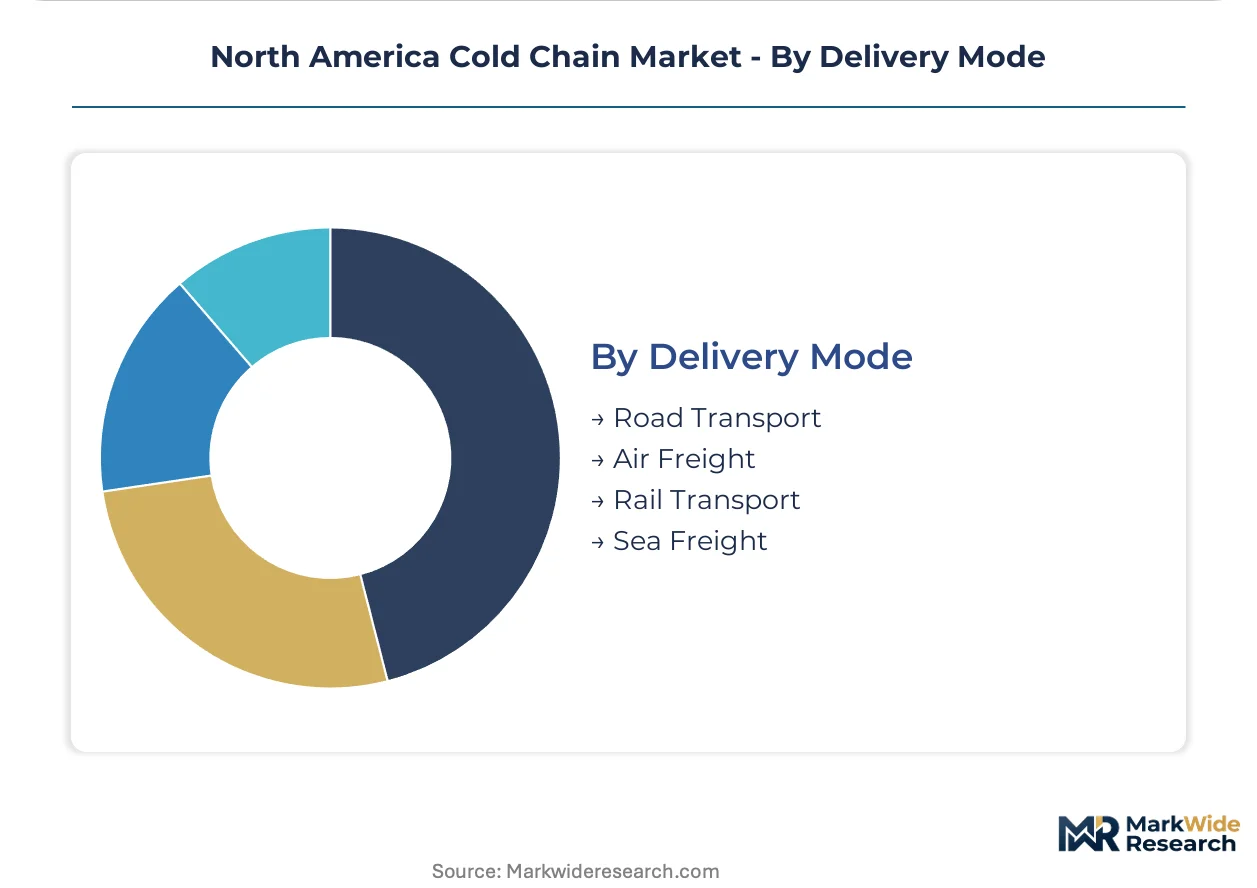
Delivery Mode:
Modal selection reflects distance-cost tradeoffs, with pharmaceutical time-sensitivity justifying air freight premiums unavailable to commodity frozen food economics.
- Road Transport:Diesel reefer trailers handle 85% of ton-miles across the United States heartland, with drayage concentration at Chicago and Memphis intermodal hubs reducing first-last mile costs for temperature-controlled containers.
- Air Freight:Cryogenic shipper containers and active temperature-controlled ULDs serve cell therapy clinical trials and emergency pharmaceutical shipments through Memphis and Louisville cargo hubs.
- Rail Transport:Refrigerated boxcar movements concentrate on California-to-Midwest produce corridors with 72-hour transit windows for apples and potatoes.
- Sea Freight:Reefer container flows through Port of Los Angeles and Port of Savannah handle South American fruit imports and protein exports to Asian markets.
Primary volume mode: Road Transport. Climbing the fastest: Air Freight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American cold chain concentration through its intermodal rail junctions and proximity to Midwest protein processing zones. The metropolitan area hosts the densest clustering of refrigerated warehousing square footage outside port gateways.
United States
FDA Drug Supply Chain Security Act mandates and EPA AIM Act refrigerant phasedowns are reshaping infrastructure investment priorities. The Inflation Reduction Act's domestic biologics manufacturing incentives are pulling pharmaceutical cold chain capacity toward Boston-Cambridge and Research Triangle Park corridors. Memphis and Louisville cargo hubs concentrate cryogenic logistics for cell therapy clinical trials.
Canada
Health Canada validation protocol divergence from FDA standards creates compliance complexity for cross-border pharmaceutical lanes. Provincial building codes in Ontario and Quebec are accelerating ahead of federal timelines on hydrofluorocarbon equipment phaseout. Toronto and Vancouver anchor temperature-controlled warehousing clusters serving Asian protein export flows and domestic grocery distribution.
Mexico
Produce export seasons to US markets drive surge capacity demands at Nuevo León and Baja California cold storage facilities. Mexican federal sanitary standards for refrigerated transport are tightening alignment with USDA inspection protocols. Guadalajara and Mexico City metropolitan areas are expanding automated high-bay freezer construction for multinational food processor consolidation.
North America Cold Chain Market Key Industry Players
Premium-margin players sit above commodity-margin players across validation intensity, with pharmaceutical-grade networks commanding audit-ready infrastructure while frozen food storage competes on cubic-foot throughput. The vendor base stratifies into three tiers: integrated warehouse-transport operators, specialized freezer storage developers, and technology-enabled monitoring providers. Dominant competitive moves include automated high-bay facility deployment and strategic port-adjacent capacity positioning.
Within the integrated warehouse-transport tier, Americold Logistics and Lineage Logistics exemplify scale-driven infrastructure concentration across Southeast and Southwest corridor networks. United States Cold Storage anchors protein-specialized positioning near major poultry and beef processing zones. These three operators represent divergent archetypes: ambient-to-frozen transition dominance, deep freezer automation leadership, and protein corridor density respectively.
| Leading Market Players |
|---|
| Americold Logistics |
| Lineage Logistics |
| United States Cold Storage |
| VersaCold Logistics Services |
| Burris Logistics |
| AGRO Merchants Group |
| Interstate Warehousing |
| Conestoga Cold Storage |
| NewCold |
| Others |
Cost & Logistics Intelligence
Transcritical CO2 refrigeration retrofits are compressing operating cost curves for FDA-validated warehouse operators while simultaneously concentrating supplier relationships around a narrow base of certified equipment vendors. This dual effect elevates compliance-grade cold storage pricing power against commodity frozen capacity, as capital barriers filter out undercapitalized competitors.
Pricing Analysis
Yield-guaranteed uptime contracts anchor pharmaceutical cold chain pricing, with biologics manufacturers paying premiums for validated temperature continuity rather than cubic-foot throughput. Three-tier pricing structure separates DSCSA-compliant pharmaceutical networks from protein-specialized frozen storage and undifferentiated commodity chill space. Cost compression in commodity frozen tiers is intensifying because reusable insulated packaging programs threaten single-use parcel economics. Retail chains exhibit acute price sensitivity on pallet-scale throughput, while gene therapy sponsors accept premium pricing for cryogenic logistics below -150°C.
Supply Chain Analysis
FDA 21 CFR Part 11 qualification requirements gate access to pharmaceutical-grade infrastructure, filtering equipment vendors and facility operators through extended validation timelines. Compressor manufacturing concentrates in Germany, Japan, and South Korea, with industrial refrigeration equipment drawing from concentrated European and Asian component bases. Single-source vulnerability runs through specialized CO2 and ammonia system suppliers facing extended lead times. Distribution runs through Chicago intermodal junctions and Memphis cargo hubs for temperature-controlled container flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cold chain operates as a cost-of-compliance market where FDA Drug Supply Chain Security Act mandates erect capital barriers that protect validated infrastructure operators from price-based competition.
For Market Incumbents: Cement dominance by accelerating automated high-bay freezer deployment in Research Triangle Park and Boston-Cambridge corridors before biologics reshoring peaks. Secure captive supply of transcritical CO2 compressor systems through preferred vendor agreements, insulating against European supplier lead time volatility that threatens expansion timelines. For New Entrants and Emerging Players: Begin with cross-border pharmaceutical lanes between Toronto and Detroit, exploiting Health Canada-FDA harmonization gaps that burden established operators with dual-certification overhead. Target direct-to-patient cryogenic delivery for cell therapy sponsors, where minute-level temperature monitoring requirements favor nimble technology-enabled entrants over legacy warehouse networks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated food conglomerates seeking pharmaceutical-grade validation capabilities. Long-term viability favors operators with parallel FDA-certified and USDA-inspected infrastructure across Midwest protein corridors. Watch EPA AIM Act state-level enforcement variance as the signal for stranded-asset risk concentration in HFC-dependent legacy freezer portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Automated High-Bay Freezer Deployment | AS/RS systems at -25°C achieve pallet-density economics that manual warehouses cannot match in Chicago clusters. |
| Dual-Certification Investment | Simultaneous FDA and Health Canada validation captures cross-border pharmaceutical lane premiums. |
| Refrigerant Retrofit Acceleration | Transcritical CO2 conversion ahead of EPA AIM Act deadlines prevents stranded-equipment risk in California and New York. |
| Cryogenic Logistics Capability Buildout | Below -150°C infrastructure positions operators for CAR-T commercialization surge in Boston-Cambridge corridor. |
| IoT Monitoring Platform Integration | Cellular-backhaul sensor networks embed minute-level excursion alerts into pharmaceutical service-level agreements. |
Research Approach
Document review covered FDA enforcement letters, EPA refrigerant phaseout schedules, and customs trade data for temperature-controlled equipment imports, complemented by interviews with cold chain operations directors, pharmaceutical quality assurance leads, refrigerated transport fleet managers, and biologics supply chain executives. Secondary validation drew from USDA inspection protocols, DOT hazardous materials filings, and state-level building code amendments. Bottom-up facility capacity tallies triangulated against top-down pharmaceutical distribution spend estimates.
Market size outputs reflect segment-level modeling across product type, temperature band, and end-user procurement archetype, with growth trajectories derived from regulatory mandate timelines and biologics manufacturing reshoring patterns. The analytical framework incorporated EPA AIM Act compliance deadlines, DSCSA serialization requirements, and cell therapy clinical trial expansion curves as demand-side inputs. CAGRs were calibrated against historical cold storage construction permitting data and intermodal container flow volumes.
Underlying measurement precision varies by segment; pharmaceutical-grade networks carry tighter precision than commodity frozen storage due to validated facility registries. Forecasts assume sustained FDA enforcement intensity and continued biologics manufacturing incentives under federal production policy. Stakeholders should weight assumptions against their own operating context and regional regulatory variance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Cooling Boxes Market