
 Cold Box Module Market | 2026-2036
Cold Box Module Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Box Module Market Analytics
Germany is narrowing its engineering lead in cryogenic cold box fabrication as Linde plc leverages its industrial gas heritage to dominate turnkey LNG and air separation projects. Chart Industries anchors North American production with specialized brazed aluminum heat exchanger capacity, while Air Liquide competes through integrated offerings spanning design, module fabrication, and site commissioning services.
A cold box module is a prefabricated, insulated enclosure housing heat exchangers, distillation columns, piping, and cryogenic equipment engineered to operate below minus 150 degrees Celsius for gas separation and liquefaction processes. The assembly typically employs vacuum perlite or polyurethane foam insulation around aluminum or stainless steel process cores to minimize thermal leakage and boil-off losses. Single cold box configurations retain the largest installed base across mature air separation units, though multi-box architectures are gaining traction in floating LNG applications where modular weight constraints dictate distributed cryogenic trains. Thermoelectric cooling occupies niche precision roles in electronics and laboratory settings, while vapor compression remains the workhorse technology for industrial-scale deployment despite refrigerant transition pressures.
The EPA enforces Significant New Alternatives Policy requirements for industrial refrigerants, directly influencing cold box module specification sheets and supplier qualification protocols. ECHA's REACH framework governs material compliance for insulation foams and sealants used in European-manufactured units, while China's GB standards and MEE directives shape import acceptance criteria for cryogenic equipment deployed in domestic LNG terminals. Stakeholders must track refrigerant phase-down schedules against equipment replacement cycles to avoid stranded asset exposure in long-life industrial installations.
Market Dynamics
The European Union's F-Gas Regulation is forcing refrigerant transitions across vapor compression systems while Qatar and United States LNG developers accelerate cryogenic procurement timelines. This dual pressure is compressing supplier qualification cycles and concentrating fabrication capacity among certified turnkey providers.
Growth Catalysts
- Feedstock Diversification:LNG infrastructure developers in Qatar are expanding cryogenic storage procurement as natural gas liquefaction capacity scales. This is pulling demand for large-format cold box modules with integrated brazed aluminum heat exchangers.
- REACH Material Compliance:ECHA's framework is standardizing insulation foam and sealant specifications across European-manufactured units. Chemical producers in Germany's industrial corridor are retrofitting cold chain systems to align with hydrogen economy integration mandates.
- Air Separation Retrofits:Industrial gas operators are replacing legacy cold box cores with vacuum perlite-insulated configurations. Single-box architectures retain the largest installed base while multi-box designs gain traction in weight-constrained floating LNG applications.
Market Restraints
- Aluminum Alloy Supply Concentration:Brazed aluminum heat exchanger fabrication depends on specialized alloy supply chains concentrated in North American and European smelter networks. Geopolitical friction is extending lead times for aerospace-grade material qualification.
- Cryogenic Weld Certification Bottlenecks:ASME Section VIII and EN 13445 compliance for stainless steel process cores requires certified welder pools that are structurally limited across fabrication hubs. Training cycles lag equipment replacement timelines by 18-24 months.
- Thermoelectric Cooling Niche Lock:Solid-state cooling occupies precision electronics and laboratory settings but cannot scale to industrial liquefaction loads. This caps addressable market expansion for modular cold box suppliers in sub-megawatt segments.
Strategic Opportunities
- Hydrogen Liquefaction Infrastructure:Germany's chemical corridor is retrofitting cryogenic systems for liquid hydrogen storage and transport. Cold box modules engineered for minus 253 degrees Celsius operation are capturing early-mover positioning in European clean hydrogen hubs.
- EPA SNAP Refrigerant Pathways:The Significant New Alternatives Policy is creating qualification windows for lower-GWP refrigerants in vapor compression cold boxes. Equipment suppliers can secure first-mover advantage by pre-certifying module configurations ahead of phase-down deadlines.
- Floating LNG Modularization:Distributed cryogenic train architectures are displacing centralized cold box designs in offshore applications. Multi-box configurations reduce single-lift weight constraints and enable shipyard assembly of liquefaction modules.
Industry Challenges
- Cryogenic System Integration Complexity:Retrofitting legacy air separation units with modern cold box modules requires thermal cycling analysis and piping stress reconciliation. Site commissioning timelines extend when existing distillation columns must interface with new vacuum-insulated enclosures.
- Cross-Border Certification Fragmentation:China's GB standards and MEE directives impose acceptance criteria that diverge from ASME and EN frameworks. Suppliers must maintain parallel documentation sets for equipment destined to domestic LNG terminals versus export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Box Module Market |
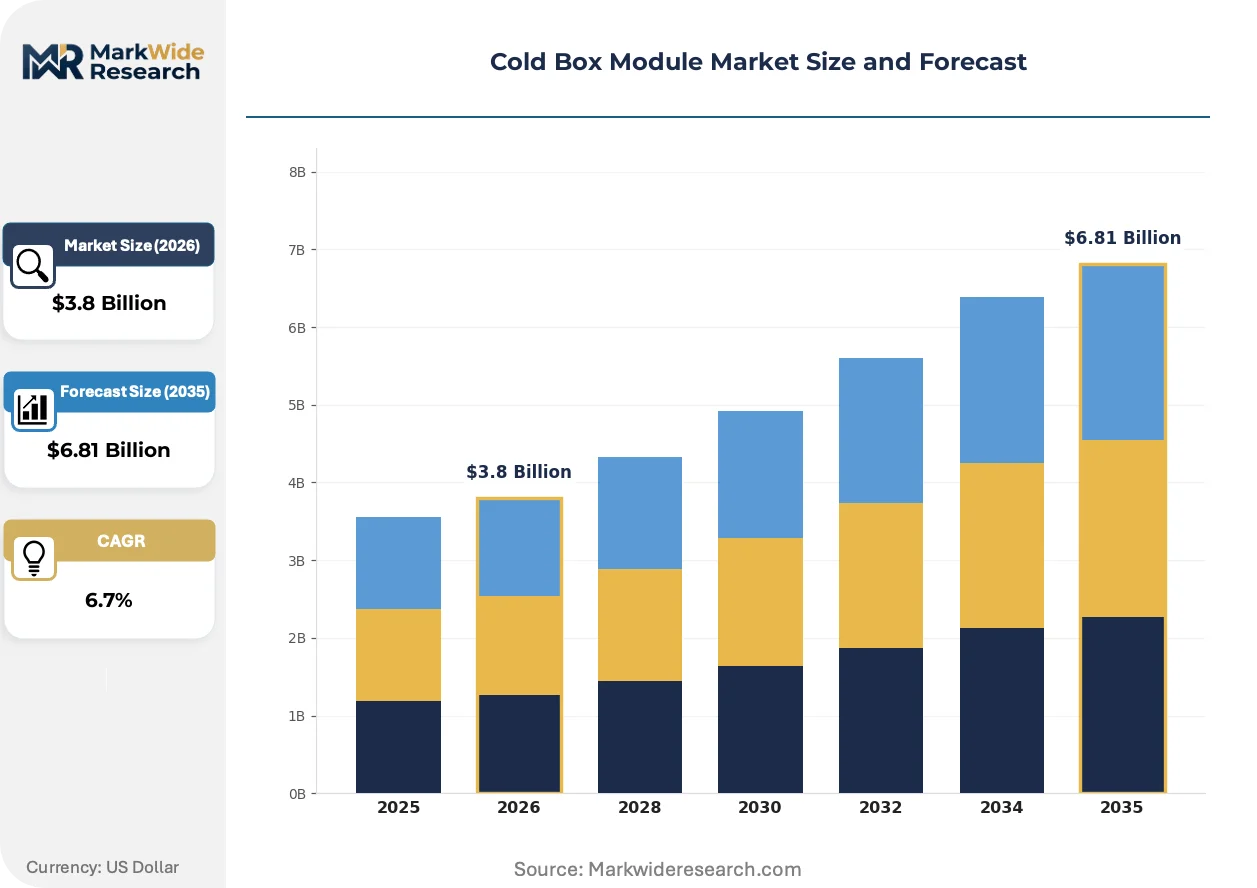
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cold Box, Dual Cold Box, Multi-Box, Customized Cold Box Application: Food Processing, Pharmaceuticals, Chemicals, Electronics End User: Manufacturers, Distributors, Retailers, Research Institutions Technology: Vapor Compression, Thermoelectric, Absorption Cooling, Liquid Nitrogen |
| Companies Covered | Linde plc, Emerson Electric Co., Chart Industries, Inc., Air Liquide, Nikkiso Clean Energy & Industrial Gases Group, Beijing Tianhai Industry Co Ltd, Cryofab Inc, HeLIUM Cryogenics, Kelvion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Box Module Market Evolving Landscape
Refrigerant chemistry transitions and modular fabrication methods are compressing traditional equipment replacement cycles. Suppliers are reconfiguring production lines to accommodate multi-box architectures while regulatory pressure accelerates low-GWP technology qualification.
Microchannel heat exchanger technology is collapsing the thermal footprint of cryogenic cold box cores. LNG developers in the United States are specifying these configurations for onshore liquefaction trains. The technology is collapsing the physical envelope required per unit of liquefaction capacity, enabling smaller plot plans and reduced insulation volumes.
The European Union's F-Gas Regulation is mandating hydrofluorocarbon phase-down schedules that directly impact vapor compression cold box specifications. Equipment suppliers must now qualify alternative refrigerants with lower global warming potential across the full operating temperature range. Chemical producers in Germany are prioritizing cold box vendors with pre-certified low-GWP configurations to avoid stranded asset exposure.
Buyer organizations are consolidating procurement authority for cryogenic equipment under centralized engineering teams. Industrial gas majors are replacing distributed site-level purchasing with global framework agreements that specify standardized module configurations. This concentration is most visible in Qatar's LNG expansion program, where developers are pre-qualifying turnkey suppliers for multi-train liquefaction complexes.
Cold Box Module Market Segmentation
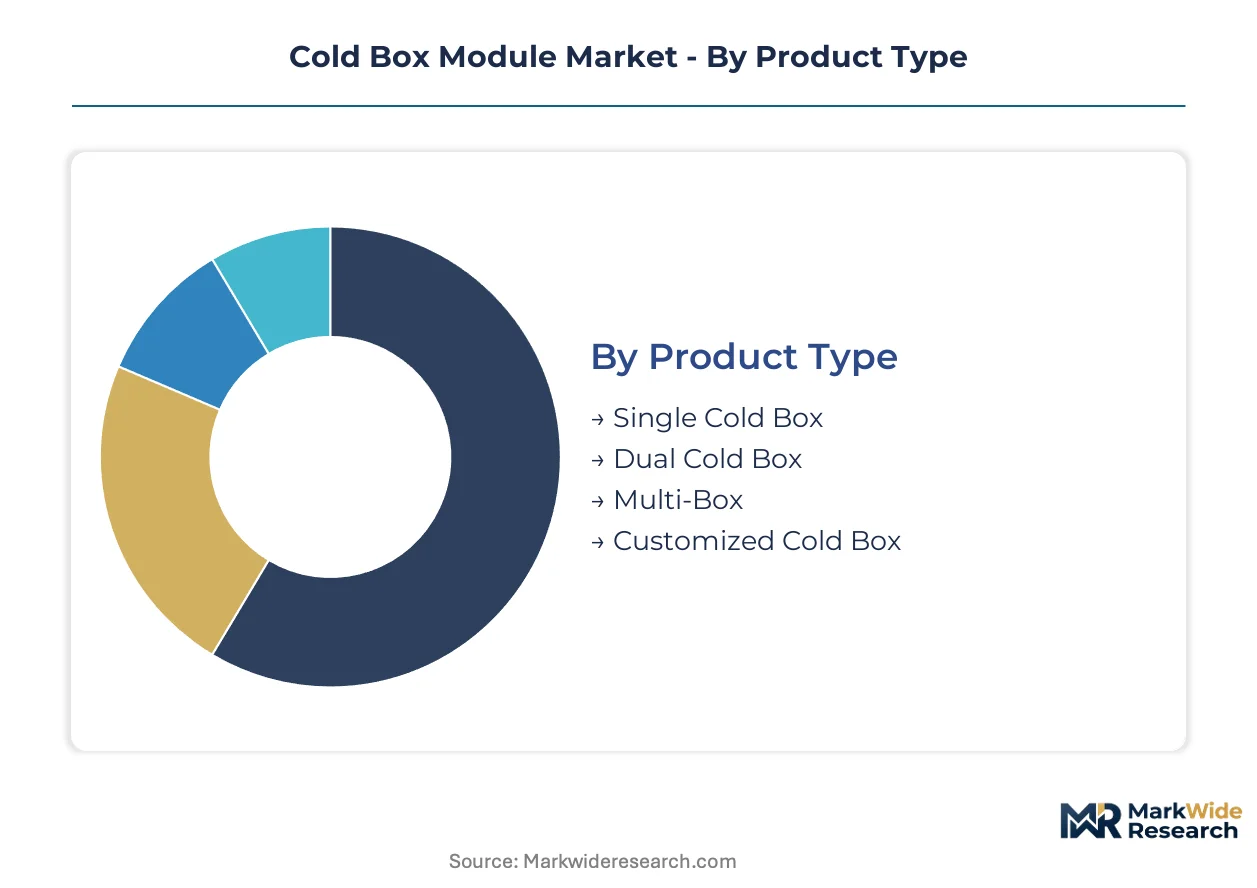
Cold box module procurement cycles vary dramatically by configuration complexity and end-use criticality. Single-box replacements in mature air separation units run 15-20 year cycles, while floating LNG multi-box installations turn over faster due to weight constraint evolution and modular upgrade paths.
Product Type:
Replacement velocity diverges sharply between standardized architectures and engineered-to-order systems, with implications for supplier working capital and fabrication scheduling.
- Single Cold Box:Vacuum perlite-insulated enclosures with integrated brazed aluminum heat exchangers dominate legacy air separation retrofits. Demand concentrates in Germany's industrial corridor where Linde plc and Air Liquide are replacing aging process cores to align with hydrogen economy integration mandates.
- Multi-Box:Distributed cryogenic train architectures employ separate vacuum-insulated enclosures for pre-cooling, liquefaction, and sub-cooling stages. Qatar's LNG expansion program is specifying these configurations to circumvent single-lift weight constraints in offshore applications.
- Dual Cold Box:Split-process designs separate warm-end and cold-end functions across two insulated enclosures. Chemical producers in the United States deploy these for mid-scale hydrogen liquefaction pilot projects.
- Customized Cold Box:Engineered-to-order configurations accommodate non-standard process pressures or exotic material specifications. Research institutions commission these for laboratory-scale cryogenic distillation experiments.
Single Cold Box dominates installed base. Multi-Box is where expansion concentrates.
Application:
End-use margins and certification burden stratify procurement authority, with food processing running commodity tenders and pharmaceuticals demanding validated qualification documentation.
- Food Processing:Blast freezing and cold storage applications specify standardized vapor compression cold boxes with polyurethane foam insulation. Germany's retail logistics sector is retrofitting distribution centers with lower-GWP refrigerant configurations to preempt EU F-Gas Regulation penalties.
- Pharmaceuticals:cGMP-validated cold boxes maintain temperature bands within plus-or-minus 2 degrees Celsius for vaccine and biologic storage. The United States FDA enforces cold chain documentation requirements that extend commissioning timelines by 6-12 months.
- Chemicals:Hydrocarbon separation and cryogenic reaction cooling demand ASME Section VIII certified process cores. Qatar's petrochemical complex developers source these through pre-qualified turnkey frameworks.
- Electronics:Semiconductor manufacturing employs compact thermoelectric cold boxes for precision temperature control in wafer processing. These occupy a niche above vapor compression scale floors but below industrial liquefaction loads.
Food Processing commands volume leadership. Pharmaceuticals carries the steepest expansion trajectory.
End User:
Procurement sophistication scales with technical staff depth, fragmenting supplier engagement models across self-service specification and engineered turnkey delivery.
- Manufacturers:Industrial gas producers and chemical operators maintain in-house cryogenic engineering teams that specify module components separately. Air Liquide and Linde plc leverage this capability to source brazed aluminum heat exchangers and vacuum-insulated enclosures from different suppliers.
- Distributors:Third-party logistics providers purchase standardized cold box configurations through framework agreements with minimal customization. These buyers prioritize lead time certainty over technical specification flexibility.
- Retailers:Supermarket chains and cold storage operators deploy vapor compression cold boxes for distribution center refrigeration. Germany's discount grocery sector is consolidating procurement under centralized engineering teams to standardize module configurations.
- Research Institutions:National laboratories and university facilities commission customized cold boxes for experimental cryogenics. These orders run smallest volume but highest margin due to engineering-intensive specification development.
Manufacturers anchor specification authority. Research Institutions represent the highest-margin addressable segment.
Technology:
Refrigerant chemistry transitions and energy efficiency mandates are compressing technology replacement cycles, with vapor compression systems facing accelerated obsolescence risk from phase-down schedules.
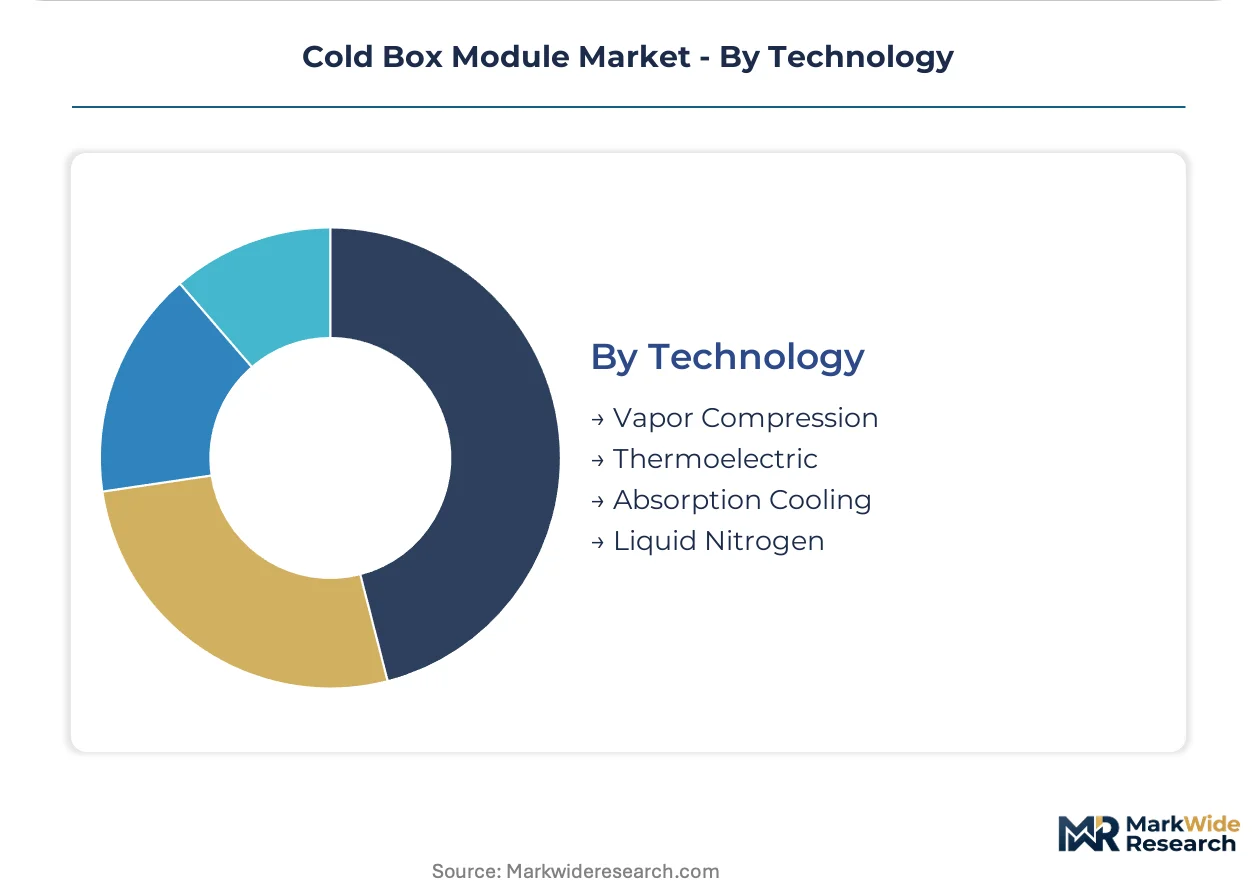
- Vapor Compression:Mechanical refrigeration cycles employing hydrofluorocarbon or lower-GWP alternatives remain the workhorse for industrial-scale deployment. The EPA's Significant New Alternatives Policy is forcing refrigerant transitions that require module re-qualification.
- Liquid Nitrogen:Open-loop cryogenic cooling eliminates refrigerant management but imposes logistics complexity for bulk nitrogen supply. Electronics manufacturers in the United States deploy these for cleanroom applications where compressor vibration is unacceptable.
- Thermoelectric:Solid-state Peltier devices provide precision temperature control without moving parts. Laboratory and medical device applications favor these despite higher energy consumption per cooling unit.
- Absorption Cooling:Heat-driven refrigeration cycles using ammonia-water or lithium bromide pairs suit waste heat recovery scenarios. Industrial cogeneration facilities in Germany pilot these for process cooling integration.
Vapor Compression retains the largest installed footprint. Liquid Nitrogen is gaining share fastest in precision electronics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized alloy supply chains and certified fabrication capacity concentrate in Germany, the United States, Qatar, China, and Japan. Each jurisdiction shapes procurement through distinct regulatory frameworks and industrial clustering patterns.
United States
LNG developers along the Gulf Coast are accelerating cryogenic procurement timelines for liquefaction train expansions. The EPA enforces Significant New Alternatives Policy requirements that directly influence cold box module specification sheets and supplier qualification protocols. Houston anchors North American production with concentrated brazed aluminum heat exchanger fabrication capacity serving export terminal projects.
Germany
Chemical producers in the industrial corridor are retrofitting cold chain systems for hydrogen economy integration mandates. ECHA's REACH framework governs material compliance for insulation foams and sealants used in European-manufactured units. The Ruhr region concentrates engineering expertise for turnkey LNG and air separation projects leveraging legacy industrial gas infrastructure.
Qatar
LNG infrastructure developers are expanding cryogenic storage procurement as natural gas liquefaction capacity scales. National procurement frameworks prioritize pre-qualified turnkey suppliers for multi-train liquefaction complexes. Ras Laffan Industrial City hosts concentrated fabrication coordination for floating LNG applications requiring distributed cryogenic train architectures.
China
Domestic LNG terminal operators are driving import substitution for cryogenic equipment under GB standards and MEE directives. The country's national environmental regulator imposes acceptance criteria that diverge from ASME and EN frameworks. Yangtze River Delta shipyards are assembling modular liquefaction units for offshore deployment.
Japan
Industrial gas operators are replacing legacy cold box cores with vacuum perlite-insulated configurations for air separation retrofits. METI standards shape domestic certification requirements for cryogenic weld procedures and material specifications. Osaka-based engineering groups coordinate technology licensing for hydrogen liquefaction pilot projects.
Cold Box Module Market Competitive Landscape
Industrial gas heritage conglomerates and specialized cryogenic fabricators split the market across turnkey project delivery and component supply vectors. Consolidation pressure concentrates fabrication capacity among certified providers capable of spanning design, module fabrication, and site commissioning services. Three strategic archetypes dominate: integrated industrial gas majors with in-house engineering depth, standalone heat exchanger specialists with captive alloy supply relationships, and regional fabricators serving domestic terminal operators. Competitive moves center on pre-qualification racing for LNG expansion frameworks and backward integration into aerospace-grade aluminum alloy sourcing.
Within the integrated industrial gas tier, Linde plc and Air Liquide exemplify turnkey positioning spanning cryogenic system design through commissioning. Chart Industries occupies a position as a North American fabricator with specialized brazed aluminum capacity. Among Asia-Pacific specialists, Nikkiso Clean Energy & Industrial Gases Group represents Japanese engineering heritage in clean energy applications. Beijing Tianhai Industry Co Ltd anchors Chinese domestic production for LNG infrastructure deployment.
| Leading Market Players |
|---|
| Linde plc |
| Emerson Electric Co. |
| Chart Industries, Inc. |
| Air Liquide |
| Nikkiso Clean Energy & Industrial Gases Group |
| Beijing Tianhai Industry Co Ltd |
| Cryofab Inc |
| HeLIUM Cryogenics |
| Kelvion |
| Others |
Value Network & Pricing Analysis
Brazed aluminum heat exchanger fabrication concentrates in North American and European smelter networks, anchoring margin pools with certified turnkey providers capable of spanning design through commissioning. Aerospace-grade alloy qualification bottlenecks compress pricing power for second-tier fabricators while industrial gas majors extract premiums through integrated service bundling.
Pricing Analysis
The EPA's Significant New Alternatives Policy dictates the pricing tier structure across vapor compression cold box configurations. Three-tier pricing separates ASME-certified premium modules from standard EN-compliant units and economy-grade China GB-destined equipment, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from refrigerant re-qualification costs as hydrofluorocarbon phase-downs accelerate, with distributors exhibiting highest price sensitivity and research institutions least.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for cryogenic equipment procurement. Fabrication draws from specialized aluminum alloy supply chains in the United States, Germany, and Japan, with brazed heat exchanger cores, vacuum perlite insulation, and stainless steel process piping as critical input dependencies. Single-source vulnerability around aerospace-grade material qualification concentrates with ASME-certified welder pools, while distribution runs through pre-qualified turnkey frameworks for LNG developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold box module procurement is consolidating under platform-economics logic as industrial gas majors standardize global framework agreements, with hydrogen liquefaction interoperability emerging as the decisive ecosystem inflection.
For Market Incumbents: Harden backward integration into aerospace-grade aluminum alloy sourcing to defend against emerging Asian fabricators with captive smelter relationships. Priority capacity addition in Germany's industrial corridor secures hydrogen economy positioning, while pre-certifying low-GWP refrigerant configurations ahead of EPA SNAP deadlines locks in LNG developer loyalty. For New Entrants and Emerging Players: Build out modular fabrication capacity serving China's domestic LNG terminal operators under GB standards compliance as the most penetrable geography. Target research institutions with customized cold box configurations for laboratory-scale cryogenic distillation, leveraging engineering-intensive specification development as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed heat exchanger specialists with stranded aerospace supply contracts. Long-term viability centers on hydrogen liquefaction infrastructure deployment across European clean hydrogen hubs. Watch German chemical corridor retrofit announcements as the inflection signal for cold box module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive aerospace-grade aluminum sourcing secures ASME certification continuity for Linde plc and Chart Industries. |
| Low-GWP Refrigerant Pre-Certification | EPA SNAP compliance ahead of phase-down deadlines captures first-mover positioning with Qatar LNG developers. |
| Hydrogen Liquefaction Module Development | Minus 253 degrees Celsius engineering capability anchors turnkey contracts across Germany's clean hydrogen hubs. |
| Multi-Box Offshore Architecture Expansion | Distributed cryogenic train designs circumvent single-lift weight constraints for floating LNG applications at Ras Laffan. |
| GB Standards Compliance Investment | Parallel documentation sets for China's MEE directives unlock domestic LNG terminal procurement against import substitution policy. |
Research Methodology
Cross-validation between primary interviews with cryogenic engineering directors and secondary validation through SEC filings anchors the qualitative findings. Conversations with plant managers at industrial gas facilities, procurement leads at LNG developers, EPC contractors for liquefaction projects, and aftermarket service heads for air separation units combined with customs trade data, ASME certification records, and EPA SNAP regulatory filings. Bottom-up module shipment tallies and top-down industrial gas capital expenditure triangulation structured the market sizing.
Calibration against historical replacement cycles for vacuum perlite-insulated configurations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type complexity, application criticality, end-user procurement sophistication, and refrigerant technology pathway, with hydrogen economy integration mandates and F-Gas Regulation phase-down schedules as industry-specific forecast inputs. CAGRs derived from equipment replacement timelines against capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by emerging Asian fabricators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Refrigeration Packaging Market