
 Freezer Liner Market | 2026-2036
Freezer Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Freezer Liner Market Analysis
Asset-light leasing models for commercial refrigeration equipment are tilting competitive dynamics toward liner suppliers with flexible contract terms. Reynolds Consumer Products leverages its retail channel density to sustain recurring revenue streams from replacement cycles. Mansfield Paper anchors its position through backward integration into coated paperboard feedstock, insulating margin pools from resin volatility. Komar Alliance differentiates by specializing in custom die-cut formats for walk-in freezer installations, occupying a niche that resists commodity erosion.
Freezer liners are barrier-coated sheet materials, typically laminated polyethylene or aluminum-composite constructions between 0.5 mm and 3 mm thick, engineered to prevent moisture migration and thermal bridging within refrigerated enclosures. Their primary commercial purpose is to protect insulation substrates from ice accumulation while enabling hygienic surface cleaning in temperature-controlled storage environments. Polyethylene formulations dominate volume due to cost scalability across residential and commercial applications, while aluminum-composite laminates command premium positioning in industrial freezers where thermal reflectivity requirements are stringent. The thickness dimension stratifies around medium-gauge specifications for standard commercial units, with thick and extra-thick categories capturing growth in cold storage warehouses handling fluctuating thermal loads.
The US FDA's Food Safety Modernization Act sanitary surface requirements and the EPA's Significant New Alternatives Policy for refrigerant containment are tightening material compatibility standards for liner substrates in food-contact applications. REACH compliance in Europe restricts certain phthalate plasticizers in PVC-based liners, redirecting formulation investment toward polypropylene and polyethylene alternatives. China's GB standards for cold chain logistics equipment are mandating liner durability testing under cyclic freeze-thaw conditions. Stakeholders must monitor how refrigerant transition timelines synchronize with liner material qualification cycles to avoid stranded inventory positions.
Market Dynamics
The US EPA's phasedown of hydrofluorocarbon refrigerants is forcing cold chain operators to replace entire liner systems ahead of historical replacement cycles, compressing demand timing and elevating material specification requirements across refrigerated transport and stationary storage assets.
Growth Catalysts
- Refrigerant Transition Mandates:The EPA's Significant New Alternatives Policy is disqualifying legacy vapor-barrier materials, creating replacement demand for qualified liner substrates that maintain thermal integrity under new refrigerant chemistries.
- Cold Chain Logistics Expansion:Third-party refrigerated transport fleets in Germany are consolidating liner specifications across centralized distribution networks, standardizing procurement volumes and reducing supplier fragmentation.
- Food Retail Consolidation:Supermarket chain mergers are driving uniform liner material standards across multi-site freezer estates, eliminating ad-hoc specification diversity and accelerating volume commitments to approved suppliers.
Market Restraints
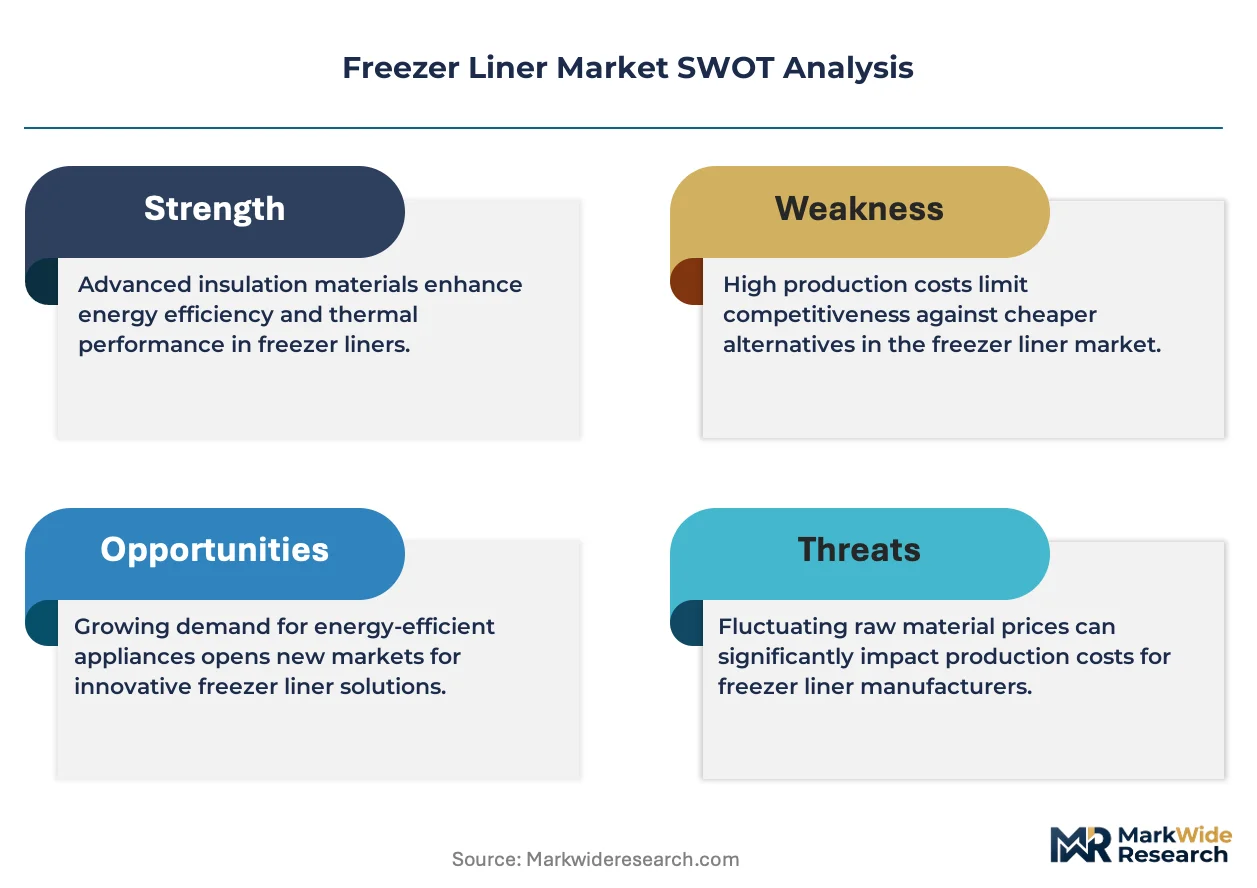
- Resin Price Volatility:Polyethylene feedstock costs fluctuate with crude oil benchmarks, compressing margin pools for non-integrated converters who lack captive supply of coated paperboard or laminated substrates.
- REACH Compliance Burden:ECHA restrictions on phthalate plasticizers in PVC-based liners are forcing formulation pivots toward polypropylene and polyethylene alternatives, extending R&D timelines and qualification costs.
- Aluminum-Composite Substitution Ceiling:Premium aluminum-composite laminates face demand elasticity limits in cost-sensitive residential segments, constraining volume expansion beyond industrial freezer applications where thermal reflectivity commands price premiums.
Strategic Opportunities
- Asset-Light Leasing Channels:Commercial refrigeration equipment lessors are unbundling liner replacement from capital equipment contracts, creating recurring revenue streams for suppliers with flexible service terms and rapid turnaround capabilities.
- GB Standard Alignment in China:China's national standards for cold chain logistics equipment are mandating cyclic freeze-thaw durability testing, opening qualification pathways for certified liner producers who can document performance under thermal stress protocols.
- Die-Cut Customization for Walk-In Installations:Precision-cut liner formats for irregular freezer geometries represent an underserved niche resistant to commodity pricing pressure, rewarding specialized fabrication capabilities.
Industry Challenges
- Refrigerant-Liner Qualification Synchronization:Stakeholders risk stranded inventory when refrigerant transition timelines misalign with liner material certification cycles, requiring coordinated R&D roadmaps between chemical suppliers and substrate converters.
- Sanitary Surface Compliance Complexity:The FDA's Food Safety Modernization Act imposes evolving material compatibility standards for food-contact applications, demanding continuous substrate reformulation and documentation updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freezer Liner Market |
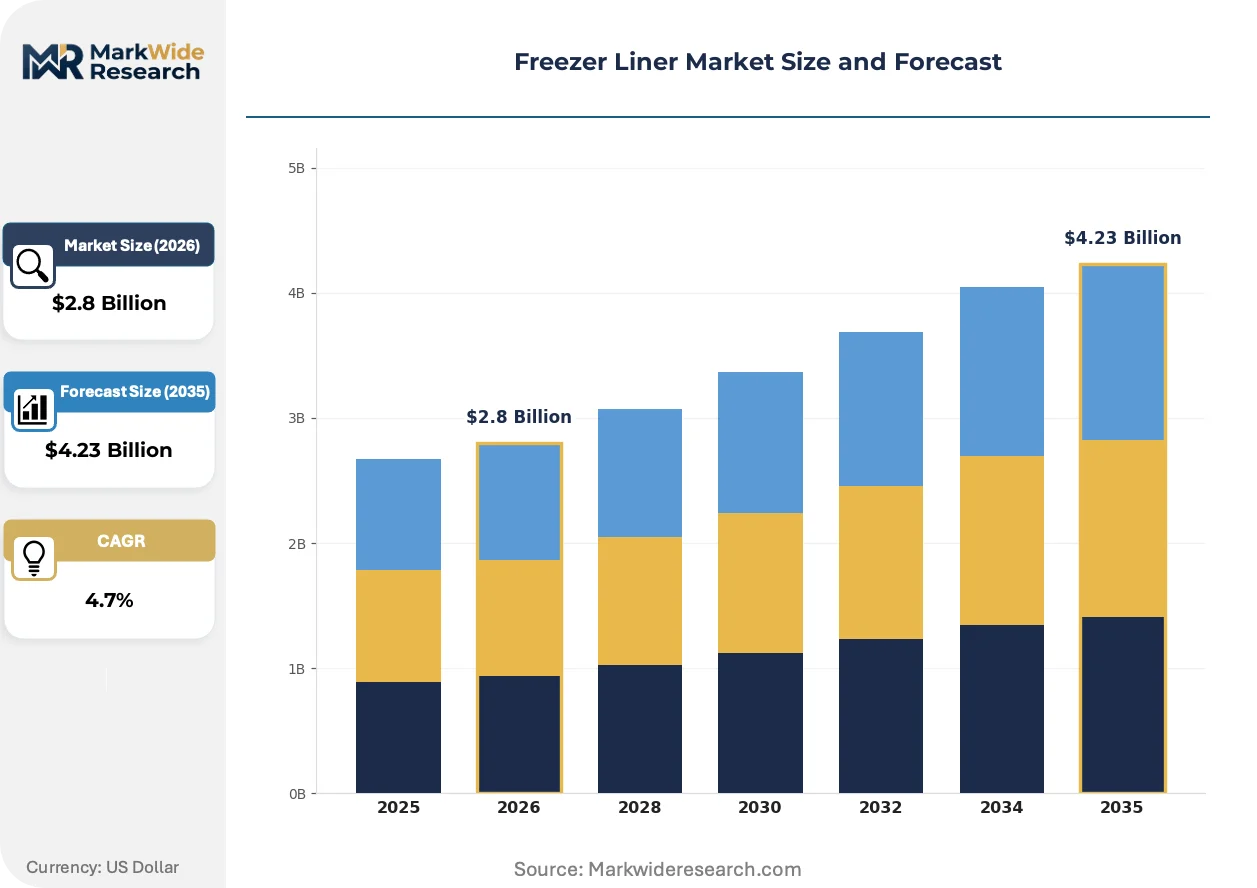
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, Polypropylene, PVC, Aluminum Application: Commercial Freezers, Residential Freezers, Industrial Freezers, Walk-in Freezers Thickness: Thin, Medium, Thick, Extra Thick Finish Type: Glossy, Matte, Textured, Smooth |
| Companies Covered | Mansfield Paper, Hangzhou Hongchang Paper Products, Reynolds Consumer Products, Zhuji Fred Packaging, Shandong Zhongrong Paper Products, Komar Alliance, Guangzhou Jieshen Paper, Zhejiang Heyi Tianze Industry and Trade, Intercon Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freezer Liner Market Emerging Trajectories
Digital specification tools and predictive replacement scheduling are compressing traditional procurement cycles, while regulatory material bans and thermal performance standards are elevating technical barriers to liner qualification.
Multi-layer vapor-barrier films with embedded sensor compatibility are virtualizing traditional liner inspection protocols. Cold storage warehouse operators in the US are adopting these smart substrates to enable real-time moisture intrusion detection without physical liner removal. This capability is virtualizing scheduled maintenance routines into condition-based interventions, reducing labor costs and downtime frequency.
The EU F-Gas Regulation is accelerating refrigerant containment requirements that cascade into liner material specifications. Industrial freezer operators must now document vapor transmission rates under specific thermal gradients, disqualifying legacy polyethylene formulations that lack certified barrier performance. German food retail chains are responding by pre-qualifying liner suppliers against consolidated specification matrices before fleet-wide rollout commitments.
Foodservice distributors are consolidating vendor relationships to reduce qualification overhead. Multi-site operators in North America are replacing fragmented regional liner sourcing with national framework agreements that bundle specification compliance, logistics coordination, and volume pricing. This concentration is most visible among institutional catering contractors managing centralized procurement for hospital and university freezer estates.
Freezer Liner Market Segmentation
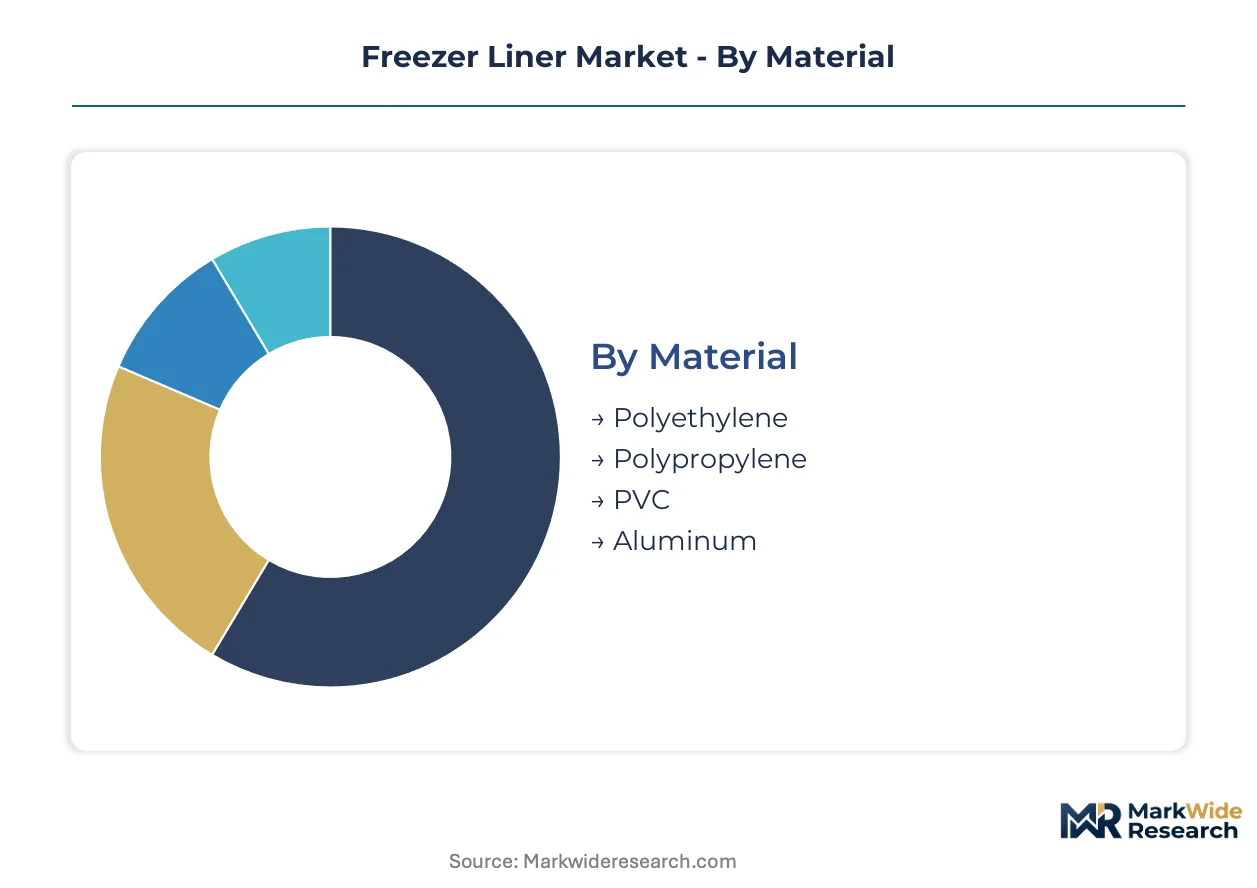
Freezer liner procurement stratifies across material chemistry, installation geometry, and thermal load specifications. Buyers segment purchases by vapor-barrier performance requirements and surface durability under cyclic freeze-thaw conditions.
Material:
Cost tier determines material selection across residential, commercial, and industrial freezer applications. Polyethylene formulations dominate volume due to feedstock scalability, while aluminum-composite laminates command premium positioning in high-performance installations.
- Polyethylene:Laminated polyethylene sheets between 0.5 mm and 3 mm thick provide moisture migration resistance at lowest unit cost. Demand concentrates in Germany's centralized food retail distribution networks where standardized procurement favors cost-scalable formulations.
- Polypropylene:Polypropylene alternatives are displacing PVC formulations restricted under ECHA REACH phthalate regulations. German cold chain logistics operators are pre-qualifying polypropylene suppliers against consolidated specification matrices ahead of fleet-wide rollouts.
- PVC:Legacy PVC liners face formulation pivots as REACH compliance burdens extend R&D timelines for plasticizer alternatives.
- Aluminum:Aluminum-composite laminates deliver thermal reflectivity for industrial freezers with stringent vapor-barrier requirements.
Polyethylene holds installed capacity. Polypropylene is rotating up the share rankings.
Application:
Installation geometry drives specification divergence between standardized units and custom-fabricated walk-in enclosures. Cold chain logistics expansion is elevating commercial and industrial segments while residential demand faces aluminum-composite substitution ceilings.
- Commercial Freezers:Supermarket and foodservice freezer estates require medium-gauge liners with FDA Food Safety Modernization Act sanitary surface compliance. US EPA refrigerant phasedown mandates are compressing replacement cycles across third-party refrigerated transport fleets.
- Industrial Freezers:Cold storage warehouses handling fluctuating thermal loads specify thick and extra-thick aluminum-composite laminates with embedded sensor compatibility for real-time moisture intrusion detection.
- Residential Freezers:Cost-sensitive residential segments constrain premium aluminum-composite volume expansion.
- Walk-in Freezers:Irregular geometries demand precision die-cut formats resistant to commodity pricing pressure.
Commercial Freezers anchor current procurement volumes. Industrial Freezers are climbing the fastest as cold storage warehouse operators adopt smart substrate technologies.
Thickness:
Volume scale stratifies around medium-gauge specifications for standard commercial units, with thick categories capturing growth in thermal-load-intensive installations. Thickness selection directly correlates with cyclic freeze-thaw durability requirements under China's GB standards.
- Medium:Standard commercial freezer units specify medium-gauge polyethylene or polypropylene liners balancing cost and thermal integrity. German food retail consolidation is standardizing medium-gauge procurement volumes across centralized distribution networks.
- Thick:Thick specifications address cold storage warehouses with fluctuating thermal loads and extended duty cycles. US cold storage operators are qualifying thick-gauge substrates under EPA Significant New Alternatives Policy refrigerant containment requirements.
- Thin:Thin liners serve residential applications with moderate thermal bridging protection needs.
- Extra Thick:Extra-thick categories target industrial installations with maximum vapor-barrier performance requirements.
Medium holds installed capacity. Thick is gaining share fastest as thermal-load specifications tighten.
Finish Type:
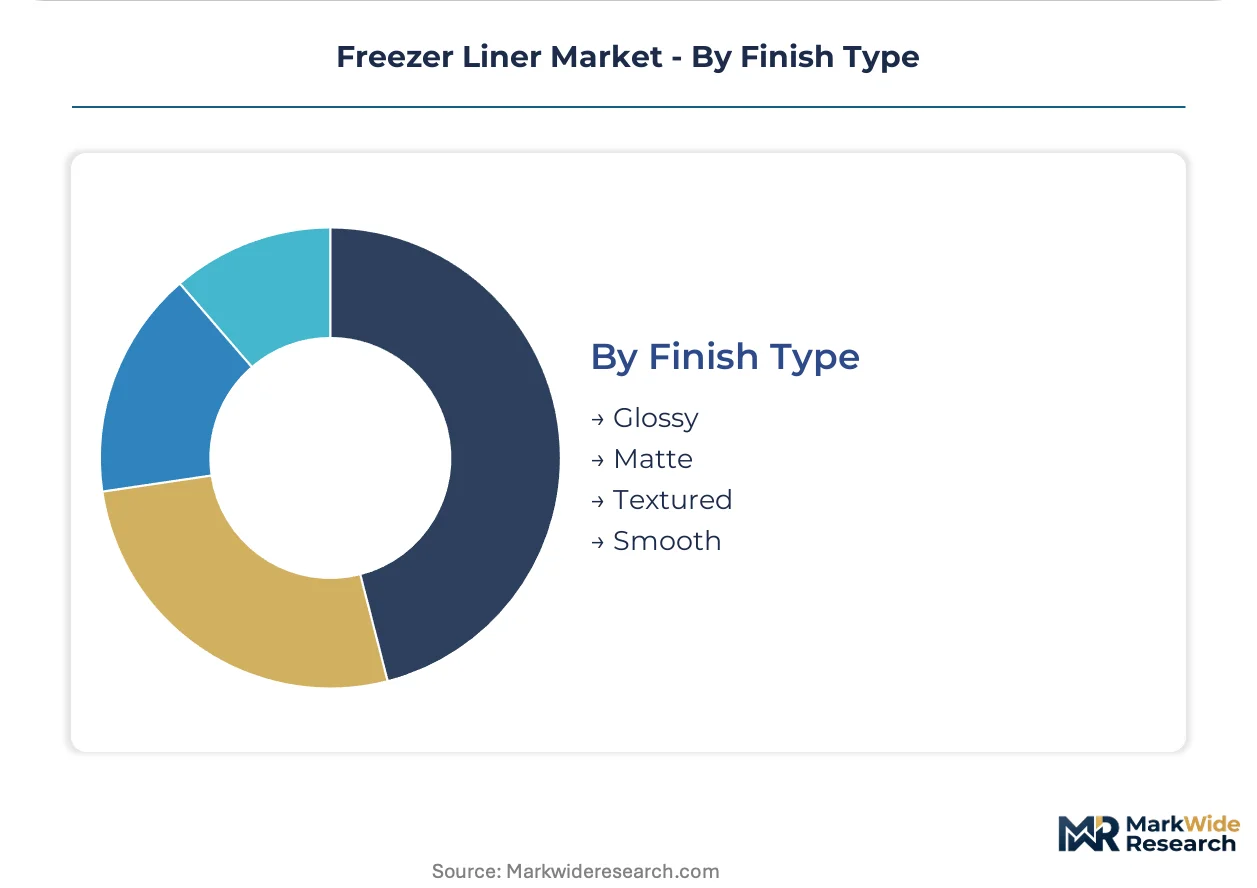
Surface texture determines hygienic cleaning protocols and aesthetic integration with freezer interior designs. Food-contact applications prioritize smooth and glossy finishes that satisfy FDA sanitary surface requirements.
- Smooth:Smooth finishes enable rapid hygienic surface cleaning in temperature-controlled food storage environments. US FDA Food Safety Modernization Act compliance favors smooth substrates that eliminate microbial harborage points.
- Glossy:Glossy surfaces provide visual inspection clarity for ice accumulation and liner integrity monitoring. German industrial freezer operators specify glossy finishes to support condition-based maintenance protocols.
- Matte:Matte finishes reduce glare in commercial display freezer applications.
- Textured:Textured surfaces offer slip resistance in walk-in freezer floor installations.
Smooth holds installed capacity. Glossy is rotating up the share rankings as real-time inspection protocols virtualize maintenance routines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in freezer liner materials tilt toward net-importing markets in Europe and North America, while Chinese and Indian converters supply cost-scalable polyethylene formulations to cold chain operators worldwide. Trade flows concentrate around refrigerated transport equipment hubs and food retail distribution clusters.
United States
Cold storage warehouse expansion in Chicago and Dallas-Fort Worth drives thick-gauge aluminum-composite demand for fluctuating thermal loads. The EPA's Significant New Alternatives Policy refrigerant containment rules compress replacement cycles across third-party refrigerated transport fleets. California's Central Valley agricultural processing corridor anchors liner procurement volumes for produce cold chain infrastructure.
Germany
Food retail consolidation across Rewe and Edeka distribution networks standardizes medium-gauge polypropylene specifications. The EU F-Gas Regulation mandates vapor transmission rate documentation that disqualifies legacy polyethylene formulations. The Ruhr industrial corridor hosts pre-qualification testing facilities where suppliers validate barrier performance under thermal stress protocols.
China
GB standards for cold chain logistics equipment mandate cyclic freeze-thaw durability testing, opening qualification pathways for certified producers. The Yangtze River Delta cold storage cluster in Shanghai-Jiangsu-Zhejiang adopts smart substrates with embedded moisture sensors. NMPA alignment with international food-contact material standards accelerates substrate reformulation investments.
India
FSSAI sanitary surface requirements for food-contact applications redirect formulation away from phthalate plasticizers toward polyethylene alternatives. The Maharashtra-Gujarat pharmaceutical cold chain corridor drives demand for extra-thick vapor-barrier specifications. BIS certification protocols for cold chain equipment create qualification bottlenecks for imported liner materials.
Japan
METI energy efficiency standards for commercial refrigeration elevate thermal reflectivity requirements in industrial freezer applications. The Kanto region's concentrated foodservice distribution networks standardize glossy finish specifications for condition-based maintenance protocols. JIS material compatibility standards synchronize with refrigerant transition timelines to prevent stranded inventory positions.
Freezer Liner Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and fabrication layers. The vendor base stratifies between multinational converters with captive resin supply and regional fabricators serving custom die-cut niches. Three archetypes dominate: backward-integrated paperboard specialists, retail-channel-anchored consumables suppliers, and precision-fabrication job shops. Competitive moves center on qualification bundling for regulatory compliance and rapid-turnaround service contracts for asset-light leasing channels.
Among North American consumables suppliers, Reynolds Consumer Products and Mansfield Paper exemplify divergent strategic positions. Reynolds occupies the retail-channel-anchored archetype through recurring revenue streams from replacement cycles. Mansfield represents backward-integrated substrate control, insulating margin pools from resin volatility through in-house coated paperboard production. Komar Alliance sits within the precision-fabrication tier, specializing in custom formats that resist commodity pricing pressure.
| Leading Market Players |
|---|
| Mansfield Paper |
| Hangzhou Hongchang Paper Products |
| Reynolds Consumer Products |
| Zhuji Fred Packaging |
| Shandong Zhongrong Paper Products |
| Komar Alliance |
| Guangzhou Jieshen Paper |
| Zhejiang Heyi Tianze Industry and Trade |
| Intercon Paper |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster in Shanghai-Jiangsu-Zhejiang anchors global polyethylene liner capacity, and its feedstock cost dynamics transmit directly into pricing power for cold chain operators sourcing vapor-barrier substrates. Downstream buyers face compressed negotiation leverage when resin volatility coincides with refrigerant transition mandates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across thick-gauge aluminum-composite specifications. Price differentiation rests on certification grade under EPA Significant New Alternatives Policy and volume scale commitments from German food retail consolidators. Cost compression in medium-gauge polyethylene tiers is intensifying because non-integrated converters lack captive coated paperboard supply. Residential freezer segments exhibit highest price sensitivity, while cold storage warehouse operators demonstrate lowest elasticity due to thermal performance mandates.
Supply Chain Analysis
Contract manufacturing concentration sits with Shandong Zhongrong Paper Products, Hangzhou Hongchang Paper Products, and Guangzhou Jieshen Paper holding laminated substrate capacity. Geographic supply concentration centers on China, Germany, and the United States. Raw material dependencies draw from polyethylene resin, coated paperboard feedstock, and aluminum foil laminates. Single-source vulnerability in phthalate-free plasticizer alternatives for polypropylene formulations poses structural risk. Distribution runs through refrigerated transport equipment hubs and food retail distribution clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified substrate fabrication capabilities are scarce relative to refrigerant transition timelines, creating acquisition premiums for converters with pre-certified barrier performance documentation. This gap widens as ECHA REACH compliance burdens extend R&D qualification cycles.
For Market Incumbents: Build regulatory certification moats by accelerating EPA Significant New Alternatives Policy pre-qualification ahead of refrigerant phasedown deadlines. Deepen backward integration into coated paperboard feedstock to insulate margin pools from polyethylene resin volatility. Consolidate die-cut fabrication capabilities in walk-in freezer niches to resist commodity pricing erosion from Chinese converters. For New Entrants and Emerging Players: Pursue asset-light leasing channel partnerships with third-party refrigerated transport fleet operators seeking unbundled liner replacement services. Target precision die-cut formats for irregular walk-in freezer geometries in North American foodservice distribution networks. Lead with rapid turnaround service contracts and flexible contract terms that incumbent paperboard specialists cannot match. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with embedded sensor compatibility and smart substrate capabilities for real-time moisture intrusion detection. Long-term viability hinges on qualification bundling for multi-jurisdictional regulatory compliance spanning FDA, ECHA REACH, and China's GB standards. The signal to watch is refrigerant-liner qualification synchronization rates as chemical suppliers and substrate converters align R&D roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coated Paperboard | Mansfield Paper's captive feedstock supply insulates margins from resin volatility. |
| Smart Substrate Technology Development | Embedded sensor compatibility enables real-time moisture detection for US cold storage operators. |
| REACH Compliance Reformulation | Polypropylene pivots displace restricted PVC liners under ECHA phthalate regulations. |
| Asset-Light Leasing Channel Partnerships | Komar Alliance's rapid-turnaround service terms capture recurring revenue from fleet operators. |
| GB Standard Qualification Pathway | Certified cyclic freeze-thaw documentation opens China's Yangtze River Delta cold storage cluster. |
Methodological Framework
Operator-level perspectives from cold chain logistics fleet managers, food retail procurement directors, liner substrate converters, refrigerated transport OEMs, and regulatory compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation from EPA refrigerant phasedown documentation, ECHA REACH restriction updates, China's GB standard filings, FDA Food Safety Modernization Act guidance, and customs trade data for polyethylene and aluminum-composite substrate flows. Bottom-up demand modeling across material chemistry, installation geometry, and thermal load specifications triangulated with top-down market sizing from converter capacity disclosures.
Scenario-bracketing framed analytical outputs across the projection horizon. Segmentation dimensions modeled include material chemistry tier, application geometry, thickness specification, and finish type, cross-referenced with regional regulatory cluster intensity. CAGRs were derived from replacement cycle compression analysis under refrigerant transition mandates and cold chain logistics expansion trajectories. Industry-specific forecast inputs incorporated vapor transmission rate qualification timelines and cyclic freeze-thaw durability testing protocols.
Sensitivities concentrate around refrigerant-liner qualification synchronization failures, resin price volatility spikes, and REACH compliance timeline extensions. Forecasts reflect assumptions regarding regulatory enforcement consistency and cold chain infrastructure investment continuity. Quarterly review of EPA refrigerant phasedown milestones, ECHA restriction amendment schedules, and Chinese GB standard implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market