

Cooling Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Boxes Market Insights
The divergence between premium and commodity tiers is hardening as material science and thermal performance benchmarks split the Cooling Boxes landscape into irreconcilable value propositions. YETI Holdings anchors the premium segment through rotational molding expertise and brand equity in high-performance outdoor applications. Igloo Products competes across mass-market channels with cost-optimized plastic constructions and broad retail distribution.
Cooling boxes are insulated enclosures engineered to maintain sub-ambient temperatures through passive ice retention or active thermoelectric refrigeration, typically achieving thermal hold times of 24–120 hours depending on wall thickness, gasket sealing, and insulation density. Their primary purpose spans food safety preservation, vaccine distribution integrity, and temperature-sensitive specimen transport. Hard-sided plastic constructions dominate volume shipments while electric variants capture expanding margin pools in pharmaceutical and food delivery applications. Foam insulation materials sustain the largest installed base, though composite formulations are penetrating premium tiers where weight reduction and extended hold times command price premiums.
FDA cold-chain guidelines for biologics transport, EPA refrigerant phase-down schedules under the AIM Act, and California's SB 1013 restrictions on high-GWP substances collectively reshape product design requirements and compliance costs for manufacturers serving North American markets. The EU's F-Gas Regulation and REACH chemical disclosure mandates impose parallel constraints on European market access. Stakeholders must monitor refrigerant technology transitions and regional compliance divergence when configuring manufacturing footprints and SKU strategies.
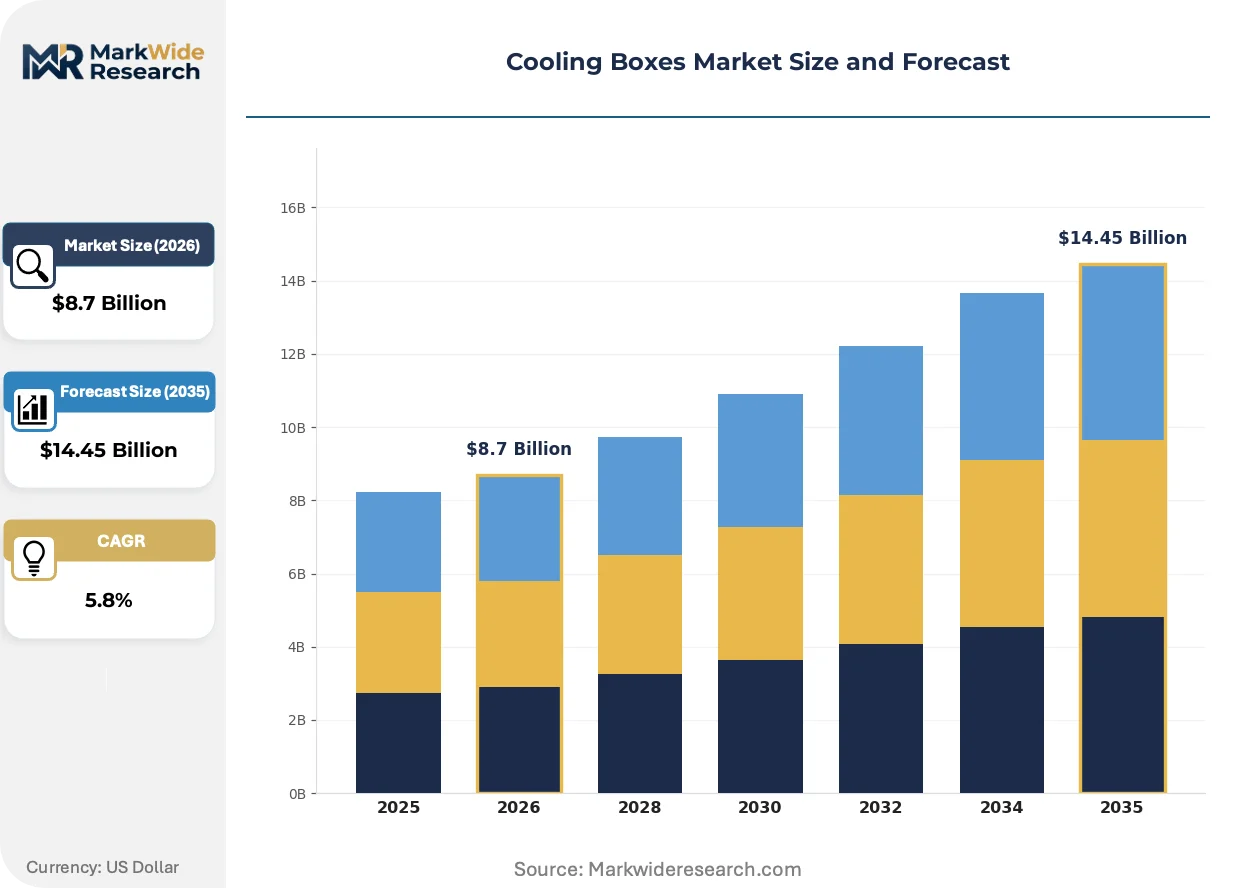
Market Dynamics
Electric cooling box architectures are bifurcating as thermoelectric systems face displacement by compressor-based mini-refrigeration units capable of sub-freezing performance. This technology transition is compressing margins for incumbent passive-insulation manufacturers while rewarding suppliers with refrigerant-handling certifications and battery-integrated power management capabilities.
Growth Catalysts
- Last-mile pharmaceutical delivery:Vaccine distribution networks in the United States are mandating temperature-logging capabilities that electric cooling boxes satisfy. Fleet operators are retrofitting vehicles with compressor-based units to meet FDA cold-chain guidelines for biologics transport.
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbon refrigerants are accelerating R&D into hydrocarbon and CO2-based cooling systems. European manufacturers are redesigning product lines to preempt 2027 quota restrictions.
- Vacuum-insulated panel adoption:Aerospace-derived VIP technology is penetrating premium outdoor recreation segments. Rotational-molded polyethylene shells bonded to nanoporous silica cores are extending thermal hold times beyond 120 hours.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack costs constitute 35-45% of electric cooling box bill-of-materials. Cobalt and nickel price swings from Democratic Republic of Congo and Indonesian supply concentration compress assembler margins unpredictably.
- Refrigerant handling certification scarcity:EPA Section 608 technician certification requirements limit service network density for compressor-based units in rural United States markets. Field repair capacity bottlenecks degrade warranty cost structures.
- Passive insulation substitution:Expanded polystyrene coolers from commodity manufacturers satisfy price-sensitive food retail and beverage distribution applications. Premium electric variants cannot penetrate these volume segments.
Strategic Opportunities
- Indian cold-chain infrastructure gaps:India's pharmaceutical exports to Africa and Southeast Asia lack reliable last-mile cooling. Domestic manufacturers can capture share by developing solar-battery hybrid units suited to grid-unreliable corridors.
- California SB 1013 compliance:Restrictions on high-GWP substances above 1500 create first-mover advantage for hydrocarbon refrigerant systems. Suppliers certifying to this standard gain preferential procurement from state-funded health logistics programs.
- Telematics integration:IoT-enabled temperature logging and geofencing are converging with cooling box hardware. Pharmaceutical 3PLs are specifying API-connected units that feed directly into their warehouse management systems.
Industry Challenges
- Thermal engineer recruitment:Competency in phase-change material modeling and CFD simulation for insulation optimization is scarce. Manufacturers compete with HVAC and automotive sectors for simulation talent.
- Multi-certification timelines:Simultaneous UL safety, FCC electromagnetic, and EPA SNAP refrigerant approvals extend product launch cycles. Sequential rather than parallel review processes delay revenue recognition.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Boxes Market Trends and Innovations
Active refrigeration miniaturization is compressing the performance gap between portable cooling boxes and fixed cold storage. Material science advances in aerogel and phase-change media are simultaneously extending passive hold times, creating overlapping competitive territories.
Phase-change materials with engineered melting points are integrating into hybrid cooling architectures that bridge passive and active thermal management. Pharmaceutical logistics providers in Germany and the Netherlands are deploying PCM-lined electric boxes that maintain 2-8°C for 72 hours without battery drain. This dual-mode capability is integrating cold-chain resilience into last-mile routes where charging infrastructure remains unreliable.
REACH chemical disclosure mandates and the EU F-Gas Regulation are forcing refrigerant transitions that favor natural working fluids. Hydrocarbon propellants and transcritical CO2 systems are displacing HFC-134a and R404A in European-manufactured units. Compressor suppliers in Italy and Denmark are retooling production lines to handle flammable refrigerants, with certification delays compressing available supply through 2027.
Direct-to-consumer subscription models for outdoor recreation equipment are fragmenting traditional retail channel concentration. YETI's DTC platform and specialized rental marketplaces are capturing weekend users who prioritize access over ownership. This behavioral shift is most visible in Colorado and Utah, where gear libraries and subscription services now account for measurable share of premium cooler transactions.
Cooling Boxes Market Segmentation
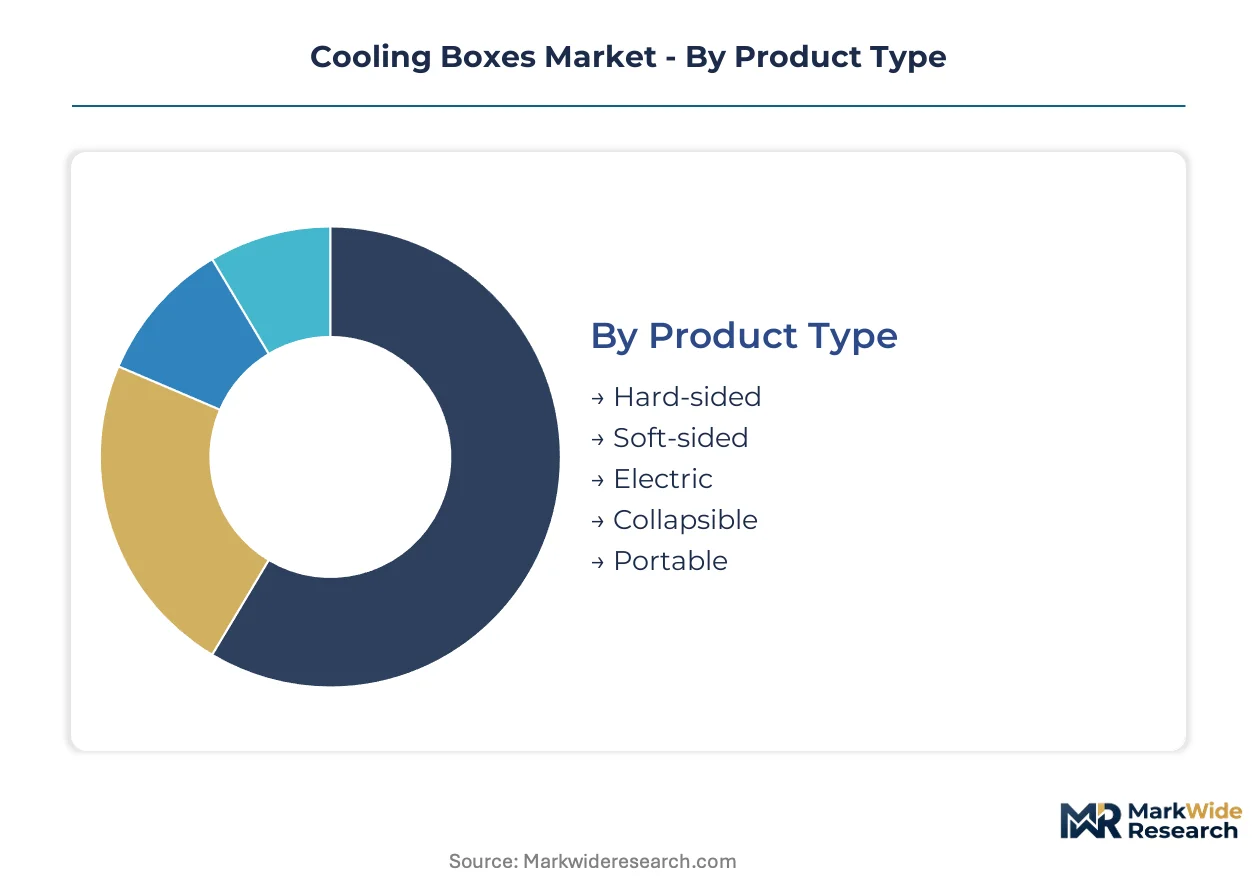
Segmentation in cooling boxes reveals how thermal performance requirements diverge across use cases. Material selection and product architecture decisions cascade into entirely different margin structures and certification burdens.
Product Type:
Customization intensity varies dramatically from commodity rotationally-molded shells to specification-heavy electric refrigeration systems.
- Hard-sided:Rotationally-molded polyethylene construction with polyurethane foam cores dominates volume shipments. Demand concentrates in United States outdoor recreation channels where weekend users prioritize ice retention over portability.
- Electric:Thermoelectric and compressor-based active refrigeration achieves sub-ambient temperatures independent of ice replenishment. Pharmaceutical transport applications in Germany and the Netherlands mandate temperature-logging capabilities that only electric variants satisfy.
- Soft-sided:Fabric exteriors with flexible insulation suit day-trip food and beverage transport. Lightweight construction appeals to hikers and cyclists prioritizing packability over thermal hold times.
- Collapsible:Silicone or fabric walls fold flat for storage efficiency. Urban delivery services in dense Japanese and South Korean metros value trunk space optimization over extended cooling duration.
- Portable:Wheeled or handled designs emphasize mobility for sports teams and mobile catering. Wider mouth openings accommodate beverage crates and prepared food trays.
Leading the category by volume: Hard-sided. Expanding most quickly: Electric.
Material:
Cost tier stratification separates aerospace-derived composites from commodity expanded polystyrene constructions.
- Plastic:Polyethylene and polypropylene dominate mass-market manufacturing through injection and rotational molding. FDA food-contact compliance and dishwasher-safe durability sustain restaurant and catering procurement.
- Composite:Fiberglass or carbon fiber skins bonded to aerogel or vacuum-insulated panel cores achieve extreme thermal performance. Premium outdoor recreation segments in Colorado and Utah absorb price premiums for sub-5-pound constructions with 120-hour hold times.
- Aluminum:Sheet metal fabrication suits institutional food service where durability under commercial kitchen abuse outweighs thermal efficiency trade-offs.
- Stainless Steel:Marine-grade alloys resist corrosion in saltwater fishing and offshore applications. Australian and New Zealand charter operators specify 316L construction for deck-mounted fish storage.
- Foam Insulation:Expanded polystyrene and polyurethane foams constitute the thermal barrier in most passive designs. California SB 1013 refrigerant restrictions indirectly favor foam-dependent passive architectures over electric alternatives using high-GWP working fluids.
Capturing the largest installed base: Foam Insulation. Gaining share fastest: Composite.
Application:
End-use maturity determines whether specifications stabilize or continue evolving under regulatory pressure.
- Pharmaceutical Transport:Cold-chain integrity requirements from FDA and EMA mandate validated thermal packaging with documented hold times. United States vaccine distribution networks are retrofitting last-mile fleets with compressor-based electric units capable of 2-8°C maintenance.
- Food Delivery:Gig economy platforms specify insulated bags and hard-sided boxes for prepared meal and grocery transport. Temperature logging is becoming standard for liability protection in litigious North American markets.
- Outdoor Recreation:Weekend camping and tailgating sustain the largest consumer volume. Brand equity and rotational molding quality separate premium tiers from mass-market commodity alternatives.
- Commercial Catering:Event and institutional food service demands stackable, wheeled designs for buffet line deployment. NSF food equipment certification gates access to United States school and hospital contracts.
- Scientific Research:Specimen and reagent transport in field biology and environmental monitoring requires calibrated temperature stability. Academic procurement prioritizes durability over weight optimization.
Generating highest average selling prices: Pharmaceutical Transport. Volume leader: Outdoor Recreation.
End User:
Customer type shapes whether procurement emphasizes total cost of ownership or upfront acquisition price.
- Delivery Services:Fleet operators amortize electric cooling box investments across high daily utilization. Battery-integrated designs with solar charging capability suit Indian and Southeast Asian markets with unreliable grid infrastructure.
- Laboratories:GLP and GMP compliance requirements drive specification toward validated, auditable thermal packaging. European REACH chemical disclosure mandates constrain material selection for direct specimen contact surfaces.
- Campers:Recreational users balance ice retention, weight, and price in discretionary purchase decisions. Subscription and rental marketplace penetration is highest in Colorado and Utah mountain towns.
- Restaurants:Food safety liability exposure drives preference for NSF-listed constructions with seamless interior surfaces. Catering divisions specify stackable, wheeled designs for off-premise event execution.
- Sports Teams:Hydration and nutrition staff prioritize rapid access and high capacity over thermal precision. Sideline deployments favor soft-sided or wheeled portable architectures.
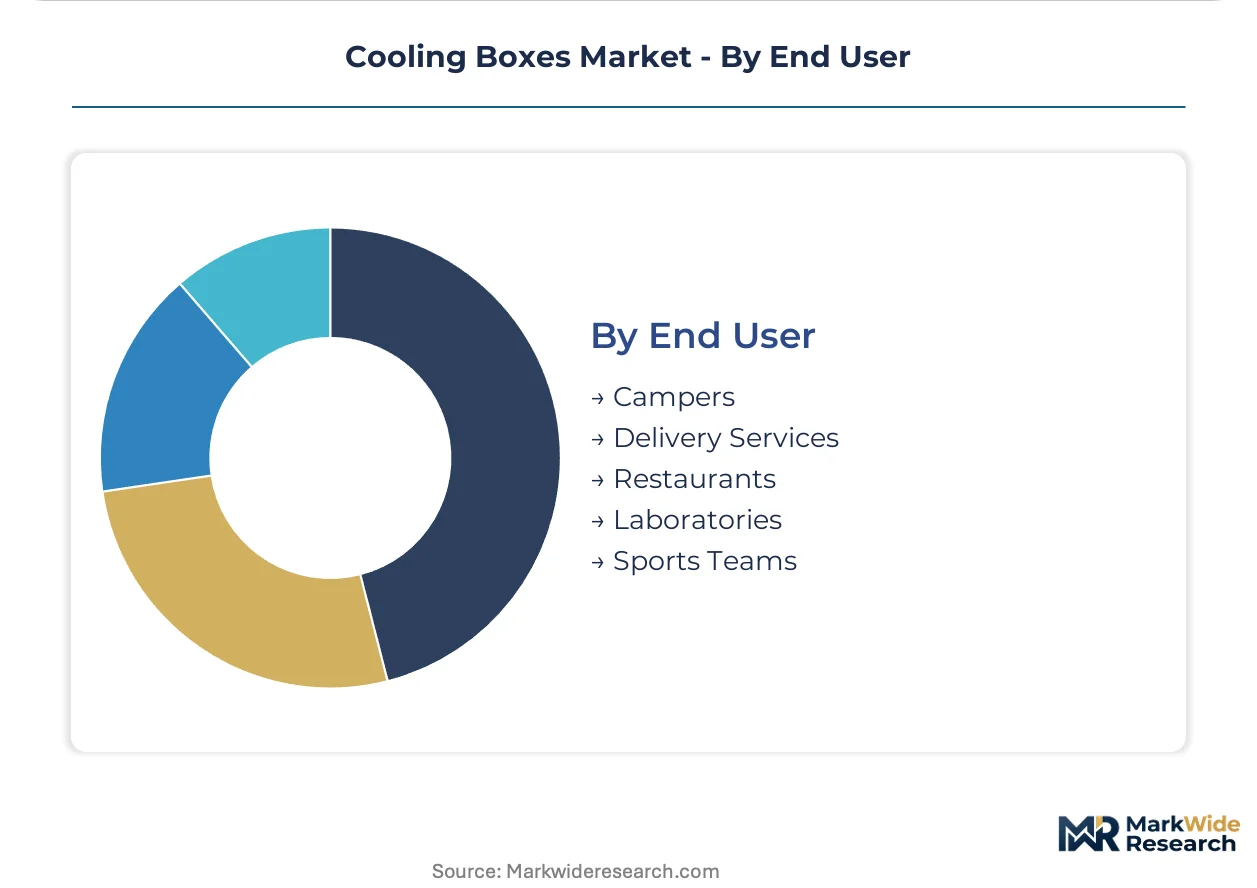
Driving specification evolution: Delivery Services. Procurement volume leader: Campers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver and Boulder anchor North American outdoor recreation demand for high-performance cooling boxes, while pharmaceutical distribution corridors in New Jersey and California drive electric refrigeration specifications. National regulatory frameworks and sub-regional industrial specializations create divergent procurement patterns across major economies.
United States
Last-mile vaccine distribution networks in New Jersey and California mandate compressor-based electric units with FDA-validated temperature logging. The EPA's AIM Act refrigerant phase-down schedule forces manufacturers toward hydrocarbon alternatives by 2027. Austin and Salt Lake City clusters concentrate rotational molding expertise for premium outdoor recreation brands.
Germany
Pharmaceutical logistics providers in Frankfurt and Munich specify PCM-lined hybrid boxes for 72-hour 2-8°C stability. The EU F-Gas Regulation accelerates R&D into CO2 transcritical systems ahead of 2027 quota restrictions. Stuttgart's automotive supplier base feeds compressor miniaturization capabilities into portable refrigeration.
China
Domestic cold-chain infrastructure investment targets pharmaceutical exports to Africa and Southeast Asia. The national dual carbon goals pressure manufacturers toward natural refrigerant adoption. Shenzhen and Dongguan electronics clusters dominate battery-integrated power management module production.
India
Pharmaceutical exporters from Hyderabad and Mumbai lack reliable last-mile cooling for African and Southeast Asian corridors. The PLI scheme incentivizes domestic solar-battery hybrid unit development. Ahmedabad manufacturers target grid-unreliable rural distribution with low-cost thermoelectric architectures.
Netherlands
Rotterdam pharmaceutical 3PLs specify API-connected cooling boxes feeding warehouse management systems. REACH chemical disclosure mandates constrain direct specimen contact surface materials. Eindhoven's high-tech systems cluster advances IoT telematics integration for fleet temperature monitoring.
Cooling Boxes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated market structure. The landscape splits between rotational molding specialists with captive manufacturing assets and brand marketers outsourcing fabrication to contract manufacturers. Three archetypes dominate: premium performance brands commanding outdoor recreation loyalty, mass-market volume players optimizing retail distribution economics, and pharmaceutical-certified specialists capturing regulated cold-chain specifications. Consolidation pressure intensifies through M&A targeting refrigerant-handling certifications and geographic expansion into Indian and Southeast Asian pharmaceutical corridors.
Among premium-tier outdoor recreation specialists, YETI Holdings and RTIC Outdoors occupy positions defined by rotational molding expertise and brand equity in high-performance applications. Igloo Products exemplifies the mass-market archetype with cost-optimized constructions and broad retail presence. On the pharmaceutical-certified vector, Sonoco ThermoSafe and Cold Chain Technologies represent validated thermal packaging specialists serving FDA and EMA-regulated distribution networks.
| Leading Market Players |
|---|
| YETI Holdings |
| Igloo Products |
| Sonoco ThermoSafe |
| Pelican Products |
| Newell Brands |
| RTIC Outdoors |
| B Medical Systems |
| va-Q-tec |
| Cold Chain Technologies |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up rotational molding specialists in the United States and family-owned mid-cap composite manufacturers in Germany anchor supply concentration that feeds directly into pricing discipline across premium and commodity tiers. Their captive production assets limit spot-market volatility for polyurethane foam cores and polyethylene resins, while California's SB 1013 refrigerant restrictions compress margins for electric variants using high-GWP working fluids.
Pricing Analysis
Value-based pricing anchored to thermal hold-time outcomes separates YETI Holdings' rotational-molded premium tier from Igloo Products' mass-market commodity positioning. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and wall thickness specifications, with FDA-validated pharmaceutical transport units commanding the highest premiums. Pricing pressure stems from lithium-ion cell cost volatility in electric variants, where battery packs constitute the dominant bill-of-materials component. Delivery services and fleet operators exhibit the least price sensitivity due to amortization across high daily utilization, while recreational campers in price-sensitive Southeast Asian markets gravitate toward expanded polystyrene alternatives.
Supply Chain Analysis
Ocean freight cost exposure from Shenzhen and Dongguan battery management module clusters to Rotterdam and New Jersey pharmaceutical distribution centers shapes landed cost structures for electric cooling box assemblers. Manufacturing concentration in China for lithium-ion cells, the United States for rotational-molded polyethylene shells, and Germany for compressor miniaturization creates multi-regional dependency. Supply chain risk centers on cobalt and nickel price swings from Democratic Republic of Congo and Indonesian mining concentration. Distribution runs through pharmaceutical 3PLs in the Netherlands, outdoor recreation retailers in Colorado and Utah, and direct-to-consumer subscription platforms fragmenting traditional channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressor-based electric cooling box manufacturing operates under supply-constrained conditions as EPA Section 608 technician certification scarcity limits service network density and props pricing for certified suppliers.
For Market Incumbents: Anchor defensive positioning through backward integration into refrigerant-handling certification networks and captive rotational molding capacity in Austin and Salt Lake City clusters. Consolidate around hydrocarbon refrigerant transitions ahead of EPA AIM Act phase-down deadlines to preempt emerging entrant disruption. Prioritize GLP and GMP certification investments for pharmaceutical transport specifications that gate hospital and laboratory procurement. For New Entrants and Emerging Players: Begin with solar-battery hybrid architectures targeting Indian pharmaceutical export corridors to Africa and Southeast Asia, where grid-unreliable last-mile infrastructure remains underpenetrated. Exploit white-space in telematics-integrated units with API-connected temperature logging for European pharmaceutical 3PLs in Rotterdam and Frankfurt. Pursue direct-to-consumer rental marketplace partnerships in Colorado and Utah mountain towns as the lowest-friction go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor refrigerant-handling certified specialists in Germany and Italy facing 2027 F-Gas Regulation quota compression, where retooling delays create temporary supply gaps. Long-term viability hinges on natural refrigerant transition completion and Indian cold-chain infrastructure buildout participation. Monitor EPA Section 608 certification expansion rates as the inflection signal for compressor-based unit service network maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Certification Investment | EPA Section 608 compliance gates access to United States pharmaceutical fleet retrofits and warranty service networks. |
| PCM-Lined Hybrid Development | German pharmaceutical logistics providers in Frankfurt specify 72-hour 2-8°C stability for last-mile resilience. |
| Telematics Platform Integration | Rotterdam 3PLs mandate API-connected units feeding directly into warehouse management systems. |
| Solar-Battery Hybrid Localization | India's PLI scheme incentivizes domestic production for grid-unreliable African and Southeast Asian corridors. |
| Direct-to-Consumer Rental Expansion | Subscription marketplace penetration in Colorado and Utah captures weekend users prioritizing access over ownership. |
Research Methodology
Document review covered SEC 10-K filings, EU F-Gas Regulation impact assessments, and pharmaceutical cold-chain validation protocols, complemented by interviews with rotational molding plant managers, pharmaceutical logistics procurement leads, EPA refrigerant compliance officers, outdoor recreation category buyers, and battery pack procurement directors. Secondary validation drew from FDA guidance documents, EMA submissions, customs trade data for cooling box imports, and IEA energy storage deployment statistics. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-level outputs across product type, material composition, application, and end-user categories were generated through structured modeling. The analytical framework incorporated thermal performance tier, certification grade, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from fitted growth curves applied to base-year estimates, with cross-validation against pharmaceutical transport volume trends and outdoor recreation equipment spending patterns.
Underlying measurement precision varies by segment; electric cooling boxes with pharmaceutical certification carry tighter precision than commodity expanded polystyrene alternatives due to documented procurement volumes. Forecasts reflect assumptions regarding refrigerant transition timelines, lithium-ion cost trajectories, and Indian cold-chain infrastructure investment rates that could revise materially. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.