
 Cold Chain Equipment Market | 2026-2036
Cold Chain Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Equipment Market Intelligence
The capital-intensity divergence between full-system integrators and component specialists is bifurcating competitive dynamics in cold chain equipment. BITZER SE leverages its compressor technology leadership to anchor premium refrigeration system contracts across European food retail networks. Carrier Transicold sustains dominant positions in transport refrigeration through extensive dealer and service infrastructure across North American trucking corridors. ebm-papst competes on fan and motor efficiency, supplying energy-optimized air movement components to multiple cold storage OEMs rather than competing at the system level.
Cold chain equipment encompasses engineered thermal management systems designed to maintain precise temperature bands between controlled atmosphere conditions and cryogenic states, typically spanning minus 196 degrees Celsius to 15 degrees Celsius, using vapor-compression, absorption, or cryogenic fluid injection methods. These systems preserve product integrity, extend shelf life, and ensure compliance with safety-critical handling protocols for perishable goods and temperature-sensitive biological materials. Refrigerated trucks occupy the largest installed base among transport modalities, though cold storage warehouses command the highest capital expenditure per project and generate recurring service revenue streams. Monitoring systems represent the fastest-expanding technology segment as pharmaceutical shippers mandate real-time temperature traceability to satisfy GDP guidelines and reduce spoilage liability.
The EPA SNAP program and EU F-Gas Regulation are both restricting high-GWP refrigerants, compelling equipment manufacturers to redesign compressor architectures and accelerate CO2 and ammonia system certifications. FDA guidance on temperature-controlled pharmaceutical distribution, alongside WHO prequalification requirements for vaccine cold chain equipment, directly shapes product specifications and market access eligibility for suppliers targeting health sector procurement. Stakeholders must weigh refrigerant transition timelines against retrofit economics while monitoring evolving pharmacopeial standards for ultra-low temperature storage.
Market Dynamics
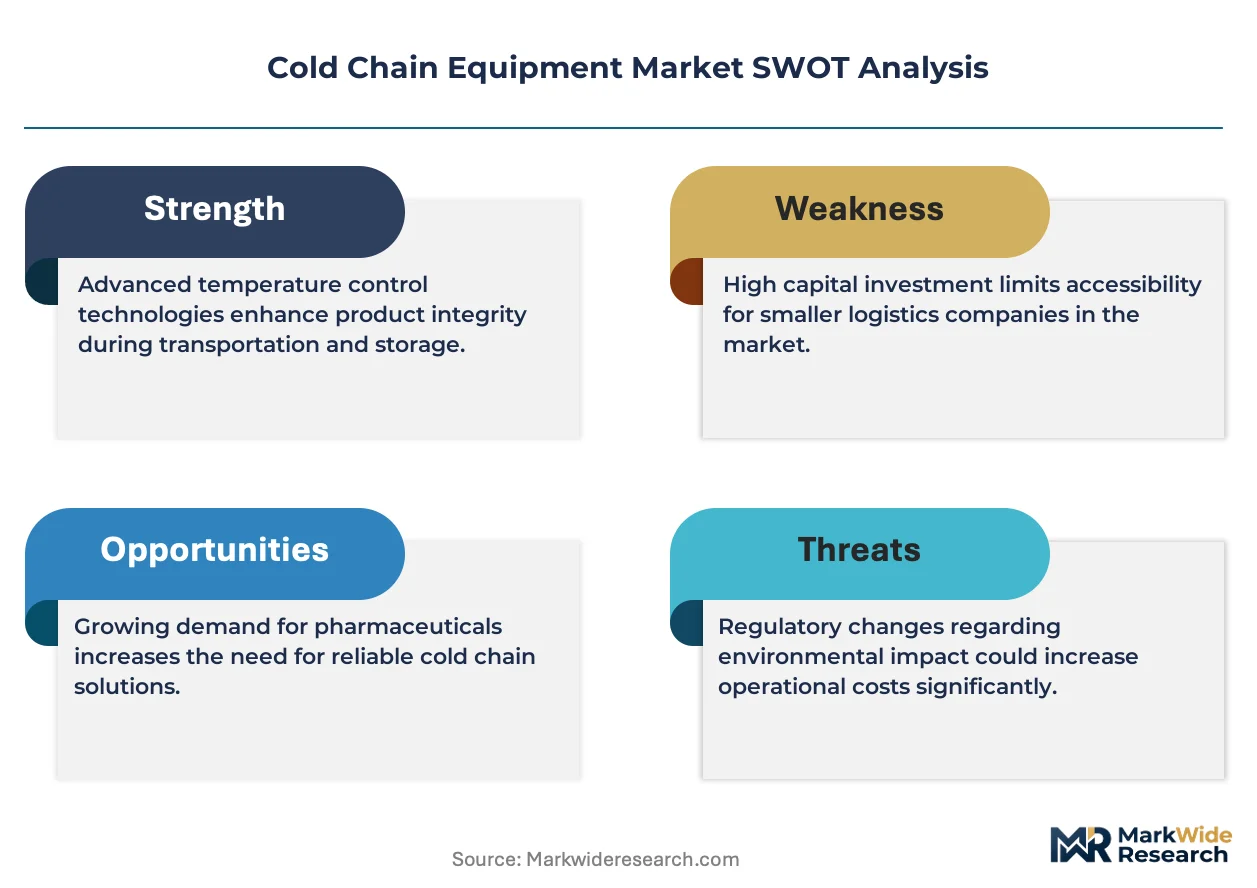
Refrigerant chemistry restrictions under the EPA SNAP program and EU F-Gas Regulation are forcing simultaneous redesign of compressor architectures and validation protocols across equipment portfolios. This regulatory compression is accelerating capital deployment into CO2 transcritical systems and ammonia-based industrial installations while lengthening product development cycles.
Growth Catalysts
- Biologics distribution expansion:Pharmaceutical cold chains now require minus 80 degrees Celsius capabilities for mRNA therapeutics, driving warehouse automation and ultra-low temperature mobile unit procurement across North American and European logistics networks.
- EU F-Gas Regulation phase-down:The mandated reduction in high-GWP refrigerant quotas is compelling European cold storage operators to accelerate natural refrigerant retrofits and new-build specifications.
- India's PLI scheme for food processing:Government-backed investment corridors in Maharashtra and Gujarat are generating concentrated demand for integrated cold storage and reefer truck fleet expansion.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and piping input costs fluctuate with commodity markets, compressing margin visibility for equipment manufacturers on fixed-price contracts.
- Compressor supply concentration:Precision scroll and screw compressor production clusters in Germany and Japan create geographic chokepoints for system integrators.
- CO2 system technical limitations:Transcritical CO2 efficiency degrades in ambient temperatures above 32 degrees Celsius, restricting deployment in subtropical climates without auxiliary cooling.
Strategic Opportunities
- Indonesia cold chain underpenetration:Perishable food loss rates exceeding 30 percent indicate substantial unmet demand for village-level solar-powered cold rooms and inter-island refrigerated vessel capacity.
- IoT-enabled predictive maintenance:Sensor convergence with cloud analytics is opening recurring revenue streams through condition-based service contracts replacing traditional break-fix arrangements.
- US Inflation Reduction Act clean energy incentives:Tax credits for energy-efficient commercial refrigeration are improving project economics for domestic cold storage new builds and deep retrofits.
Industry Challenges
- Natural refrigerant technician scarcity:CO2 and ammonia system installation and maintenance require specialized certification pipelines that training institutions have not yet scaled to match equipment deployment rates.
- WHO prequalification timeline compression:Vaccine cold chain equipment suppliers face extended validation protocols for performance qualification under shifting pharmacopeial standards.
- Legacy HFC asset stranded value:Existing installed bases using phased refrigerants create retrofit-versus-replace decision friction for fleet and warehouse operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Chain Equipment Market |
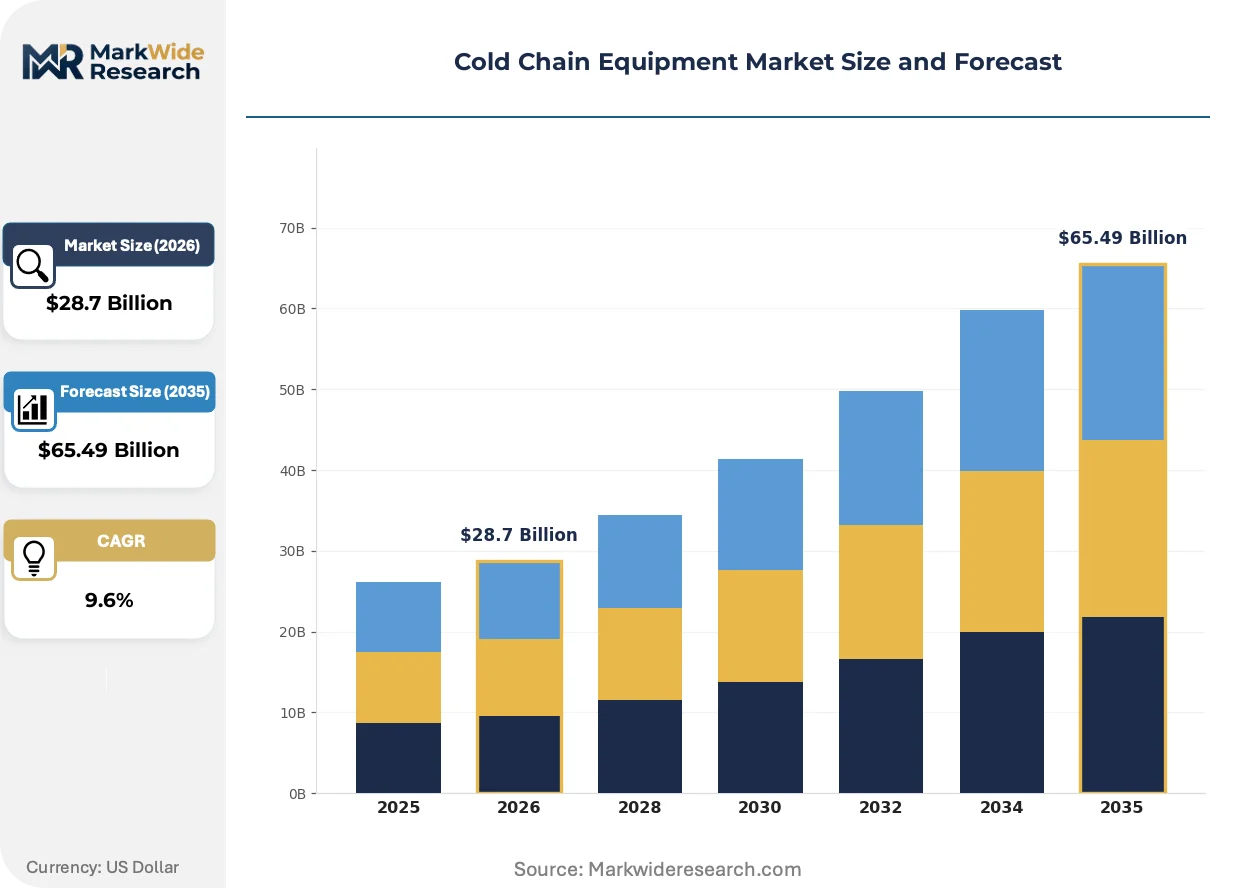
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $65.49 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Trucks, Cold Storage Warehouses, Temperature-Controlled Containers, Cryogenic Equipment End User: Food & Beverage, Pharmaceuticals, Biotechnology, Chemicals Temperature Range: Controlled Atmosphere, Chill Temperature, Freezer Temperature, Cryogenic Technology: Active Systems, Passive Systems, Monitoring Systems, Refrigeration Technology |
| Companies Covered | BITZER SE, ebm-papst, Thermo King, Schmitz Cargobull, Viessmann, Carrier Transicold, CAREL, Intertecnica, Zanotti SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Equipment Market Strategic Shifts & Innovations
Equipment intelligence layers are migrating from aftermarket add-ons to factory-integrated architectures, reshaping how thermal performance is validated, monetized, and regulated across pharmaceutical and food supply chains.
CO2 transcritical booster systems are supplanting conventional HFC architectures in European supermarket and warehouse applications. Retailers in Germany and the Netherlands are specifying these configurations as standard for new builds above 1,000 square meters. The technology is compressing energy consumption benchmarks while eliminating synthetic refrigerant dependency entirely.
The EU F-Gas Regulation's stepped quota reductions are mandating refrigerant transition timelines that compress equipment replacement cycles. Industrial cold storage operators face 2027-2030 deadlines for high-GWP system phase-out. Pharmaceutical logistics providers are responding by front-loading capital expenditure into ammonia and CO2 installations ahead of regulatory enforcement windows.
Outcome-based service contracting is displacing traditional equipment sale-and-install models in North American pharmaceutical cold chain procurement. Third-party logistics providers now specify uptime guarantees and temperature excursion liability transfer rather than capital asset ownership. This shift concentrates most visibly in vaccine distribution networks where GDP compliance risk sits with the equipment operator rather than the shipper.
Cold Chain Equipment Market Segmentation
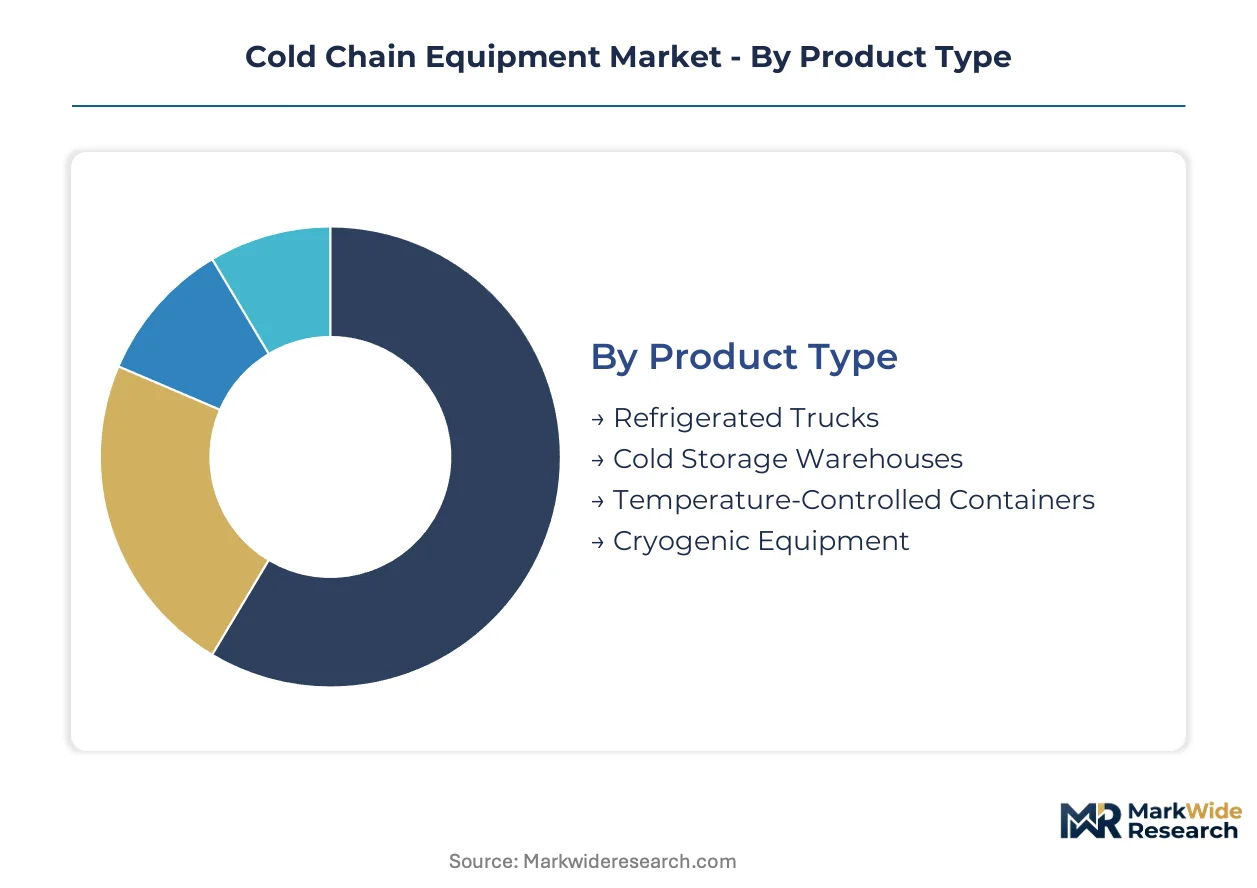
Cold chain equipment segmentation reveals distinct regulatory exposure profiles across product architectures and end-use applications. Equipment specifications diverge sharply between food safety mandates and pharmaceutical GDP compliance, creating non-overlapping procurement channels and certification requirements.
Product Type:
EU F-Gas Regulation quotas and EPA SNAP refrigerant phase-downs are forcing divergent capital allocation across transport and stationary assets, with compliance timelines stretching from 2027 through 2030.
- Refrigerated Trucks:These mobile vapor-compression units dominate installed transport capacity across North American interstate corridors and Indian national highways. Fleet operators in Germany and the US face simultaneous pressure from diesel emission zones and refrigerant chemistry restrictions, compressing replacement cycles for long-haul tractor-trailer configurations.
- Cold Storage Warehouses:Stationary industrial systems command the highest capital expenditure per project and generate recurring service revenue through ammonia and CO2 transcritical architectures. Indian government-backed food processing corridors in Maharashtra and Gujarat are driving concentrated warehouse automation procurement ahead of FSSAI cold chain infrastructure mandates.
- Temperature-Controlled Containers:Intermodal reefers serving pharmaceutical sea lanes between Belgium and Singapore require dual-mode power systems and real-time temperature logging for GDP compliance.
- Cryogenic Equipment:Liquid nitrogen and mechanical cascade systems preserve biological materials at minus 196 degrees Celsius for biobanking and cell therapy distribution networks.
Refrigerated trucks handle the majority of throughput; cryogenic equipment is climbing the fastest on share as mRNA therapeutic distribution expands.
End User:
Customer procurement authority concentrates in distinct regulatory jurisdictions, with FDA, EMA, and CDSCO each imposing non-harmonized validation protocols on equipment specifications.
- Food & Beverage:Processors and retailers specify equipment against FSSAI, FDA, and EU food safety frameworks, with fresh produce and dairy applications driving the largest volume procurement in India and Brazil. Cold storage depreciation schedules in the US benefit from IRA clean energy tax credits, improving project economics for domestic operators.
- Pharmaceuticals:Third-party logistics providers now mandate outcome-based uptime guarantees and temperature excursion liability transfer rather than capital asset ownership, concentrating risk with equipment operators across vaccine distribution networks in the US and EU.
- Biotechnology:Cell and gene therapy manufacturers require minus 80 to minus 150 degrees Celsius capabilities for cryopreserved material stability, driving ultra-low temperature warehouse specifications.
- Chemicals:Specialty chemical distributors utilize controlled atmosphere systems for moisture-sensitive and oxidation-prone compounds, with demand clustering in German and Japanese industrial corridors.
Food and beverage absorbs the greatest equipment volume; biotechnology is expanding most quickly as regenerative medicine manufacturing scales.
Temperature Range:
Pharmacopeial standards and food safety codes create rigid band definitions that equipment manufacturers must certify against, with cryogenic and controlled atmosphere extremes commanding premium engineering margins.
- Controlled Atmosphere:Oxygen, carbon dioxide, and ethylene management systems extend horticultural shelf life for high-value produce shipments from Chile and New Zealand to European retail networks.
- Chill Temperature:Zero to 15 degrees Celsius bands serve fresh dairy, prepared meals, and certain vaccine formulations, representing the most densely penetrated specification across existing installed bases.
- Freezer Temperature:Minus 18 to minus 25 degrees Celsius configurations dominate frozen food logistics and standard pharmaceutical storage, with ammonia-based industrial systems displacing HFC architectures in European warehouse retrofits.
- Cryogenic:Minus 80 to minus 196 degrees Celsius mechanical cascade and liquid nitrogen systems preserve mRNA therapeutics, cell therapies, and biological specimens, with WHO prequalification requirements compressing supplier validation timelines.
Freezer temperature equipment carries the largest installed base; cryogenic systems are gaining share fastest on biologics distribution expansion.
Technology:
System intelligence layers are migrating from aftermarket add-ons to factory-integrated architectures, with monitoring and active control convergence reshaping how thermal performance is validated and monetized.
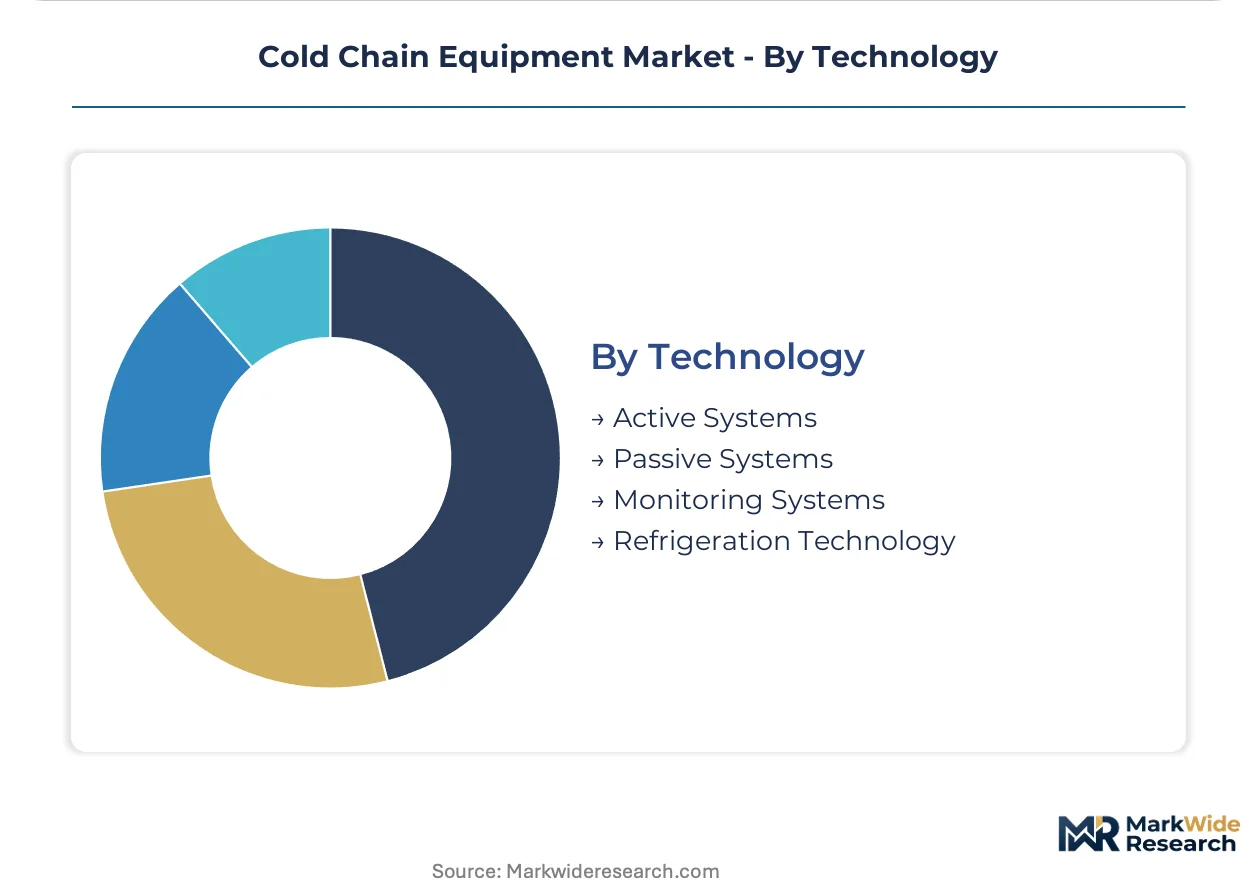
- Active Systems:Powered vapor-compression and absorption units maintain temperature through continuous energy input, with CO2 transcritical boosters supplanting HFC configurations in German and Dutch supermarket new builds above 1,000 square meters.
- Passive Systems:Insulated containers with phase-change materials provide temporary thermal protection for last-mile pharmaceutical delivery, with demand concentrating in Indian vaccine outreach programs and African immunization campaigns.
- Monitoring Systems:IoT-enabled sensors and cloud analytics platforms deliver real-time temperature traceability to satisfy GDP guidelines, opening recurring revenue streams through predictive maintenance contracts replacing traditional break-fix arrangements.
- Refrigeration Technology:Compressor, heat exchanger, and refrigerant management subsystems form the core thermal engineering stack, with natural refrigerant certifications creating technician scarcity bottlenecks in CO2 and ammonia system deployment.
Active systems manage the greatest thermal load; monitoring systems are expanding most quickly on pharmaceutical traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering corridors while cost-sensitive procurement dominates Indian government tenders, creating a bifurcated regional landscape where equipment specifications diverge sharply across regulatory jurisdictions.
United States
Third-party logistics providers are expanding refrigerated fleet capacity to handle mRNA therapeutic distribution at minus 80 degrees Celsius. The EPA SNAP program is accelerating refrigerant phase-down timelines for transport and stationary assets. Cold storage automation clusters in New Jersey and Illinois are retrofitting ammonia systems ahead of 2027 compliance deadlines.
Germany
Food retailers are specifying CO2 transcritical boosters as standard for supermarket new builds above 1,000 square meters. The EU F-Gas Regulation is compressing replacement cycles through stepped quota reductions through 2030. Industrial refrigeration engineering concentrates in Baden-Württemberg, where compressor manufacturers anchor premium system integration contracts.
India
Government-backed food processing investments in Maharashtra and Gujarat are driving warehouse automation and mobile refrigeration procurement. The PLI scheme for food processing is generating concentrated demand for integrated cold storage infrastructure. Vaccine distribution programs are expanding last-mile cold room networks in rural Telangana and Karnataka.
Netherlands
Rotterdam port logistics operators are deploying dual-mode temperature-controlled containers for pharmaceutical sea lanes to Singapore. REACH and EU F-Gas Regulation compliance is mandating natural refrigerant certifications for port-side cold storage. Dutch supermarket chains are piloting CO2 systems with auxiliary cooling for subtropical climate adaptation.
Japan
Precision scroll compressor production clusters are creating geographic chokepoints for regional system integrators. METI energy efficiency standards are accelerating adoption of variable-speed refrigeration architectures. Pharmaceutical cold chain specifications in Osaka and Tokyo are tightening around real-time temperature traceability requirements.
Cold Chain Equipment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with German engineering specialists commanding premium pricing for compressor and heat exchanger subsystems while Asian fabricators compete on standardized transport refrigeration volume. The market structures around three tiers: full-system integrators with service infrastructure, component specialists supplying multiple OEMs, and regional assemblers targeting price-sensitive procurement. Dominant competitive moves include backward integration into compressor manufacturing and geographic expansion through dealer network density.
Among European engineering specialists, BITZER SE and ebm-papst occupy positions at opposite ends of the value chain. BITZER SE anchors the compressor technology tier, supplying precision scroll and screw units that system integrators specify for industrial cold storage. ebm-papst exemplifies the component specialist archetype, providing energy-optimized fan and motor assemblies to multiple equipment manufacturers without competing at the integrated system level. Carrier Transicold represents the full-system integrator model, sustaining market presence through extensive service infrastructure rather than subsystem supply relationships.
| Leading Market Players |
|---|
| BITZER SE |
| ebm-papst |
| Thermo King |
| Schmitz Cargobull |
| Viessmann |
| Carrier Transicold |
| CAREL |
| Intertecnica |
| Zanotti SpA |
| Others |
Cost & Logistics Intelligence
WHO prequalification requirements for vaccine cold chain equipment simultaneously gate supplier market access and stratify price tiers across pharmaceutical procurement channels. Equipment manufacturers must absorb extended validation costs to qualify for health sector tenders, while buyers in food and beverage segments face divergent cost structures driven by refrigerant transition timelines and commodity input volatility.
Pricing Analysis
Configured-to-order pricing for ultra-low temperature systems commands substantial premiums over standard freezer configurations, with cryogenic equipment for mRNA distribution reaching multiples of conventional warehouse specifications. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling, with WHO-prequalified suppliers extracting scarcity rents in vaccine cold chain tenders. Cost compression in transport refrigeration is intensifying because fleet operators face simultaneous diesel emission zone penalties and refrigerant chemistry retrofit obligations. Food processors in India exhibit highest price sensitivity, while biotechnology manufacturers demonstrate lowest sensitivity given GDP compliance liability exposure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for precision compressor and heat exchanger subsystems manufactured in Germany and Japan. Geographic supply concentration centers on Germany for scroll and screw compressor production, Japan for precision refrigeration components, and China for aluminum heat exchanger fabrication. Raw material dependencies span copper tubing, aluminum fin stock, and rare-earth permanent magnets for variable-speed motor architectures. Single-source vulnerability concentrates in German compressor engineering corridors. Distribution runs through OEM system integrators, authorized dealer networks, and direct procurement for large-scale warehouse projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician pipelines for CO2 and ammonia systems constitute the critical capability gap constraining deployment velocity, with training institution throughput lagging equipment installation rates across European and North American markets.
For Market Incumbents: Fortify service infrastructure density in pharmaceutical logistics corridors to capture recurring revenue from outcome-based uptime contracts. Deepen backward integration into compressor manufacturing to reduce exposure to German and Japanese supply chokepoints. Accelerate natural refrigerant certification programs to preempt technician scarcity bottlenecks constraining competitor deployment timelines. For New Entrants and Emerging Players: Anchor in Indonesia's village-level cold room segment, where perishable food loss rates exceeding thirty percent indicate substantial unmet demand for solar-powered distributed refrigeration. Target inter-island refrigerated vessel capacity as the most penetrable logistics gap. Pursue equipment-as-a-service models to bypass capital procurement constraints among smallholder agricultural cooperatives. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward natural refrigerant technology portfolios and certified installation capabilities. Long-term viability favors specialists with ammonia and CO2 system expertise over legacy HFC-dependent asset bases. Monitor WHO prequalification approval velocity as the signal indicating which suppliers will capture vaccine distribution procurement concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant System Certification | EU F-Gas Regulation compliance unlocks European cold storage retrofit contracts ahead of quota deadlines. |
| Predictive Maintenance Platform Launch | IoT-enabled sensor convergence transforms break-fix service relationships into recurring revenue contracts. |
| Technician Training Pipeline Expansion | CO2 and ammonia certification scarcity constrains competitor deployment velocity across German supermarket networks. |
| Backward Integration into Compressor Manufacturing | In-house scroll production reduces dependency on Baden-Württemberg engineering clusters for system integrators. |
| Outcome-Based Service Contracting | Liability transfer models concentrate risk with equipment operators in North American vaccine distribution networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold storage facility managers, fleet procurement directors, pharmaceutical logistics executives, refrigeration system integrators, and aftermarket service technicians. Secondary validation drew from EPA SNAP program filings, EU F-Gas Regulation quota tracking databases, WHO prequalification performance reports, and customs trade data on compressor and heat exchanger imports. Bottom-up equipment installation tracking and top-down capital expenditure surveys were triangulated to establish market sizing boundaries.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product architecture, temperature range specification, end-use regulatory jurisdiction, and refrigerant technology pathway. CAGRs were derived from installed base replacement cycle analysis and new-build capital commitment tracking. Forecast inputs incorporated biologics distribution expansion trajectories and natural refrigerant adoption curves across European supermarket and warehouse specifications.
Decision-makers should treat outputs as directional under assumptions of sustained pharmaceutical cold chain investment and stepped EU F-Gas Regulation enforcement; material deviation in refrigerant transition timelines or biologics approval velocity would warrant model refresh. Specific risks include commodity price volatility in copper and aluminum, compressor supply disruption from geographic concentration, and technician certification pipeline scaling shortfalls. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Fish Boxes Market