
 Latin America Pharmaceutical Cold Chain Logistics Market | 2026-2036
Latin America Pharmaceutical Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pharmaceutical Cold Chain Logistics Market Insights
Good Distribution Practice certification is unwinding legacy warehouse operations across the region. Frialsa Frigorificos SA leverages its multi-country refrigerated footprint to anchor cross-border vaccine flows. Emergent Cold Latin America competes through purpose-built pharma facilities that meet international temperature standards. DHL Supply Chain dominates express cold-chain corridors with integrated air-road monitoring systems.
Latin America pharmaceutical cold chain logistics encompasses temperature-controlled storage, handling, and distribution of medicinal products requiring maintenance between minus 80 degrees Celsius and plus 25 degrees Celsius to preserve efficacy and safety. The discipline employs validated thermal packaging, real-time data loggers, and redundant cooling infrastructure to prevent excursions that degrade active pharmaceutical ingredients. Vaccines command the largest product-type volume pool due to national immunization program scale, while biologics generate premium margins through deep-frozen handling complexity. Road transport anchors last-mile delivery across Brazil's interior states, whereas air freight captures time-sensitive biologics moving between São Paulo and Mexico City.
ANVISA enforces Brazil's pharmaceutical distribution standards through inspection protocols that mandate continuous temperature documentation. Mexico's COFEPRIS aligns with WHO prequalification requirements for vaccine import validation, while Colombia's INVIMA tightens cold-chain licensing for biological product handlers. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance frameworks as customs harmonization lags behind temperature-control mandates.
Market Dynamics
ANVISA's real-time monitoring mandate is compressing legacy warehouse operations into validated, sensor-dense facilities across Brazil's pharmaceutical corridor. This regulatory pressure cascades through Mexico and Colombia as national regulators harmonize with WHO prequalification standards.
Growth Catalysts
- Vaccine production clusters:São Paulo state's concentrated manufacturing base generates dedicated frozen storage demand. Biologics manufacturers require minus 80 degrees Celsius corridors that only specialized providers can construct.
- COFEPRIS import validation:Mexico's alignment with WHO prequalification accelerates cross-border vaccine flows. This framework reduces customs friction for temperature-sensitive biological products entering through Mexico City.
- IoT sensor networks:Real-time data loggers enable continuous temperature documentation required by emerging market regulators. Pharmaceutical distributors deploy these systems to preempt excursion events during last-mile delivery.
Market Restraints
- Diesel price volatility:Road transport dominates Brazil's interior last-mile networks. Refrigerated fleet operators face margin compression from fuel cost swings that cannot be fully passed to pharmaceutical clients.
- Specialized equipment scarcity:Ultra-low temperature freezers capable of minus 80 degrees Celsius handling concentrate among limited regional suppliers. Equipment lead times extend operational planning horizons.
- Mercosur-Pacific Alliance divergence:Customs harmonization lags behind temperature-control mandates. Cross-border shippers navigate conflicting documentation requirements between southern cone and Pacific bloc frameworks.
Strategic Opportunities
- Colombia's INVIMA licensing expansion:The regulator's tightened cold-chain licensing for biological handlers creates first-mover advantage for certified operators entering Bogotá's emerging pharma distribution hub.
- Cell and gene therapy logistics:Cryogenic liquid nitrogen handling requirements for emerging biologics categories exceed current regional infrastructure. Purpose-built facilities capture premium margins from complex handling protocols.
- Multi-modal air-road integration:Time-sensitive biologics moving between São Paulo and Mexico City demand seamless temperature handoffs. Integrated monitoring systems reduce excursion risk at modal transfer points.
Industry Challenges
- Qualified personnel scarcity:Validated thermal packaging design and GDP audit preparation require specialized expertise. Training pipelines for cold-chain engineers and quality assurance specialists remain underdeveloped regionally.
- Redundant cooling infrastructure capex:Dual-compressor systems and backup generator arrays impose heavy upfront investment. Smaller distributors struggle to finance facility upgrades mandated by ANVISA inspection protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pharmaceutical Cold Chain Logistics Market |
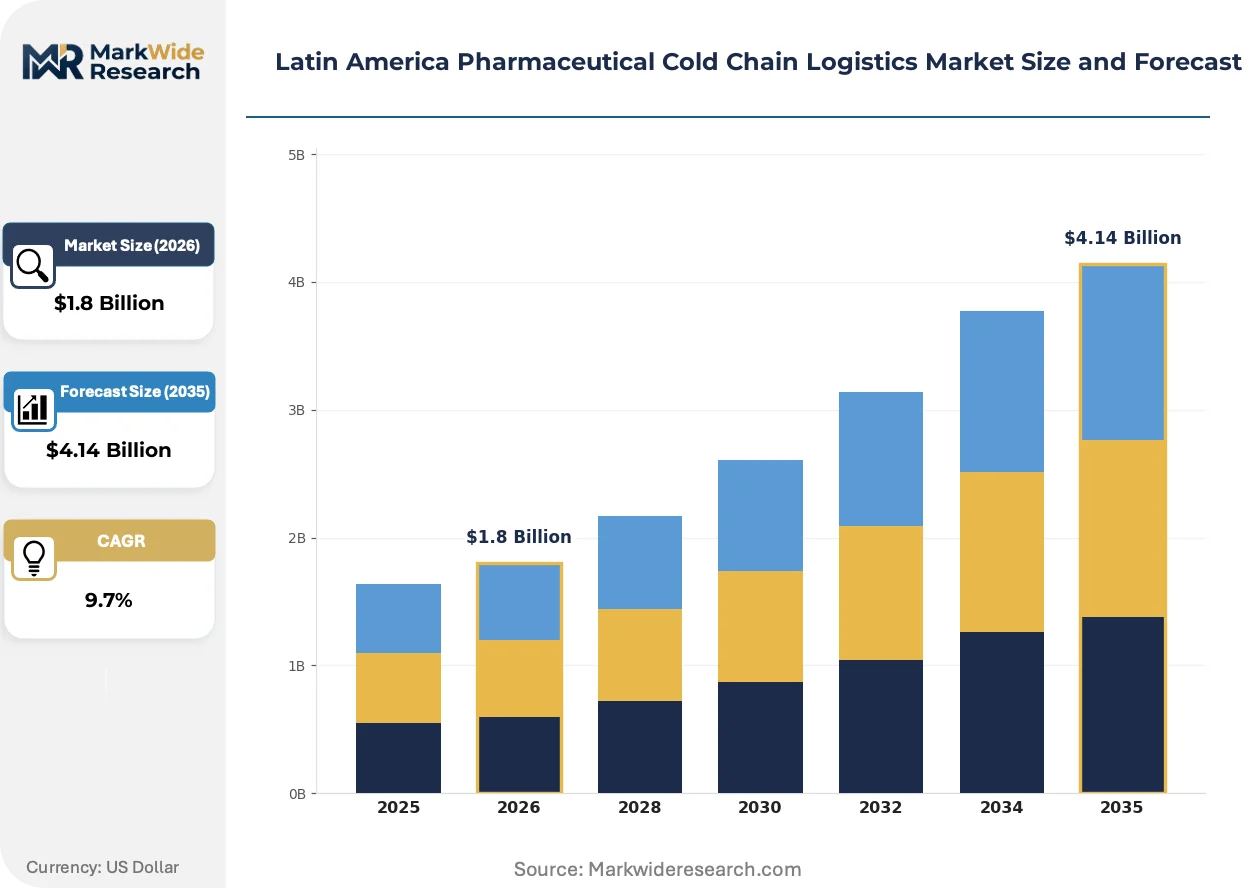
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Biologics, Tablets, Injectables Temperature Range: Deep Frozen, Frozen, Refrigerated, Ambient Transportation Mode: Air Freight, Road Transport, Sea Freight, Rail Freight Packaging Type: Active Containers, Passive Containers, Insulated Boxes, Refrigerated Trucks |
| Companies Covered | Frialsa Frigorificos SA, Comfrio Solucoes Logisticas, Friozem Armazens Frigorificos, Superfrio Armazens Gerais, Americold Logistics, Emergent Cold Latin America, Brasfrigo, DHL Supply Chain, Solistica, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pharmaceutical Cold Chain Logistics Market Trends and Innovations
Digital traceability systems are displacing paper-based temperature logs across Latin America's pharmaceutical corridors. This shift compresses audit preparation timelines while enabling predictive intervention before product degradation occurs.
Bluetooth Low Energy data loggers is miniaturizing cold-chain monitoring hardware to package-level granularity. Vaccine distributors in São Paulo and Mexico City deploy these devices for lane-level risk assessment. The technology compresses insurance premiums by providing excursion evidence admissible in liability disputes.
ANVISA's updated Good Distribution Practices mandate forces warehouse operators to retrofit legacy facilities with continuous environmental monitoring. Pharmaceutical distributors face inspection queue bottlenecks as certification demand outstrips auditor capacity. Brazil's São Paulo state exhibits the steepest compliance acceleration as vaccine production clusters expand.
Consolidated procurement by national immunization programs concentrates buying power among ministry of health purchasers. Third-party logistics providers respond with outcome-based contracts that bundle storage, transport, and compliance documentation. Mexico's federal vaccine acquisition system demonstrates this pattern most visibly, compressing vendor margins while extending contract durations.
Latin America Pharmaceutical Cold Chain Logistics Market Segmentation
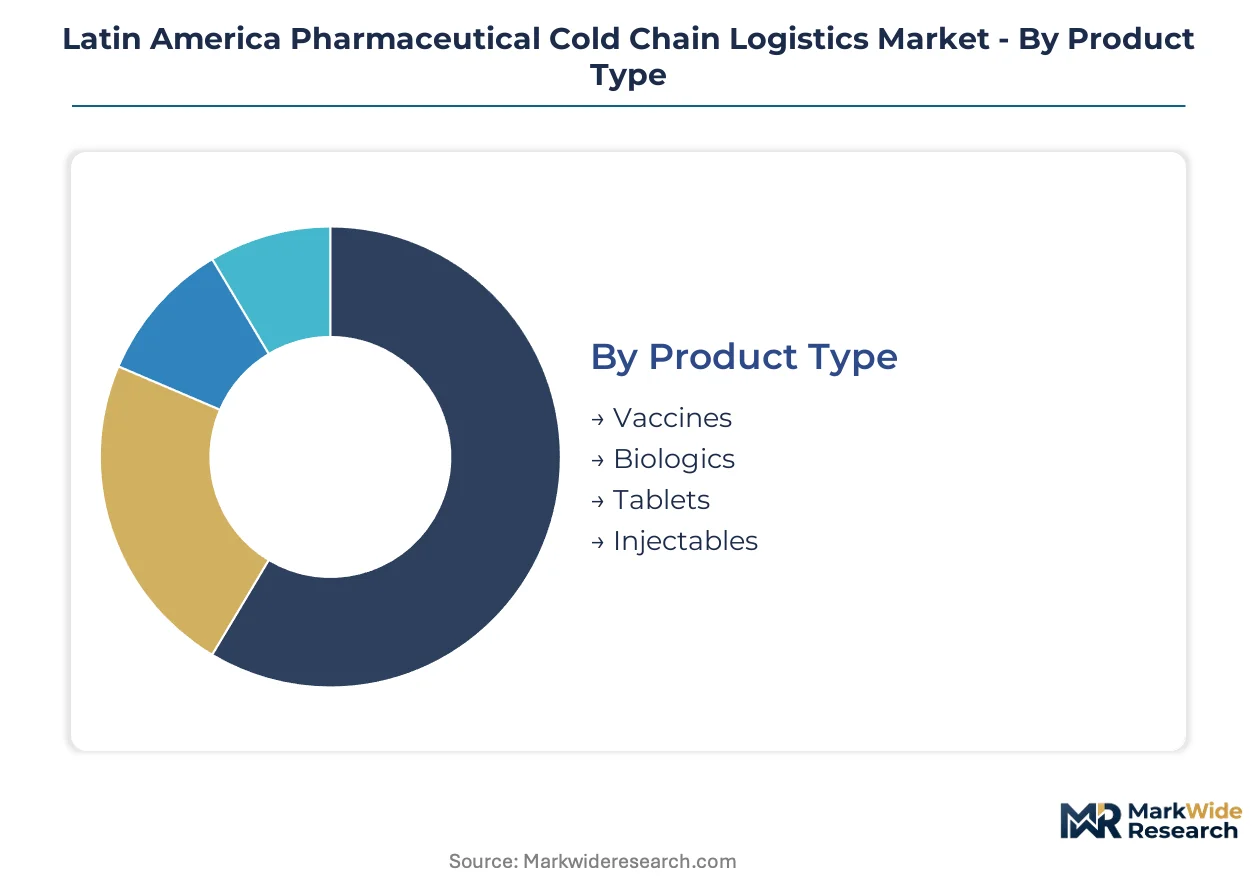
Latin America's pharmaceutical cold chain logistics market segments along four critical dimensions that determine compliance requirements, infrastructure investment, and margin structures. ANVISA, COFEPRIS, and INVIMA each impose distinct validation protocols across these categories, forcing operators to maintain parallel certification tracks.
Product Type:
ANVISA's Good Distribution Practices differentiate handling protocols most sharply across biological versus chemical product categories, with inspection intensity scaling to cold-chain complexity.
- Vaccines:National immunization programs in Brazil and Mexico generate the largest volume flows, requiring validated storage at plus 2 to plus 8 degrees Celsius with continuous temperature documentation. São Paulo's production clusters demand dedicated frozen corridors that only specialized regional providers can construct.
- Biologics:Monoclonal antibodies and recombinant proteins require deep-frozen handling at minus 80 degrees Celsius, creating premium margin pools through specialized equipment scarcity. Cross-border flows between São Paulo and Mexico City concentrate demand for validated ultra-low temperature infrastructure.
- Tablets:Ambient-stable solid dosages dominate volume but carry lower compliance overhead, attracting generalist logistics providers with limited cold-chain investment.
- Injectables:Liquid formulations requiring refrigerated stability occupy a mid-tier complexity position, with demand clustering around hospital pharmacy networks in Colombia's Bogotá corridor.
Established volume favors vaccines; emerging adoption favors biologics.
Temperature Range:
Equipment capital intensity escalates nonlinearly as temperature thresholds drop, segmenting the provider base by financial capacity.
- Deep Frozen:Minus 80 degrees Celsius handling for cell therapies and certain biologics demands liquid nitrogen or specialized mechanical freezers with redundant compressor arrays. Equipment lead times from limited regional suppliers extend operational planning horizons for Brazilian operators.
- Frozen:Minus 20 degrees Celsius corridors serve vaccine bulk storage and plasma derivatives, with São Paulo state exhibiting the steepest capacity expansion as manufacturing clusters grow.
- Refrigerated:Plus 2 to plus 8 degrees Celsius represents the most contested segment, where GDP certification requirements compress legacy warehouse operations.
- Ambient:Plus 15 to plus 25 degrees Celsius handling excludes true cold-chain players, instead attracting pharmaceutical generalists with lower compliance burdens.
Refrigerated corridors capture the widest provider participation; deep frozen commands the steepest expansion trajectory.
Transportation Mode:
Modal selection reflects time-sensitivity versus cost tradeoffs, with biologics flows commanding premium air freight while vaccines tolerate slower road networks.
- Air Freight:Time-sensitive biologics moving between São Paulo and Mexico City demand seamless temperature handoffs, with integrated monitoring systems reducing excursion risk at modal transfer points.
- Road Transport:Diesel price volatility compresses margins for refrigerated fleet operators across Brazil's interior last-mile networks, where fuel cost swings cannot be fully passed to pharmaceutical clients.
- Sea Freight:Bulk vaccine imports through Pacific Alliance ports leverage cost advantages for non-urgent replenishment cycles.
- Rail Freight:Limited refrigerated rail infrastructure constrains adoption to select corridors in southern Brazil and northern Mexico.
Road transport anchors volume; air freight captures value concentration.
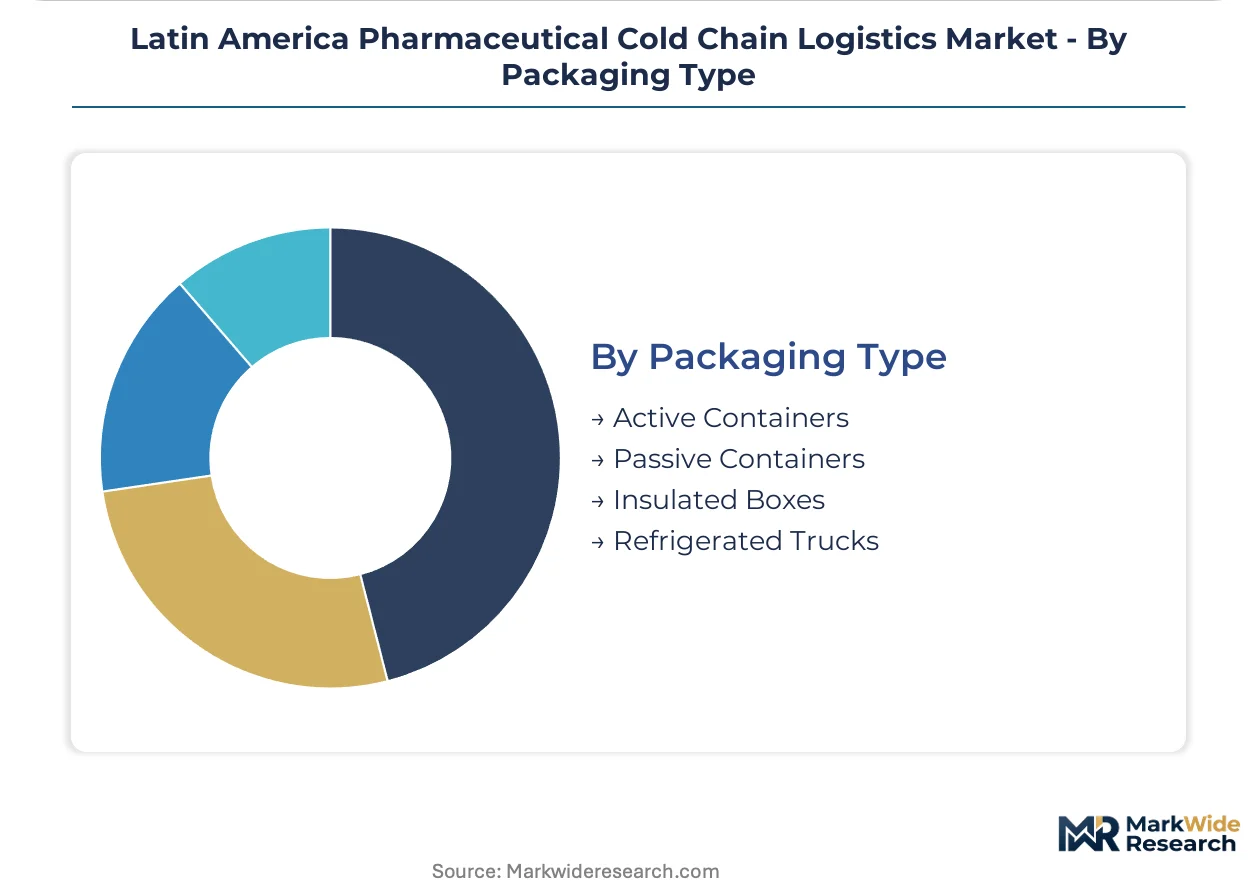
Packaging Type:
Technology sophistication separates validated thermal solutions from commodity insulation, with regulatory documentation requirements favoring sensor-integrated systems.
- Active Containers:Battery-powered refrigeration units with real-time telemetry command premium positioning for high-value biologics, with Bluetooth Low Energy data loggers enabling package-level granularity for lane-level risk assessment.
- Passive Containers:Phase-change material systems without active cooling dominate vaccine last-mile distribution in cost-constrained national immunization programs.
- Insulated Boxes:Expanded polystyrene or polyurethane solutions serve short-duration shipments with limited temperature excursion tolerance.
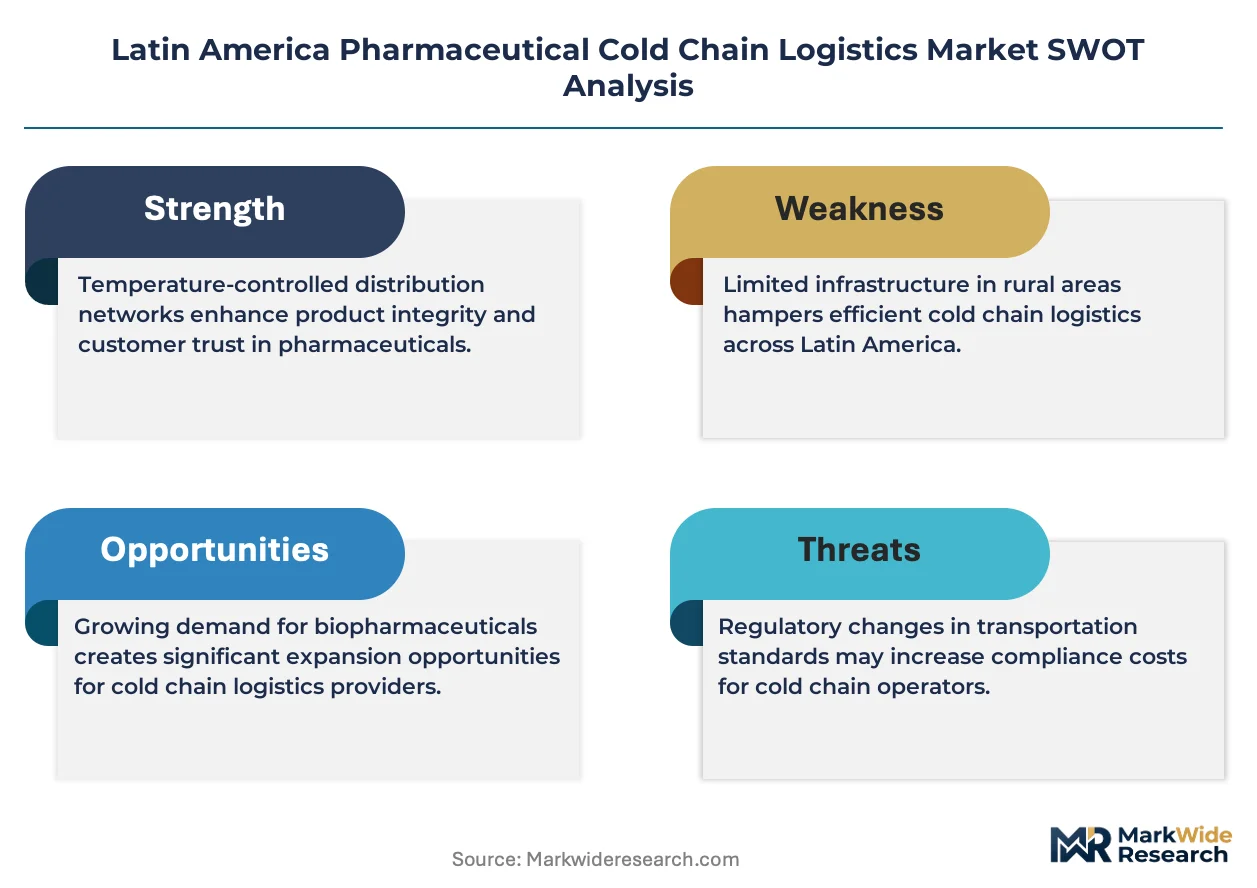
- Refrigerated Trucks:Dedicated vehicle fleets with continuous monitoring anchor Brazil's pharmaceutical distribution backbone, though qualified driver scarcity constrains expansion.
Passive containers dominate procurement volume; active containers are gaining share fastest in premium biologics segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin America pharmaceutical cold chain logistics exhibits a pronounced import dependency for temperature-sensitive biologics, with Brazil and Mexico running structural deficits in ultra-low temperature infrastructure. Cross-border vaccine flows from São Paulo manufacturing clusters toward Pacific Alliance markets generate the region's dominant trade corridors.
Brazil
ANVISA's real-time monitoring mandate is compressing legacy warehouse operations into validated facilities across São Paulo state's pharmaceutical corridor. The regulator's updated Good Distribution Practices force continuous temperature documentation that smaller distributors struggle to finance. São Paulo's vaccine production clusters demand dedicated minus 80 degrees Celsius corridors that only specialized regional providers can construct.
Mexico
COFEPRIS alignment with WHO prequalification standards accelerates cross-border vaccine flows through Mexico City distribution hubs. The federal vaccine acquisition system concentrates procurement power among ministry of health purchasers, compressing vendor margins while extending contract durations. Northern border states handle time-sensitive biologics handoffs from US manufacturers seeking Pacific Alliance market access.
Colombia
INVIMA's tightened cold-chain licensing for biological product handlers creates first-mover advantage for certified operators entering Bogotá's emerging pharma distribution hub. National immunization program scale drives refrigerated corridor demand, though ultra-low temperature infrastructure remains underdeveloped relative to Andean biologics import growth. The country's Pacific ports capture bulk vaccine replenishment cycles from Asian manufacturers.
Chile
Santiago's concentrated hospital pharmacy networks generate mid-tier cold-chain demand for injectables requiring plus 2 to plus 8 degrees Celsius stability. The national pharmaceutical regulator enforces continuous temperature documentation that favors sensor-integrated logistics providers over commodity handlers. Valparaíso's Pacific port infrastructure supports sea freight vaccine imports with cost advantages for non-urgent replenishment.
Argentina
Buenos Aires anchors Mercosur's southern cone pharmaceutical distribution, though customs harmonization lags behind temperature-control mandates create cross-border friction with Brazil. The national health secretariat's immunization programs generate seasonal vaccine volume spikes that strain refrigerated fleet capacity. Local distributors face margin compression from diesel price volatility across interior last-mile networks.
Latin America Pharmaceutical Cold Chain Logistics Market Competitive Landscape
Concentration sits with multi-country refrigerated network operators and international express logistics specialists. Brazil and Mexico each host dominant regional players with validated GDP certification, while global third-party logistics providers capture premium biologics segments through integrated monitoring systems. Three archetypes define competitive positioning: domestic cold storage specialists with multi-country footprints, international express carriers with air-road integration capabilities, and emerging purpose-built pharma facility operators. Capacity expansion and regulatory certification acceleration constitute the dominant competitive moves as ANVISA inspection queues create certification bottlenecks.
Among Mexico-based refrigerated network operators, Frialsa Frigorificos SA anchors cross-border vaccine flows through its multi-country footprint. Emergent Cold Latin America occupies a position within the purpose-built facility tier, exemplifying operators constructing infrastructure to international temperature standards. DHL Supply Chain represents the integrated express carrier archetype, sitting within premium biologics corridors through seamless air-road monitoring systems.
| Leading Market Players |
|---|
| Frialsa Frigorificos SA |
| Comfrio Solucoes Logisticas |
| Friozem Armazens Frigorificos |
| Superfrio Armazens Gerais |
| Americold Logistics |
| Emergent Cold Latin America |
| Brasfrigo |
| DHL Supply Chain |
| Solistica |
| Others |
Pricing and Supply Chain Analysis
Long-term outcome-based contracts with ministry of health purchasers lock in supply access and price visibility across Brazil and Mexico, binding storage, transport, and compliance documentation into multi-year agreements that insulate specialized providers from spot-market volatility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in Latin America's pharmaceutical cold chain. ANVISA GDP certification grade and volume scale drive price differentiation between validated ultra-low temperature handlers and generalist warehouse operators. Cost compression in refrigerated road transport is intensifying because diesel price volatility cannot be fully passed to pharmaceutical clients. National immunization program procurement teams exhibit highest price sensitivity, while biologics manufacturers accept premium positioning for minus 80 degrees Celsius capability.
Supply Chain Analysis
Port congestion at São Paulo's pharmaceutical corridor and container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for ultra-low temperature equipment imports. Equipment manufacturing concentrates in Germany, Japan, and the United States. Regional operators draw from specialized compressor arrays, liquid nitrogen systems, and validated thermal packaging as critical inputs. Single-source vulnerability from limited regional suppliers of minus 80 degrees Celsius freezers creates structural risk. Distribution runs through multi-modal air-road networks anchored by São Paulo and Mexico City hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's pharmaceutical cold chain logistics functions as a service-attach opportunity where compliance documentation and real-time monitoring subscriptions expand faster than warehouse square footage. Recurring revenue from sensor networks and audit preparation services outpaces storage rental growth.
For Market Incumbents: Shield market position by accelerating ANVISA GDP certification for legacy facilities before inspection queue bottlenecks worsen. Vertical integration into IoT sensor deployment captures recurring monitoring revenue that pure-play storage competitors cannot match. Capacity addition in Colombia's Bogotá corridor preempts INVIMA licensing expansion by emerging entrants.
For New Entrants and Emerging Players: Differentiate on cryogenic liquid nitrogen handling capability for cell and gene therapy logistics, a segment where current regional infrastructure falls short of emerging biologics requirements. White-space concentration sits with purpose-built pharma facilities in Pacific Alliance markets outside São Paulo and Mexico City. Go-to-market leverage rests on outcome-based contracts bundling storage, transport, and compliance documentation.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic cold storage specialists with multi-country footprints and active GDP certification pipelines. Long-term viability across the analysis window favors operators with validated ultra-low temperature infrastructure and ministry of health contract relationships. The signal to watch as inflection indicator is INVIMA licensing acceleration in Colombia's emerging pharma distribution hub.
| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Acceleration | ANVISA inspection protocols compress legacy warehouse operations into validated, sensor-dense facilities. |
| Ultra-Low Temperature Infrastructure Buildout | Minus 80 degrees Celsius corridors capture premium margins from biologics manufacturers in São Paulo state. |
| Multi-Modal Air-Road Integration | Seamless temperature handoffs between São Paulo and Mexico City reduce excursion risk at modal transfer points. |
| IoT Sensor Network Deployment | Bluetooth Low Energy data loggers enable package-level granularity for lane-level risk assessment and insurance compression. |
| Outcome-Based Contract Structuring | Bundled storage, transport, and compliance documentation aligns with consolidated procurement by national immunization programs. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cold-chain logistics executives, regulatory affairs specialists at ANVISA and COFEPRIS, pharmaceutical quality assurance directors, and third-party logistics procurement managers; and secondary validation through customs trade records, pharmaceutical distribution licensing databases, SEC filings of listed logistics providers, and WHO prequalification documentation. Bottom-up facility capacity enumeration triangulated against top-down national immunization program procurement disclosures.
Across the projection horizon, the analytical framework modeled volume and value outputs through four segmentation dimensions: product type, temperature range, transportation mode, and packaging technology, with regional regulatory cluster as an overlay. CAGRs derived from fitted growth curves applied to validated infrastructure capacity expansion plans and ministry of health contract award patterns. Modeled inputs incorporated diesel price volatility scenarios and equipment lead time distributions from regional ultra-low temperature freezer suppliers.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA enforcement intensity, stable ministry of health procurement continuity, and resolved Mercosur-Pacific Alliance customs harmonization would require recalibration. Forecasts reflect documented assumptions regarding regulatory certification timelines and cross-border vaccine flow volumes. Specific risk factors that could revise projections include abrupt diesel subsidy removal, extended equipment import delays, or regulatory divergence between southern cone and Pacific bloc frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Freezer Liner Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
North America Passive Temperature Controlled Packaging Market