
 Coffee Gummy Market | 2026-2036
Coffee Gummy Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Gummy Market Insights
Confectionery formulation expertise is unwinding as a bottleneck, with trained food technologists migrating from traditional candy houses into functional gummy startups. HVMN leverages its nootropic heritage to anchor premium positioning in cognitive-performance positioning. Seattle Gummy Company dominates West Coast specialty retail through deep pharmacy and health-food channel relationships. Punch'd Energy competes on portability, sustaining distribution gains in convenience and travel retail formats.
Coffee gummies combine gelatin or pectin matrices with spray-dried or cold-brew coffee extract, typically delivering 20–100 mg caffeine per serving alongside functional additives like L-theanine or B vitamins for sustained energy release. Sugar-free Coffee Gummies lead volume contribution as diabetic-friendly and keto-aligned consumers reject sucrose-laden alternatives, while Vitamin-Infused Coffee Gummies represent the fastest-growing margin pool as wellness-positioned buyers accept premium pricing for dual-benefit positioning. Energy Boost Coffee Gummies occupy an established functional niche where repeat purchase rates exceed flavor-driven variants, though Classic Espresso and Mocha Chocolate flavor profiles still command the largest combined share of first-time trials.
FDA oversight of caffeine content and novel food ingredient notifications constrains formulation freedom for entrants lacking regulatory affairs capacity, while USDA organic certification requirements and state-level cottage food laws create uneven market access across jurisdictions. EFSA caffeine exposure guidelines indirectly shape export-bound product specifications for manufacturers targeting European health-food channels. Stakeholders must monitor evolving caffeine disclosure mandates and clean-label certification thresholds to preserve shelf placement and consumer trust without reformulation drag.
Market Dynamics
Functional confectionery is fragmenting traditional candy economics as gelatin and pectin expertise migrates toward caffeinated wellness formats, compressing formulation timelines while expanding permissible ingredient matrices.
Growth Catalysts
- Clean-label certification thresholds:USDA organic and Non-GMO Project verification unlocks shelf placement in Whole Foods and Sprouts channels, commanding 15-25% price premiums over conventional alternatives.
- Cold-brew extraction protocols:Ambient-stable coffee concentrate production preserves volatile aromatic compounds, enabling flavor parity with ready-to-drink coffee in shelf-stable gummy formats.
- Young urban professional commute patterns:Dense coastal metropolitan clusters in the United States generate concentrated trial velocity through grab-and-go pharmacy and convenience formats.
Market Restraints
- FDA novel food notification requirements:Caffeinated ingredient thresholds trigger extended safety review timelines, delaying product launches by 12-18 months for entrants lacking established GRAS dossiers.
- Gelatin supply concentration:Bovine and porcine gelatin production clusters in Brazil and India expose formulators to livestock commodity volatility and religious dietary restriction conflicts.
- Energy drink substitution:Liquid caffeine delivery maintains cost and habit-formation advantages in convenience retail, constraining gummy format penetration among price-sensitive energy seekers.
Strategic Opportunities
- European health-food channel expansion:EFSA caffeine exposure guidelines create compliant formulation roadmaps for export-bound manufacturers targeting German and Dutch pharmacy retail.
- L-theanine and nootropic stacking:Cognitive-performance positioning converges with adaptogen demand, opening premium tier pricing comparable to supplement rather than confectionery categories.
- Travel retail and airport convenience:TSA-compliant portable caffeine formats capture business traveler segments underserved by liquid restrictions and brewing equipment dependencies.
Industry Challenges
- Food technologist talent scarcity:Trained confectionery chemists command premium compensation as traditional candy houses and functional startups compete for gelatin-pectin matrix expertise.
- Dual certification timelines:Simultaneous pursuit of FDA facility registration and USDA organic approval extends go-to-market schedules, straining working capital for emerging brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Gummy Market |
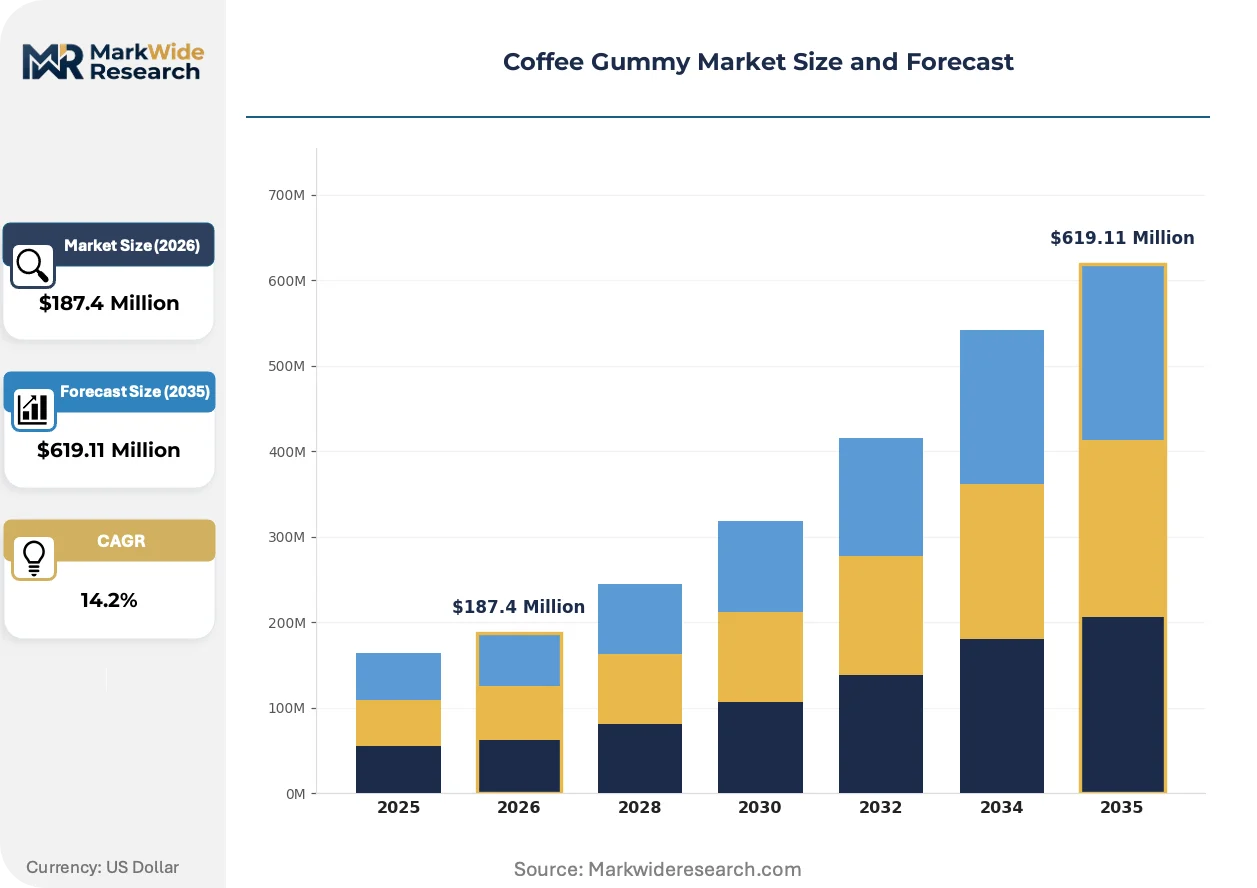
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Coffee Gummies, Organic Coffee Gummies, Sugar-free Coffee Gummies, Energy Boost Coffee Gummies, Vitamin-Infused Coffee Gummies Flavor Profile: Classic Espresso, Mocha Chocolate, Vanilla Latte, Caramel Macchiato, Hazelnut Aroma Packaging Format: Blister Packs, Resealable Pouches, Single-Serve Sachets, Jar Containers, Gift Boxes Distribution Channel: Specialty Stores, Health Food Shops, Online Retailers, Pharmacists, Vending Machines |
| Companies Covered | HVMN, Dry Brew, TopGum, Seattle Gummy Company, Fuwei Fruits & Nuts Manufacturing Co., Man Matters, Hilo Gummies, Energy Bytes, Punch’d Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Gummy Market Trends and Innovations
Spray-dried coffee microencapsulation is compressing flavor degradation curves while pectin-based vegan matrices displace gelatin in premium positioning. These shifts are reconfiguring ingredient supplier relationships and clean-label certification strategies across the functional confectionery value chain.
Microencapsulation technology is miniaturizing coffee oil droplet distribution within carbohydrate shells, masking bitterness while enabling 18-month shelf stability without artificial preservatives. Premium wellness brands are adopting this at accelerated cadences, collapsing the historical trade-off between flavor fidelity and functional ingredient loading. The technology is miniaturizing batch-to-batch variation, allowing contract manufacturers to guarantee consistent caffeine titration across production runs.
EFSA caffeine exposure guidelines are tightening import specifications for European-bound products, capping single-serving content and mandating pregnancy warning labels. Manufacturers are reformulating export SKUs below 200mg daily thresholds, diverting higher-dose variants exclusively to United States distribution. German pharmacy chains are demanding EFSA-compliant documentation as a prerequisite for health-food aisle placement, filtering out non-compliant entrants.
Subscription-direct models are displacing traditional distributor relationships for repeat-purchase energy segments, capturing consumption data that informs flavor rotation and dosing optimization. Digital-native brands are bypassing UNFI and KeHE middlemen, retaining margin that funds sampling programs in co-working spaces and fitness studios. This channel migration concentrates in coastal United States metropolitan markets where delivery logistics density supports cold-chain-free fulfillment.
Coffee Gummy Market Segmentation
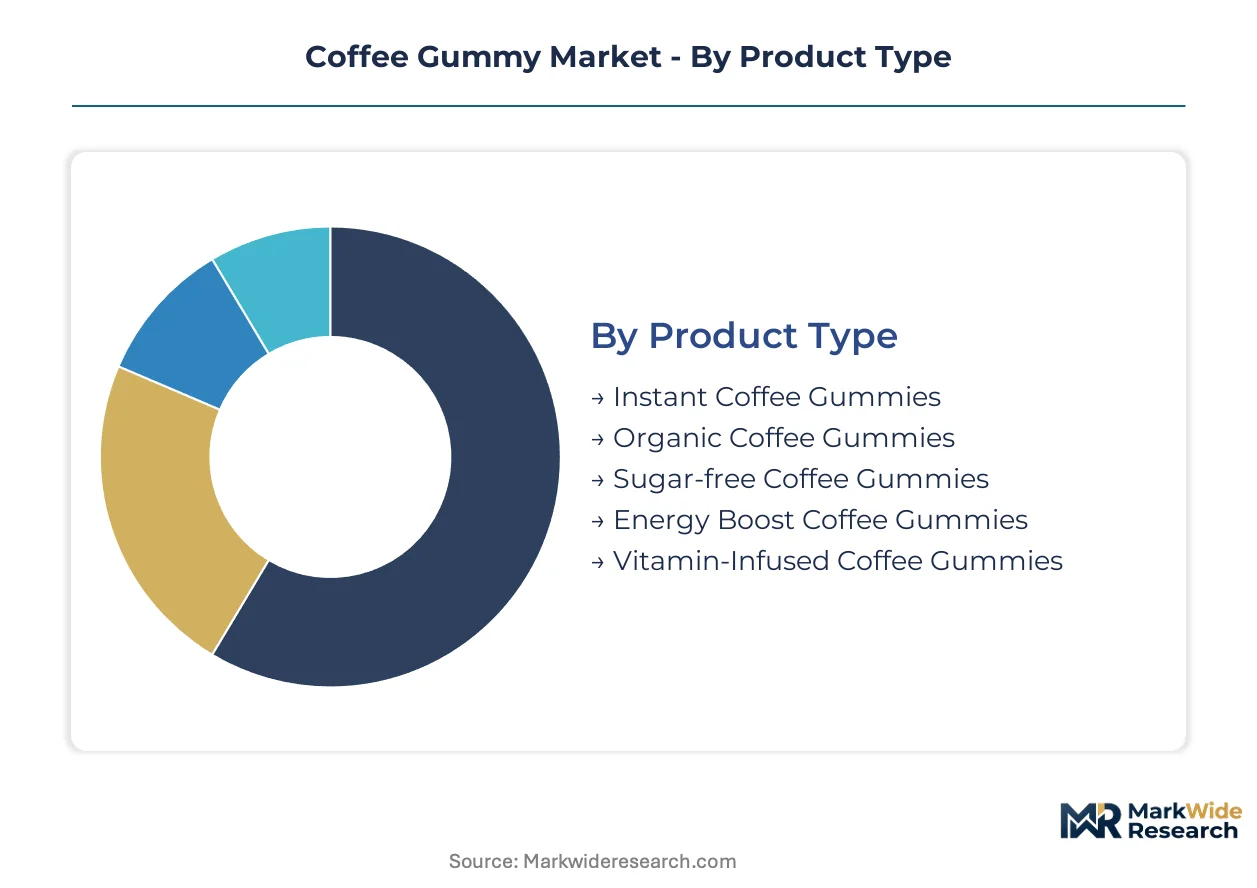
Segmentation in the coffee gummy market determines channel access and margin capture. Product composition dictates whether brands penetrate pharmacy, convenience, or specialty retail. Packaging and flavor choices shape trial rates among commuter versus wellness-oriented buyers.
Product Type:
Channel placement varies sharply by functional positioning. Sugar-free variants dominate pharmacy and health-food aisles. Energy-boost formats capture convenience retail and travel channels.
- Sugar-free Coffee Gummies:Formulated with sugar alcohols or stevia to replace sucrose, targeting diabetic-friendly and ketogenic diet adherents. Demand concentrates in United States coastal metropolitan clusters where Whole Foods and Sprouts channels enforce clean-label certification thresholds.
- Vitamin-Infused Coffee Gummies:Stack caffeine with B-complex vitamins, L-theanine, or adaptogens for sustained-release positioning. Wellness-positioned buyers in Seattle and San Francisco pharmacy channels accept premium pricing for dual-benefit formulations.
- Energy Boost Coffee Gummies:High-caffeine matrices (80–100mg per serving) optimized for immediate effect.
- Instant Coffee Gummies:Spray-dried coffee concentrate in rapid-dissolve formats.
- Organic Coffee Gummies:USDA-certified inputs with full supply chain traceability.
By volume, Sugar-free Coffee Gummies lead. By growth pace, Vitamin-Infused Coffee Gummies are climbing the fastest.
Flavor Profile:
Flavor selection drives first-trial conversion versus repeat purchase retention. Classic profiles anchor mass-market penetration. Novel variants capture premium positioning.
- Classic Espresso:Bitter-forward profile using dark-roast arabica extract. Dominates first-time trials through familiarity transfer from ready-to-drink coffee habits in United States grab-and-go channels.
- Mocha Chocolate:Cocoa powder and coffee extract combination masking caffeine bitterness. Coastal metropolitan clusters with dense specialty retail footprints show highest velocity for this crossover appeal.
- Vanilla Latte:Creamy flavor profile with dairy or plant-based milk notes.
- Caramel Macchiato:Sweet-forward positioning for confectionery-oriented buyers.
- Hazelnut Aroma:Nutty flavor variant targeting European-origin taste preferences.
Classic Espresso commands the largest share of initial purchases. Mocha Chocolate posts the steepest expansion trajectory in repeat-buyer cohorts.
Packaging Format:
Packaging determines shelf-life economics and consumption occasion targeting. Single-serve formats command per-unit premiums. Bulk formats reduce cost-per-dose for subscription channels.
- Single-Serve Sachets:Individual foil or paper wrappers enabling precise dosing and TSA-compliant portability. Business travelers in United States airport convenience formats drive demand for this restriction-compliant caffeine delivery.
- Resealable Pouches:Multi-layer barrier films with zip-lock closures for moisture protection. Daily commuters in dense urban clusters favor this format for desk-drawer storage and controlled portioning.
- Blister Packs:Thermoformed plastic cavities with foil backing for pharmaceutical-grade presentation.
- Jar Containers:Rigid PET or glass packaging for home pantry storage.
- Gift Boxes:Premium rigid packaging for seasonal and corporate gifting occasions.
Resealable Pouches generate highest unit volume. Single-Serve Sachets are gaining share fastest among format innovations.
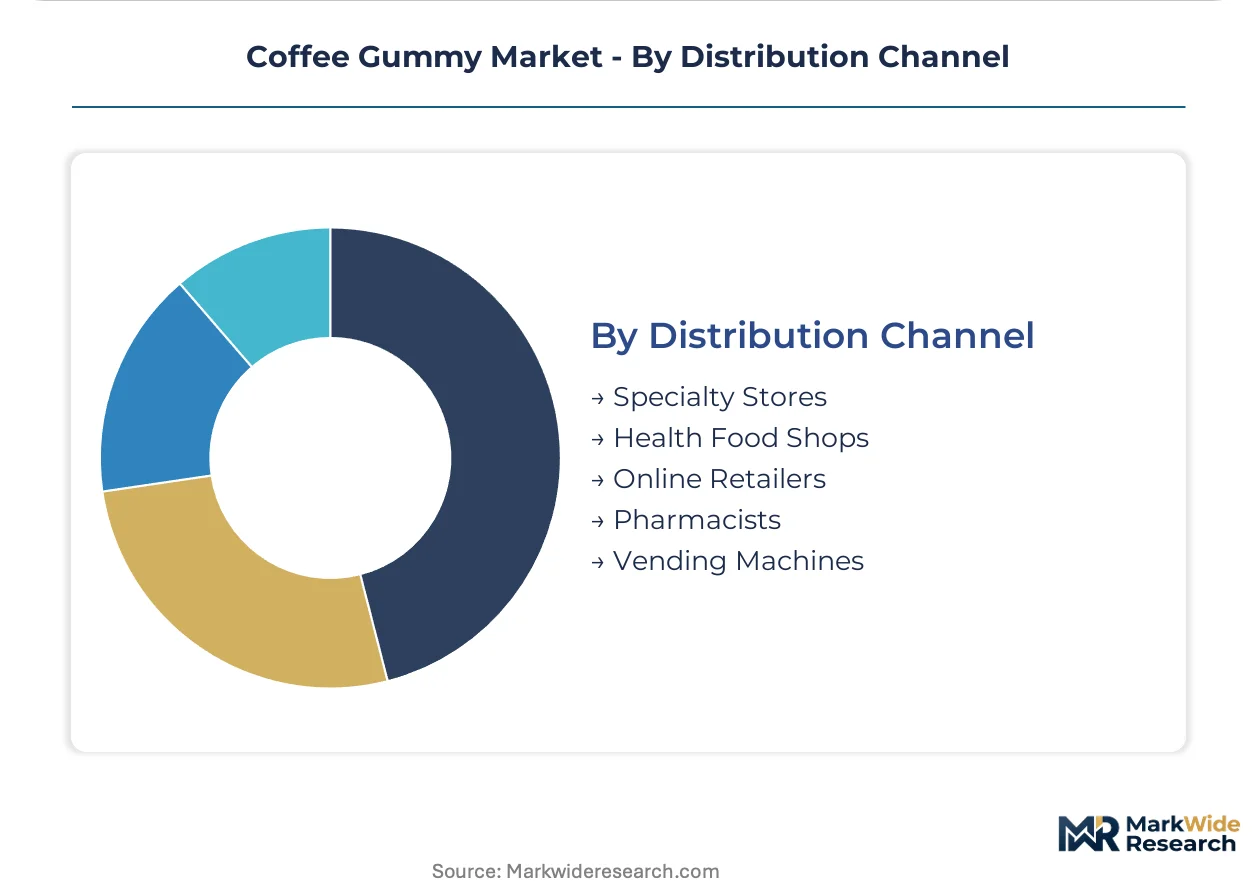
Distribution Channel:
Channel selection determines margin structure and regulatory exposure. Pharmacy channels demand FDA-compliant labeling. Online channels enable subscription economics but sacrifice impulse trial.
- Specialty Stores:Curated assortments in independent grocers and regional chains with trained staff. West Coast United States markets with deep health-food channel relationships sustain highest velocity for premium-positioned variants.
- Online Retailers:Direct-to-consumer and marketplace platforms capturing subscription-direct models. Digital-native brands bypass UNFI and KeHE middlemen, concentrating in coastal metropolitan markets with delivery logistics density.
- Health Food Shops:Natural product retailers with certified organic requirements.
- Pharmacists:Professional channel with trained consultation and functional positioning.
- Vending Machines:Automated retail in co-working spaces, fitness studios, and transit hubs.
Online Retailers lead by transaction volume. Specialty Stores show the strongest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA novel food notification requirements shape formulation freedom for United States manufacturers, while EFSA caffeine exposure guidelines constrain export-bound product specifications for European health-food channels.
United States
Young urban professionals in coastal metropolitan clusters drive trial velocity through grab-and-go pharmacy formats. FDA oversight of caffeine content and novel food ingredient notifications extends safety review timelines for entrants lacking established GRAS dossiers. Seattle and San Francisco sustain dense specialty retail footprints where clean-label certification unlocks shelf placement.
Germany
Pharmacy channel buyers demand EFSA-compliant documentation for health-food aisle placement. German regulators enforce strict caffeine exposure thresholds capping single-serving content below 200mg daily limits. Berlin and Munich anchor distribution networks filtering out non-compliant entrants through documentation requirements.
United Kingdom
Subscription-direct models capture repeat-purchase segments in London and Southeast England delivery corridors. The Food Standards Agency coordinates with EFSA guidelines on novel food ingredient assessments. Manchester and Birmingham health-food independents curate assortments demanding Non-GMO Project verification.
Japan
Business traveler segments in Tokyo and Osaka airports favor TSA-compliant portable caffeine formats. METI standards on functional food labeling shape product positioning for cognitive-performance claims. Nagoya and Fukuoka vending machine networks test automated retail for commuter convenience.
Australia
TGA oversight of complementary medicines influences caffeine disclosure mandates for wellness-positioned imports. Sydney and Melbourne specialty grocers enforce clean-label thresholds comparable to United States coastal markets. Brisbane fitness studios generate sampling velocity for energy-boost variants.
Coffee Gummy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with formulation expertise migrating from traditional candy houses into functional startups while contract manufacturers scale cold-brew extraction protocols. The vendor base spans nootropic heritage brands, West Coast specialty retail specialists, and Asian manufacturing conglomerates with gelatin supply chain control. Three archetypes dominate: cognitive-performance premium positioners, convenience-format portability champions, and private-label production platforms. Competitive moves concentrate on strategic partnerships for channel access and portfolio diversification into adaptogen stacking.
Within the nootropic heritage tier, HVMN anchors premium positioning through cognitive-performance expertise. Among West Coast specialty retail specialists, Seattle Gummy Company occupies a position exemplifying deep pharmacy and health-food channel relationships. On the portability vector, Punch'd Energy represents the convenience and travel retail format archetype.
| Leading Market Players |
|---|
| HVMN |
| Dry Brew |
| TopGum |
| Seattle Gummy Company |
| Fuwei Fruits & Nuts Manufacturing Co. |
| Man Matters |
| Hilo Gummies |
| Energy Bytes |
| Punch'd Energy |
| Others |
Pricing and Supply Chain Analysis
USDA organic certification gates both supplier qualification and price differentiation simultaneously, filtering contract manufacturers while unlocking 15-25% shelf-price premiums in Whole Foods and Sprouts channels. Gelatin and pectin matrix expertise concentrates among a shrinking pool of trained food technologists, compressing margins for brands lacking captive formulation capacity while rewarding vertically integrated producers with cost control.
Pricing Analysis
Coastal United States metropolitan clusters command 20-35% price premiums over interior markets due to clean-label certification density and specialty retail concentration. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic variants from conventional alternatives and private-label economy tiers. Cost compression in the standard tier is intensifying because contract manufacturers compete for limited food technologist talent. Keto-aligned and diabetic-friendly buyers in pharmacy channels show least price sensitivity, while convenience-format energy seekers exhibit highest elasticity.
Supply Chain Analysis
Bovine and porcine gelatin production clusters in Brazil and India expose formulators to livestock commodity volatility and religious dietary restriction conflicts. Cold-brew extraction protocols draw from Colombian and Ethiopian arabica supply chains, while pectin alternatives rest on citrus peel processing concentrated in Mexico and Spain. Single-source vulnerability runs through Brazilian gelatin processors serving North American contract manufacturers. Distribution runs through UNFI and KeHE for traditional retail, though digital-native brands bypass these intermediaries via subscription-direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional confectionery fragmentation creates white-space niches as wellness-positioned buyers reject sucrose-laden alternatives and demand dual-benefit vitamin stacking. Young urban professional commute patterns and TSA-compliant portability requirements generate segmentable demand pools underserved by liquid energy formats.
For Market Incumbents: Shield formulation expertise through exclusive employment contracts with trained food technologists migrating from traditional candy houses. Deepen backward integration into cold-brew extraction capacity to secure ambient-stable concentrate supply against Colombian arabica price volatility. Fortify pharmacy channel relationships against digital-native subscription competitors by embedding co-branded sampling programs in fitness studios. For New Entrants and Emerging Players: Lead with TSA-compliant single-serve sachets targeting business travelers in airport convenience formats, the most penetrable white-space segment. Capture trial velocity through co-working space sampling programs in Seattle and San Francisco before expanding through UNFI distribution. Anchor positioning in L-theanine and adaptogen stacking to access supplement-category pricing rather than confectionery margins. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microencapsulation-equipped production lines as spray-dried coffee technology demands specialized equipment investment. Acquisition targets should display captive gelatin-pectin matrix expertise and established GRAS dossiers shortening FDA novel food notification timelines. Monitor EFSA caffeine exposure guideline enforcement as the inflection signal determining European export viability for portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Investment | Spray-dried coffee oil miniaturization preserves 18-month shelf stability without artificial preservatives. |
| USDA Organic Certification Pursuit | Clean-label verification unlocks Whole Foods and Sprouts shelf placement commanding premium pricing. |
| Subscription-Direct Channel Launch | Digital-native brands bypass UNFI middlemen while capturing consumption data for flavor rotation optimization. |
| EFSA-Compliant Formulation Development | German pharmacy chains demand compliant documentation filtering non-compliant entrants from health-food aisles. |
| Food Technologist Talent Acquisition | Trained confectionery chemists command premium compensation as traditional candy houses and startups compete. |
Research Methodology
Operator-level perspectives from food technologists at contract manufacturers, regulatory affairs leads at functional gummy startups, category buyers at Whole Foods and Sprouts, and procurement managers at gelatin suppliers anchored the qualitative base. Secondary validation drew from FDA novel food notification filings, USDA organic certification databases, EFSA caffeine exposure guidelines, and customs records tracking Brazilian and Indian gelatin imports. Bottom-up demand modeling across commuter occasion segments triangulated against top-down functional confectionery market sizing.
Sensitivity analysis tested caffeine content thresholds, clean-label certification penetration rates, and contract manufacturing capacity constraints across the projection horizon. Segmentation dimensions modeled included product composition tier, flavor profile category, packaging format type, and distribution channel structure. CAGRs were derived from historical functional confectionery adoption curves adjusted for coffee-specific trial velocity in coastal metropolitan clusters. Forecast inputs incorporated cold-brew extraction protocol adoption rates and food technologist labor market tightness indices.
Forecasts assume regulatory continuity in FDA novel food notification requirements and EFSA caffeine exposure guidelines; material policy shifts would require re-modeling launch timelines and export SKU specifications. Practitioners should keep alternative scenarios live as FDA enforcement discretion on caffeinated novel foods and state-level cottage food law variations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Gum Base Candy Market
Confectionery
Milk Chocolate Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Ice Cream Coating Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
South Korea Chocolate Market
Confectionery
Macarons Market
Confectionery
Canada Chocolate Market
Confectionery
Chocolate Confectionery Market
Confectionery
South America Chocolate Market
Confectionery
North America Chocolate Market
Confectionery
South America Compound Chocolate Market
Confectionery
Caramel Chocolate Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Low-Calorie Candy Market
Confectionery
Low-Fat Sweets Market