
 South Korea Chocolate Market | 2026-2036
South Korea Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Chocolate Market Outlook
Young adult gift buyers is rotating toward premium bean-to-bar and single-origin products, displacing traditional mass-market purchases in South Korea. Lotte Wellfood Co., Ltd. anchors the domestic landscape through its entrenched retail and duty-free distribution networks. Orion Confectionery Co., Ltd. differentiates via snack-coated chocolate hybrids that dominate convenience store shelves. Ferrero International S.A. competes in the premium gifting tier with its imported assortment positioning.
Chocolate comprises cocoa solids, cocoa butter, sugar, and emulsifiers processed through conching, tempering, and molding into confectionery products with defined cocoa mass percentages. The primary commercial purpose centers on indulgent consumption, seasonal gifting, and food service ingredient applications across bakery and beverage formulations. Dark chocolate leads product type margins due to health-positioned antioxidant claims and elevated price points, while ruby chocolate represents the fastest-growing niche driven by visual differentiation in gift packaging. Convenience stores dominate sales channel volume through impulse placement, though online retailers capture the fastest expansion via subscription gifting models.
MFDS enforces strict food labeling standards governing cocoa content declarations and allergen warnings, directly shaping product formulation and packaging design requirements. The Korea Food & Drug Safety Ministry's sugar reduction guidelines and import tariff structures under KFTA agreements influence domestic pricing and sourcing strategies. Stakeholders must monitor evolving clean-label expectations and e-commerce regulatory frameworks to sustain competitive positioning in premium segments.
Market Dynamics
MFDS labeling mandates for cocoa content transparency and allergen disclosure are compressing formulation flexibility while redirecting R&D investment toward clean-label compliance and premium positioning in Seoul's boutique retail corridor.
Growth Catalysts
- Experiential Gifting Formats:Young adult consumers in Seoul's Gangnam and Hongdae districts are rotating toward bean-to-bar tasting sets and origin-story packaging, displacing conventional boxed assortments.
- KFTA Tariff Structures:Import duty adjustments under the Korea Free Trade Agreement framework are lowering landed costs for European cocoa butter and specialty ingredients, enabling margin expansion in premium tiers.
- Single-Origin Positioning:Bean-to-bar processing technology is allowing domestic craft producers to command price premiums through terroir narratives and direct-trade sourcing stories.
Market Restraints
- Cocoa Butter Volatility:West African supply concentration and currency fluctuation against the Korean won are compressing input cost predictability for domestic manufacturers.
- MFDS Compliance Friction:Mandatory allergen warning expansions and cocoa percentage declaration precision are extending new product development timelines and raising packaging redesign costs.
- Sugar Reduction Mandates:Korea Food & Drug Safety Ministry guidelines on added sugar thresholds are constraining formulation options in milk chocolate segments where consumer taste expectations remain fixed.
Strategic Opportunities
- Subscription Gifting Models:Online retailers are capturing fastest channel expansion through curated monthly chocolate clubs targeting corporate gift procurement and milestone occasion buyers.
- Ruby Chocolate Applications:Barry Callebaut's pink-hued cocoa variety is creating visual differentiation opportunities in seasonal gift packaging for Valentine's and Chuseok holiday segments.
- Duty-Free Channel Expansion:Incheon International Airport's transit retail corridors offer underpenetrated access to Chinese and Southeast Asian tourist segments seeking premium Korean confectionery souvenirs.
Industry Challenges
- Confectionery Technologist Scarcity:Specialized expertise in bean-to-bar roasting profiles and tempering precision is concentrated among a small cohort of European-trained Korean chocolatiers, constraining craft sector scaling.
- Clean-Label Reformulation Complexity:Removing soy lecithin and synthetic vanillin while maintaining shelf stability and mouthfeel is extending pilot production cycles and raising failure rates in premium line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Chocolate Market |
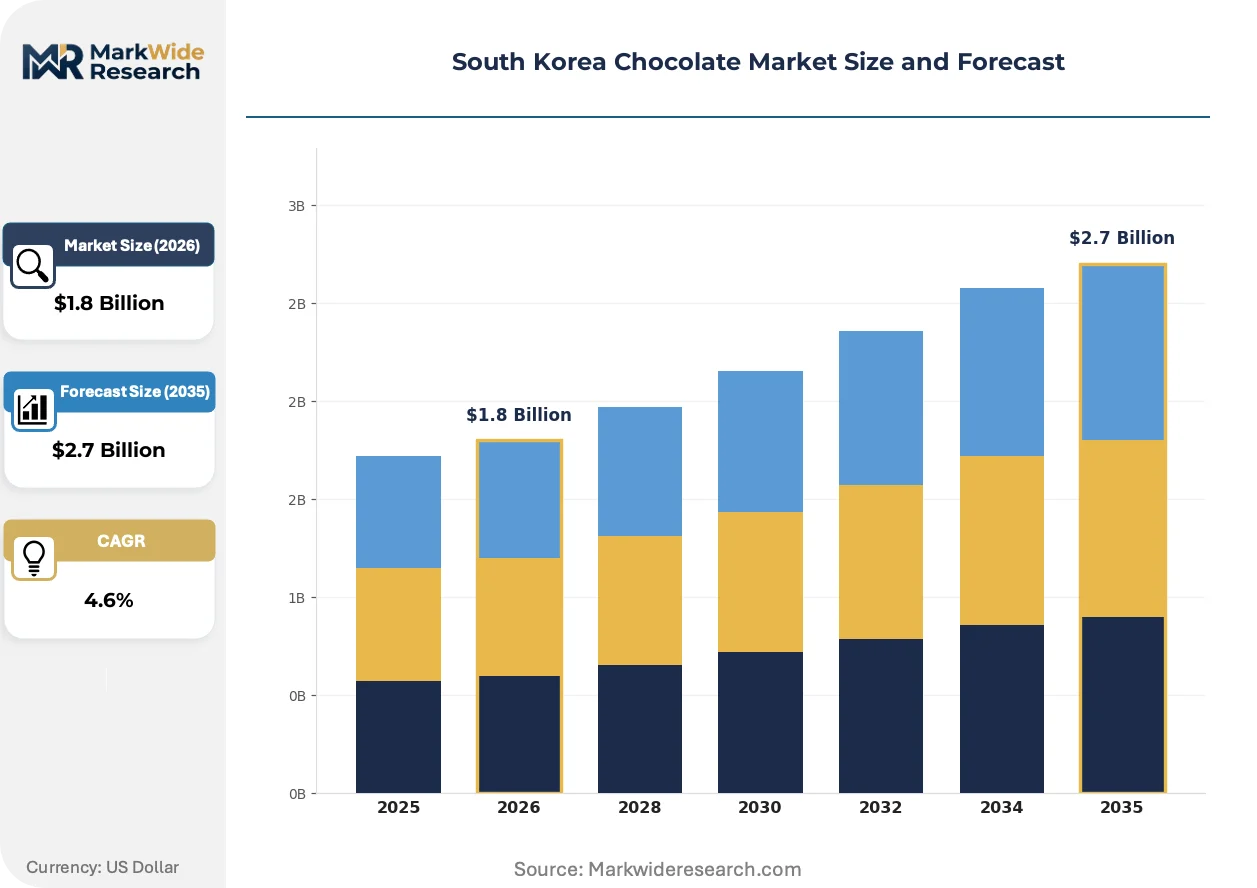
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Food Service, Confectionery Manufacturers, Bulk Buyers Packaging Type: Bags, Boxes, Bulk Containers, Individual Wrappers Sales Channel: Online Retailers, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Mars, Incorporated, Haitai Confectionery & Foods Co., Ltd., Lotte Wellfood Co., Ltd., Meiji Holdings Co., Ltd., Mondelez International, Inc., Orion Confectionery Co., Ltd., Ferrero International S.A., Hershey Korea Co., Ltd., Crown Confectionery Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Chocolate Market Strategic Shifts
Technology-driven production transparency and regulatory pressure on ingredient disclosure are converging to reshape competitive positioning, while channel fragmentation between convenience impulse and curated online discovery is rewriting go-to-market architectures.
Precision conching equipment with real-time particle size monitoring is supplanting traditional batch processing in Seoul's craft chocolate ateliers. Premium boutique producers in Seongsu-dong are adopting these systems to achieve sub-20-micron fineness consistency that signals quality to discerning gift buyers. The technology is compressing quality variance between small-batch and industrial-scale output, eroding a traditional differentiator for mass manufacturers.
MFDS enforcement of expanded allergen labeling and cocoa content declaration precision is tightening packaging design constraints. Manufacturers must now display specific percentage thresholds for cocoa solids and butter alongside mandatory warning symbols for milk, soy, and tree nuts. Dark chocolate SKUs positioned above 70% cocoa content are most affected, as label real estate competition intensifies between health claims and regulatory disclosures.
Gift buyers are rotating from supermarket seasonal displays toward curated online discovery platforms featuring origin documentaries and maker profiles. Subscription services and boutique e-commerce sites are displacing department store confectionery halls as the primary research and purchase channel for premium bean-to-bar selections. This behavioral shift is most pronounced among millennials in Seoul's central districts, where convenience store impulse purchasing persists for snack-coated hybrids but collapses for occasion gifting.
South Korea Chocolate Market Segmentation
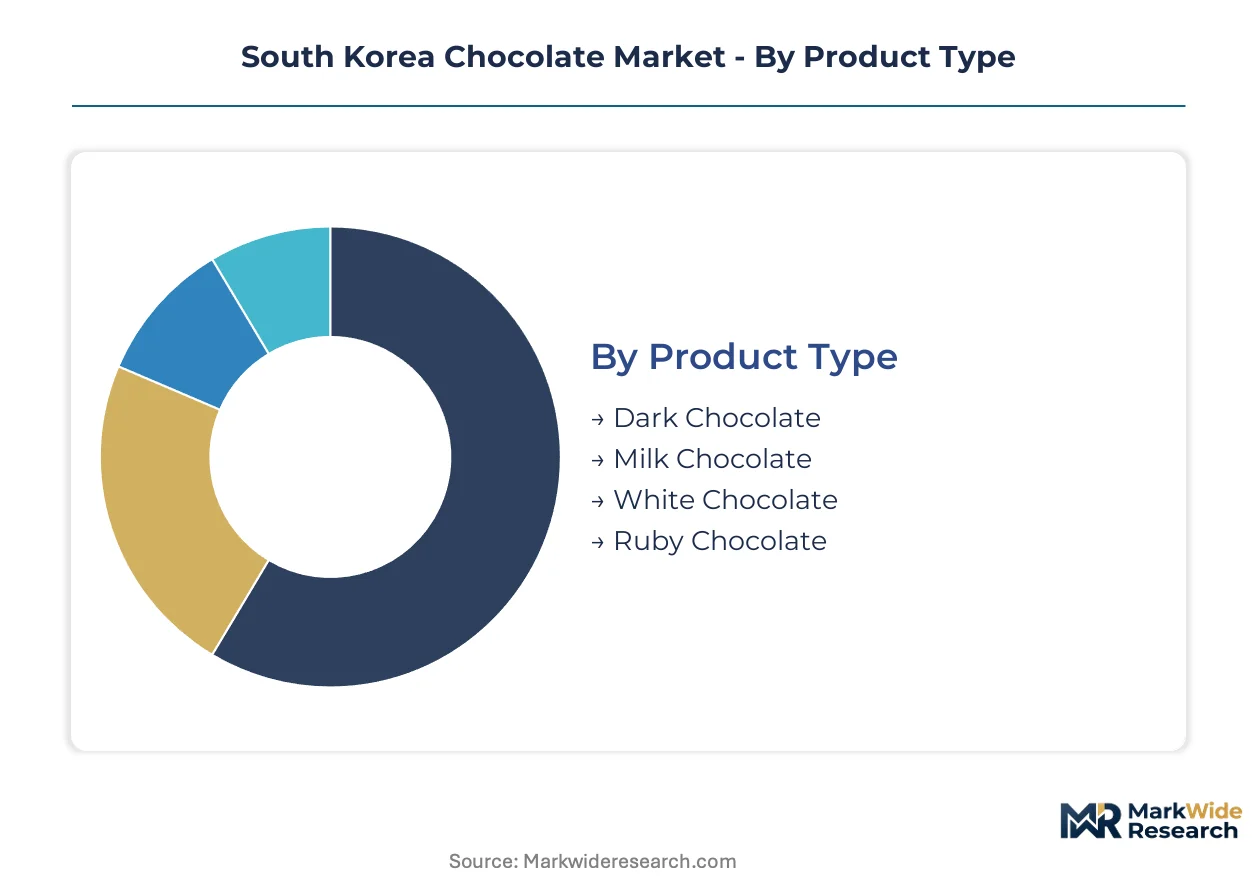
Segmentation in South Korea's chocolate market reveals distinct demand pockets shaped by Seoul's premium gifting culture and the regulatory precision enforced by MFDS. Understanding these divisions enables targeted positioning across convenience-driven impulse purchases and curated experiential formats.
Product Type:
Dark chocolate and milk chocolate anchor domestic manufacturing output, while ruby chocolate enters primarily through European import channels targeting duty-free and boutique retail.
- Dark Chocolate:Cocoa mass exceeding 70% dominates premium positioning in Gangnam district specialty shops, where antioxidant health claims justify elevated price points. MFDS labeling mandates for precise cocoa percentage declarations compress formulation flexibility for domestic producers.
- Milk Chocolate:Sugar reduction guidelines from the Korea Food & Drug Safety Ministry constrain reformulation options where consumer taste expectations remain fixed, forcing manufacturers to balance compliance against mouthfeel retention.
- White Chocolate:Cocoa butter-based formulations without cocoa solids face margin pressure from volatile West African supply chains.
- Ruby Chocolate:Barry Callebaut's pink-hued variety creates visual differentiation for Valentine's and Chuseok seasonal packaging.
Dark chocolate holds the largest share; momentum sits with ruby chocolate.
End User:
Cost tier stratification separates mass-market retail from premium food service procurement, with bulk buyers commanding volume discounts unavailable to boutique channels.
- Retail Consumers:Young adult gift buyers in Seoul's Hongdae district rotate toward bean-to-bar tasting sets with origin-story packaging, displacing conventional boxed assortments at department stores.
- Food Service:Bakery and beverage ingredient applications demand consistent cocoa butter ratios for tempering stability in commercial kitchen environments.
- Confectionery Manufacturers:Snack-coated chocolate hybrid production concentrates among domestic industrial players serving convenience store distribution.
- Bulk Buyers:Corporate gift procurement through subscription models captures fastest channel expansion via curated monthly clubs.
Retail consumers dominate volume; food service commands the steepest expansion trajectory.
Packaging Type:
Application-driven selection separates impulse convenience formats from occasion-gifting presentation tiers, with MFDS allergen disclosure requirements reshaping label real estate across all formats.
- Boxes:Premium gifting formats in Seongsu-dong boutiques emphasize origin documentaries and maker profiles through QR-linked packaging experiences.
- Individual Wrappers:Single-serve portions dominate convenience store shelf placement for snack-coated hybrids targeting commuter impulse purchases.
- Bags:Share-size formats capture family consumption occasions in premium supermarket channels.
- Bulk Containers:Food service and manufacturing procurement relies on cocoa mass stability during extended storage periods.
Boxes retain the largest share; individual wrappers are climbing the fastest.
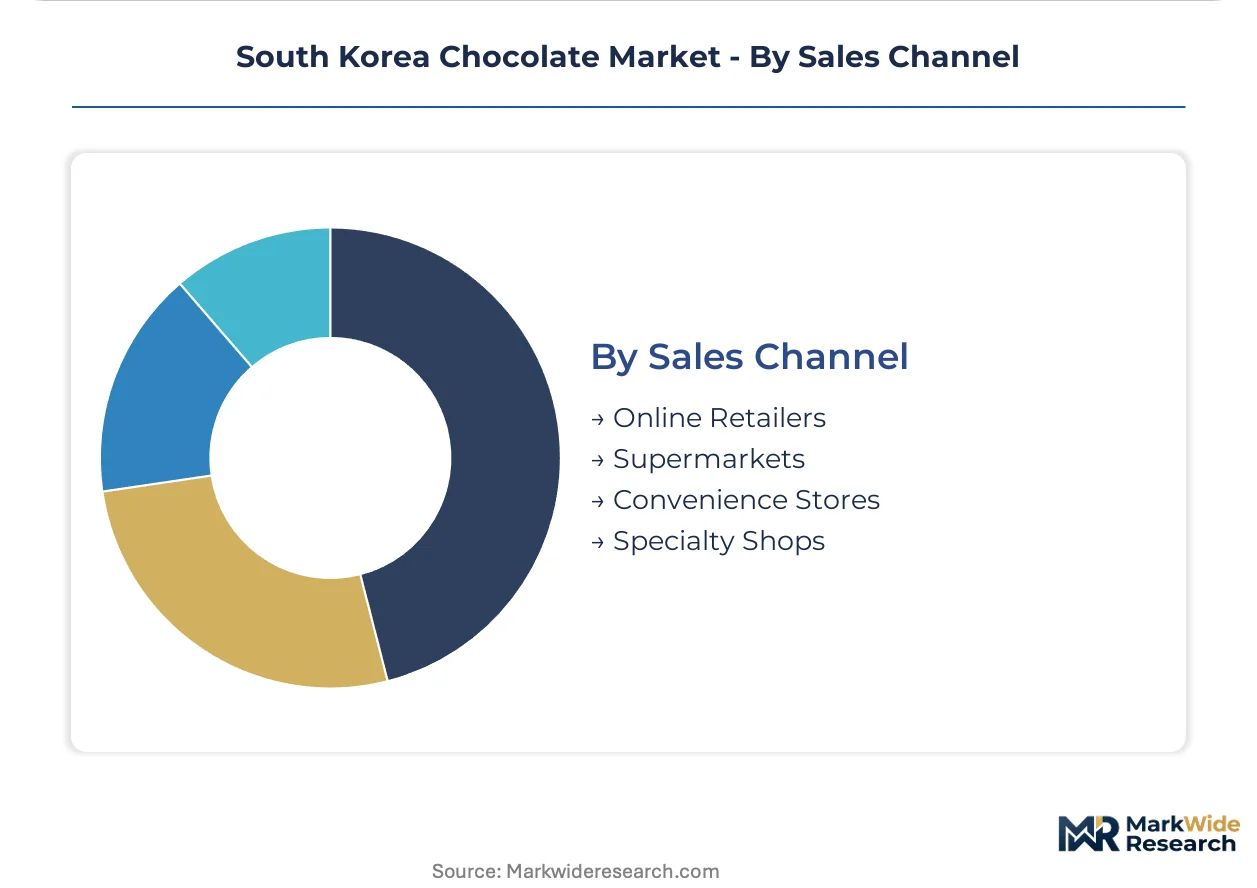
Sales Channel:
Geographic concentration in Seoul's central districts fragments between digital discovery platforms and physical retail corridors, with Incheon International Airport offering underpenetrated transit retail access.
- Online Retailers:Subscription gifting models and boutique e-commerce sites displace department store confectionery halls as primary research channels for premium bean-to-bar selections.
- Specialty Shops:Seongsu-dong and Gangnam ateliers featuring precision conching equipment with real-time particle size monitoring signal quality to discerning buyers.
- Convenience Stores:Impulse placement dominates snack-coated chocolate hybrid volume through Orion and Lotte Wellfood distribution networks.
- Supermarkets:Premium channels in Seoul's affluent districts curate seasonal displays for Chuseok and Valentine's occasion purchasing.
Convenience stores lead volume; online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Incheon International Airport's transit retail corridors anchor South Korea's chocolate export visibility, channeling premium Korean confectionery toward Chinese and Southeast Asian tourist segments seeking duty-free souvenirs.
Seoul Capital Area
Gangnam district specialty boutiques and Seongsu-dong craft ateliers drive premium bean-to-bar demand through origin-story packaging and precision conching demonstrations. MFDS labeling mandates for cocoa content transparency reshape formulation standards for domestic producers headquartered in the metropolitan core. Hongdae's young adult gift buyers rotate toward experiential tasting sets, displacing conventional department store assortments.
Busan-Ulsan
Industrial-scale confectionery manufacturing clusters around Busan's port infrastructure, facilitating cocoa butter import logistics from West African supply chains. The Korea Free Trade Agreement tariff structures lower landed costs for European specialty ingredients entering through this southeastern gateway. Orion Confectionery's snack-coated hybrid production concentrates here, serving convenience store distribution networks nationwide.
Daegu-Gyeongbuk
Regional food service procurement for bakery and beverage ingredient applications concentrates in this southeastern manufacturing belt. Local wholesalers command volume discounts unavailable to boutique retail channels in Seoul. Sugar reduction guidelines from the Korea Food & Drug Safety Ministry constrain reformulation options for milk chocolate segments serving institutional buyers.
Daejeon-Sejong
Government administrative concentration in Sejong drives corporate gift procurement through subscription chocolate clubs targeting public sector milestone occasions. Regulatory oversight functions for MFDS compliance and food safety audits operate from this central administrative hub. Clean-label R&D investment redirects toward allergen disclosure precision and packaging redesign requirements.
Gwangju-Honam
Agricultural processing infrastructure in the southwestern Honam region supports domestic cocoa butter refinement and confectionery ingredient supply chains. Regional distribution networks extend toward Jeju Island's tourism-dependent retail corridors. Ruby chocolate visual differentiation strategies target seasonal Valentine's and Chuseok packaging for this culturally distinct consumer base.
South Korea Chocolate Market Competitive Environment
Listed leaders compete with private specialists across retail and duty-free distribution channels, creating a tiered structure where scale-driven conglomerates anchor mass-market volume while craft producers capture premium pricing through terroir narratives. Three strategic archetypes dominate: integrated confectionery conglomerates with captive retail networks, European-imported premium gifting specialists, and domestic craft bean-to-bar ateliers. Competitive moves concentrate on subscription gifting model expansion and precision processing technology licensing.
Within the integrated conglomerate tier, Lotte Wellfood Co., Ltd. and Orion Confectionery Co., Ltd. exemplify scale-driven positioning through entrenched convenience store and duty-free distribution networks. Ferrero International S.A. occupies a position representing European-imported premium gifting archetypes. These three entities anchor the competitive spectrum from mass-market impulse placement to curated seasonal assortment positioning.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Haitai Confectionery & Foods Co., Ltd. |
| Lotte Wellfood Co., Ltd. |
| Meiji Holdings Co., Ltd. |
| Mondelez International, Inc. |
| Orion Confectionery Co., Ltd. |
| Ferrero International S.A. |
| Hershey Korea Co., Ltd. |
| Crown Confectionery Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Scale economies in cocoa butter refining anchor price floors for domestic manufacturers, compressing margins for mid-tier producers while concentrating procurement leverage among integrated conglomerates with captive West African sourcing networks. Capacity utilization at Busan's port infrastructure directly shapes landed cost predictability, feeding back into subscription pricing models and premium tier positioning.
Pricing Analysis
Volume-discount tiering structures separate corporate subscription procurement from boutique retail markups, with bulk buyers commanding 30-40% differentials unavailable to Seongsu-dong craft ateliers. Price differentiation hinges on cocoa percentage certification and MFDS compliance tiering, where allergen disclosure precision adds packaging cost premiums. Cost compression in milk chocolate segments intensifies as sugar reduction mandates constrain formulation flexibility. Convenience store impulse buyers exhibit highest price sensitivity, while duty-free tourist segments absorb premium positioning without volume erosion.
Supply Chain Analysis
Inventory lead times for West African cocoa butter shipments extend 45-60 days through Busan port clearance, compressing working capital cycles for domestic processors. Supply concentration centers on Côte d'Ivoire, Ghana, and Indonesia for bean sourcing, with European specialty ingredient channels feeding premium tier formulation. Raw material dependencies span cocoa butter, cane sugar, and soy lecithin replacements for clean-label lines. Single-source vulnerability in West African bean procurement exposes margins to currency fluctuation against the Korean won. Distribution runs through Lotte and Orion captive retail networks, convenience store franchise systems, and emerging direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized confectionery technologist scarcity constrains craft sector scaling, creating acquisition premiums for European-trained Korean chocolatiers and precision processing equipment operators. This capability gap rewards early investment in bean-to-bar roasting expertise and tempering precision training pipelines.
For Market Incumbents: Fortify position by acquiring precision conching technology licenses and locking exclusive distribution through Incheon duty-free corridors before craft producers scale. Threats from subscription gifting platforms erode department store volume; channel control through captive online retail infrastructure is the critical defensive lever. Backward integration into cocoa butter refining secures margin predictability against West African supply volatility. For New Entrants and Emerging Players: Lead with ruby chocolate visual differentiation targeting Chuseok and Valentine's seasonal packaging white space, where incumbent innovation cycles lag 18-24 months. The most penetrable segment sits in corporate gift procurement through curated monthly clubs, bypassing established retail gatekeepers. A direct-to-consumer origin documentary content strategy builds terroir credibility without physical boutique overhead. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision equipment-enabled craft ateliers with scalable subscription infrastructure over capital-heavy industrial conglomerates. Long-term viability hinges on clean-label reformulation capability and MFDS compliance automation. Acquisition targets should demonstrate sub-20-micron fineness consistency and direct-trade sourcing relationships. The signal to watch is MFDS enforcement intensity on expanded allergen warnings, which would accelerate consolidation among sub-scale domestic producers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Conching Technology Licensing | Sub-20-micron fineness consistency signals quality to Gangnam gift buyers and compresses quality variance. |
| Subscription Gifting Platform Launch | Curated monthly clubs displace department store confectionery halls among millennial corporate procurement officers. |
| Ruby Chocolate Seasonal Line Extension | Barry Callebaut's pink-hued variety creates visual differentiation for Valentine's and Chuseok packaging tiers. |
| Backward Integration into Cocoa Butter Refining | Busan port infrastructure utilization secures margin predictability against West African currency volatility. |
| Clean-Label Reformulation Investment | MFDS allergen disclosure mandates extend NPD timelines; early compliance captures premium positioning. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with bean-to-bar chocolatiers, convenience store category buyers, corporate gift procurement managers, and MFDS regulatory affairs specialists; and secondary validation through Korea Customs Service import records, MFDS food labeling guidance documents, and Nielsen retail audit data for Seoul metropolitan channels. Bottom-up triangulation across specialty shop revenue estimates and top-down reconciliation against industrial production volumes anchored segmentation sizing.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, end-user archetype, packaging format, and sales channel dimensions. CAGRs were derived from elasticity-adjusted volume projections incorporating cocoa butter price volatility assumptions and KFTA tariff structure evolution. Industry-specific inputs included MFDS enforcement intensity scenarios and subscription service adoption curves among millennial gift buyers.
The analysis sits within stated boundaries; outcomes outside sustained premium gifting culture expansion or MFDS regulatory stability would require recalibration. Forecasts reflect documented assumptions on West African supply chain continuity and Korean won exchange rate bands. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Global Industrial Chocolate Market
Confectionery
Global Mochi Market
Confectionery
South Africa Confectionery Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Low-Fat Candy Market
Confectionery
Durian Chocolate Market
Confectionery
Real and Compound Chocolate Market
Confectionery
UK Compound Chocolate Market
Confectionery
Gummy Market
Confectionery
Licorice Candy Market
Confectionery
Bangladesh Candy Market
Confectionery
Salted Caramel Products Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Gum Base Candy Market
Confectionery
US Dark Chocolate Market
Confectionery
North America Premium Chocolate Market