
 South America Chocolate Market | 2026-2036
South America Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
South America Chocolate Market Analytics
Food service procurement is collapsing toward artisanal and single-origin offerings as hotel chains and café networks upgrade dessert menus. Arcor leverages its Argentine sugar-to-chocolate vertical integration to dominate mass-market distribution across the Southern Cone. Mondelēz International sustains manufacturing scale through its Brazilian production complex, while Grupo Nutresa anchors Andean supply with Medellín-based cocoa processing. Cacau Show differentiates through Brazil's largest specialty retail footprint.
South America chocolate encompasses cocoa-based confectionery manufactured from fermented, dried, roasted, and ground Theobroma cacao beans, typically containing 10-70% cocoa solids depending on product classification. The category serves retail consumption, industrial ingredient supply, and hospitality food service applications. Milk chocolate occupies the largest revenue pool across Brazilian and Argentine retail channels, while dark chocolate registers the fastest structural expansion driven by cocoa percentage claims and reduced sugar positioning. Online retail distribution is accelerating fastest among channels, though supermarkets retain the dominant transaction volume.
ANVISA governs food safety standards and allergen labeling across Brazil, while Argentina's national food regulator enforces Mercosur-aligned additive restrictions; both frameworks elevate compliance costs for imported formulations. The EU Deforestation Regulation indirectly shapes market access by requiring geolocated cocoa traceability for any European-bound exports. Stakeholders must monitor how forthcoming Mercosur-EU trade ratification affects tariff structures on processed chocolate versus bean imports.
Market Dynamics
ANVISA's updated food labeling regulations are tightening ingredient disclosure requirements and reshaping formulation strategies across Brazilian manufacturing. This regulatory pressure cascades through the supply chain, forcing reformulation investments and traceability upgrades that alter competitive positioning between domestic and imported brands.
Growth Catalysts
- Premium food service adoption:Hotel chains and café networks across São Paulo and Rio de Janeiro are upgrading dessert menus with artisanal and single-origin chocolate offerings, creating pull-through demand for higher-cocoa formulations.
- Mercosur-EU trade trajectory:Pending ratification of the Mercosur-EU agreement is generating investment anticipation around tariff restructuring for processed chocolate versus bean imports.
- Dark chocolate positioning:Cocoa percentage claims and reduced sugar formulations are capturing health-conscious consumers in Argentine and Brazilian retail channels, expanding the addressable premium segment.
Market Restraints
- Cocoa price volatility:Input cost instability for fermented cacao beans concentrates risk in West African supply origins, compressing margin predictability for processors lacking long-term purchase contracts.
- EU Deforestation Regulation compliance:Geolocated traceability mandates for European-bound exports impose documentation burdens that disadvantage smaller South American processors without integrated farm networks.
- Regulatory fragmentation:Divergent allergen labeling standards between ANVISA and Argentina's national food regulator elevate compliance costs for cross-border formulations.
Strategic Opportunities
- Colombian market underpenetration:Medellín-based cocoa processing infrastructure anchors Andean supply, but branded retail penetration in Bogotá and Cali remains below Brazilian saturation levels.
- Online channel acceleration:E-commerce distribution is expanding fastest among channels, offering direct-to-consumer pathways that bypass supermarket slotting fee structures.
- Single-origin certification convergence:Geographic indication protocols combined with organic certification are creating premium tier differentiation for Ecuadorian and Peruvian cacao sourcing.
Industry Challenges
- Traceability system integration:Legacy batch tracking infrastructure requires capital-intensive upgrades to meet ANVISA's serialized disclosure mandates and EU Deforestation Regulation geolocation requirements.
- Specialized fermentation expertise:Scarcity of technicians trained in controlled fermentation protocols for flavor profile consistency constrains quality scaling at mid-sized processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Chocolate Market |
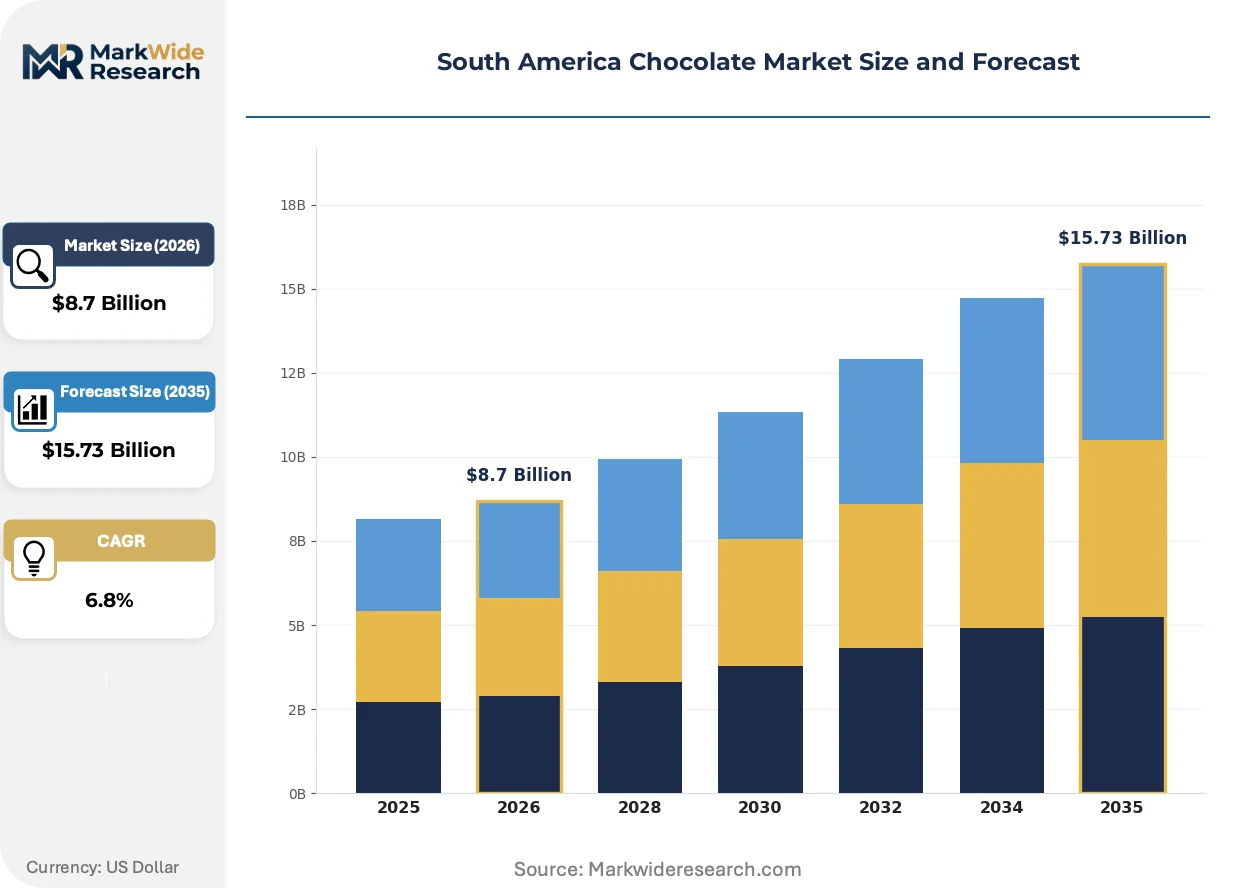
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Form: Bars, Bites, Truffles, Coated End User: Retail, Food Service, Manufacturing, Wholesale Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores |
| Companies Covered | Arcor, Mondelēz International, Nestlé, Mars, Ferrero International, Grupo Nutresa, Cacau Show, Barry Callebaut, The Hershey Co., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Chocolate Market Evolving Landscape
Bean-to-bar processing technology is reshaping competitive dynamics by enabling smaller-scale producers to bypass traditional industrial chocolate manufacturing infrastructure. This shift fragments supply concentration and creates new entry pathways outside established Southern Cone distribution networks.
Cold-pressing cocoa butter extraction is displacing conventional high-temperature processing in premium segment manufacturing. Artisanal producers in São Paulo's specialty corridor are adopting this method to preserve volatile aromatic compounds. The technology is compressing batch sizes and enabling flavor differentiation that mass-market thermal processing cannot replicate.
ANVISA's front-of-pack warning label requirements are forcing reformulation across milk chocolate portfolios. Manufacturers must reduce sugar content or accept prominent disclosure placement that alters shelf appeal. Brazilian retail channels are responding with accelerated private-label development featuring simplified ingredient statements.
Specialty retail footprint expansion is concentrating consumer education and tasting experiences in physical locations. Cacau Show's network demonstrates how controlled environment retail is displacing traditional supermarket impulse purchasing for gift and premium occasions. This channel shift is most visible in Brazil's southeastern manufacturing corridor where disposable income concentration supports experiential formats.
South America Chocolate Market Segmentation
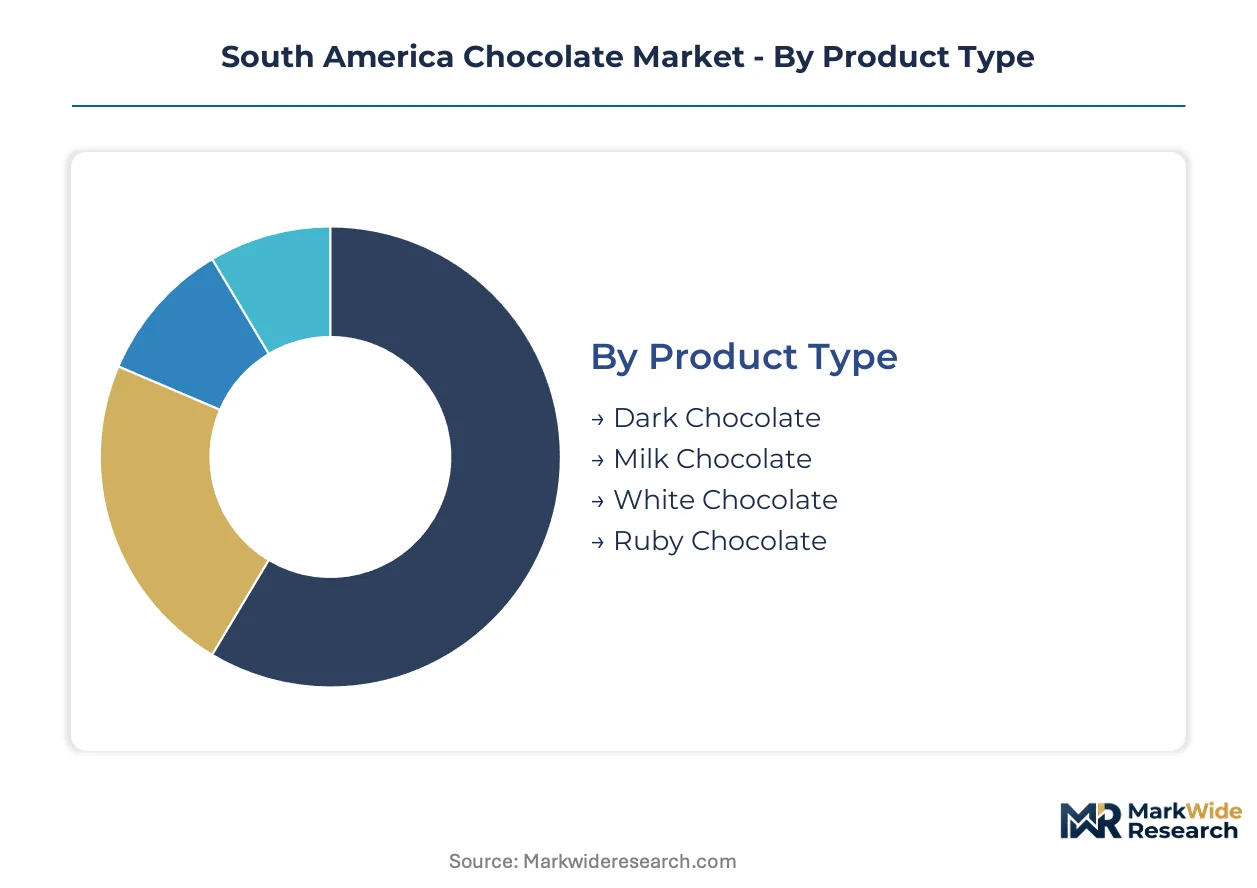
Segmentation in South America's chocolate market reveals how formulation choices, consumption occasions, and channel strategies fragment competitive positioning. Each dimension carries distinct margin profiles and regulatory exposure that reshape investment priorities across Brazilian, Argentine, and Colombian manufacturing corridors.
Product Type:
Milk chocolate faces the most acute substitution pressure from reduced-sugar dark formulations as ANVISA's front-of-pack warning labels alter consumer calculus.
- Dark Chocolate:Cocoa solids content ranging from 50-90% defines this category, with single-origin and high-percentage claims commanding premium shelf positioning. Brazilian retail channels in São Paulo's southeastern corridor are concentrating demand for 70%+ formulations driven by health-conscious positioning and reduced sugar disclosure requirements.
- Milk Chocolate:Standard 10-50% cocoa solids combined with milk powder or condensed milk dominates mass-market volume. Argentine supermarket chains and Brazilian wholesale clubs anchor consumption, though reformulation pressures from ANVISA's labeling mandates are compressing margins for traditional high-sugar recipes.
- White Chocolate:Cocoa butter base without cocoa solids serves confectionery applications and dessert manufacturing. Colombian processing facilities supply regional food service operators seeking consistent fat bloom resistance.
- Ruby Chocolate:Pink-hued formulation from specific cacao varietals offers color differentiation for gift and premium segments. Limited production scale constrains penetration beyond specialty retail in Rio de Janeiro and Buenos Aires corridors.
Milk chocolate retains volume leadership; dark chocolate holds the steepest expansion curve.
Form:
Cost tier stratification runs deepest here, with bite-sized formats capturing impulse volume while bars anchor planned purchasing.
- Bars:Standard molded tablets from 20g to 100g+ serve retail pantry stocking and premium gifting occasions. Brazilian supermarkets and Argentine hypermarkets concentrate volume, though single-origin bean-to-bar producers in São Paulo's specialty corridor are fragmenting brand loyalty through flavor differentiation.
- Bites:Individual portion formats target checkout lane impulse and portion-controlled consumption. Convenience store networks across Colombia's Andean cities and Brazilian urban centers are expanding SKU density for this format.
- Truffles:Ganache-centered enrobed pieces dominate premium gifting and food service dessert applications. Cacau Show's controlled-environment retail footprint anchors Brazilian demand for artisanal truffle assortments.
- Coated:Chocolate-enrobed nuts, fruits, and confections serve industrial ingredient and seasonal gifting markets. Argentine sugar-to-chocolate integrated processors leverage cost advantages in this commoditized segment.
Bars retain volume leadership; bites hold the steepest expansion curve.
End User:
Application-driven demand divergence separates commodity ingredient buyers from experience-oriented food service procurement.
- Retail:Direct consumer purchase through supermarkets, specialty stores, and online channels. Brazilian southeastern manufacturing corridor households and Argentine urban centers concentrate premium retail experimentation with single-origin and organic certifications.
- Food Service:Hotel chains, café networks, and restaurant dessert menus drive artisanal and high-cocoa formulation demand. São Paulo and Rio de Janeiro hospitality upgrades are pulling through specialty chocolate procurement at premium price points.
- Manufacturing:Industrial ingredient supply for bakery, dairy, and confectionery processing. Colombian cocoa processing infrastructure in Medellín anchors Andean supply for regional manufacturing customers.
- Wholesale:Bulk distribution to institutional buyers and secondary retailers. Price-sensitive volume procurement in this segment favors Argentine and Brazilian mass-market producers with scale economies.
Retail retains volume leadership; food service holds the steepest expansion curve.
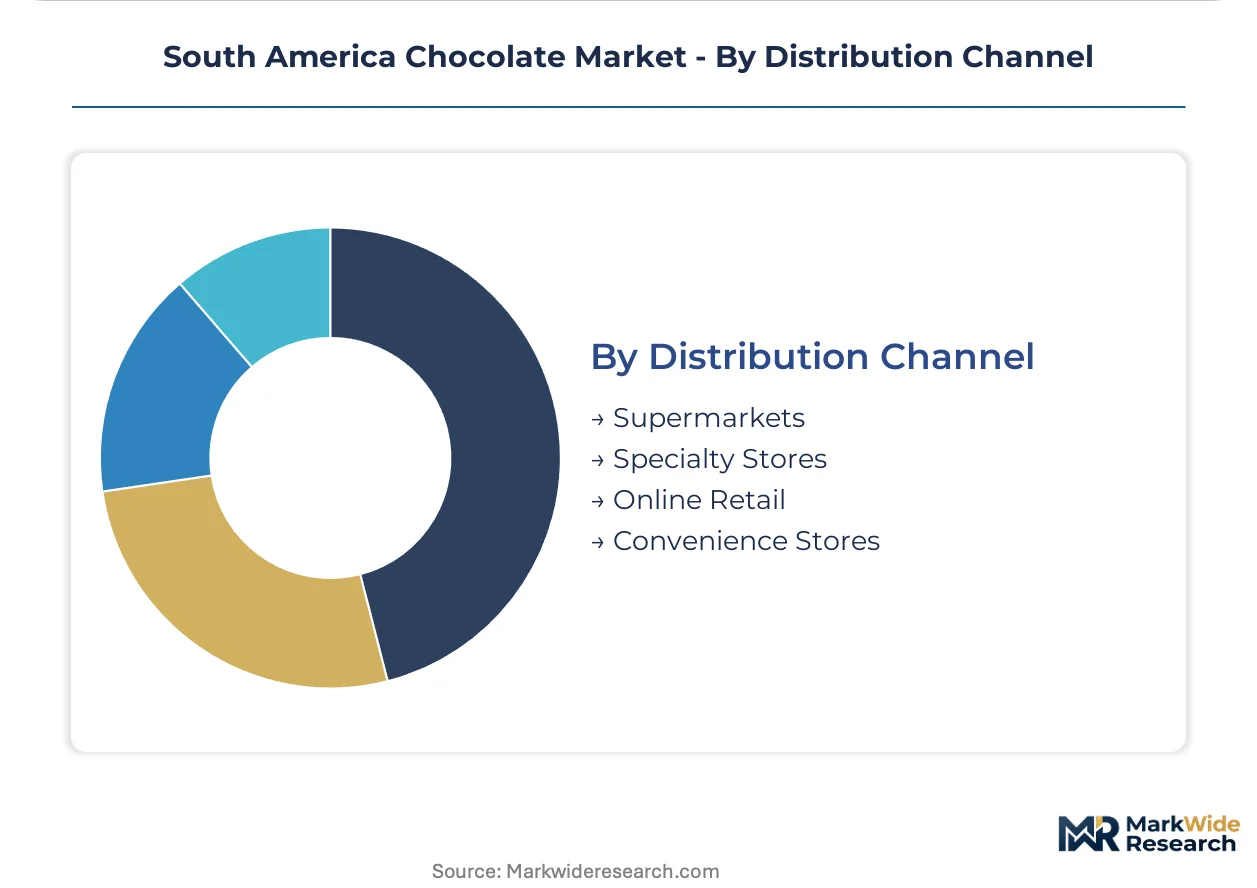
Distribution Channel:
Channel maturity varies sharply, with legacy supermarket dominance eroding fastest where digital infrastructure penetrates.
- Supermarkets:Hypermarket and supermarket chains retain dominant transaction volume across Brazilian and Argentine retail. Slotting fee structures and planogram control favor established brands with marketing budgets, though private-label development is accelerating under ANVISA's simplified ingredient disclosure incentives.
- Specialty Stores:Controlled-environment retail with tasting and education components targets gift and premium occasions. Cacau Show's Brazilian network demonstrates how experiential formats displace impulse purchasing for higher-margin transactions.
- Online Retail:Direct-to-consumer and marketplace platforms bypass traditional distribution markups. Brazilian e-commerce penetration is expanding fastest among channels, enabling subscription models and limited-batch releases from bean-to-bar producers.
- Convenience Stores:Small-format urban retail targets immediate consumption and impulse replacement. Colombian and Argentine urban density supports this channel's bite-sized and single-serve format concentration.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports processed chocolate formulations to European Union markets under tightening traceability mandates, while Argentine processors supply Mercosur partners through integrated sugar-cocoa infrastructure. Colombian bean exports to North American craft chocolate makers are expanding alongside domestic processing investments.
Brazil
São Paulo's southeastern manufacturing corridor concentrates premium food service demand as hotel chains and café networks upgrade dessert menus. ANVISA's front-of-pack warning label requirements are forcing sugar reduction across milk chocolate portfolios. Cacau Show's specialty retail footprint in Rio de Janeiro and Belo Horizonte is displacing supermarket impulse purchasing for gift occasions.
Argentina
Buenos Aires anchors mass-market consumption through hypermarket chains and wholesale club networks serving price-sensitive households. The national food regulator enforces Mercosur-aligned additive restrictions that elevate compliance costs for imported formulations. Arcor's integrated sugar-to-chocolate operations in the Litoral region dominate Southern Cone distribution through captive supply chains.
Colombia
Bogotá and Cali present underpenetrated branded retail opportunities relative to Brazilian saturation levels. Medellín-based cocoa processing infrastructure anchors Andean supply for regional manufacturing customers. The country's national food regulator is aligning traceability standards with EU Deforestation Regulation requirements for European-bound bean exports.
Peru
Lima's specialty food sector is pulling through single-origin and organic certified cacao from Amazonian and coastal growing regions. Geographic indication protocols combined with organic certification are creating premium tier differentiation for export markets. Arequipa's emerging craft chocolate cluster is fragmenting brand loyalty through flavor differentiation unavailable from mass-market processors.
Ecuador
Guayaquil serves as the primary export corridor for Arriba nacional cacao varietals to European and North American premium buyers. The central agricultural authority maintains strict genetic purity standards for denomination of origin protection. Quito-based artisanal producers are leveraging bean-to-bar processing technology to bypass traditional industrial manufacturing infrastructure.
South America Chocolate Market Competitive Landscape
Listed leaders compete with private specialists across formulation tiers and channel access. The market structure consolidates around three to five multinational corporations with Brazilian manufacturing complexes, while fragmented bean-to-bar producers fragment premium segment loyalty. Strategic archetypes include integrated agricultural processors, scale-driven confectionery conglomerates, and specialty retail network operators. Dominant competitive moves center on backward integration into fermentation infrastructure and direct-to-consumer channel development.
Within the integrated processing tier, Arcor and Grupo Nutresa exemplify agricultural-to-retail control structures. Arcor occupies a position representing Southern Cone mass-market dominance through sugar-cocoa vertical integration. Grupo Nutresa anchors Andean supply concentration from its Medellín base. Among specialty retail specialists, Cacau Show represents experiential format expansion that displaces traditional supermarket transactions for premium and gift occasions.
| Leading Market Players |
|---|
| Arcor |
| Mondelēz International |
| Nestlé |
| Mars |
| Ferrero International |
| Grupo Nutresa |
| Cacau Show |
| Barry Callebaut |
| The Hershey Co. |
| Others |
Value Network & Pricing Analysis
EU Deforestation Regulation geolocation mandates gate both supply qualification and price differentiation simultaneously, forcing traceability investments that stratify processor tiers while compressing margins for non-compliant operators unable to pass documentation costs downstream.
Pricing Analysis
Bean-to-bar processing technology widens the pricing gap between artisanal micro-producers and industrial thermal processors. Three-tier pricing structure across premium single-origin, standard mass-market, and economy private-label levels dominates Brazilian and Argentine retail. Price differentiation hinges on cocoa percentage certification and organic origin claims. Cost compression in milk chocolate intensifies because ANVISA's front-of-pack sugar warnings erode shelf appeal for traditional formulations. Food service buyers exhibit lowest price sensitivity; wholesale club procurement shows highest.
Supply Chain Analysis
Fermented cacao bean inventories carry 4-6 month lead times from West African and Ecuadorian origins to Brazilian processing facilities. Supply concentrates in Ghana, Côte d'Ivoire, and Ecuador for bean inputs; Brazil, Argentina, and Colombia for regional processing. Mid-sized processors depend on spot market purchases for 30-40% of bean requirements. Single-source vulnerability in West African supply origins exposes margin predictability to weather-driven crop failures. Distribution runs through supermarket chain procurement offices for retail volume; direct-to-consumer platforms bypass traditional markups for premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's serialized disclosure mandates and EU Deforestation Regulation traceability requirements are disrupting established supply relationships, creating acquisition opportunities for processors with integrated farm networks and compliant documentation systems.
For Market Incumbents: Consolidate fermentation infrastructure investments in Brazil's southeastern corridor to defend against bean-to-bar entrants fragmenting premium loyalty. Lock long-term purchase contracts with Ecuadorian Arriba nacional cooperatives before Mercosur-EU tariff restructuring alters relative input costs. Channel control through captive specialty retail networks represents the priority defensive lever.
For New Entrants and Emerging Players: Lead with Colombian branded retail penetration in Bogotá and Cali, where Brazilian saturation levels have not yet materialized. Cold-pressing cocoa butter extraction technology offers white-space differentiation in São Paulo's specialty corridor. Direct-to-consumer subscription models bypass supermarket slotting fee structures entirely.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across traceability-compliant processing infrastructure, favoring scaled operators over fragmented mid-tier facilities. Long-term viability over a 5-10 year window rests on backward integration into controlled fermentation protocols. Acquisition targets should display integrated farm networks or established EU export documentation systems. The signal to watch is Mercosur-EU ratification timing and its tariff restructuring impact on processed chocolate versus bean import economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Controlled fermentation protocols at Arcor's Litoral facilities secure flavor consistency for premium positioning. |
| Direct-to-Consumer Channel Launch | Cacau Show's experiential retail network displaces supermarket impulse purchasing for gift occasion volume. |
| Sustainability Repositioning | Geographic indication protocols combined with organic certification create premium tier differentiation for Peruvian cacao. |
| Long-term Supply Agreement | Grupo Nutresa's Medellín-based cocoa processing anchors Andean manufacturing customer relationships. |
| Regulatory Compliance Investment | ANVISA's serialized disclosure mandates force capital-intensive traceability upgrades at mid-sized Brazilian processors. |
Research Methodology
The analysis maps dark chocolate, milk chocolate, white chocolate, and ruby chocolate sub-sectors, each validated through procurement directors at Brazilian supermarket chains, Argentine wholesale club buyers, Colombian food service operators, and Ecuadorian cooperative export managers. Primary interviews with fermentation technicians, specialty retail category heads, and cocoa processing plant engineers combined with secondary validation from ANVISA regulatory filings, Mercosur trade databases, EU Deforestation Regulation implementation guidance, and customs export records. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Consistency checks validated outputs against external benchmarks including regional cocoa grind statistics and chocolate confectionery trade flows across the analysis window. Segmentation dimensions modeled include product type, form, end user application, and distribution channel complexity. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points. Forecast inputs incorporated cocoa futures price volatility bands and ANVISA compliance cost assumptions.
The analysis sits within stated boundaries; outcomes outside Mercosur-EU ratification, sustained cocoa price stability, or unchanged ANVISA disclosure timelines would require recalibration. Forecasts reflect documented assumptions around traceability technology adoption curves and premium segment elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar-Free Chocolate Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Sugar Confectionery Market
Confectionery
Ice Cream Coating Market
Confectionery
North America Sugar Confectionery Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Caramel Chocolate Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Gummy Candy Market
Confectionery
Sugar Free Candy Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Global Compound Chocolate Market
Confectionery
Europe Chocolate Market