
 Gummy Market | 2026-2036
Gummy Market Size, Share, and Industry Trends Forecast 2026-2036
Gummy Market Intelligence
NSF International certification for dietary supplements is unwinding the traditional separation between confectionery and nutraceutical categories. Legacy confectionery giant Haribo GmbH & Co. KG competes by leveraging its global brand recognition and distribution scale. In contrast, Bayer AG specializes in the medicated and vitamin-enriched gummy segment, focusing on clinical efficacy. Church & Dwight Co. Inc. positions its brands to capture the mainstream wellness consumer through broad retail availability.
Gummies are a category of chewable confections produced using hydrocolloids like gelatin or pectin to create a distinct elastic texture. The manufacturing process controls water activity and pH to ensure microbiological stability and a consistent chew profile, making them an effective delivery system. Functional gummies, including vitamins and CBD-infused products, represent the fastest-growing product type. The expansion of vegan gummies using plant-based gelling agents creates new market opportunities, with distribution expanding from specialty stores into mainstream supermarkets and pharmacies.
Regulatory frameworks from the U.S. FDA and Europe's EFSA dictate permissible health claims and daily dosage limits for vitamin and mineral content. In markets like India, FSSAI standards for food additives and labeling directly influence product formulation and market access for manufacturers. Stakeholders must now navigate the diverging regulatory paths for gummies classified as food versus those classified as dietary supplements or over-the-counter medicine.
Market Dynamics
The primary force shaping the gummy market is the regulatory divergence classifying products as either confectionery, dietary supplements, or medicine. This distinction dictates formulation, permissible claims, and distribution channels available to manufacturers, creating a complex strategic landscape.
Growth Catalysts
- Functional Ingredient Demand:A consumer shift towards preventative health boosts demand for gummies fortified with vitamins, probiotics, and botanical extracts for targeted wellness benefits.
- Pectin-Based Gelling Agents:The adoption of plant-based pectin instead of gelatin expands the addressable market to vegan and vegetarian consumers, aligning with broader dietary trends.
- E-commerce Channel Growth:Direct-to-consumer and online retail platforms provide brands with a low-barrier entry to reach global consumers, bypassing traditional retail gatekeepers.
Market Restraints
- Ingredient Cost Volatility:Prices for specialized inputs like high-purity pectin and specific vitamin premixes are subject to supply-demand imbalances, impacting production costs and final pricing.
- Complex Regulatory Pathways:Navigating the separate and often conflicting requirements of the FDA, EFSA, and FSSAI for health claims and dosage creates significant compliance burdens.
- Sugar Content Perception:Heightened consumer and regulatory focus on sugar reduction presents a formulation challenge, as altering sweeteners can affect the texture and taste profile that defines gummies.
Strategic Opportunities
- Personalized Nutrition Platforms:Developing subscription services that offer customized gummy formulations based on diagnostic testing or user-input health data creates a high-margin business model.
- Expansion in Southeast Asia:Markets like Vietnam and Indonesia, with their young populations and growing disposable incomes, represent a significant, underpenetrated opportunity for functional and confectionery gummies.
- OTC Drug Delivery:Formulating gummies with established over-the-counter active ingredients for indications like pain relief or sleep aids can create new product categories.
Industry Challenges
- Active Ingredient Stability:Ensuring the potency and stability of sensitive compounds like probiotics or Omega-3s through the manufacturing process and shelf life is a persistent technical hurdle.
- Dosage Accuracy at Scale:Achieving consistent, precise dosing of active ingredients in every unit during high-volume production requires significant investment in advanced manufacturing and quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gummy Market |
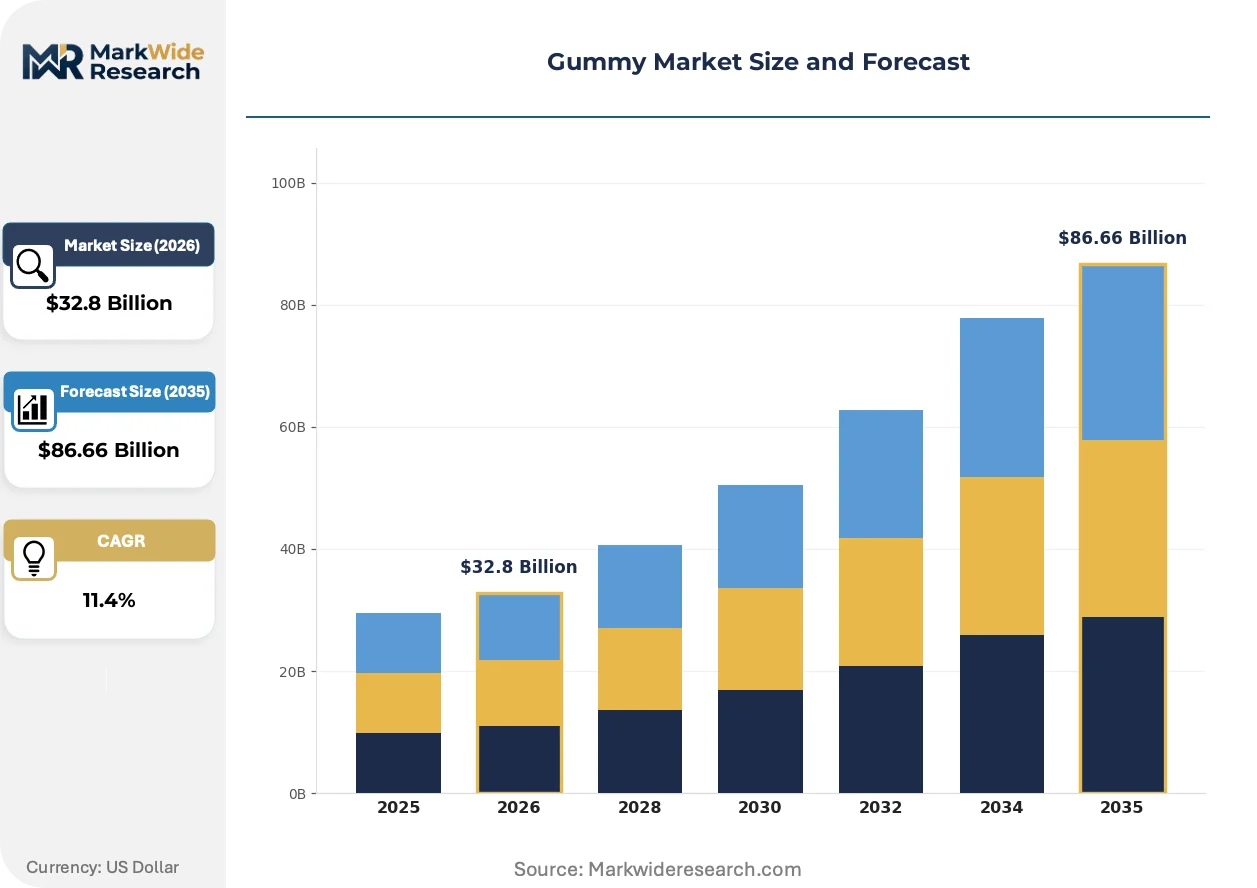
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegan Gummies, Sugar-Free Gummies, Functional Gummies, Gummy Vitamins Form: Bear-Shaped, Fruit-Flavored, Sour Gummies, CBD Gummies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Target Consumer: Health Enthusiasts, Children, Wellness Seekers, Seniors |
| Companies Covered | Haribo GmbH & Co. KG, Ferrara Candy Company, Church & Dwight Co. Inc., Bayer AG, Nestle SA, Mars Incorporated, Haleon plc, Pharmavite LLC, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gummy Market Strategic Shifts & Innovations
The gummy format’s dual identity as both a confection and a health delivery system is being refined by manufacturing and regulatory pressures. This evolution is creating distinct product tiers and go-to-market strategies for participants.
Precision dosing technology, using micro-encapsulation and automated depositing systems, ensures ingredient accuracy. Nutraceutical startups and contract manufacturers are rapidly adopting this to meet pharmaceutical-grade standards. This technology is bifurcating the market into basic, mass-produced gummies and premium, verifiably dosed functional products that command higher prices.
European Food Safety Authority (EFSA) opinions on health claims for botanicals and other novel ingredients are becoming stricter. This forces manufacturers to invest heavily in clinical data to substantiate any on-package marketing claims in the EU. Products with generic wellness claims are most affected, pushing brands towards simpler vitamin and mineral formulations with pre-approved claims.
Consumer purchasing behavior is shifting from one-off retail buys to subscription-based, direct-to-consumer (DTC) models for functional gummies. This trend disrupts traditional pharmacy and supermarket channels, allowing new brands to build direct relationships and gather valuable customer data. This DTC model is most advanced in the United States wellness market.
Gummy Market Segmentation
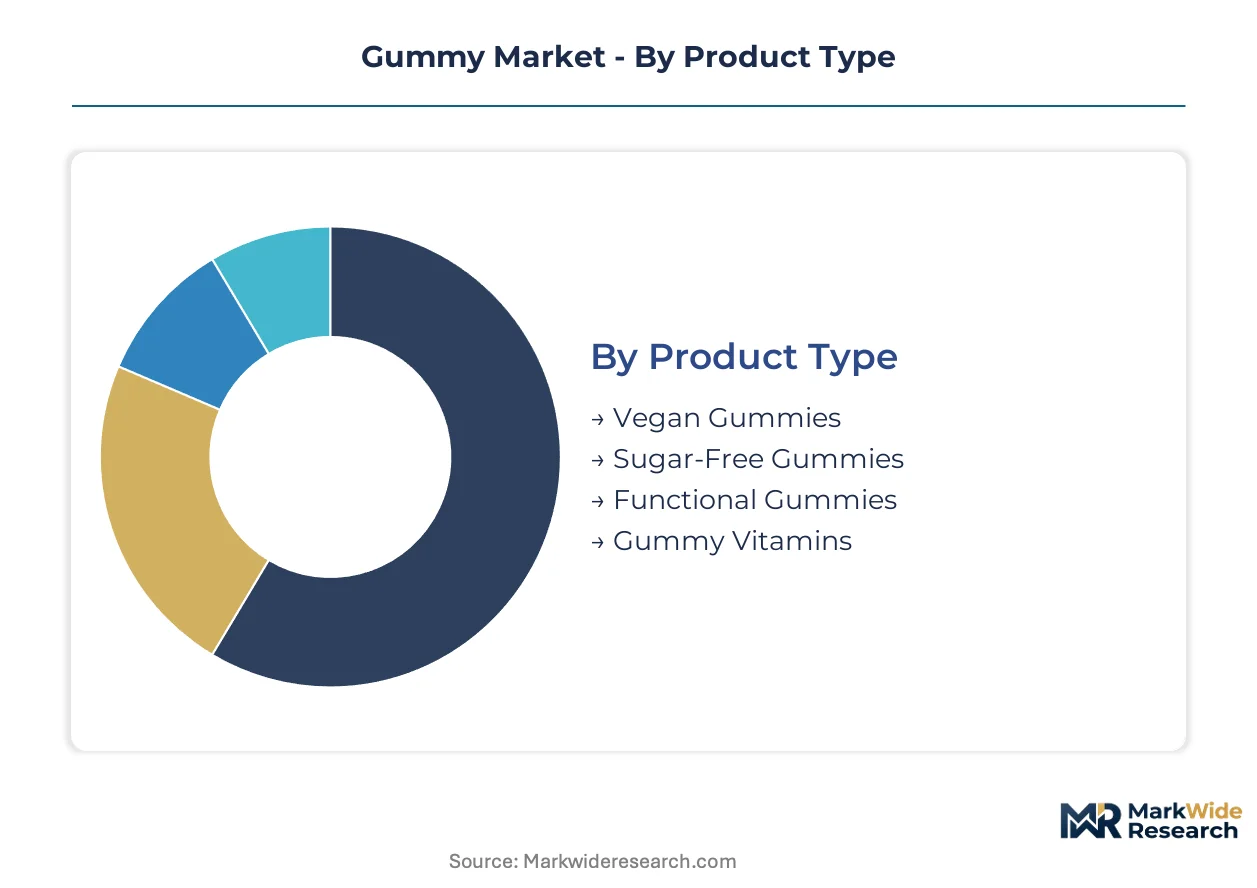
Market segmentation provides a critical framework for understanding the diverse consumer needs and operational complexities within the gummy industry. Analyzing these distinct segments allows manufacturers to tailor product development, marketing strategies, and distribution networks effectively. This granular view highlights areas of concentrated demand and emerging opportunities across different product attributes and consumer demographics.
Product Type:
Margin pools within the product type category are highest for specialized formulations addressing specific health needs and dietary preferences.
- Functional Gummies:These products incorporate active ingredients such as vitamins, probiotics, or botanical extracts to deliver targeted health benefits. Demand for these gummies is concentrating in developed markets like the United States and Germany, driven by consumer interest in preventative health and convenient supplement formats.
- Vegan Gummies:Formulated with plant-based gelling agents like pectin, these gummies appeal to consumers following vegan or vegetarian diets. The segment is expanding rapidly, particularly in European markets, as dietary preferences shift towards plant-based alternatives.
- Sugar-Free Gummies:These gummies use alternative sweeteners to reduce sugar content, catering to health-conscious consumers and those managing dietary restrictions. Regulatory bodies like the European Food Safety Authority (EFSA) scrutinize claims related to sugar reduction.
- Gummy Vitamins:Standard vitamin and mineral supplements delivered in a chewable gummy format, offering an appealing alternative to pills for various age groups. Product formulations must comply with daily dosage limits set by regulators such as the U.S. FDA.
The dominant share belongs to Gummy Vitamins, while Functional Gummies are closing the gap fastest.
Form:
This category highlights diverse consumer preferences for gummy characteristics, influencing both product appeal and manufacturing complexity.
- CBD Gummies:Infused with cannabidiol, these gummies are popular for their purported wellness benefits, though regulatory frameworks from agencies like the U.S. FDA are still evolving for these products. This segment is experiencing significant growth in North America.
- Fruit-Flavored:These gummies rely on traditional fruit essences for taste, providing broad appeal across all age groups and maintaining a strong market presence. The consistent demand spans global confectionery markets.
- Bear-Shaped:A classic and widely recognized form, bear-shaped gummies primarily target children and nostalgic adult consumers. Their simple design allows for high-volume, cost-effective production.
- Sour Gummies:Characterized by an acidic coating or flavor, sour gummies appeal to consumers seeking an intense taste experience. This niche segment maintains consistent popularity among younger demographics.
Fruit-flavored gummies maintain broad appeal, yet CBD gummies are expanding most quickly.
Distribution Channel:
Customer access points significantly influence brand visibility and sales volumes, with each channel serving distinct consumer purchasing habits.
- Online Retail:Direct-to-consumer platforms and e-commerce marketplaces provide brands with global reach and lower entry barriers. This channel enables personalized nutrition platforms and subscription services, particularly in the United States.
- Supermarkets:Mass-market grocery stores offer broad consumer access and high sales volumes for both confectionery and basic vitamin gummies. These outlets are crucial for mainstream brand positioning and impulse purchases.
- Specialty Stores:Health food stores and boutique retailers cater to consumers seeking premium, niche, or organic gummy products. These stores often provide detailed product information and cater to specific dietary needs.
- Pharmacies:Drugstores and chemists are key channels for medicated gummies and vitamin supplements, leveraging consumer trust in health-related purchases. Regulatory compliance for products sold in pharmacies is often more stringent, as dictated by bodies like Health Canada.
Supermarkets remain the primary distribution channel, with online retail gaining significant traction.
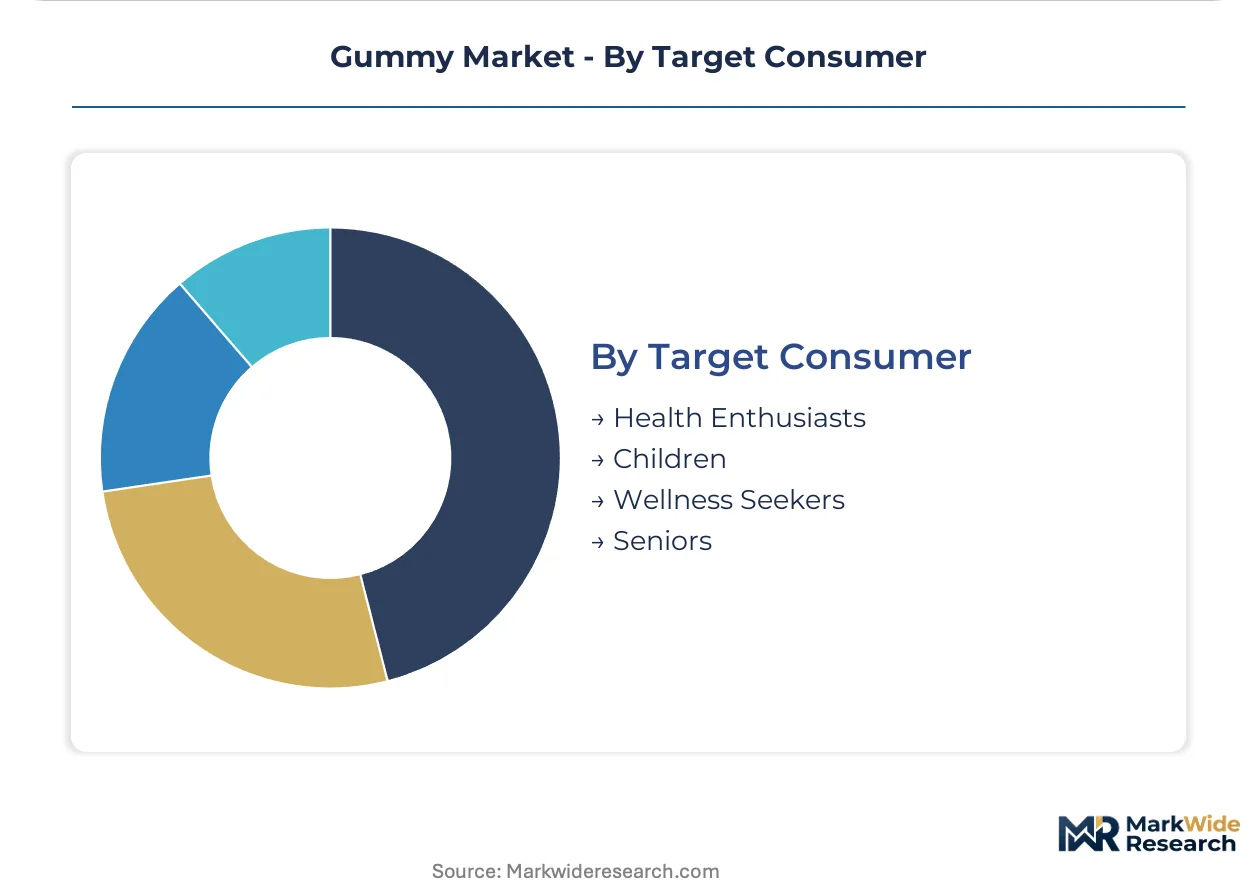
Target Consumer:
Purchasing motivations and age demographics define distinct consumer segments, guiding product innovation and marketing efforts.
- Wellness Seekers:Consumers actively pursuing health and well-being through diet and supplements, driving demand for functional and fortified gummies. This segment is particularly strong in developed economies with high health consciousness.
- Seniors:This demographic seeks convenient and palatable forms for daily essential nutrients and specific health support, often preferring gummies over traditional pills. Products target concerns like bone health and cognitive function.
- Health Enthusiasts:Individuals highly engaged in fitness and nutrition, often seeking performance-enhancing or recovery-focused gummy supplements. This group is attentive to ingredient quality and efficacy claims.
- Children:A foundational segment driven by taste and fun shapes, with parents seeking easy ways to provide vitamins and essential nutrients. Products often feature appealing flavors and characters.
Children's gummies represent a foundational segment, while wellness seekers drive current innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks profoundly shape the gummy market across diverse geographies, influencing product formulation and market access. These policy environments drive manufacturers to tailor offerings to specific health claims and consumer preferences. Regional dynamics reflect varied health consciousness and distribution channel maturity.
United States
Wellness seekers and the expanding functional gummies segment drive significant demand in the United States. The U.S. FDA dictates permissible health claims and daily dosage limits for vitamin content. California's robust nutraceutical hub sees continuous innovation in CBD-infused and personalized gummy product development.
Germany
Germany's health-conscious consumers maintain strong demand for preventative health solutions and plant-based gummies. European Food Safety Authority (EFSA) opinions on botanicals increasingly influence product claims and formulation strategies. The Rhine-Ruhr region, with its confectionery heritage, adapts production facilities for functional gummy manufacturing.
India
FSSAI standards for food additives and labeling directly influence product formulation and market access in India. Growing disposable incomes and an increasing focus on nutrition boost demand for accessible gummy formats. Mumbai and Delhi-NCR serve as key food processing hubs, driving new gummy product introductions for local markets.
Vietnam
Young populations and rising disposable incomes represent a significant, underpenetrated opportunity for functional and confectionery gummies in Vietnam. The Ministry of Health regulates food supplements and confectionery, ensuring product safety and quality. Ho Chi Minh City's expanding food manufacturing sector attracts investments in modern gummy production lines.
United Kingdom
The United Kingdom exhibits strong demand for vegan gummies and health-conscious consumer products, supported by growing online retail. The Food Standards Agency (FSA) governs food supplements and novel foods, impacting product development and market entry. London's vibrant health and wellness scene fosters the launch of new functional gummy brands.
Gummy Market Key Industry Players
Listed leaders compete with private specialists across brand recognition, distribution scale, and specialized formulations for gummy products. The market structure exhibits a tiered consolidation, where established confectionery giants coexist with agile nutraceutical startups. Strategic archetypes include legacy confectioners, pharmaceutical-backed vitamin brands, and direct-to-consumer wellness providers. Portfolio diversification into functional gummies, geographic expansion into emerging markets, and strategic partnerships for novel ingredients are dominant competitive moves.
Legacy confectionery giants like Haribo GmbH & Co. KG exemplify global brand recognition and extensive distribution networks, primarily for traditional fruit-flavored gummies. Pharmaceutical-backed entities such as Bayer AG occupy a distinct position within the medicated and vitamin-enriched gummy segment, emphasizing clinical efficacy and regulatory compliance. Church & Dwight Co. Inc. represents mainstream wellness consumers, leveraging broad retail availability and brand positioning to capture demand for dietary supplement gummies. These players collectively shape the market's diverse offerings and consumer reach.
| Leading Market Players |
|---|
| Haribo GmbH & Co. KG |
| Ferrara Candy Company |
| Church & Dwight Co. Inc. |
| Bayer AG |
| Nestle SA |
| Mars Incorporated |
| Haleon plc |
| Pharmavite LLC |
| Unilever PLC |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for specialized pectin lock in both supply access and price visibility for functional gummy manufacturers. This contract structure helps mitigate ingredient cost volatility for critical inputs, supporting stable production planning.
Pricing Analysis
NSF International certification creates the primary spread in gummy pricing, differentiating premium functional products. A hybrid model combines per-unit transactional pricing for mass-market confections with subscription tiers for personalized functional gummies. Brand premium and high-purity ingredient quality drive price differentiation. Pricing pressure stems from ingredient cost volatility, particularly for specific vitamin premixes and botanical extracts. Mainstream confectionery consumers exhibit the highest price sensitivity, while wellness seekers prioritize efficacy over cost.
Supply Chain Analysis
Inbound logistics costs for specialized vitamin premixes and botanical extracts are impacted by global trade lane efficiency. Supply concentrates in countries like China for some raw materials and Europe for high-purity pectin. Key dependencies include gelatin, pectin, and alternative sweeteners. Regulatory restrictions on certain ingredients present a significant structural risk. Distribution runs through mass-market supermarkets, e-commerce platforms, and pharmacies, each serving distinct product tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gummy market represents a high-growth disruption, driven by the regulatory inflection of diverging product classifications across regions.
For Market Incumbents: Shield core confectionery market share by diversifying into functional gummies and investing in plant-based gelling agent research and development. This counters the threat from agile nutraceutical startups. Channel control through broad retail availability and strategic partnerships remains a key lever against emerging direct-to-consumer models.
For New Entrants and Emerging Players: Lead with personalized nutrition platforms to capture health-conscious consumers in developed markets. Target the underpenetrated Southeast Asian market for functional gummies, focusing on local dietary preferences. A direct-to-consumer model offers a strong go-to-market angle, building direct customer relationships and gathering valuable data.
For Investors and Strategic Acquirers: Mid-sized nutraceutical manufacturers with strong R&D capabilities and established regulatory compliance offer attractive acquisition targets for long-term viability. Strategic acquirers should monitor evolving regulatory frameworks for CBD and novel ingredients as a key inflection signal, particularly in the United States and Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Plant-Based Gelling Agent R&D | Expands addressable market to vegan consumers, aligning with broader dietary trends. |
| Precision Dosing Technology Adoption | Ensures consistent active ingredient delivery, meeting pharmaceutical-grade standards. |
| E-commerce Channel Optimization | Provides direct access to global consumers, bypassing traditional retail gatekeepers. |
| Personalized Nutrition Platform Launch | Creates high-margin subscription models based on individual health data. |
| OTC Drug Delivery Formulation | Opens new product categories for established over-the-counter active ingredients. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade publications, and company reports. Primary interviews with R&D scientists, brand managers, regulatory affairs specialists, and procurement leads across the value chain informed market dynamics. This approach enabled bottom-up and top-down triangulation to validate market size and growth projections.
Product type, form, distribution channel, target consumer, and regional regulatory cluster define the segmentation dimensions modeled. Analytical frameworks extrapolate historical trends across the analysis window, accounting for market-specific nuances. Compound annual growth rates were derived from volume and value projections. Consumer health spending and plant-based ingredient availability serve as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant regulatory shifts or unforeseen ingredient supply disruptions would require recalibration. Forecasts reflect assumptions regarding consumer health consciousness and market access. Practitioners should keep alternative scenarios live as global trade policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
US Confectionery Market
Confectionery
Sugar Confectionery Market
Confectionery
North America Chocolate Market
Confectionery
Truffle Chocolate Market
Confectionery
UK Confectionery Market
Confectionery
Caramel Chocolate Market
Confectionery
Middle East Chocolate Market
Confectionery
Gum Base Candy Market
Confectionery
Ruby Chocolate Market
Confectionery
Brain Mint Market
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Vegan Candies Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Low Calorie Nutella Market