
 Asia-Pacific Confectionery Market | 2026-2036
Asia-Pacific Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Confectionery Market Analysis
Japan's FSSAI-aligned sugar reduction mandates is recalibrating the cost-of-entry calculus for new confectionery entrants across the Asia-Pacific region. Nestlé leverages its R&D intensity to reformulate core chocolate lines with alternative sweeteners ahead of compliance deadlines. Lotte Corporation anchors its position through backward integration into domestic cocoa processing and specialty ingredient sourcing. Mars Incorporated competes on manufacturing scale, operating multiple production facilities optimized for regional taste profiles and portion-size preferences.
Asia-Pacific confectionery encompasses chocolate, sugar-based candies, and chewing gums formulated through conching, panning, or depositing processes, typically containing cocoa mass, sucrose, glucose syrup, and emulsifiers designed for sensory appeal and shelf stability. Chocolate dominates value pools due to premiumization trends and gifting culture, while gummy candy captures the fastest growth trajectory among younger demographics seeking novel textures and functional ingredient claims. Distribution through online retail is expanding fastest as platform logistics mature, though supermarkets still control the largest volume throughput across the region.
India's FSSAI enforces labeling and additive standards that directly shape product registration timelines and reformulation costs for entrants. Japan's PMDA and METI coordinate on novel food ingredient approvals, creating a dual-track compliance environment for functional confectionery claims. China's SAMR monitors sugar content claims and advertising to minors, restricting how brands position products toward children. Stakeholders must monitor how these regulatory frameworks evolve to determine where reformulation investment yields sustainable market access versus stranded product development.
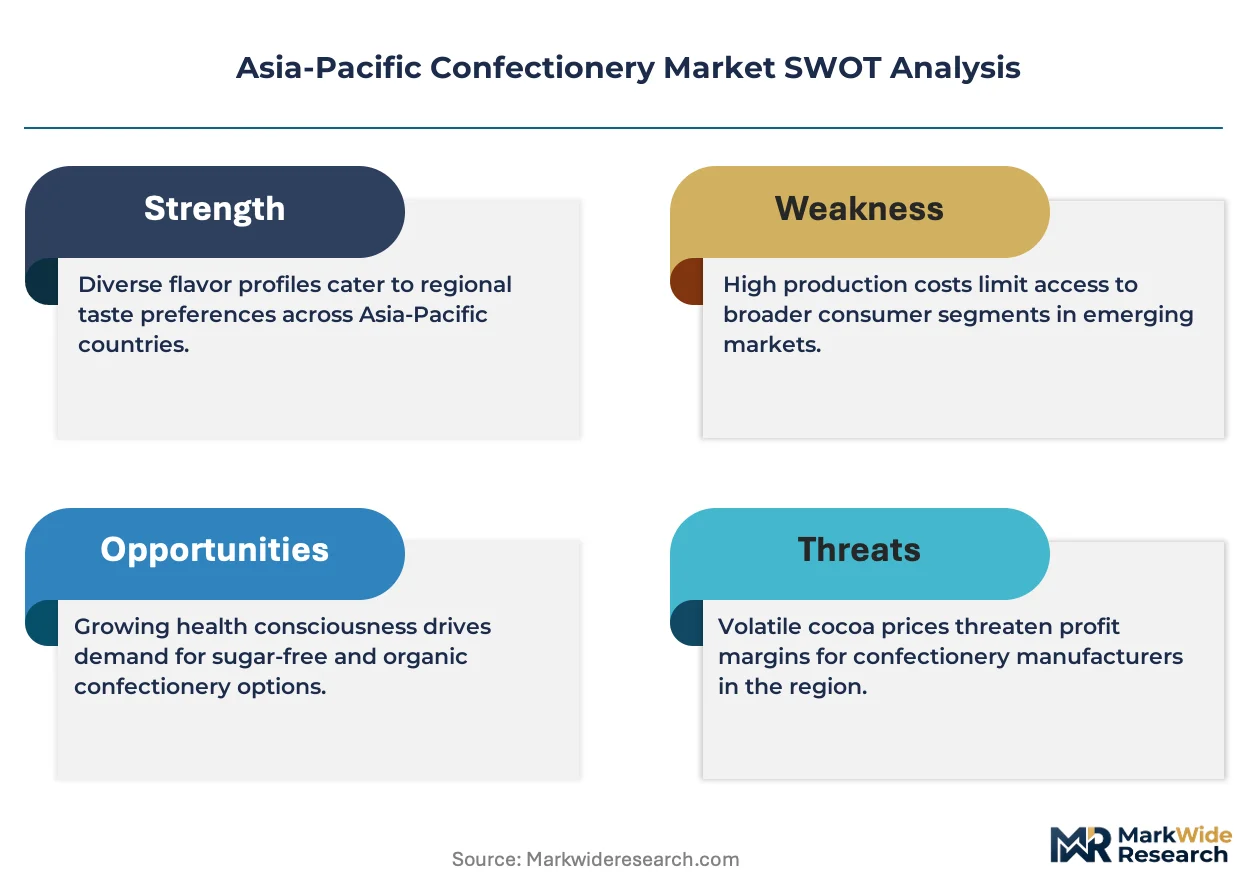
Market Dynamics
Japan's FSSAI-aligned sugar reduction mandates are compressing formulation timelines and forcing rapid clean-label transitions across the Asia-Pacific confectionery sector. Manufacturers must now reconcile sensory performance with compliance-driven ingredient substitution.
Growth Catalysts
- India's FSSAI labeling modernization:Streamlined product registration timelines accelerate new entrant market access in tier-one cities.
- Urban gifting culture expansion:Young adult consumers in China and Southeast Asia elevate premium chocolate purchases for seasonal occasions.
- Alternative sweetener fermentation technology:Novel enzymatic processes enable clean-label sugar reduction without sensory compromise.
Market Restraints
- Cocoa butter equivalent supply concentration:Southeast Asian palm oil derivative sourcing creates input cost volatility for chocolate manufacturers.
- Japan's PMDA novel ingredient approval timelines:Functional confectionery claims face extended safety evaluation periods.
- Clean-label emulsifier technical limitations:Lecithin alternatives struggle to match shelf stability performance in tropical climates.
Strategic Opportunities
- Vietnam and Indonesia underpenetrated modern trade:Convenience store expansion in secondary cities opens impulse purchasing channels.
- China SAMR sugar content claim frameworks:Reformulation investments align with advertising restrictions targeting minors.
- Direct-to-consumer platform logistics maturation:Cold-chain last-mile capabilities enable premium chocolate subscription models.
Industry Challenges
- Food technologist skill scarcity:Clean-label reformulation expertise concentrates in Japan and Australia, creating talent acquisition friction.
- Dual-track certification complexity:India's FSSAI and Japan's PMDA functional claim pathways demand parallel compliance investments.
- Legacy panning equipment retrofit costs:Alternative sweetener viscosity profiles require coating line modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Confectionery Market |
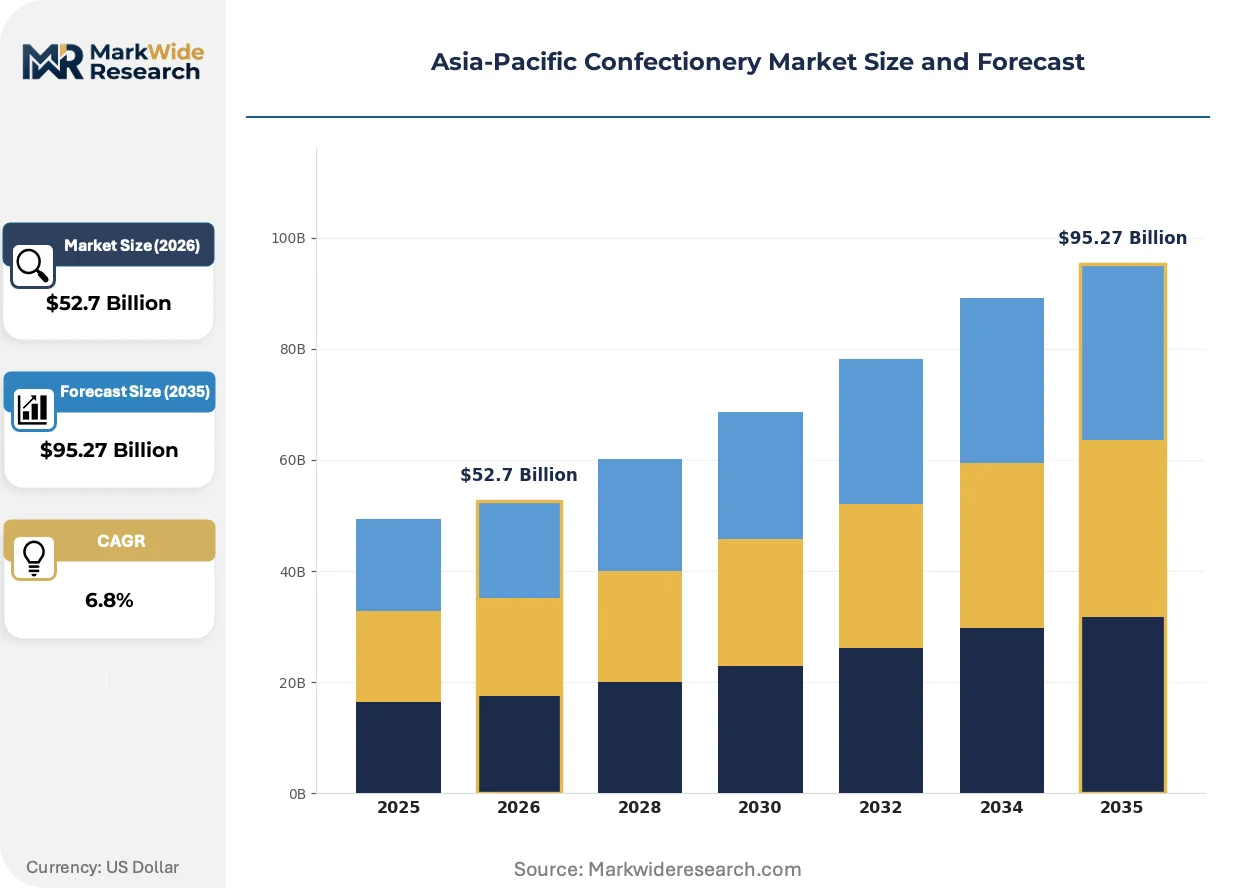
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Hard Candy, Gummy Candy, Sugar-Free Candy Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Customer Type: Adults, Children, Teens, Health-Conscious Consumers Packaging Type: Bags, Boxes, Tubs, Pouches |
| Companies Covered | Nestlé, Lotte Corporation, Mars Incorporated, Lindt & Sprüngli, Ezaki Glico, Mondelēz International, Meiji Holdings, The Hershey Company, Ferrero Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Confectionery Market Emerging Trajectories
Clean-label reformulation is actively fragmenting competitive advantage across the Asia-Pacific confectionery landscape. Technology investments now separate compliance-ready manufacturers from stranded asset positions.
Enzymatic sugar reduction platforms are modularizing production flexibility for Asia-Pacific manufacturers. Mid-scale chocolate producers in Thailand and Malaysia adopt these systems to serve both domestic FSSAI-aligned markets and export destinations with divergent standards. This modularization is compressing the minimum viable scale for clean-label product lines.
Japan's METI coordinates with PMDA on functional confectionery ingredient approvals, creating a dual-track compliance environment. Manufacturers seeking probiotic or protein-fortified claims must navigate parallel safety and efficacy evaluations. Chocolate segments targeting adult wellness demographics face the longest approval timelines.
Gifting occasion purchasing is rotating toward digitally-enabled personalization across China's tier-one cities. Alibaba and JD.com platform data drives seasonal assortment curation, displacing traditional supermarket promotional calendars. This behavioral shift concentrates demand forecasting capabilities with platform operators rather than brand manufacturers.
Asia-Pacific Confectionery Market Segmentation
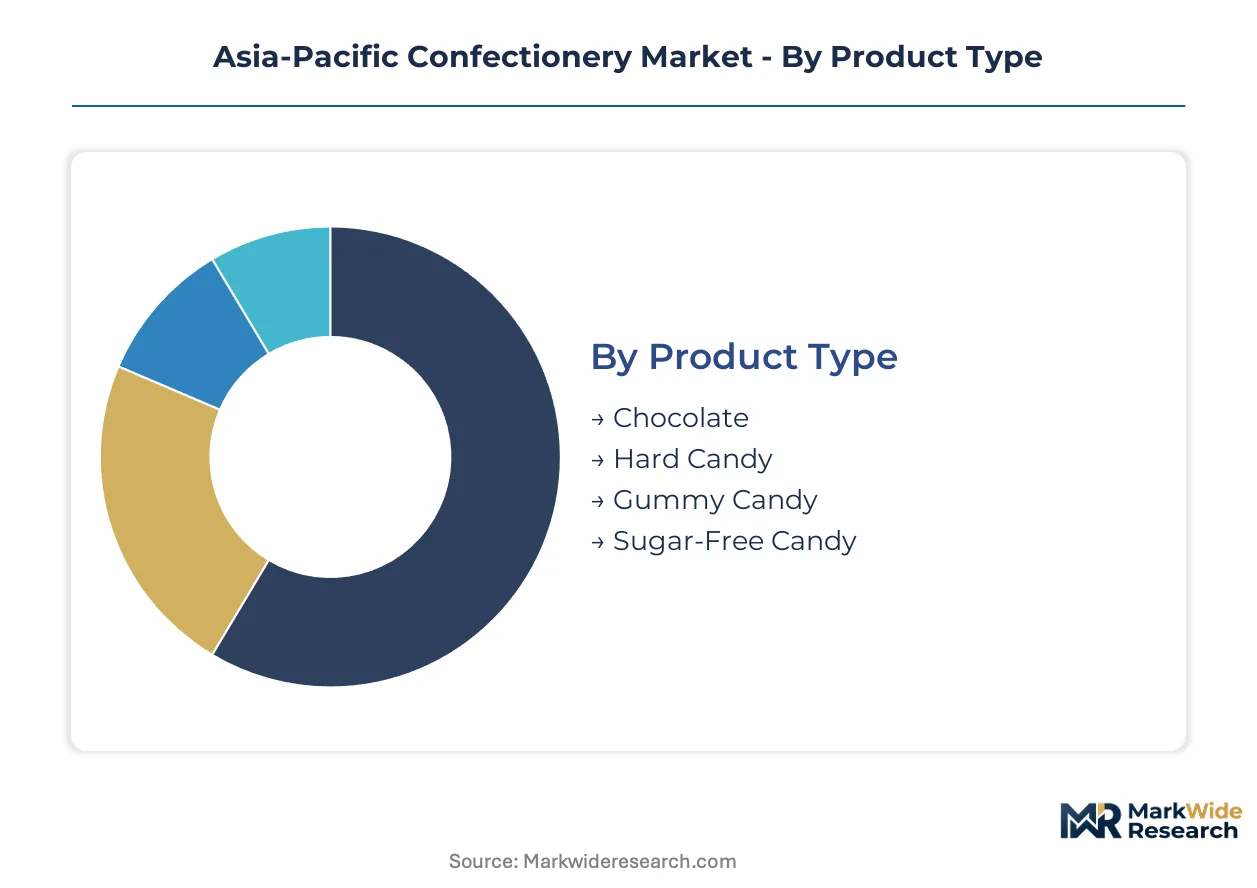
Asia-Pacific confectionery purchasing patterns fragment sharply across product formats and channel access. Manufacturers must align formulation investments with distinct consumption occasions and regulatory exposure profiles across the region.
Product Type:
Supply concentration in cocoa butter alternatives and specialty ingredient sourcing tilts competitive advantage toward segments with backward-integrated sourcing capabilities.
- Chocolate:Formulated through conching and tempering processes using cocoa mass, cocoa butter, and emulsifiers for snap and mouthfeel stability. Premium gifting demand concentrates in China's tier-one cities and Japan's urban corridors, where seasonal purchasing drives velocity spikes. Reformulation pressures from Japan's FSSAI-aligned sugar mandates compress margin structures for non-compliant entrants.
- Gummy Candy:Manufactured via starch or pectin-based depositing and mogul processes, yielding elastic textures with high flavor carrying capacity. Young adult consumers in Southeast Asian markets propel expansion, with functional ingredient claims accelerating trial rates. Novel texture innovation outpaces traditional hard candy in social media-driven discovery.
- Hard Candy:High-boiled sucrose or isomalt formulations produced through vacuum cooking and pulling operations for glass-like clarity.
- Sugar-Free Candy:Polyol-based formulations targeting metabolic health positioning, constrained by aftertaste masking technical limitations.
Today's leader: Chocolate. Tomorrow's challenger: Gummy Candy.
Distribution Channel:
Channel cost-to-serve varies dramatically by cold-chain requirements and impulse activation infrastructure, reshaping where premium versus mass products concentrate.
- Supermarkets:Control the largest volume throughput across India and Southeast Asia through promotional calendar-driven assortment rotation. Modern trade penetration in Vietnam and Indonesia secondary cities remains underdeveloped, constraining national brand scale.
- Online Retail:Platform logistics maturation enables premium chocolate subscription and gifting personalization through Alibaba and JD.com data-driven curation. Cold-chain last-mile capabilities determine serviceable geography for temperature-sensitive formats.
- Convenience Stores:Impulse purchasing density peaks in Japan and South Korea's urban convenience networks.
- Specialty Stores:Curated assortments target premium discovery occasions with higher margin capture potential.
Supermarkets anchor current volume. Online Retail captures steepest expansion trajectory.
Customer Type:
Purchasing authority and regulatory scrutiny intensity diverge across age cohorts, forcing distinct marketing compliance strategies.
- Adults:Drive premium chocolate gifting and functional confectionery trial, particularly wellness-positioned probiotic or protein-fortified formats. Japan's PMDA approval timelines for functional claims create entry barriers that concentrate advantage with established reformulation specialists.
- Health-Conscious Consumers:Clean-label and reduced-sugar demand pressures manufacturers to substitute conventional emulsifiers and sweeteners. China's SAMR advertising restrictions to minors amplify this segment's strategic importance as compliant targeting refuge.
- Children:Subject to strictest sugar content claim limitations and marketing constraints across regional regulators.
- Teens:Social media discovery patterns favor novel texture and limited-edition formats.
Adults command current spending. Health-Conscious Consumers reshape formulation roadmaps.
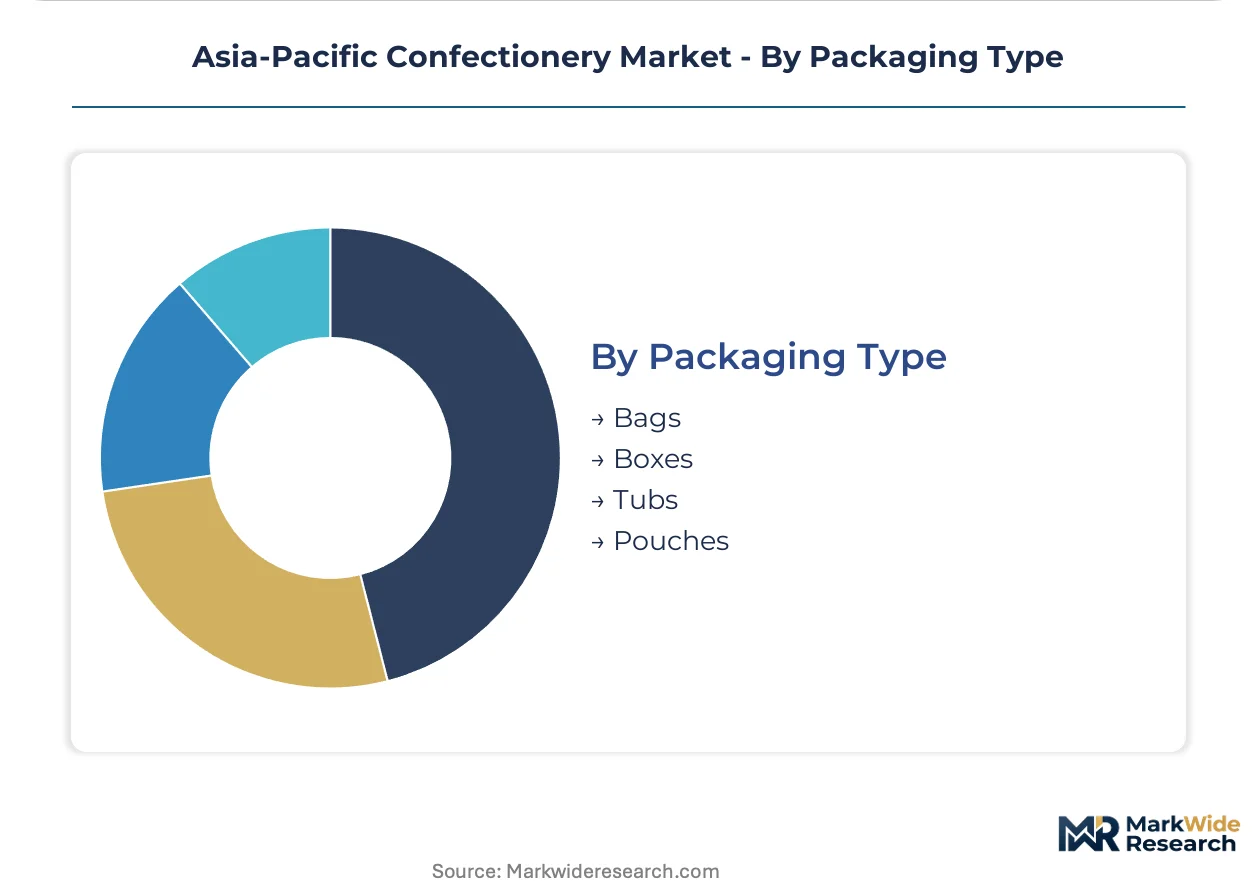
Packaging Type:
Packaging investment priorities reflect shelf stability requirements and gifting occasion differentiation needs across climate zones.
- Boxes:Premium gifting presentation format dominating seasonal revenue concentration in China and Japan. Structural integrity and humidity resistance determine tropical market viability.
- Pouches:Flexible format gaining share in impulse and on-the-go consumption contexts across Southeast Asian convenience channels.
- Bags:Standard sharing-size format for family and social consumption occasions.
- Tubs:Bulk format targeting pantry stocking and foodservice ingredient applications.
Boxes define premium positioning. Pouches expand fastest in emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists with clean-label reformulation expertise concentrate in Japan and Australia, creating talent acquisition friction for manufacturers across the region. This workforce distribution shapes where compliance-ready production capabilities emerge.
China
Young adult urban consumers in tier-one cities elevate premium chocolate purchases for seasonal gifting occasions. SAMR monitors sugar content claims and advertising to minors, restricting brand positioning toward children. Shanghai and Beijing anchor modern trade penetration where Alibaba and JD.com platform data drives assortment curation.
Japan
Adult wellness demographics drive probiotic and protein-fortified functional confectionery trial. METI coordinates with PMDA on novel ingredient approvals, creating dual-track compliance for health claims. Tokyo and Osaka urban corridors concentrate seasonal purchasing velocity and R&D-intensive reformulation capabilities.
India
Tier-one cities reshape category velocity through modern trade penetration and impulse purchasing expansion. FSSAI enforces labeling and additive standards that shape product registration timelines and reformulation costs. Mumbai and Delhi-NCR anchor demand concentration where streamlined registration accelerates new entrant access.
Indonesia
Secondary cities present underpenetrated modern trade opportunities as convenience store expansion opens impulse channels. National regulators enforce food safety standards aligned with ASEAN harmonization frameworks. Jakarta and Surabaya clusters concentrate distribution infrastructure while emerging urban centers capture fastest channel growth.
Vietnam
Rising disposable incomes in urban centers propel premium chocolate discovery and gifting adoption. The national food administration implements evolving safety and labeling requirements for imported confectionery. Ho Chi Minh City and Hanoi anchor modern retail development where cold-chain capabilities determine serviceable geography.
Asia-Pacific Confectionery Market Vendor Landscape
The competitive structure tilts toward multinational scale players with integrated R&D and regional manufacturing footprints. Tier-one manufacturers leverage backward integration into cocoa processing and specialty ingredient sourcing to secure input cost stability. Three archetypes dominate: reformulation specialists with compliance-ready clean-label pipelines, scale-driven producers optimizing for regional taste profiles, and gifting-focused brands with platform-enabled personalization capabilities. Dominant competitive moves include enzymatic sugar reduction technology licensing and cold-chain last-mile partnership expansion.
Among scale-anchored multinationals, Nestlé, Lotte Corporation, and Mars Incorporated exemplify divergent strategic positioning. Nestlé occupies the reformulation-specialist tier with R&D intensity directed at alternative sweetener integration ahead of regulatory deadlines. Lotte Corporation anchors the backward-integrated archetype through captive cocoa processing and domestic specialty ingredient supply chains. Mars Incorporated sits within the manufacturing-scale tier, operating production facilities optimized for regional portion-size preferences and sensory profiles.
| Leading Market Players |
|---|
| Nestlé |
| Lotte Corporation |
| Mars Incorporated |
| Lindt & Sprüngli |
| Ezaki Glico |
| Mondelēz International |
| Meiji Holdings |
| The Hershey Company |
| Ferrero Group |
| Others |
Supply Flow & Price Mechanics
Japan's FSSAI-aligned sugar reduction mandates are compressing procurement timelines for alternative sweeteners and clean-label emulsifiers, forcing manufacturers to absorb reformulation cost premiums or pass them through to premium-tier buyers. This specification-driven sourcing pressure is fragmenting pricing power across the Asia-Pacific confectionery value chain.
Pricing Analysis
Bundled reformulation services with compliance certification command substantial premiums over unbundled ingredient supply in Japan and India. Three-tier pricing structure across premium gifting, standard retail, and economy impulse tiers separates chocolate positioned for seasonal occasions from mass-market candy. Pricing pressure stems from cocoa butter equivalent input volatility linked to Southeast Asian palm oil derivative markets. Health-conscious adult buyers in China's tier-one cities exhibit lowest price sensitivity, while teens and impulse purchasers in Vietnam's secondary cities drive volume at thin margins.
Supply Chain Analysis
Freight cost differentials between temperature-controlled chocolate logistics and ambient candy distribution are widening as cold-chain capabilities concentrate in Japan, South Korea, and China's eastern seaboard. Cocoa mass and specialty ingredient sourcing draws from Indonesia, Malaysia, and domestic Japanese processing facilities. Single-source vulnerability in enzymatic sugar reduction technology licensing creates bottleneck risk for clean-label transitions. Distribution runs through platform-enabled direct-to-consumer channels for premium tiers and modern trade supermarkets for mass volume across the region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through enzymatic reformulation technology licensing and premium gifting tier capture, as compliance-driven cost premiums concentrate with capable suppliers.
For Market Incumbents: Extend clean-label reformulation pipelines ahead of FSSAI deadline cascades across Southeast Asia. Secure backward integration into domestic cocoa processing to insulate margin structures from palm oil derivative volatility. Channel control through Alibaba and JD.com platform data partnerships defends against gifting occasion disintermediation. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting India's tier-one city health-conscious adults with probiotic-functional gummy formats. Vietnam and Indonesia's underpenetrated modern trade in secondary cities offers white-space expansion with lower incumbent saturation. Prioritize FSSAI registration streamlining as a go-to-market accelerator. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Thai and Malaysian manufacturers possessing modular enzymatic sugar reduction systems serving dual export markets. Long-term viability hinges on compliance-ready production capabilities rather than brand equity alone. Watch for PMDA functional claim approval accelerations as inflection signals for wellness-positioned consolidation targets.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Sugar Reduction Technology Licensing | Modular clean-label capabilities separate compliance-ready manufacturers from stranded reformulation investments. |
| Backward Integration into Cocoa Processing | Captive supply of cocoa mass and specialty ingredients insulates margin structures from palm oil derivative volatility. |
| Direct-to-Consumer Platform Partnership Expansion | Alibaba and JD.com data-driven curation concentrates gifting occasion demand forecasting with brand manufacturers. |
| Functional Confectionery PMDA Approval Investment | Probiotic and protein-fortified claims face extended timelines, creating defensive moats for early filers. |
| Cold-Chain Last-Mile Capability Buildout | Temperature-controlled logistics determine serviceable geography for premium chocolate subscription models. |
Methodological Framework
Bottom-up confectionery consumption modeling reconciled against top-down ingredient supply tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at Alibaba and JD.com, FSSAI registration consultants, and plant engineers at Thai and Malaysian manufacturing facilities combined with secondary validation from customs records, Nielsen retail audit data, and regulatory filing databases. Triangulation across these sources ensures segment-level precision without over-reliance on any single data stream.
Historical trendline analysis of chocolate and sugar candy velocity patterns across China's tier-one cities, Japan's urban corridors, and India's modern trade channels informed projection frameworks. Segmentation dimensions include product format, distribution channel, customer type, and packaging configuration across the modeling period. CAGRs derive from regression-adjusted growth rate synthesis incorporating regulatory deadline impacts, platform logistics maturation curves, and gifting occasion behavioral shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FSSAI harmonization or prolonged PMDA functional claim delays. Forecasts reflect assumptions about clean-label technology adoption curves and alternative sweetener cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Brain Mint Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Xylitol Lollipops Market
Confectionery
Mints Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Low-Calorie Candy Market
Confectionery
Chocolate Confectionery Market
Confectionery
North America Marshmallow Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Global Chocolate Market
Confectionery
North America Sugar Confectionery Market
Confectionery
Organic Chocolate Confectionery Market