
 Coffee Concentrate Market | 2026-2036
Coffee Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Concentrate Market Analysis
Arabica bean sourcing is consolidating around high-altitude origins as manufacturers seek cleaner flavor profiles and lower defect rates. JDE Peet's N.V. leverages its green coffee procurement network across Latin America to secure premium lots. Nestlé S.A. anchors its concentrate portfolio through proprietary freeze-concentration patents. Califia Farms differentiates via oat-milk-compatible cold brew formulations.
Coffee concentrate denotes a reduced-water extract produced through thermal evaporation, freeze concentration, or cold brewing, typically yielding solids between 25% and 50% by weight for industrial dilution. Liquid concentrate commands the largest volume position due to its compatibility with fountain dispensing systems in foodservice. Powdered extract generates the highest margin pool per kilogram shipped, though its share remains constrained by solubility limitations in cold applications. Ready-to-drink formats are expanding fastest through convenience-store and grab-and-go channels.
The U.S. FDA sets labeling thresholds for caffeine content per serving, while the USDA Organic certification shapes premium positioning and pricing power. Brazil's national agricultural regulator enforces phytosanitary standards on green coffee imports that directly affect concentrate feedstock costs. Stakeholders must monitor how evolving single-use packaging restrictions in the European Union and select U.S. states redirect investment toward refillable dispensers and bulk concentrate systems.
Market Dynamics
Cold brew processing technology is compressing extraction timelines from 24 hours to under two hours while preserving volatile aromatics, forcing legacy thermal evaporation operators to retool or exit commodity concentrate tiers.
Growth Catalysts
- Fountain dispensing retrofit programs:Quick-service restaurants in the United States are installing dual-tap concentrate systems to replace brewed coffee carafes, cutting labor costs per cup served.
- EU single-use packaging directives:Refillable bulk concentrate dispensers qualify for reduced extended producer responsibility fees, accelerating foodservice adoption across Germany, France, and Italy.
- High-altitude Arabica procurement networks:Consolidated sourcing from Colombia's Nariño and Ethiopia's Yirgacheffe zones is lowering defect rates below 2% for premium concentrate feedstock.
Market Restraints
- Green coffee price volatility:ICE Arabica futures swings above 15% annually compress concentrate processor margins when hedging coverage expires.
- Brazilian phytosanitary enforcement:ANVISA inspection backlogs at Santos port delay concentrate production schedules by 3-6 weeks during harvest peaks.
- Powder solubility thresholds:Agglomerated extracts fail to fully dissolve below 10°C, limiting cold-beverage applications in convenience-store fountain systems.
Strategic Opportunities
- Oat-milk compatibility formulations:Barista-grade concentrates that emulsify without curdling in plant-based milks unlock specialty cafe channels in Australia and the United Kingdom.
- USDA Organic certification pipeline:Premium pricing power of 15-25% above conventional concentrates incentivizes processor conversion of wet mills to certified organic.
- Direct-to-office subscription channels:Post-pandemic hybrid work patterns concentrate demand in corporate micro-kitchens bypassing traditional foodservice distributors.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise bridging roast profile mapping with shelf-stable extraction kinetics commands premium compensation exceeding processor budget norms.
- Freeze-concentration capex cycles:Vacuum sublimation equipment requires 7-10 year depreciation horizons, stranding capital if cold brew membrane technology achieves equivalent solids concentration.
- Prop 65 litigation exposure:California's chemical warning requirements create compliance uncertainty for acrylamide levels in thermally processed concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Concentrate Market |
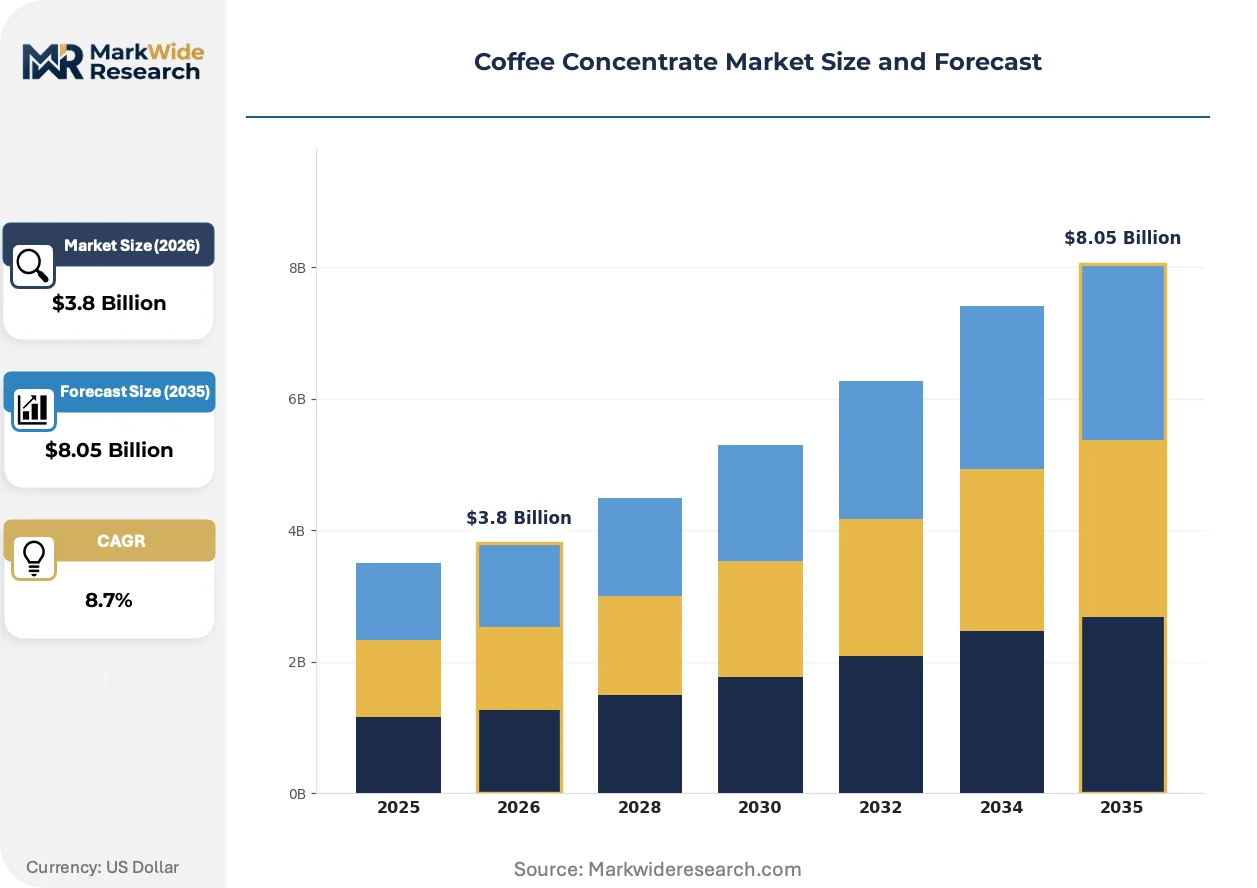
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrate, Powdered Extract, Ready-to-Drink, Instant Coffee End User: Restaurants, Cafes, Retailers, Foodservice Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | JDE Peet’s N.V., The J.M. Smucker Company, Nestlé S.A., Stumptown Coffee Roasters, Califia Farms, Starbucks Corporation, JAB Holding Company, Wandering Bear Coffee, Keurig Dr Pepper Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Concentrate Market Emerging Trajectories
Processing intensification and regulatory pressure on packaging waste are converging to reward operators who master both extraction efficiency and circular dispensing infrastructure.
Membrane-assisted cold extraction is electrifying the competitive landscape by delivering 40% solids concentration without thermal degradation. Mid-scale processors in Japan and the United States are adopting ceramic nanofiltration skids to bypass traditional 18-hour steeping cycles. This compression is enabling same-day concentrate production from green bean receipt, collapsing working capital requirements for regional roasters.
The EU Packaging and Packaging Waste Regulation is mandating 10% minimum recycled content in single-use beverage containers by 2030. Concentrate formats distributed in refillable stainless-steel kegs or bag-in-box systems bypass these thresholds entirely. Foodservice operators in France and Germany are prioritizing bulk concentrate contracts to secure regulatory compliance without packaging redesign costs.
Barista-automation hardware is shifting procurement authority from distributor relationships to equipment-integrated supply agreements. Concentrate producers now contract directly with espresso machine OEMs to embed calibrated dosing systems. This channel compression is most advanced in South Korea's cafe sector, where super-automatic machines with built-in concentrate reservoirs dominate new outlet openings.
Coffee Concentrate Market Segmentation
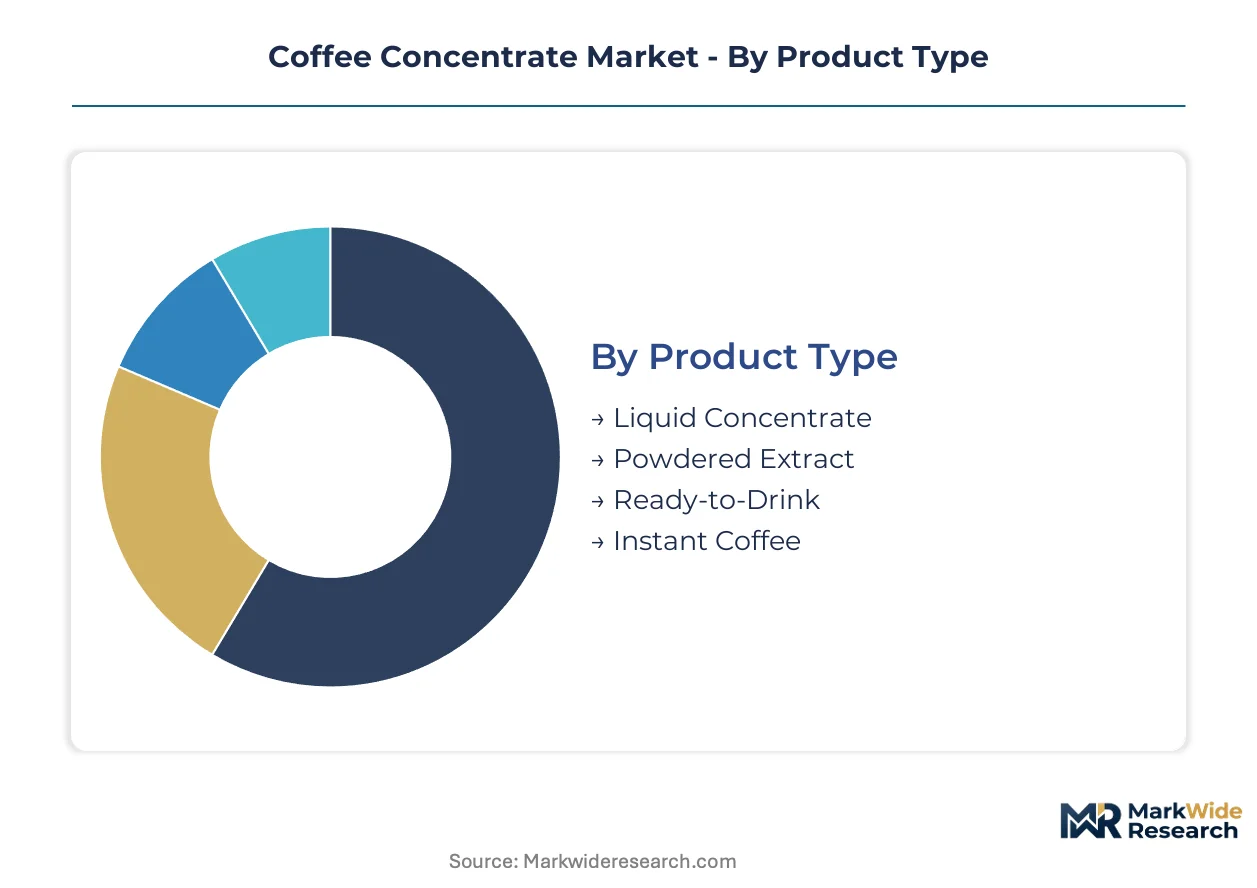
Coffee concentrate processors configure product portfolios around extraction technology economics and foodservice dispensing infrastructure. Segment boundaries blur where liquid concentrates feed ready-to-drink bottling lines, yet margin structures and working capital requirements remain distinct across each category.
Product Type:
Volume concentration favors liquid formats in fountain systems, while premium capture concentrates in specialty extraction methods with higher solids yields.
- Liquid Concentrate:Reduced-water extracts with 25-50% solids by weight, produced through thermal evaporation or cold brewing. Demand concentrates in United States quick-service restaurants installing dual-tap dispensing systems to replace brewed carafes and cut labor costs per cup.
- Powdered Extract:Spray-dried or freeze-dried concentrates offering highest margin per kilogram shipped. Solubility limitations below 10°C constrain convenience-store fountain applications, though agglomeration advances are expanding cold-beverage compatibility.
- Ready-to-Drink:Pre-diluted concentrates in consumer-ready formats. Expansion concentrates in grab-and-go channels and convenience stores where speed of service overrides customization.
- Instant Coffee:Soluble granules from hot-water extraction. Mature demand sits in traditional retail and hospitality settings with lower equipment investment requirements.
Mature deployment sits with Instant Coffee. Newer deployment is concentrated in Liquid Concentrate.
End User:
Procurement authority is shifting from broadline distributors to equipment-integrated supply agreements, reshaping how concentrate producers access each channel.
- Restaurants:Full-service operators deploying concentrate for consistency across locations. Demand is climbing fastest in hybrid-format concepts blending quick-service speed with specialty coffee quality.
- Cafes:Specialty coffee shops driving premium concentrate adoption. Barista-automation hardware in South Korea and Australia is embedding calibrated dosing systems directly into espresso machine supply chains.
- Retailers:Supermarkets and convenience stores stocking ready-to-drink and powdered formats. Shelf-stable extraction kinetics are critical for inventory turnover in ambient storage conditions.
- Foodservice:Institutional and contract catering operations. Bulk concentrate systems in France and Germany are gaining share as operators seek EU Packaging and Packaging Waste Regulation compliance without single-use container redesign costs.
Established volume sits with Foodservice. Emerging volume is concentrating in Cafes.
Distribution Channel:
Channel compression is accelerating as concentrate producers contract directly with equipment OEMs and corporate procurement platforms.
- Online Retail:Direct-to-consumer and subscription platforms. Post-pandemic hybrid work patterns are concentrating demand in corporate micro-kitchen subscriptions bypassing traditional foodservice distributors.
- Offline Retail:Brick-and-mortar supermarkets and specialty stores. Physical shelf space allocation favors ready-to-drink formats with higher velocity and brand recognition.
- Wholesale:Broadline distributors serving restaurants and cafes. Margin pressure from green coffee price volatility compresses processor willingness to absorb distributor markups.
- Direct Sales:Producer-to-operator contracts, often equipment-attached. This channel is expanding most quickly in South Korea's cafe sector where super-automatic machines with built-in concentrate reservoirs dominate new outlet openings.
Traditional volume anchors in Wholesale. Channel expansion is steepest in Direct Sales.
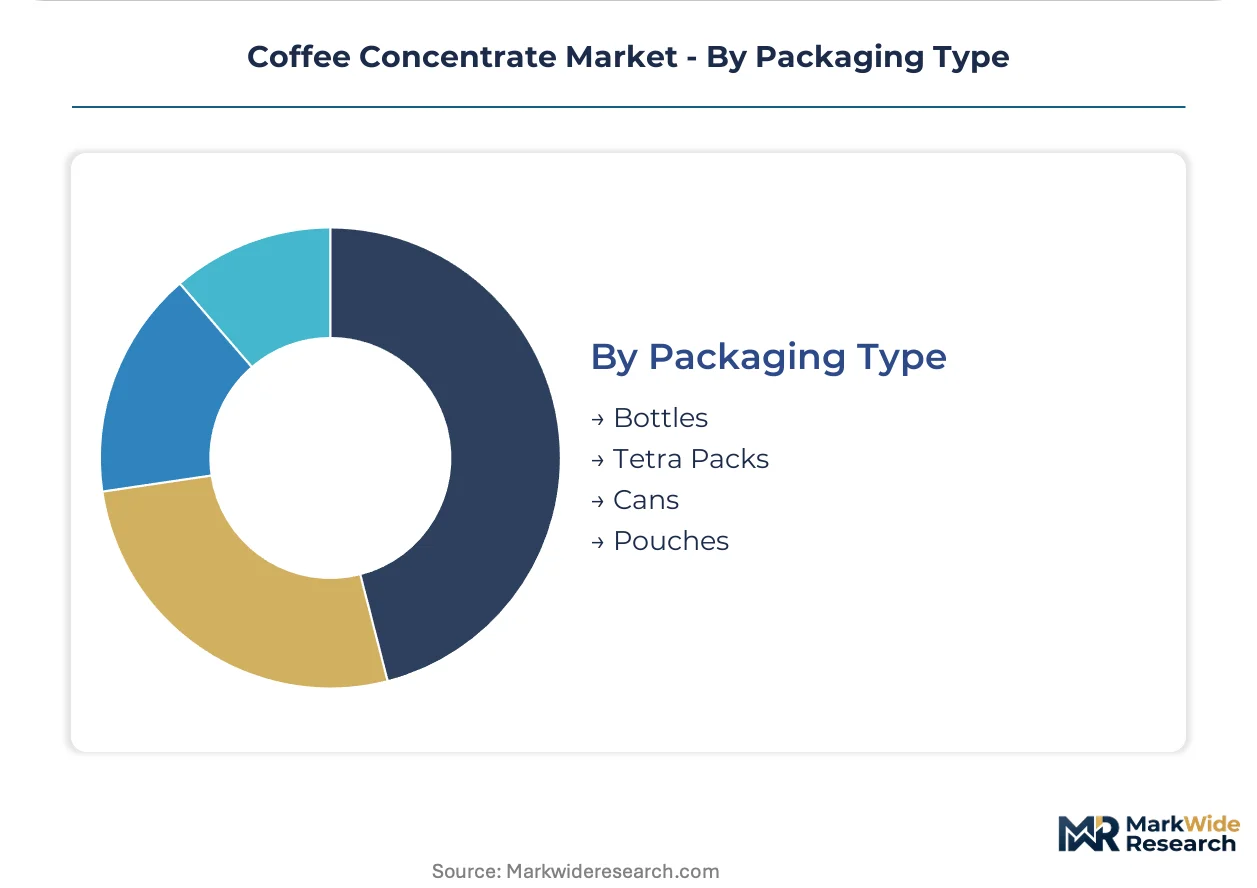
Packaging Type:
Regulatory pressure on single-use packaging is redirecting investment toward refillable dispensers and bulk concentrate systems.
- Bottles:Glass and PET containers for ready-to-drink and liquid concentrate retail. California's Proposition 65 litigation exposure creates compliance uncertainty for acrylamide levels in thermally processed concentrates packaged for direct consumer sale.
- Tetra Paks:Aseptic cartons for ambient-stable liquid concentrates. EU mandates for 10% minimum recycled content by 2030 are forcing packaging redesign investments or format shifts toward exempt bulk systems.
- Cans:Aluminum containers for ready-to-drink formats. Recyclability aligns with sustainability positioning, though flavor chemist scarcity complicates formulation for shelf-stable taste profiles in metal contact.
- Pouches:Flexible film for single-serve and foodservice portions. Lowest packaging weight per unit reduces logistics costs, yet extended producer responsibility fees in Germany and France disadvantage single-use formats regardless of material.
Established infrastructure sits with Bottles. Regulatory-compliant deployment is concentrating in Tetra Paks and bulk-dispensed formats bypassing packaging thresholds entirely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for coffee concentrate clusters in the United States, Brazil, and Japan, with each market shaped by distinct foodservice infrastructure and regulatory frameworks. Fountain dispensing retrofit programs and cold brew processing adoption vary sharply by geography.
United States
Quick-service restaurants drive liquid concentrate volume through dual-tap dispensing systems replacing brewed carafes. The FDA sets caffeine labeling thresholds per serving that processors must meet for retail distribution. Seattle's specialty roasting cluster anchors cold brew innovation, with regional processors adopting membrane-assisted extraction to compress production timelines.
Brazil
Green coffee procurement networks concentrate in São Paulo state, feeding both domestic concentrate production and export feedstock supply. ANVISA enforces phytosanitary standards on imports that delay production schedules during harvest peaks. Santos port logistics create 3-6 week bottlenecks that concentrate processors navigate through advance contracting with Nariño and Minas Gerais growers.
Japan
Ready-to-drink formats dominate convenience-store channels where grab-and-go speed overrides customization. METI standards shape foodservice equipment integration, accelerating barista-automation adoption. Tokyo's cafe sector leads super-automatic machine deployment with built-in concentrate reservoirs, compressing procurement authority toward equipment-attached supply agreements.
Germany
EU Packaging and Packaging Waste Regulation compliance redirects foodservice investment toward refillable bulk concentrate dispensers. Extended producer responsibility fees disadvantage single-use formats, rewarding bag-in-box and stainless-steel keg distribution. Berlin's foodservice operators prioritize concentrate contracts that bypass 10% recycled content mandates hitting PET and Tetra Pak containers by 2030.
United Kingdom
Oat-milk compatible concentrate formulations unlock specialty cafe channels in London and Manchester. Barista-grade emulsification without curdling commands premium positioning in plant-forward outlets. The Competition and Markets Authority monitors vertical arrangements between concentrate producers and espresso machine OEMs as channel compression accelerates.
Coffee Concentrate Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with liquid concentrate tilting toward foodservice-integrated suppliers and powdered extract favoring diversified consumer goods portfolios. Market structure shows moderate consolidation at the top tier, with three to five operators commanding premium positioning through proprietary extraction patents or green coffee procurement scale. Strategic archetypes include freeze-concentration patent holders, Latin American sourcing-integrated processors, and plant-milk-compatible formulation specialists. Competitive moves center on equipment-attached supply agreements and organic certification pipeline investments.
Among diversified consumer goods conglomerates, Nestlé S.A. and JDE Peet's N.V. occupy positions anchored by global green coffee procurement networks and proprietary processing intellectual property. Califia Farms exemplifies the plant-based compatibility vector, with its positioning reflecting oat-milk formulation specialization rather than traditional roast-and-brew heritage. These three represent distinct competitive anchors: patent-protected freeze-concentration, Latin American sourcing integration, and alternative-dairy channel access.
| Leading Market Players |
|---|
| JDE Peet's N.V. |
| The J.M. Smucker Company |
| Nestlé S.A. |
| Stumptown Coffee Roasters |
| Califia Farms |
| Starbucks Corporation |
| JAB Holding Company |
| Wandering Bear Coffee |
| Keurig Dr Pepper Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty roasters anchor pricing discipline through captive green coffee sourcing networks spanning Colombia's Nariño and Ethiopia's Yirgacheffe, compressing feedstock cost variance while passing USDA Organic certification premiums downstream to foodservice buyers.
Pricing Analysis
Liquid concentrate volumes trade at thinner margins than powdered extract premiums, with three-tier pricing structure across premium, standard, and economy levels separating freeze-concentration patent holders from thermal evaporation operators and commodity cold brew suppliers. Price differentiation hinges on organic certification tier and volume scale, with foodservice fountain contracts commanding 15-25% premiums above retail equivalents. Pricing pressure stems from ICE Arabica futures volatility above 15% annually, squeezing unhedged processors. Quick-service restaurants exhibit highest price sensitivity due to per-cup labor cost targets, while specialty cafes absorb premiums for barista-grade emulsification.
Supply Chain Analysis
Dual-sourcing qualification mandates from Nestlé and JDE Peet's N.V. force processors to maintain parallel procurement channels across Brazil's Minas Gerais and Colombia's high-altitude zones, insulating against ANVISA inspection backlogs at Santos port. Raw material dependencies center on Arabica green coffee, filtration membranes, and aseptic packaging substrates. Supply chain risk concentrates in Brazilian phytosanitary enforcement delays stretching 3-6 weeks during harvest peaks. Distribution runs through equipment-attached direct sales in South Korea's cafe sector, broadline wholesale for U.S. quick-service restaurants, and refillable bulk systems in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
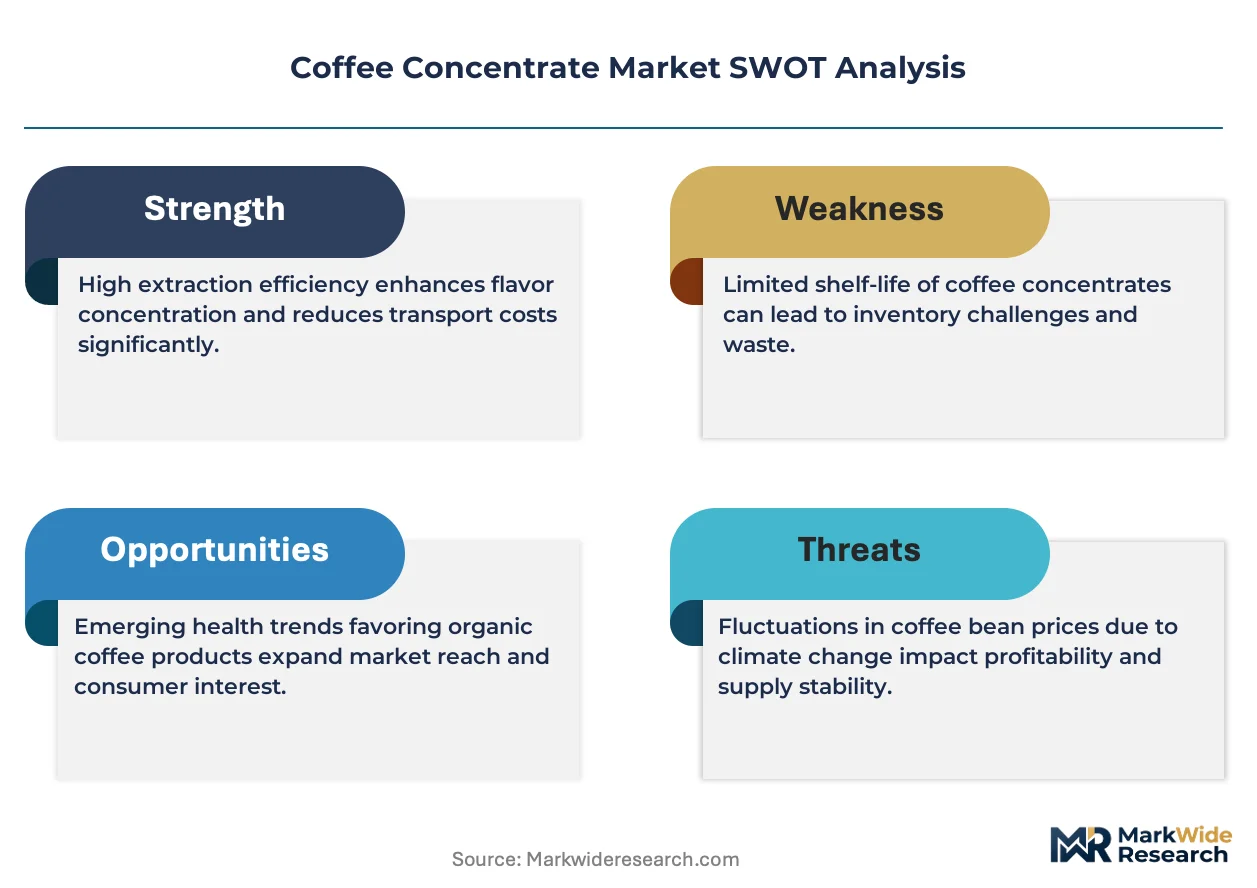
The coffee concentrate market is becoming a vertical-integration race, with upstream control over high-altitude Arabica procurement networks and downstream capture of espresso machine OEM calibration systems determining margin capture.
For Market Incumbents: Extend freeze-concentration patent portfolios into oat-milk-compatible formulations to defend against Califia Farms' plant-based encroachment. Anchor procurement authority through direct contracting with Nariño and Yirgacheffe cooperatives, bypassing volatile spot markets. Prioritize equipment-integrated supply agreements with South Korean super-automatic machine OEMs to lock out challenger brands from cafe channel expansion. For New Entrants and Emerging Players: The price-point gap between premium freeze-concentration and economy thermal evaporation tiers opens white-space at the barista-grade mid-market in Australia and the United Kingdom. Target corporate micro-kitchen subscription channels bypassing traditional foodservice distributors, where hybrid work patterns concentrate demand. Lead with membrane-assisted cold extraction technology offering same-day production cycles to undercut incumbent working capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional roasters with wet mill assets in Colombia and Ethiopia during green price downturns, when organic certification conversion costs compress. Long-term viability rests on backward integration into high-altitude sourcing networks rather than brand equity alone. Watch for cold brew membrane technology achieving 40% solids concentration parity with vacuum sublimation as the signal to exit freeze-concentration equipment-heavy positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Green Coffee Sourcing | Captive supply from Nariño and Yirgacheffe lowers defect rates below 2% for premium feedstock. |
| Equipment-Attached Supply Agreements | Direct contracts with South Korean espresso machine OEMs compress procurement authority from distributors. |
| USDA Organic Certification Pipeline | Premium pricing power of 15-25% above conventional concentrates justifies wet mill conversion costs. |
| Membrane-Assisted Cold Extraction Scale-Up | Ceramic nanofiltration skids collapse 18-hour steeping cycles to under two hours, reducing working capital. |
| Refillable Bulk Dispenser Deployment | Bag-in-box and stainless-steel keg systems bypass EU Packaging and Packaging Waste Regulation mandates entirely. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of concentrate processing plant managers, specialty cafe procurement heads, espresso machine OEM supply chain directors, and foodservice distributor category buyers. Specific sources included ICE Arabica futures documentation, ANVISA phytosanitary enforcement records, EU Packaging and Packaging Waste Regulation impact assessments, and USDA Organic certification databases. Bottom-up modeling of extraction technology economics triangulated against top-down demand segmentation across fountain dispensing, ready-to-drink, and powdered extract formats.
Data-stream reconciliation across production volume surveys, import-export customs declarations, and equipment installation records shaped the analytical framework. Segmentation dimensions modeled encompassed extraction technology type, solids concentration tier, end-use dispensing infrastructure, and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and foodservice capital expenditure patterns. Industry-specific forecast inputs incorporated cold brew processing timeline compression rates and EU extended producer responsibility fee schedules.
Underlying measurement precision varies by segment; liquid concentrate fountain system deployments carry tighter precision than emerging direct-to-office subscription channels due to established distributor reporting. Forecasts reflect assumptions on membrane technology cost curves, organic certification conversion rates, and Brazilian port logistics normalization. Deviation in ANVISA inspection clearance timelines or ICE Arabica futures volatility spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Green Coffee Bean Extract Market
Coffee
Coffee Premixes Market
Coffee
Oceania Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Robusta Coffee Beans Market
Coffee
US Coffee Roaster Market
Coffee
Take Out Coffee Market
Coffee
US Coffee Machine Market
Coffee
UK Coffee Roaster Market
Coffee
Espresso Tamper Market
Coffee
North America Instant Coffee Market
Coffee
Encapsulated Caffeine Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Single-Serve Coffee Containers Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Coffee Bottle Market