
 Coconut Sugar Market | 2026-2036
Coconut Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Sugar Market Analysis
USDA Organic and EU Organic certification cycles is unwinding competitive access across the coconut sugar supply base. Big Tree Farms leverages its vertically integrated farm-to-table infrastructure across Indonesian cooperatives. Celebes Coconut Corporation anchors large-scale sap collection networks in the southern Philippines. Madhava Ltd differentiates through specialized organic liquid coconut sugar formulations targeting North American natural food channels.
Coconut sugar is the crystallized sap of coconut palm (Cocos nucifera) flowers, composed primarily of sucrose with trace fructose and glucose, produced through low-temperature evaporation to preserve mineral content including potassium, magnesium, and inulin. Its primary commercial purpose is serving as a one-to-one replacement for refined cane sugar in clean-label formulations where glycemic index reduction and mineral retention carry premium positioning. Organic coconut sugar commands the deepest margin pools as certification scarcity and longer farm conversion timelines constrain supply expansion. Liquid coconut sugar and coconut sugar syrup are gaining fastest in beverage and sauce applications where dissolution speed and moisture retention matter. Granulated coconut sugar remains the volume leader through established baking and private-label manufacturing demand.
USDA Organic standards, EU Organic Regulation 2018/848, and Indonesia's Ministry of Agriculture export certification protocols collectively determine which producers can access premium shelf space in regulated Western markets. These frameworks enforce traceability from individual farmer to finished product, raising compliance costs that favor scaled operators with dedicated quality teams. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their potential to redirect Indonesian and Philippine export flows toward alternative Asian markets.
Market Dynamics
USDA Organic and EU Organic certification scarcity is compressing supplier access to premium shelf space, forcing food manufacturers to consolidate procurement around vertically integrated Indonesian and Philippine producers with dedicated compliance teams.
Growth Catalysts
- Clean-label bakery reformulation:North American and European food manufacturers are substituting refined cane sugar with coconut sugar to achieve glycemic index reduction claims on packaged goods labels.
- EU Organic Regulation 2018/848:Stricter traceability mandates are locking in compliant suppliers while raising barriers for uncertified competitors, concentrating margin pools among pre-qualified exporters.
- Indonesian plantation concentration:The country's dominance in coconut palm sap collection infrastructure creates economies of scale in organic certification and batch consistency that smaller origins cannot replicate.
Market Restraints
- Sap supply seasonality:Coconut palm flowering cycles limit raw material availability to specific harvest windows, constraining year-round production planning for manufacturers.
- Monoculture dependency:Heavy reliance on Indonesian and Philippine supply clusters exposes buyers to climate disruption, port congestion, and localized pest pressures without geographic diversification.
- Allulose and monk fruit substitution:Zero-calorie sweeteners are capturing beverage and confectionery formulations where glycemic index is the sole purchase driver, squeezing coconut sugar out of price-sensitive applications.
Strategic Opportunities
- EU deforestation-free supply chain regulations:Early compliance investments by Indonesian cooperatives will unlock preferential access to European retail and foodservice channels as due diligence requirements tighten.
- Liquid coconut sugar in beverage manufacturing:Dissolution speed advantages over granulated formats are opening formulation contracts with ready-to-drink tea and coffee bottlers seeking clean-label positioning.
- South Korean and Japanese natural food retail expansion:METI-backed organic import incentives and aging consumer bases seeking mineral-retentive sweeteners are creating new demand nodes outside Western markets.
Industry Challenges
- Organic certification timeline compression:Three-year farm conversion periods and multi-stage audit backlogs delay new supplier market entry, frustrating manufacturers seeking second-source security.
- In-house laboratory capability gaps:Smaller Indonesian cooperatives lack spectroscopy and microbiology testing infrastructure to meet EU and North American contaminant thresholds without third-party outsourcing.
- Sap collection labor specialization:Traditional tappers require multi-year apprenticeship in palm climbing and fermentation prevention, constraining workforce expansion as plantation acreage grows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Sugar Market |
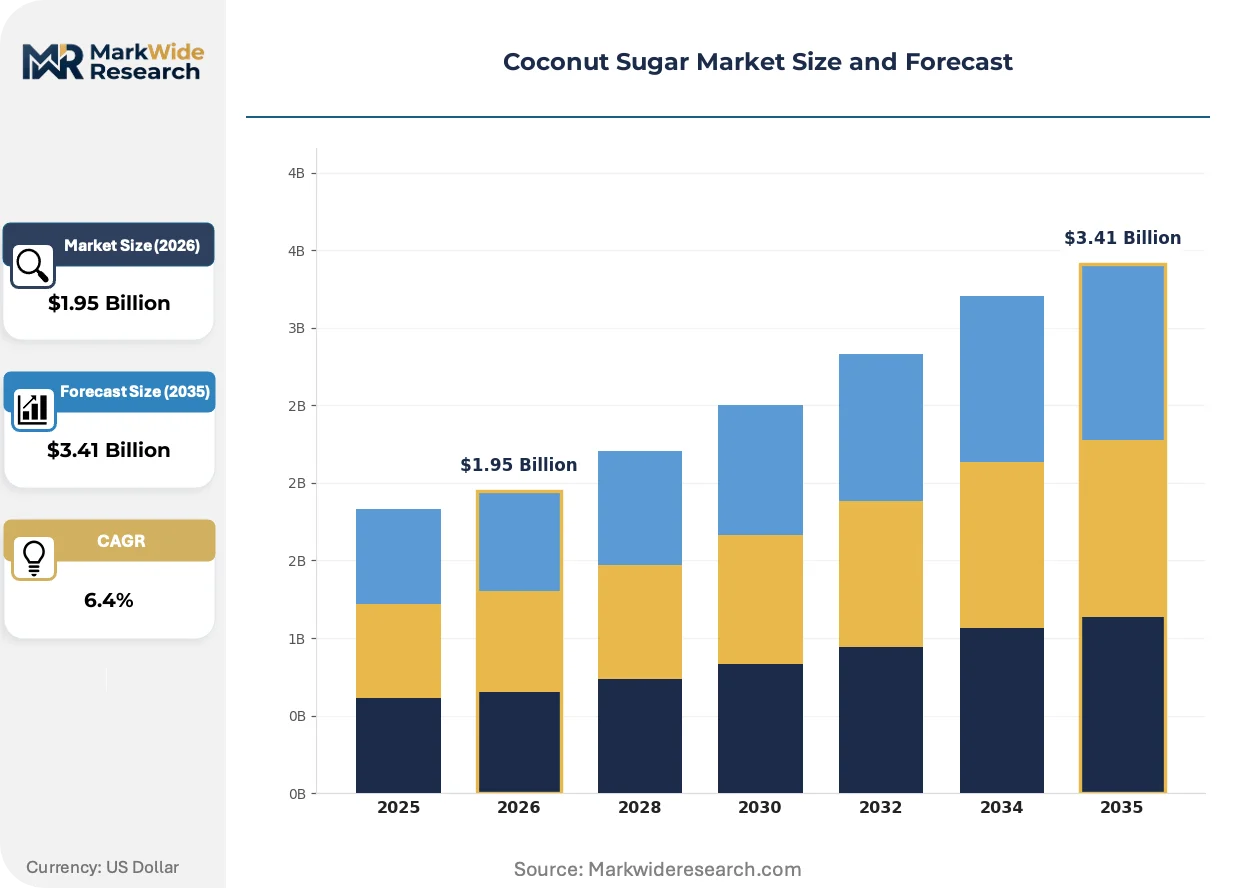
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Coconut Sugar, Organic Coconut Sugar, Liquid Coconut Sugar, Coconut Sugar Syrup End User: Bakers, Food Manufacturers, Health Conscious Consumers, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Packaging Type: Bags, Bottles, Bulk Packaging, Jars |
| Companies Covered | Big Tree Farms, The Coconut Company Ltd, Coconut Secret, SunOpta, Celebes Coconut Corporation, Wholesome Sweeteners, PT. Coco Sugar Indonesia, Madhava Ltd, Nutiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Sugar Market Emerging Trajectories
Low-temperature evaporation technology and blockchain-enabled farm-to-shelf traceability are reconfiguring how coconut sugar quality is verified and premiumized across regulated Western markets.
Near-infrared spectroscopy is decomposing traditional wet chemistry methods for sucrose, fructose, and mineral content verification. Large North American private-label manufacturers are adopting inline NIR systems to accelerate batch release and reduce third-party laboratory dependency. This technology is decomposing quality assurance bottlenecks that previously delayed export shipments by weeks.
EU deforestation-free supply chain regulations are mandating geolocation verification for every farm contributing to exported coconut sugar batches. European importers are now requiring polygon mapping and satellite monitoring integration from Indonesian cooperatives. The regulation most affects granulated organic coconut sugar destined for German and Dutch retail channels, where supermarket chains have advanced compliance deadlines ahead of statutory requirements.
Direct-procurement contracts between food manufacturers and Indonesian cooperative federations are displacing spot-market purchasing through trading houses. North American natural food brands are negotiating multi-year offtake agreements with named farm clusters to secure USDA Organic lineage documentation. This pattern is most visible in the bakery and confectionery vertical, where clean-label positioning requires defensible ingredient provenance for litigation protection and consumer trust marketing.
Coconut Sugar Market Segmentation
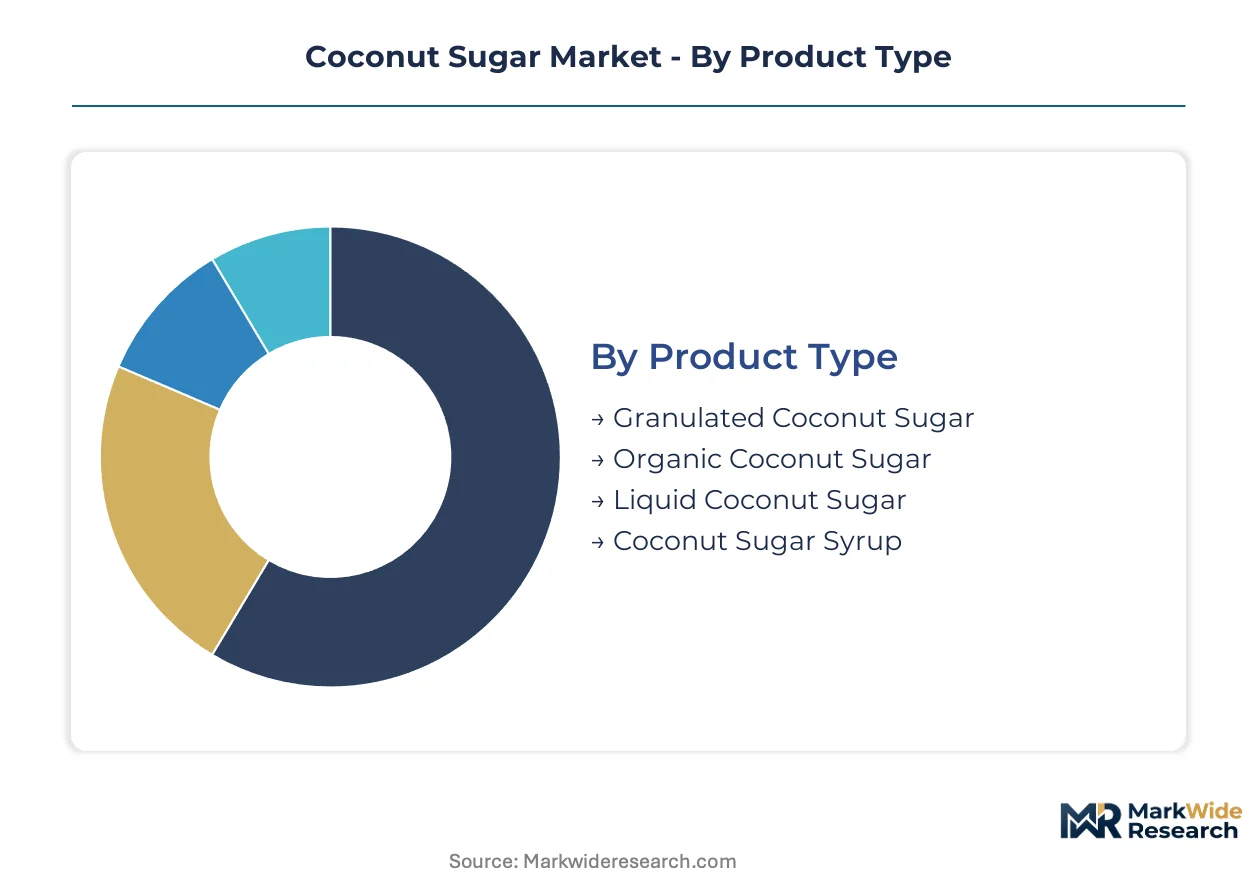
Coconut sugar segmentation reflects divergent supply chain architectures across product formats and customer tiers. Organic certification scarcity and liquid formulation complexity create asymmetric margin pools that reward specialized operators over commodity traders.
Product Type:
Granulated and organic variants dominate export flows to North American and European markets, while liquid formats serve regional Southeast Asian foodservice channels.
- Granulated Coconut Sugar:Crystallized sucrose with trace minerals retained through low-temperature evaporation. North American private-label manufacturers source this format for clean-label bakery reformulations where one-to-one cane sugar replacement preserves recipe integrity.
- Organic Coconut Sugar:USDA and EU Organic certified sap processed under traceable farm-to-table protocols. German and Dutch retail chains concentrate procurement here, locking in multi-year contracts with Indonesian cooperative federations to secure defensible provenance documentation.
- Liquid Coconut Sugar:Non-crystallized syrup with faster dissolution profiles for beverage applications.
- Coconut Sugar Syrup:Higher moisture variant targeting sauce manufacturers and Asian foodservice operators.
Granulated coconut sugar holds the largest share; momentum sits with liquid coconut sugar.
End User:
Cost tier segmentation separates premium-positioned health-conscious consumers from price-sensitive institutional buyers.
- Bakers:Artisan and commercial bakeries specify granulated organic grades for glycemic index claims on packaged goods. French and Italian specialty bakeries drive premium pricing through origin storytelling and mineral retention marketing.
- Food Manufacturers:Large-scale North American CPG companies integrate coconut sugar into clean-label cookie and granola bar lines. These buyers negotiate direct-procurement contracts with named Indonesian farm clusters to satisfy litigation-risk management protocols.
- Health Conscious Consumers:Individuals purchasing through natural food retail for home baking and beverage sweetening.
- Restaurants:Farm-to-table establishments in California and New York sourcing for dessert menu differentiation.
Food manufacturers command the deepest volume contracts; health conscious consumers are expanding most quickly.
Distribution Channel:
Volume concentration favors wholesale and supermarket channels, while specialty stores capture the steepest margin premiums.
- Online Retail:Direct-to-consumer platforms serving dispersed health-conscious buyers with subscription replenishment models. Amazon and Thrive Market aggregate demand for smaller Indonesian brands lacking supermarket slotting fees.
- Supermarkets:German REWE, Dutch Albert Heijn, and US Whole Foods chains dominate organic granulated volume. These retailers enforce EU deforestation-free geolocation requirements ahead of statutory deadlines.
- Specialty Stores:Independent natural food retailers with trained staff explaining glycemic index and mineral content differentiation.
- Wholesalers:Trading houses aggregating uncertified commodity grades for price-sensitive Asian foodservice markets.
Supermarkets hold the largest share; specialty stores are gaining share fastest.
Packaging Type:
Application-driven packaging segmentation aligns with end-use dissolution requirements and shelf-life demands.
- Bags:Multi-layer kraft packaging with moisture barriers for granulated organic retail SKUs. North American natural food brands specify resealable zip closures to preserve flowability in humid climates.
- Bottles:PET and glass containers for liquid coconut sugar targeting ready-to-drink tea bottlers. Japanese and South Korean beverage manufacturers prefer amber glass for UV protection during extended distribution cycles.
- Bulk Packaging:Food-grade totes and drums for industrial bakery and confectionery manufacturers.
- Jars:Premium positioning for gift sets and specialty retail with visible crystalline structure.
Bags hold the largest share; bottles are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Ministry of Agriculture export certification protocols and the EU Deforestation Regulation are redirecting coconut sugar trade flows toward compliant supply corridors. These policy instruments are concentrating processing capacity in established plantation zones while penalizing non-certified origins.
Indonesia
USDA Organic and EU Organic certification scarcity is locking in premium access for cooperative federations with dedicated compliance teams. The Ministry of Agriculture enforces traceability from farmer to finished product through multi-stage audit protocols. Java and Sulawesi host the densest concentrations of certified sap collection networks, where vertically integrated operators control batch consistency for North American private-label manufacturers.
Philippines
German and Dutch retail chains are sourcing granulated organic grades through direct-procurement contracts with named farm clusters. The Philippines' Bureau of Agriculture and Fisheries Standards aligns with EU Organic Regulation 2018/848 traceability mandates. Southern Mindanao anchors large-scale sap collection infrastructure, where established exporters are investing in geolocation verification systems ahead of EU deforestation-free deadlines.
United States
North American natural food brands are negotiating multi-year offtake agreements to secure defensible ingredient provenance for litigation protection. FDA labeling requirements for glycemic index claims are tightening documentation standards. California and New York Metro area formulators drive demand for liquid coconut sugar in ready-to-drink tea and coffee applications, where dissolution speed carries formulation premiums.
Germany
REWE and other supermarket chains are enforcing EU deforestation-free geolocation requirements ahead of statutory deadlines. The EU Green Deal's supply chain due diligence provisions are locking in compliant Indonesian suppliers while raising barriers for uncertified competitors. Hamburg and Rotterdam corridor importers are integrating satellite monitoring systems to verify polygon-mapped farm contributions to exported batches.
Japan
METI-backed organic import incentives are creating new demand nodes for mineral-retentive sweeteners among aging consumer bases. The Ministry of Agriculture, Forestry and Fisheries enforces contaminant thresholds that favor suppliers with in-house spectroscopy capability. Tokyo and Osaka natural food retail channels are expanding shelf space for amber-glass bottled liquid coconut sugar, where UV protection commands distribution premiums.
Coconut Sugar Market Vendor Landscape
Player mix skews toward vertically integrated plantation operators with captive certification infrastructure. Tiered competitive structure separates USDA Organic-certified exporters from commodity-grade traders serving price-sensitive Asian foodservice channels. Two strategic archetypes dominate: cooperative federations with farm-to-table traceability systems, and North American natural food brands with direct-procurement contract structures. Capacity consolidation and backward integration into sap collection networks represent the dominant competitive moves.
Within the cooperative federation tier, Big Tree Farms and Celebes Coconut Corporation exemplify vertically integrated operators with Indonesian and Philippine plantation control. Madhava Ltd occupies a position among North American natural food specialists with formulated liquid product lines. These three anchors represent divergent geographic and format specializations: Big Tree Farms leverages Indonesian cooperative infrastructure, Celebes anchors Philippine southern island networks, and Madhava targets North American beverage formulation channels.
| Leading Market Players |
|---|
| Big Tree Farms |
| The Coconut Company Ltd |
| Coconut Secret |
| SunOpta |
| Celebes Coconut Corporation |
| Wholesome Sweeteners |
| PT. Coco Sugar Indonesia |
| Madhava Ltd |
| Nutiva |
| Others |
Supply Flow & Price Mechanics
USDA Organic and EU Organic certification regimes gate both supplier qualification and price differentiation simultaneously, compressing margin pools among compliant Indonesian cooperatives while excluding uncertified commodity traders from premium shelf space.
Pricing Analysis
Certification level creates the primary spread between commodity-grade and premium coconut sugar tiers. Three-tier pricing structure across organic-certified, conventional granulated, and liquid syrup formats reflects farm-to-table traceability investments and batch consistency guarantees. Cost compression in conventional grades is intensifying because allulose and monk fruit substitutes capture glycemic-index-sensitive beverage formulations. Food manufacturers command the deepest volume discounts through multi-year offtake agreements, while health-conscious retail consumers show the least price sensitivity for USDA Organic lineage documentation.
Supply Chain Analysis
Inventory cycles stretch six to nine months due to coconut palm flowering seasonality and multi-stage organic audit backlogs. Raw material flows draw from Indonesia, the Philippines, and Sri Lanka, with Indonesian Java and Sulawesi clusters anchoring certified sap collection infrastructure. Processing rests on coconut palm sap, low-temperature evaporation equipment, and spectroscopy testing capabilities. Single-source vulnerability concentrates in Indonesian cooperative federations controlling two-thirds of export-certified volume. Distribution runs through direct-procurement contracts between North American natural food brands and named farm clusters, displacing spot-market trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service offerings and blockchain-enabled traceability subscriptions expand faster than base commodity sales, creating recurring revenue layers that deepen customer switching costs and margin durability.
For Market Incumbents: Secure deforestation-free geolocation verification systems ahead of EU statutory deadlines to lock in German and Dutch retail channel access. Consolidate backward integration into sap collection networks across southern Mindanao and Sulawesi to buffer climate disruption risks. Invest in in-house NIR spectroscopy capabilities to accelerate batch release and reduce third-party laboratory dependency for North American private-label contracts.
For New Entrants and Emerging Players: Lead with liquid coconut sugar formulation specialization targeting Japanese and South Korean beverage manufacturers seeking dissolution speed advantages. Penetrate the South Korean natural food retail channel where METI-backed organic import incentives create favorable entry economics. Deploy direct-to-consumer subscription models on Amazon and Thrive Market to bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across blockchain-traceability and spectroscopy testing infrastructure as compliance requirements tighten. Five-to-ten year viability favors vertically integrated cooperative federations with captive certification teams and named farm cluster relationships. Monitor EU deforestation-free enforcement timelines as the signal to watch for supply corridor reallocation and distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sap Collection Networks | Celebes Coconut Corporation and Big Tree Farms anchor Philippine and Indonesian plantation control for batch consistency. |
| Blockchain-Enabled Farm-to-Shelf Traceability | German REWE and Dutch Albert Heijn mandate polygon mapping ahead of EU statutory deadlines. |
| Liquid Coconut Sugar Formulation Development | Madhava Ltd targets North American ready-to-drink tea bottlers seeking clean-label positioning. |
| EU Deforestation-Free Compliance Investment | Indonesian cooperatives unlock preferential Hamburg and Rotterdam corridor access. |
| Direct-Procurement Contract Structuring | North American natural food brands secure litigation-protective provenance documentation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs export records, Indonesian Ministry of Agriculture certification databases, and EU Organic Regulation 2018/848 compliance filings. Primary interviews engaged cooperative federation managers, North American natural food brand procurement directors, German supermarket chain sustainability officers, and South Korean beverage formulation technologists. Secondary validation drew from USDA National Organic Program audit summaries, FDA labeling guidance documents, and METI organic import incentive program disclosures. Bottom-up volume modeling triangulated against top-down trade flow analysis.
Segmentation dimensions modeled include product format, certification status, end-use application, packaging type, and distribution channel across the projection horizon. CAGRs were derived from trend extrapolation of clean-label reformulation adoption curves and organic certification expansion rates. Industry-specific forecast inputs incorporated coconut palm flowering cycle variability and EU deforestation-free enforcement timeline scenarios.
Forecasts assume regulatory continuity in USDA Organic, EU Organic Regulation 2018/848, and Indonesia's Ministry of Agriculture export protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
India Food Sweetener Market
Sweeteners
Natural Sweetener Blends Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Icing Sugar Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Starch Glucose Syrup Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Russia Food Sweetener Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Erythritol Market
Sweeteners
Dry Molasses Market
Sweeteners
Italy Food Sweetener Market