
 Dry Molasses Market | 2026-2036
Dry Molasses Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Molasses Market Intelligence
The unbundling of bulk shipments into smaller, application-specific packaging formats like fiber drums and specialized bags is hardening purchasing criteria for livestock farms. This shift allows for more precise feed mixing and reduced waste. Archer Daniels Midland Company leverages its extensive distribution network to offer varied packaging sizes. Westway Feed Products differentiates through its focus on specialty blends, while Alltech specializes in nutritional additives that often incorporate dry molasses as a carrier.
Dry molasses is a free-flowing powder produced by spray-drying liquid molasses onto an absorbent carrier material like soybean hulls or wheat middlings. It typically contains 40-50% sugar content, making it a valuable energy source and palatability agent in various formulations. Within product types, blackstrap molasses derivatives command a significant share due to their nutrient density and cost-effectiveness. The animal feed application remains the primary demand driver, far outpacing its use in fermentation or as a food additive.
Feed ingredient safety regulations, enforced by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA), govern product purity and labeling. In India, standards from the Bureau of Indian Standards (BIS) influence quality benchmarks for feed components. These frameworks directly impact market access and formulation compliance for producers. Success will depend on navigating evolving animal nutrition science and managing the volatility of sugarcane and beet supply chains.
Market Dynamics
The regulatory-driven phase-out of antibiotic growth promoters in animal husbandry is the central force shaping the dry molasses market. This compels livestock producers to seek alternative palatability enhancers, directly increasing reliance on dry molasses in feed formulations.
Growth Catalysts
- Regulatory Mandates:The European Union's ban on specific antibiotic growth promoters in animal feed directly stimulates demand for palatable, non-medicated alternatives like dry molasses to maintain feed intake and animal performance.
- Consumer-Driven Production Standards:Growing consumer preference for meat and dairy products from animals raised without antibiotics pressures large-scale food companies and their farm suppliers to reformulate feed, favoring natural ingredients.
- Feed Formulation Efficiency:In large-scale cattle and dairy operations, the use of dry molasses as a free-flowing powder improves the homogeneity of feed mixes and enhances palatability, leading to more consistent nutrient intake.
Market Restraints
- Input Cost Volatility:The market is exposed to price fluctuations in raw materials, primarily sugarcane and sugar beets, which are influenced by weather events, agricultural policies, and global commodity trading dynamics.
- Hygroscopic Nature:Dry molasses readily absorbs moisture from the atmosphere, which can lead to caking and handling issues, requiring investment in specialized, climate-controlled storage and moisture-proof packaging.
- Carrier Material Competition:The absorbent carriers used in production, such as soybean hulls or wheat middlings, have their own supply chains and can face competing demand from other sectors of the animal feed industry.
Strategic Opportunities
- Aquaculture Feed Development:There is an opportunity to formulate specialized dry molasses blends for aquaculture feeds, targeting species where palatability is a key factor in improving feed conversion ratios and reducing waste.
- Geographic Expansion:Producers can target developing livestock markets in Southeast Asia and Africa where large-scale farming is professionalizing, creating new demand for standardized and effective feed ingredients.
- Functional Blend Innovation:Development of value-added products that combine dry molasses with probiotics, prebiotics, or specific minerals offers a pathway to differentiate products beyond simple energy and palatability functions.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers must navigate a patchwork of international feed safety standards, including purity and labeling requirements from the US FDA, the EU's EFSA, and India's BIS.
- Supply Chain Logistics:The shift from bulk to smaller, application-specific packaging formats increases logistical complexity and handling costs for producers, demanding more sophisticated inventory and distribution management.
- Quality Control Consistency:Maintaining consistent product quality, particularly sugar content and flowability, is a persistent operational challenge when sourcing carrier materials from various suppliers with differing specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Molasses Market |
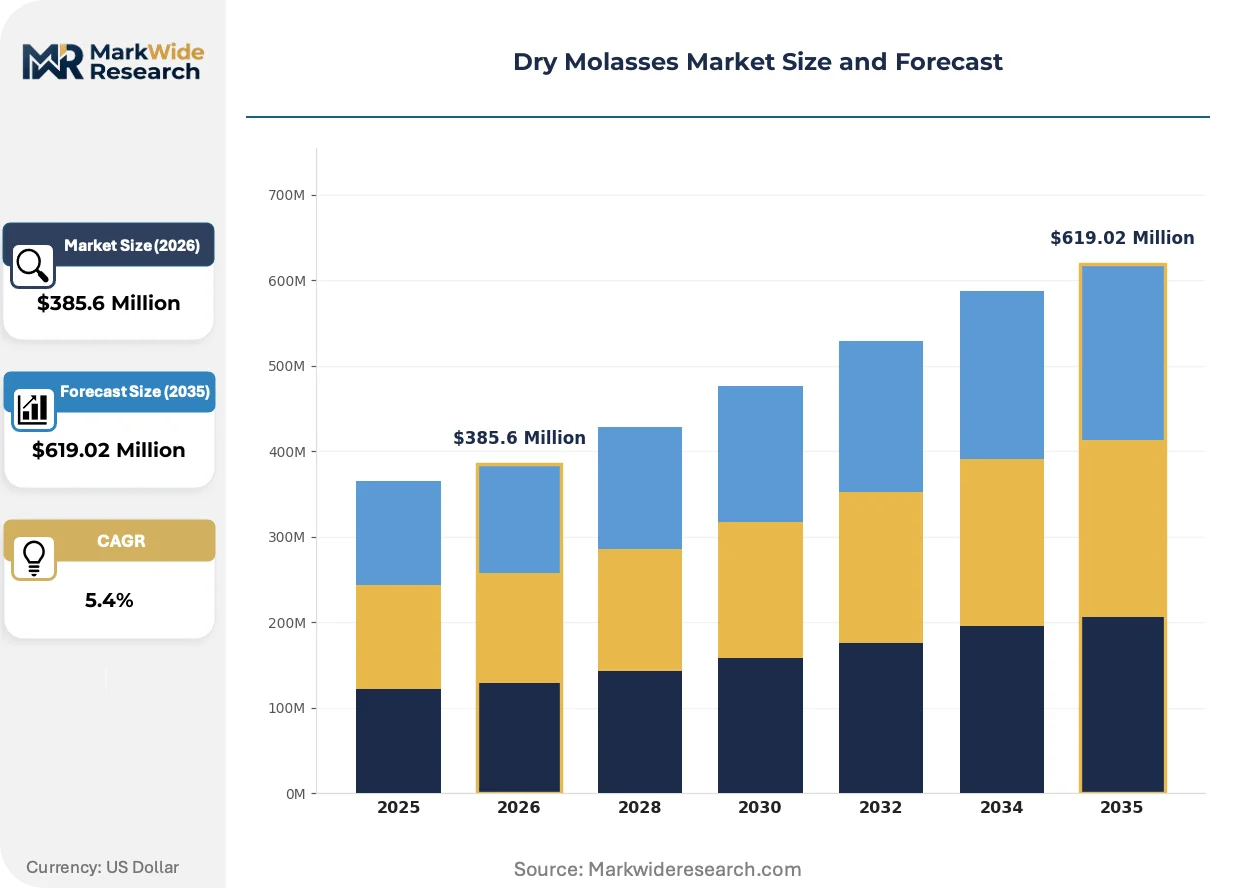
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blackstrap Molasses, Cane Molasses, Beet Molasses, Citrus Molasses Application: Animal Feed, Fermentation, Food Additive, Biofuel Production End User Industry: Livestock Farms, Bioenergy Plants, Food Manufacturers, Pharmaceutical Firms Packaging Type: Bulk Bags, Fiber Drums, Cardboard Boxes, Plastic Containers |
| Companies Covered | International Molasses Corporation, Westway Feed Products, Archer Daniels Midland Company, Standish Milling, Pestell Nutrition Inc., Zook Molasses Company, Alltech, Imperial Sugar, Mercer Milling Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Molasses Market Strategic Shifts & Innovations
A definitive shift toward precision and functionality in animal nutrition defines the market's evolution. Dry molasses is increasingly viewed not just as a bulk energy source or flavor agent, but as a functional carrier for delivering complex nutritional solutions.
Micro-encapsulation is a key product evolution, shielding the sugars and other nutrients within a protective coating. Premium feed compounders and specialty additive manufacturers are the primary adopters of this advanced production method. This technology is integrating dry molasses with sensitive ingredients like vitamins and probiotics, creating higher-value, all-in-one additives that simplify feed formulation for farmers.
The European Food Safety Authority's stringent framework governing feed additives and veterinary medicinal products continues to tighten. This regulatory environment creates a direct commercial incentive for feed formulators to find effective, non-pharmaceutical methods to encourage feed consumption. The swine and dairy cattle sectors are most affected, spurring investment in dry molasses-based formulations to maintain animal health and productivity.
A move from commodity purchasing to specification-driven sourcing is altering buying behavior among large-scale agricultural enterprises. Buyers now demand certificates of analysis detailing specific sugar content, carrier material, and particle size to optimize automated feeding systems and ensure ration consistency. This trend is most visible in the high-efficiency dairy sectors of the United States and the Netherlands, where precise feed management is critical.
Dry Molasses Market Segmentation
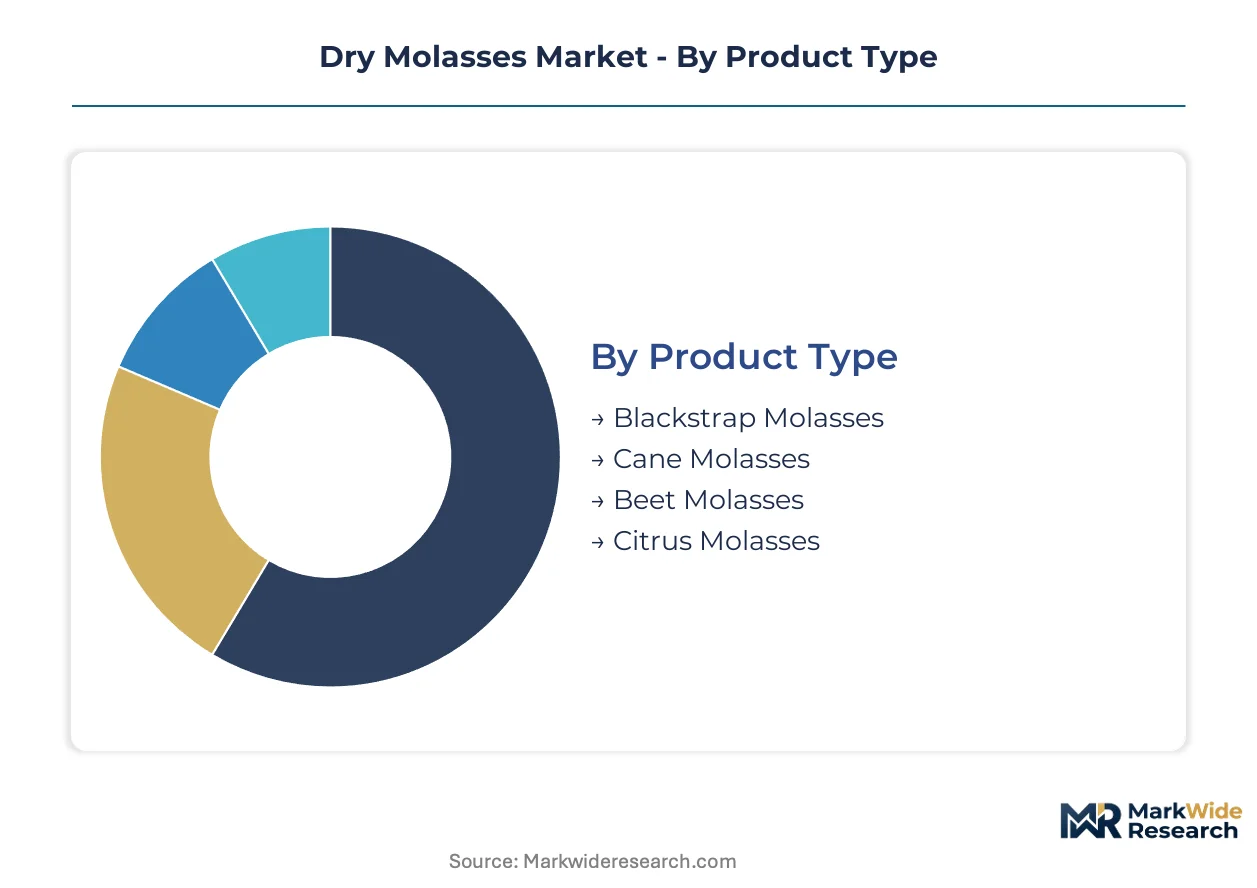
The dry molasses market's segmentation reveals the diverse forms and uses of this versatile ingredient across various industries. Understanding these distinct categories allows producers to tailor product specifications and distribution strategies effectively. This granular view helps stakeholders identify specific demand pockets and regulatory compliance requirements.
Product Type:
The varying sugar content and nutrient profiles of dry molasses product types often dictate specific regulatory approvals for their intended use.
- Blackstrap Molasses:Derived from the final stage of sugar refining, this product offers high mineral content and a distinct flavor profile. Demand concentrates within the animal feed sector, particularly for cattle operations in Brazil, due to its cost-effectiveness and palatability.
- Cane Molasses:Produced from sugarcane, this widely available form provides a balanced sugar profile and consistent quality. Large-scale livestock farms in the United States increasingly demand it as an energy source and feed binder, driven by its reliable supply chain.
- Beet Molasses:Originating from sugar beets, this type is often utilized in animal feed formulations in European markets, valued for its consistent energy contribution.
- Citrus Molasses:A byproduct of citrus processing, this niche product finds application in specialty animal feeds, particularly in regions with significant citrus production.
Leading the category by volume: Blackstrap Molasses. Growing fastest: Cane Molasses.
Application:
Demand for dry molasses varies significantly across applications, with each end-use requiring distinct product specifications and handling characteristics.
- Animal Feed:This application dominates the market, utilizing dry molasses as a palatability enhancer and energy source for livestock. Large dairy farms and beef cattle operations in the United States are the primary consumers, driven by the need for consistent feed intake.
- Fermentation:Dry molasses provides a cost-effective carbon source for various industrial fermentation processes, including yeast and ethanol production. Bioenergy plants in India increasingly adopt it to optimize fermentation yields and reduce input costs.
- Food Additive:Dry molasses is used sparingly in certain food products for its color, flavor, and humectant properties, primarily in baked goods and sauces.
- Biofuel Production:This application leverages the sugar content of dry molasses as a feedstock for producing biofuels, particularly in regions seeking renewable energy sources.
Margin concentration is highest in fermentation, while customer type focus remains on large-scale animal feed operations.
End User Industry:
The end-user industry dictates the specific volume requirements and quality standards for dry molasses, influencing packaging and distribution networks.
- Livestock Farms:This industry segment represents the largest consumer of dry molasses, integrating it into feed formulations for cattle, swine, and poultry. Large-scale operations in Brazil and the United States prioritize consistent quality and reliable supply for their automated feeding systems.
- Food Manufacturers:Food manufacturers utilize dry molasses as an ingredient for its sweetening and coloring attributes in various processed foods. This segment often requires higher purity standards and specific certifications for human consumption.
- Bioenergy Plants:These facilities use dry molasses as a fermentation substrate for producing ethanol and other bioproducts, driven by the need for cost-effective carbon sources.
- Pharmaceutical Firms:A smaller segment, pharmaceutical firms may use highly purified molasses derivatives as excipients or fermentation media in certain specialized applications.
Supply concentration for dry molasses is greatest for livestock farms, and the maturity of demand varies significantly across these distinct end-user industries.
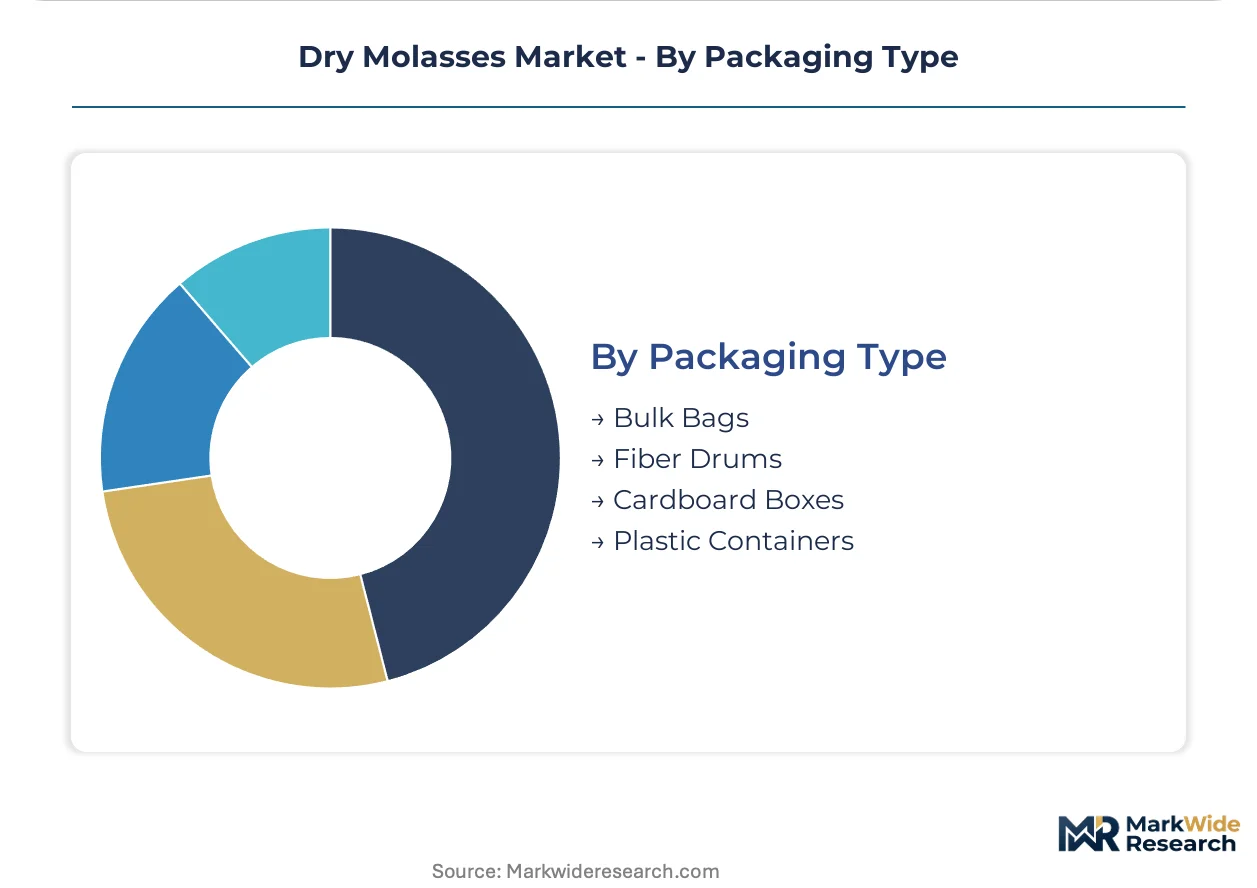
Packaging Type:
The choice of packaging for dry molasses is heavily influenced by logistical efficiency, storage conditions, and the end-user's operational scale.
- Bulk Bags:These large, industrial containers are designed for high-volume shipments to large feed mills and integrated livestock operations. Bulk bags optimize transport costs and reduce handling for major buyers in the United States.
- Fiber Drums:Offering a balance between bulk and smaller formats, fiber drums provide protection against moisture and facilitate easier handling for medium-sized farms and specialty blenders. This packaging type supports precision mixing in European dairy farms.
- Cardboard Boxes:Used for smaller quantities, cardboard boxes cater to niche applications or smaller farm operations that require precise dosing and easy storage.
- Plastic Containers:These containers provide robust moisture protection and are often preferred for premium or specialized dry molasses blends in regions with high humidity.
Regulatory impact on packaging is most stringent for plastic containers, while geographic distribution patterns favor bulk bags for long-distance transport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dry molasses market exhibits a clear divide between raw material production and concentrated consumption. Sugarcane and beet-producing nations often supply global demand for molasses derivatives. However, the primary end-use demand for dry molasses centers in advanced livestock farming regions.
United States
United States livestock farms drive substantial demand for dry molasses, particularly in large-scale beef and dairy operations requiring consistent feed intake. The US Food and Drug Administration (FDA) enforces stringent feed ingredient safety regulations, ensuring product purity and labeling compliance. High-efficiency dairy sectors in California and Wisconsin prioritize specification-driven sourcing for automated feeding systems.
Brazil
Brazil's expansive cattle industry represents a major consumer of blackstrap molasses derivatives, valued for their cost-effectiveness and palatability. Brazil's Ministry of Agriculture, Livestock, and Food Supply (MAPA) sets standards for animal feed ingredients, influencing market access. Large-scale cattle operations in Mato Grosso and Goiás integrate dry molasses to enhance feed consistency and performance.
Germany
European animal feed sectors, particularly in Germany, utilize dry molasses as a consistent energy source in antibiotic-free formulations. The European Food Safety Authority (EFSA) tightens regulations on feed additives, creating commercial incentives for non-pharmaceutical palatability enhancers. Precision dairy farms in Bavaria and Lower Saxony adopt fiber drums for smaller, application-specific packaging formats.
India
Indian bioenergy plants increasingly adopt dry molasses as a cost-effective carbon source for fermentation processes. The Bureau of Indian Standards (BIS) influences quality benchmarks for feed components, impacting market access for producers. Growing livestock sectors and bioenergy plants in Maharashtra and Uttar Pradesh drive demand for standardized feed ingredients.
Dry Molasses Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the dry molasses market, creating a multi-tiered competitive environment. This landscape includes large agricultural processors leveraging extensive distribution networks and niche players specializing in functional blends for specific applications. Strategic archetypes encompass integrated feed ingredient suppliers, specialty blend formulators, and advanced nutritional additive developers. Geographic expansion into developing livestock markets and functional blend innovation are dominant competitive moves.
Within the integrated agricultural conglomerate tier, Archer Daniels Midland Company exemplifies leveraging an extensive distribution network for varied packaging sizes. Westway Feed Products occupies a position as a specialty blend producer, differentiating through its focus on customized formulations. Alltech represents a nutritional additive specialist, integrating dry molasses as a carrier for complex solutions. These players anchor different segments of the value chain, from bulk commodity supply to high-value functional ingredients. Their strategies reflect the market's shift towards precision and functionality in animal nutrition.
| Leading Market Players |
|---|
| International Molasses Corporation |
| Westway Feed Products |
| Archer Daniels Midland Company |
| Standish Milling |
| Pestell Nutrition Inc. |
| Zook Molasses Company |
| Alltech |
| Imperial Sugar |
| Mercer Milling Company |
| Others |
Cost & Logistics Intelligence
Micro-encapsulation technology, as a production-method transition, simultaneously reshapes cost economics for specialty blends and creates new supply concentration points for advanced processing. This shift influences both raw material procurement and the pricing of value-added dry molasses products.
Pricing Analysis
Cost-down pressure on commodity dry molasses accelerates because raw material input cost volatility persists. The dominant pricing model remains commodity spot trading for bulk volumes, supplemented by contract-based long-term offtake agreements for larger buyers. Price differentiation stems from quality grade, specifically sugar content and flowability, and the level of customization for specialty blends. Buyer price sensitivity is highest among bioenergy plants seeking cost-effective carbon sources, while large-scale animal feed operations prioritize consistent quality and reliable supply over marginal price differences.
Supply Chain Analysis
Single-source vulnerability sits with raw material suppliers of sugarcane and sugar beets, primarily concentrated in Brazil, India, and European agricultural regions. The dry molasses production process draws from these agricultural commodities, along with carrier materials like soybean hulls and wheat middlings. Commodity price volatility for sugarcane and beet presents a significant structural risk across the supply chain. Distribution runs through large industrial containers like bulk bags for major feed mills and integrated livestock operations, with fiber drums and plastic containers serving more specialized or smaller-scale end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race, with players actively pursuing control over specialized carrier materials and advanced processing capabilities.
For Market Incumbents:
Hedge against input cost volatility by securing long-term supply agreements for raw sugarcane and beet molasses. Invest in advanced processing technologies, such as micro-encapsulation, to differentiate products and mitigate the threat of generic commodity offerings. Expand proprietary distribution networks to ensure reliable delivery of varied packaging formats, reinforcing control over market access. Develop functional blends that integrate nutritional additives, moving beyond simple palatability enhancement.
For New Entrants and Emerging Players:
A price-point gap exists between premium, highly customized blends and bulk commodity dry molasses, offering entry opportunities. Target niche applications like aquaculture feed development where palatability is critical for feed conversion ratios. Focus on geographic expansion into developing livestock markets in Southeast Asia and Africa, leveraging demand for standardized, effective feed ingredients. A specific go-to-market angle involves offering value-added products that combine dry molasses with probiotics or prebiotics for enhanced animal health.
For Investors and Strategic Acquirers:
Exit pathways concentrate in specialized dry molasses blenders and nutritional additive developers with proprietary technologies or strong regional distribution. The long-term viability of the dry molasses market is anchored in sustained demand for antibiotic-free livestock feed. Identify acquisition targets offering strong intellectual property in functional blend innovation or unique access to specific carrier materials. The signal to watch is the tightening of feed safety regulations in emerging livestock markets, indicating increased demand for compliant, high-quality ingredients.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enables producers to meet the rising demand from large-scale cattle and dairy operations in the United States. |
| Functional Blend Innovation | Differentiates products by integrating probiotics, prebiotics, or specific minerals, enhancing value for livestock farms. |
| Geographic Expansion | Targets developing livestock markets in Southeast Asia, creating new demand for standardized feed ingredients. |
| Advanced Packaging Solutions | Addresses the hygroscopic nature of dry molasses, improving handling and extending shelf life for European dairy farms. |
| Long-term Supply Agreements | Mitigates input cost volatility associated with sugarcane and beet, securing stable raw material access for manufacturers. |
Research Approach
Multi-period observation of dry molasses market trends and regulatory shifts anchored the trend analysis, supplemented by interviews with feed formulators, livestock farm managers, bioenergy plant operators, and ingredient procurement specialists. This primary research was triangulated with extensive secondary validation from sources including US FDA reports, EFSA guidelines, BIS standards, and agricultural commodity market data. The approach integrated both bottom-up aggregation of segment data and top-down market sizing for comprehensive insights.
The input-output matrix framing guided the quantitative model, projecting market dynamics across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, packaging type, and specific sugar content. Compound annual growth rates were derived from historical data and projected market drivers such as global sugar production forecasts and the adoption rates of antibiotic-free feed. This framework provided a robust basis for market projections.
Inputs from regulatory bodies and commodity market data were available through the study window; gaps in specific regional consumption statistics introduce uncertainty bands into the forecasts. Forecasts reflect assumptions regarding agricultural policies and consumer preferences. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Glucose Syrup Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Vanilla Sugar Market
Sweeteners
China Allulose Market
Sweeteners
Saccharin Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
Oligofructose Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Date Sugar Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Compressible Sugar Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
North America High-Intensity Sweeteners Market
Sweeteners
South Korea Allulose Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Trehalose Market