
 North America Low-Calorie Sweeteners Market | 2026-2036
North America Low-Calorie Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
North America Low-Calorie Sweeteners Market Analytics
Midwestern corn-derived ingredient processing capacity is expanding across Iowa and Illinois, reinforcing the region's role as a feedstock hub for fermentation-based sweetener production. Cargill, Incorporated leverages its integrated supply chain from corn milling to high-intensity sweetener refinement, sustaining cost advantages in bulk aspartame and erythritol output. Tate & Lyle PLC anchors its North American position through specialty starch and sweetener formulation expertise, while Archer Daniels Midland Company competes on fermentation scale and bioprocess engineering capabilities.
North America low-calorie sweeteners encompass high-intensity compounds and bulk sugar substitutes that deliver perceptible sweetness at substantially reduced caloric contribution, typically manufactured through fermentation, chemical synthesis, or extraction from steviol glycosides with purity thresholds exceeding ninety-five percent. These ingredients serve primarily to enable food and beverage manufacturers to achieve sugar reduction targets while preserving consumer-acceptable taste profiles. The stevia segment leads in clean-label positioning among natural-positioned product lines, whereas sucralose maintains cost efficiency dominance in mass-market beverage applications. Powder and granular forms capture the majority of industrial procurement volumes due to handling efficiency and shelf stability advantages in high-throughput manufacturing environments.
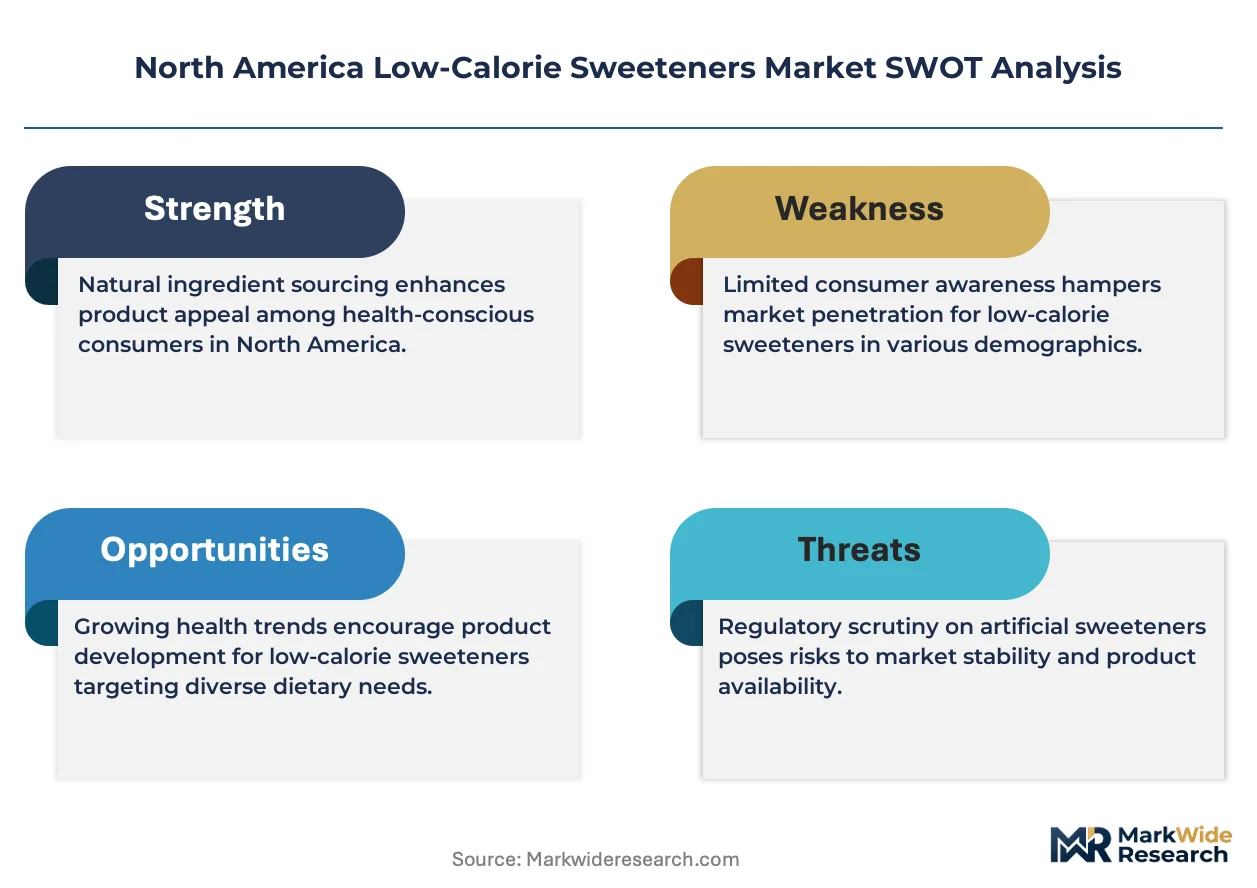
The FDA governs high-intensity sweetener safety through its food additive petition process and GRAS notification program, while Health Canada maintains parallel pre-market approval requirements that create dual compliance obligations for cross-border suppliers. The USDA's BioPreferred program and evolving EPA guidelines on fermentation effluent management are adding sustainability and environmental compliance dimensions to facility investment decisions. Stakeholders must monitor pending FDA guidance on novel sweetener blends and state-level sugar tax proposals that could abruptly alter demand trajectories across key consuming states.
Market Dynamics
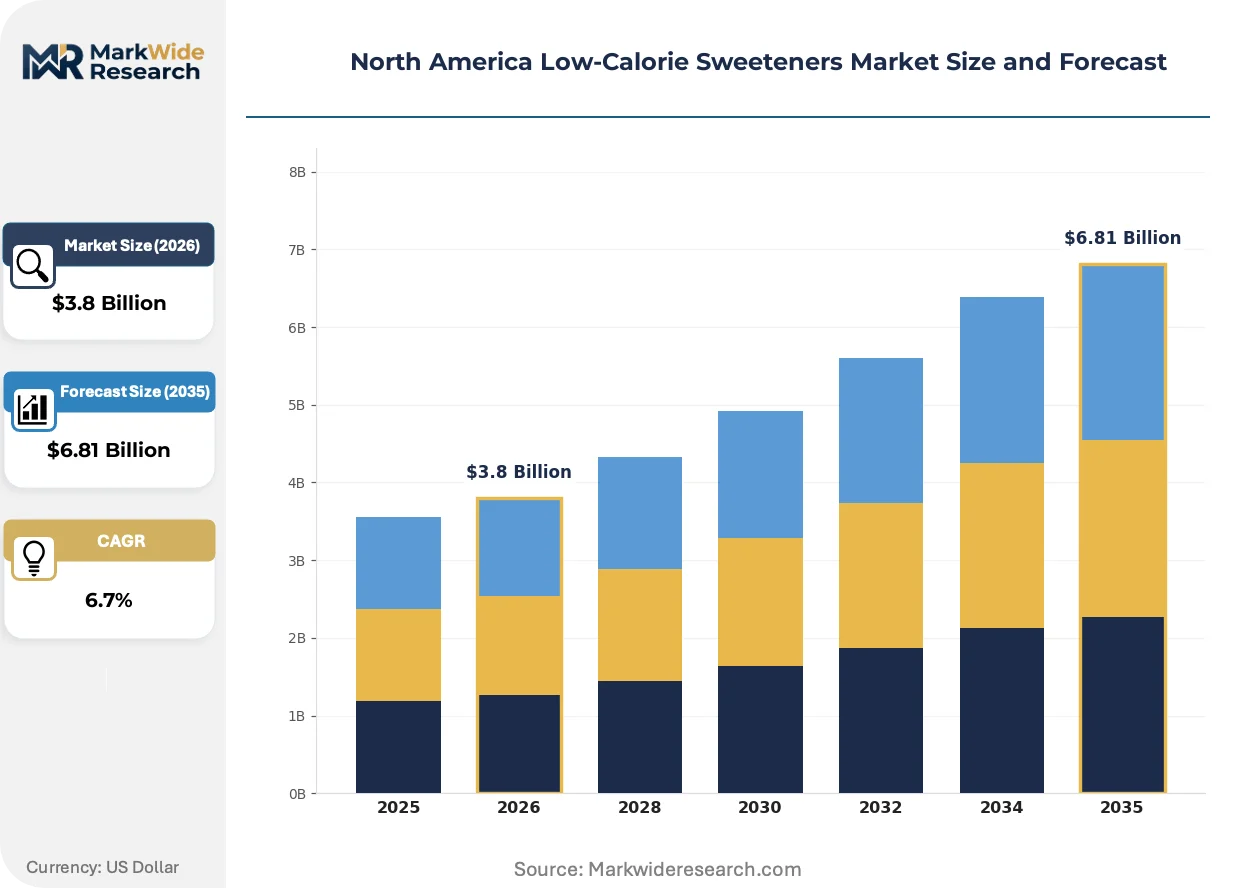
Beverage reformulation mandates from the FDA and Health Canada are compressing development cycles while corn-derived fermentation capacity concentrates in the Midwest, creating supply-demand tension between clean-label positioning and cost efficiency targets.
Growth Catalysts
- Front-of-Package Labeling:Health Canada's mandatory high-sugar warning symbols are forcing CPG manufacturers to accelerate reformulation timelines, expanding procurement volumes for high-intensity alternatives.
- Fermentation Scale-Up:Bioprocess engineering advances in Iowa and Illinois are reducing unit costs for erythritol and allulose, enabling broader adoption across mid-tier beverage brands.
- Steviol Glycoside Extraction:Purification thresholds exceeding ninety-five percent are unlocking clean-label positioning in premium ready-to-drink tea segments across the United States.
Market Restraints
- Corn Price Volatility:Feedstock cost swings for dextrose-based fermentation create margin compression for bulk sweetener producers dependent on Midwest grain markets.
- Dual Compliance Burden:Divergent FDA and Health Canada approval timelines for novel sweetener blends delay cross-border product launches and inflate regulatory overhead.
- Aftertaste Limitations: Lingering sensory profiles in monk fruit extracts restrict penetration in mainstream carbonated soft drinks where sucralose maintains taste acceptance.
Strategic Opportunities
- Underpenetrated Mexican Market:Latin American beverage manufacturers represent nascent demand for U.S.-exported fermentation-based sweeteners as sugar tax proposals advance in state legislatures.
- USDA BioPreferred Procurement:Federal purchasing preferences for biobased ingredients are opening institutional foodservice channels previously dominated by conventional sugar.
- Precision Fermentation Convergence:Integration of synthetic biology with existing corn-processing infrastructure enables novel rare sugar production at commercial scale.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Fermentation scale-up expertise concentrates at a handful of Midwest universities, constraining facility expansion timelines for new market entrants.
- GRAS Notification Backlogs:FDA review delays for novel sweetener blends extend go-to-market cycles beyond eighteen months, freezing R&D investment decisions.
- Legacy Equipment Retrofit Costs:Powder handling systems designed for sucrose require capital-intensive modifications to accommodate hygroscopic high-intensity alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Low-Calorie Sweeteners Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspartame, Sucralose, Stevia, Acesulfame K Application: Beverages, Bakery, Dairy, Confectionery End User: Household, Food Industry, Beverage Industry, Pharmaceutical Form: Liquid, Powder, Granular, Tablet |
| Companies Covered | Cargill, Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Ajinomoto Health & Nutrition North America, Inc., Koninklijke DSM N.V., DuPont de Nemours, Inc., Ingredion Incorporated, Roquette Frères, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Low-Calorie Sweeteners Market Evolving Landscape
Biotechnology advances and regulatory disclosure requirements are converging to reshape how sweetener suppliers demonstrate value, shifting competition from purity metrics toward carbon intensity transparency and clean-label substantiation.
Enzymatic conversion of corn starch to allulose is electrifying production economics for this rare sugar, enabling food manufacturers to achieve deeper caloric reduction without reformulating texture systems. Major bakery and frozen dessert producers in the United States are integrating allulose at commercial scale, compressing the price premium versus erythritol from triple-digit percentages to mid-single digits within three production cycles.
The FDA's pending guidance on fermented sweetener labeling nomenclature is forcing suppliers to pre-emptively standardize identity claims before enforcement actions commence. This regulatory friction most acutely affects stevia-fermentation hybrids, where manufacturers must distinguish between extracted glycosides and bioconverted variants to maintain consumer trust. Canadian import documentation requirements are tightening in parallel, creating dual-track compliance investments for cross-border suppliers.
Carbon accounting is displacing traditional procurement criteria as large beverage buyers unbundle supplier selection from landed cost alone. Nestlé Waters and PepsiCo procurement teams now require Scope 3 emissions disclosures for corn-derived inputs, favoring Midwest processors with captive ethanol-to-sweetener conversion and renewable energy offtake agreements. This behavioral shift concentrates contract awards among vertically integrated suppliers with verified biogenic carbon claims, marginalizing toll manufacturers without traceability infrastructure.
North America Low-Calorie Sweeteners Market Segmentation
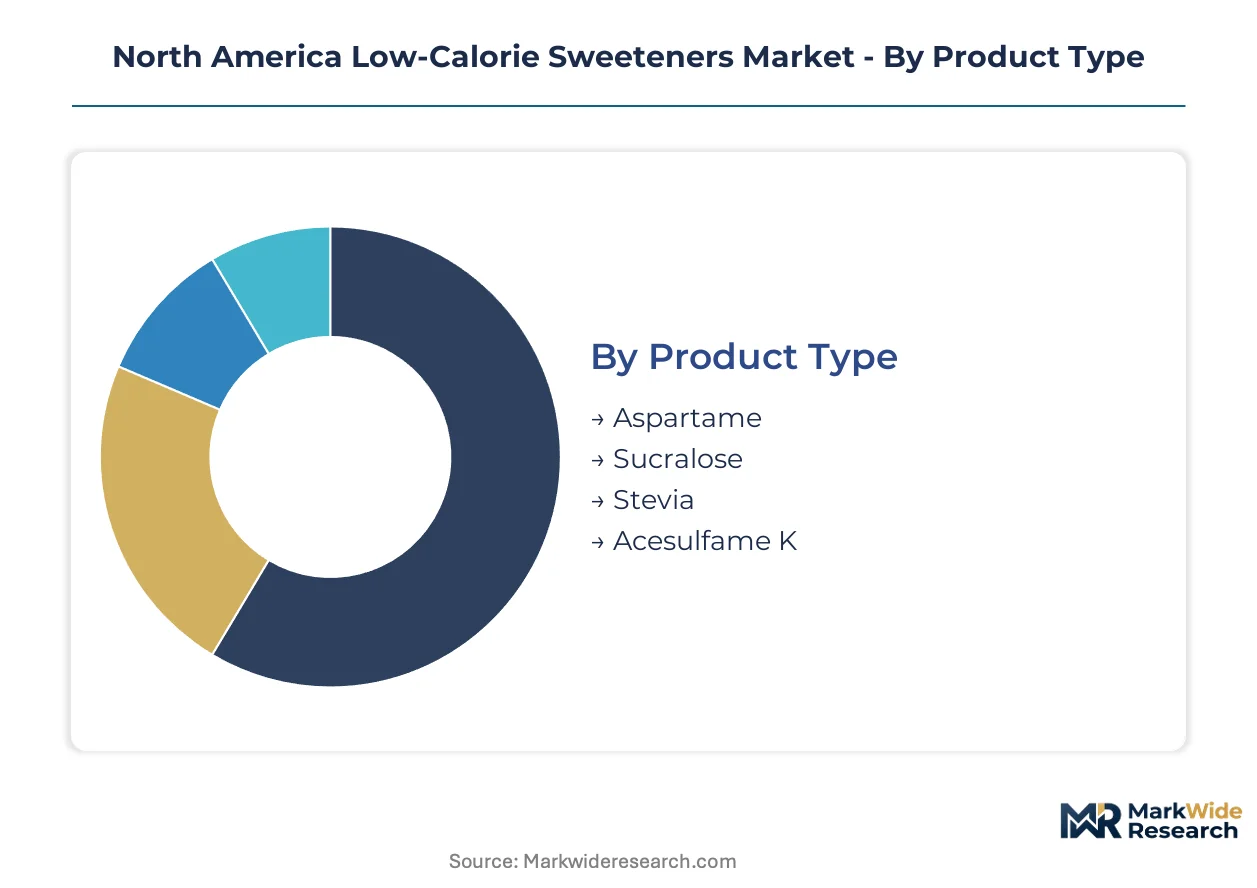
Segmentation in the North America low-calorie sweeteners market reveals divergent procurement patterns between mass-market beverage manufacturers seeking cost efficiency and premium food brands prioritizing clean-label positioning. Understanding these splits enables suppliers to align fermentation capacity and extraction investments with actual demand concentration.
Product Type:
Standardization dominates high-volume fermentation outputs, while customization concentrates in steviol glycoside extraction where purity thresholds and blend ratios vary by end-use specification.
- Stevia:Extracted steviol glycosides with purity exceeding ninety-five percent enable clean-label claims in premium ready-to-drink tea segments across the United States. FDA guidance on fermented versus extracted labeling nomenclature is forcing suppliers to segregate bioconverted variants to maintain consumer trust.
- Sucralose:Chemically synthesized from sucrose, this high-intensity sweetener delivers cost efficiency in mass-market carbonated soft drinks where taste acceptance remains paramount. Procurement volumes concentrate with beverage manufacturers in the Midwest and Southeast United States.
- Aspartame:Fermentation-derived phenylalanine-based compound serving diet carbonated beverages and tabletop sweetener applications.
- Acesulfame K:Synthetic high-intensity sweetener blended with sucralose or aspartame to mask aftertaste in sugar-free gum and confectionery.
Leading the category by volume: sucralose. Expanding most quickly: stevia.
Application:
Volume scale separates beverage procurement from bakery and dairy, where reformulation complexity and texture system requirements create specification fragmentation.
- Beverages:Carbonated soft drinks, ready-to-drink teas, and flavored waters represent the largest procurement base, with manufacturers leveraging high-intensity sweeteners to meet FDA and Health Canada sugar reduction mandates. Allulose integration is accelerating in functional beverage segments.
- Bakery:Maillard reaction limitations and moisture retention requirements drive demand for bulk sugar substitutes like erythritol and allulose in reduced-calorie breads and pastries.
- Dairy:Yogurt and ice cream applications require cold-soluble formulations with clean flavor release profiles.
- Confectionery:Sugar-free chocolates and hard candies depend on polyol blends to manage cooling effects and crystallization behavior.
Dominant by procurement tonnage: beverages. Steepest expansion trajectory: bakery.
End User:
Customer type determines packaging format and specification intensity, with industrial buyers driving bulk powder volumes and household channels requiring retail-ready unitization.
- Beverage Industry:Concentrated demand from carbonated soft drink and ready-to-drink tea producers in the United States, where reformulation timelines compress in response to front-of-package labeling regulations. Procurement contracts emphasize carbon accounting and Scope 3 emissions disclosures.
- Food Industry:Bakery, dairy, and confectionery manufacturers specify blends tailored to texture and shelf stability requirements.
- Household:Retail tabletop sweeteners in packet and pourable formats serve diabetic and weight-management consumers.
- Pharmaceutical:Excipient applications in chewable tablets and liquid formulations require USP-grade certification.
Largest volume concentration: beverage industry. Gaining share fastest: food industry.
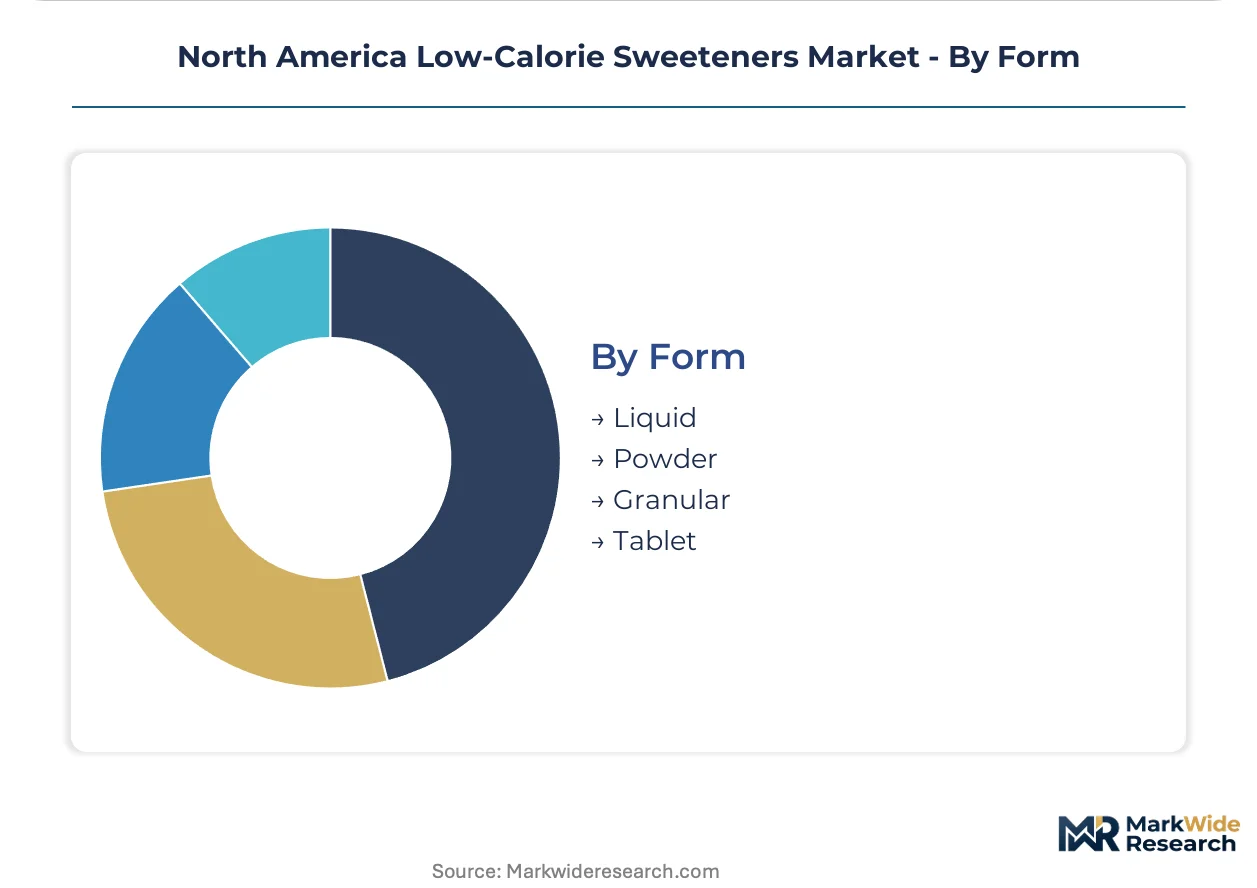
Form:
Handling efficiency and hygroscopicity management separate industrial-grade powder and granular formats from liquid and tablet alternatives serving specialized applications.
- Powder:Spray-dried and crystalline forms dominate industrial procurement for high-throughput beverage and bakery manufacturing, offering shelf stability and dosing precision in automated handling systems.
- Granular:Free-flowing crystals designed for direct tabletop use and small-scale foodservice applications where visual parity with sucrose matters.
- Liquid:Pre-dissolved concentrates serving beverage fountain systems and pharmaceutical syrup formulations.
- Tablet:Compressed formats for pharmaceutical excipients and portable consumer sweetener dispensers.
Leading by industrial procurement volume: powder. Climbing the fastest: liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn belt counties across Iowa and Illinois anchor North American fermentation capacity for dextrose-derived sweetener production. This feedstock concentration shapes procurement economics for beverage reformulators from Ontario to Mexico City.
United States
Carbonated soft drink manufacturers in Atlanta and Purchase drive bulk sucralose and aspartame procurement volumes. FDA nutrition labeling mandates compress reformulation timelines for legacy brands. Corn milling clusters in Decatur, Illinois, and Blair, Nebraska, sustain captive ethanol-to-sweetener conversion infrastructure.
Canada
Ready-to-drink tea producers in Toronto and Vancouver accelerate steviol glycoside adoption for clean-label positioning. Health Canada front-of-package high-sugar warning symbols force CPG acceleration. Montreal-area food scientists specialize in cold-soluble formulation for dairy applications.
Mexico
Beverage bottlers in Mexico City and Monterrey represent nascent demand for U.S.-exported fermentation-based inputs. State-level sugar tax proposals in Nuevo León and Jalisco signal regulatory convergence with northern neighbors. Guadalajara distribution hubs consolidate cross-border sweetener logistics.
North America Low-Calorie Sweeteners Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and rare sugar synthesis. The supplier base concentrates among agricultural processors with captive corn supply and chemical synthesis specialists with phenylalanine expertise. Three archetypes dominate: integrated agribusiness conglomerates, fermentation-scale bioprocess engineers, and extraction-focused natural ingredient specialists. Capacity expansion and backward integration into dextrose supply represent the primary competitive vectors.
Among integrated agribusiness conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify the Midwest-based model combining grain origination with downstream sweetener refinement. Tate & Lyle PLC occupies a position within the specialty formulation tier, representing European-headquartered expertise applied to North American starch and sweetener applications. These three anchors illustrate how geographic proximity to corn belt feedstock and regulatory fluency across FDA and Health Canada jurisdictions shape sustainable contract positioning.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Ajinomoto Health & Nutrition North America, Inc. |
| Koninklijke DSM N.V. |
| DuPont de Nemours, Inc. |
| Ingredion Incorporated |
| Roquette Frères |
| Celanese Corporation |
| Others |
Value Network & Pricing Analysis
Carbon accounting mandates from Nestlé Waters and PepsiCo procurement teams are forcing Midwest processors to invest in traceability infrastructure, compressing margins for toll manufacturers without captive ethanol-to-sweetener conversion capabilities.
Pricing Analysis
Carbon intensity disclosure bundling now separates contract winners from commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and Scope 3 emissions verification status. Cost compression in standard-tier fermentation outputs is intensifying because corn price volatility feeds directly into dextrose-based production economics. Mid-tier beverage brands exhibit the highest price sensitivity, while premium ready-to-drink tea manufacturers absorb clean-label premiums for verified steviol glycoside extraction.
Supply Chain Analysis
Regional distribution centers in Decatur, Illinois and Blair, Nebraska operate hub-and-spoke patterns feeding beverage manufacturers across the United States and Canada. Supply concentrates in Iowa and Illinois corn belt counties, with secondary processing nodes in Ontario serving Health Canada-compliant formulations. Raw material flows draw from Midwest grain markets, fermentation dextrose, and stevia leaf imports. Single-source vulnerability in bioprocess engineering talent constrains facility expansion timelines. Distribution runs through integrated agribusiness conglomerates with captive corn milling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GRAS notification backlogs exceeding eighteen months are accelerating consolidation, forcing capital-constrained toll manufacturers to exit as vertically integrated processors capture contract awards.
For Market Incumbents: Hedge against regulatory friction by pre-emptively segregating fermented versus extracted steviol glycoside inventory before FDA enforcement actions commence. Deepen backward integration into renewable energy offtake agreements to satisfy Scope 3 disclosure requirements from large beverage buyers. Precision fermentation convergence represents the priority R&D lever for rare sugar production at commercial scale. For New Entrants and Emerging Players: Capture underpenetrated procurement relationships with Mexican beverage bottlers in Mexico City and Monterrey before state-level sugar tax proposals mature. Precision fermentation expertise offers the most penetrable wedge against established corn-derived fermentation capacity. Lead with carbon-negative positioning and biogenic carbon verification to differentiate from Midwest incumbents. For Investors and Strategic Acquirers: The window for entry favors fermentation-scale bioprocess engineers with existing Health Canada regulatory fluency and Midwest facility footprints. Long-term viability hinges on backward integration into dextrose supply rather than toll manufacturing dependence. Watch FDA guidance on novel sweetener blends as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Milling | Cargill and ADM sustain cost advantages through captive dextrose supply from Iowa and Illinois facilities. |
| Precision Fermentation Scale-Up | Synthetic biology integration enables commercial rare sugar production beyond conventional fermentation outputs. |
| Carbon Accounting Infrastructure | Verified biogenic carbon claims now determine contract awards from Nestlé Waters and PepsiCo procurement teams. |
| Dual Regulatory Compliance Investment | Parallel FDA and Health Canada approval capabilities unlock cross-border product launches and reduce launch delays. |
| Renewable Energy Offtake Agreements | Midwest processors with wind and solar contracts satisfy Scope 3 emissions disclosures required by institutional buyers. |
Research Methodology
Document review covered FDA food additive petitions, Health Canada pre-market approval filings, and USDA BioPreferred program records, complemented by interviews with fermentation plant managers, beverage procurement leads, and regulatory affairs directors at sweetener suppliers. Secondary validation drew from SEC 10-K filings, customs trade data, and industry association reports. Bottom-up capacity assessments and top-down demand modeling were triangulated against primary fieldwork.
Cross-referencing historical price trajectories against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and form, with additional granularity on carbon intensity tier and regulatory approval status. CAGRs were derived from supply-demand balance modeling and capacity expansion timelines. Forecast inputs incorporated corn price volatility indices and GRAS notification queue status.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pending FDA guidance on novel sweetener blends and state-level sugar tax adoption patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Tagatose Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Date Sugar Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Sweet Modulator Market
Sweeteners
Corn Syrup Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Compressible Sugar Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
United States Xylitol Market