
 Icing Sugar Market | 2026-2036
Icing Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Icing Sugar Market Analysis
The EU Green Deal is recalibrating sourcing priorities across European sugar refiners by mandating lower-carbon cultivation benchmarks. Südzucker leverages integrated beet-to-bag operations across Central European processing plants. Cargill anchors North American supply through corn-derived sweetener diversification and foodservice channel control. Nordzucker AG specializes in certified organic icing grades for premium bakery accounts.
Icing sugar denotes sucrose milled to sub-100-micron particle size with anti-caking agents such as tricalcium phosphate or cornstarch to ensure flowability in humid conditions. The material dissolves instantly upon liquid contact, making it indispensable for fondant, royal icing, and glaze formulations in commercial and artisanal settings. Powdered sugar dominates volume within the product type split due to universal adoption across industrial bakeries and confectionery lines. The confectionery application commands the fastest expansion as chocolate enrobing and panned candy production scale in emerging markets. Home bakers represent a margin-rich end-user segment where specialty and organic variants sustain price premiums through specialty store and online channels.
The FDA maintains food-grade purity standards under 21 CFR while the EPA regulates wastewater discharge from sugar refineries, both shaping compliance costs for domestic producers. REACH and EFSA frameworks in Europe impose maximum residue limits for pesticides in beet-sourced raw material, directly filtering which suppliers qualify for continental distribution. Stakeholders must monitor evolving clean-label certifications and carbon-border adjustment mechanisms to preserve market access across regulatory jurisdictions.
Market Dynamics
The EU Green Deal's carbon-border adjustment mechanisms are forcing sugar refiners to restructure beet sourcing and processing footprints to maintain continental market access.
Growth Catalysts
- Clean-label certification mandates:REACH and EFSA pesticide residue limits are filtering supplier pools, creating competitive advantage for integrated beet-to-bag operators who control cultivation compliance.
- Artisanal bakery expansion:Germany's industrial baking corridor is scaling specialty-grade procurement as craft producers commercialize regional heritage recipes requiring sub-100-micron particle specifications.
- Confectionery automation:Chocolate enrobing and panned candy lines in emerging markets are standardizing on instant-dissolve formulations to accelerate production throughput.
Market Restraints
- Input cost volatility:Natural gas prices for beet processing and cornstarch anti-caking agent supply create margin compression for non-integrated refiners.
- Supply concentration risk:Central European processing plant networks dominate high-grade output, exposing buyers to single-region weather and energy disruption.
- Substitution pressure:Erythritol and allulose blends are capturing clean-label confectionery formulations where crystalline structure requirements permit.
Strategic Opportunities
- Organic certification tier:Premium bakery accounts in France and Italy are contracting multi-year supply for certified organic icing grades at sustained price premiums.
- Direct-to-baker channels:E-commerce platforms and specialty store networks are disintermediating traditional foodservice distribution for home baker segments.
- Carbon-border positioning:Early compliance with EU Green Deal benchmarks creates export eligibility advantages as third-country suppliers face adjusted tariff exposure.
Industry Challenges
- Retrofitting legacy refineries:Wastewater discharge compliance under EPA and REACH frameworks requires capital-intensive anaerobic digestion upgrades at aging Central European facilities.
- Particle specification talent scarcity:Milling engineers capable of maintaining sub-100-micron consistency across humidity-variable climates command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Icing Sugar Market |
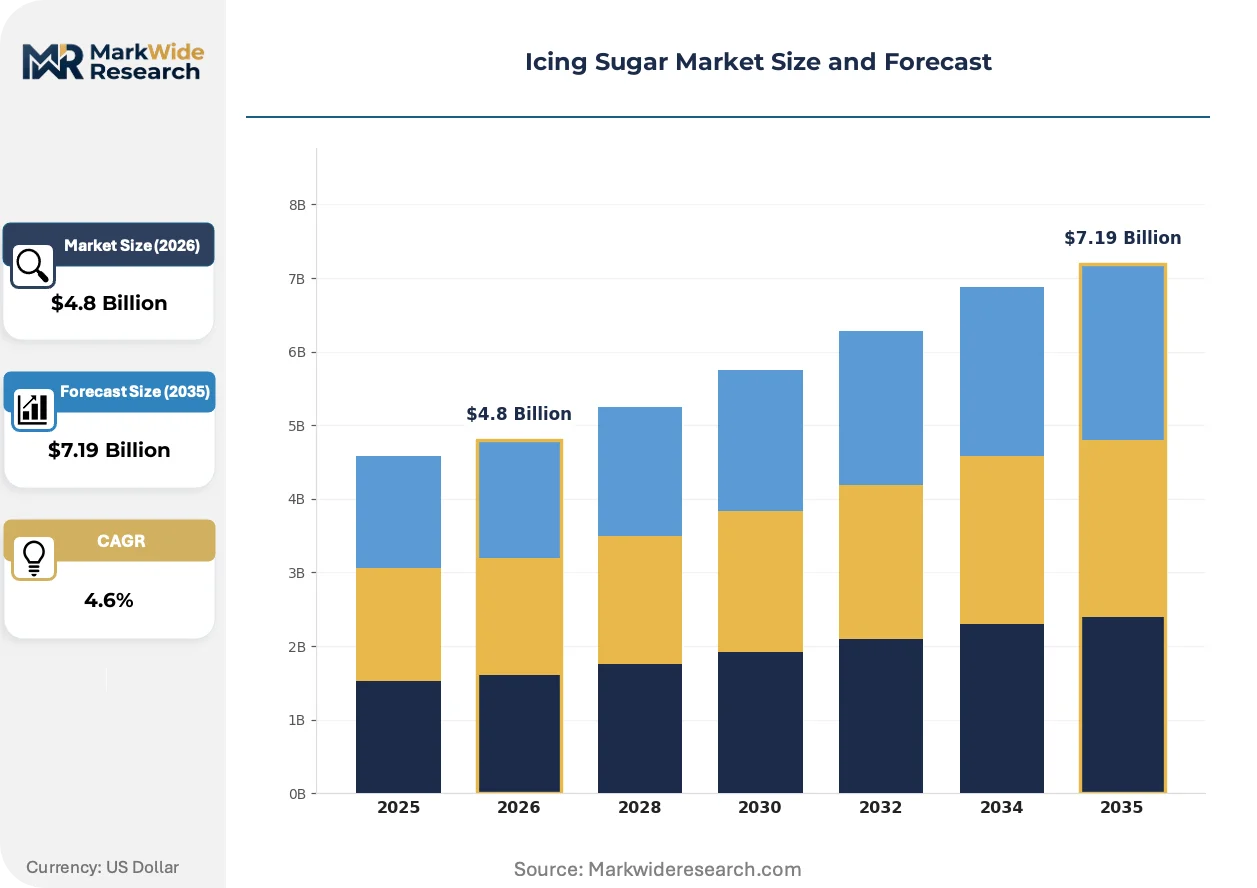
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Sugar, Granulated Sugar, Organic Sugar, Flavored Sugar Application: Baking, Confectionery, Desserts, Beverage End User: Food Manufacturers, Bakeries, Restaurants, Home Bakers Distribution Channel: Wholesale, Retail, Online, Specialty Stores |
| Companies Covered | Wilmar Sugar, U.S. Sugar, Cargill, Imperial Sugar, Nordzucker AG, Südzucker, Bundaberg Sugar, Mitr Phol Group, American Crystal Sugar Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Icing Sugar Market Emerging Trajectories
Digital traceability and precision milling technologies are compressing quality variance while regulatory carbon accounting is embedding sustainability verification into procurement specifications.
Air-classification milling systems with real-time particle-size feedback loops are consolidating quality control within single-pass processing. Industrial bakeries in Germany and France are retrofitting lines to accept these tighter-specification inputs. The technology is consolidating regional supplier tiers by disqualifying batch-variance-dependent operations.
REACH authorization requirements for processing aids are extending compliance documentation burdens through the value chain. Sugar refiners must now certify anti-caking agent provenance back to phosphate rock or corn origin. Confectionery exporters to the European Union are responding by qualifying dedicated low-residue supply chains ahead of 2027 enforcement milestones.
Home bakers are migrating toward subscription-based ingredient curation that bundles specialty icing grades with recipe content. This channel is displacing conventional retail shelf purchasing in urban UK and US markets. The shift is most visible in direct-to-consumer platforms targeting holiday baking cycles with limited-edition organic variants.
Icing Sugar Market Segmentation
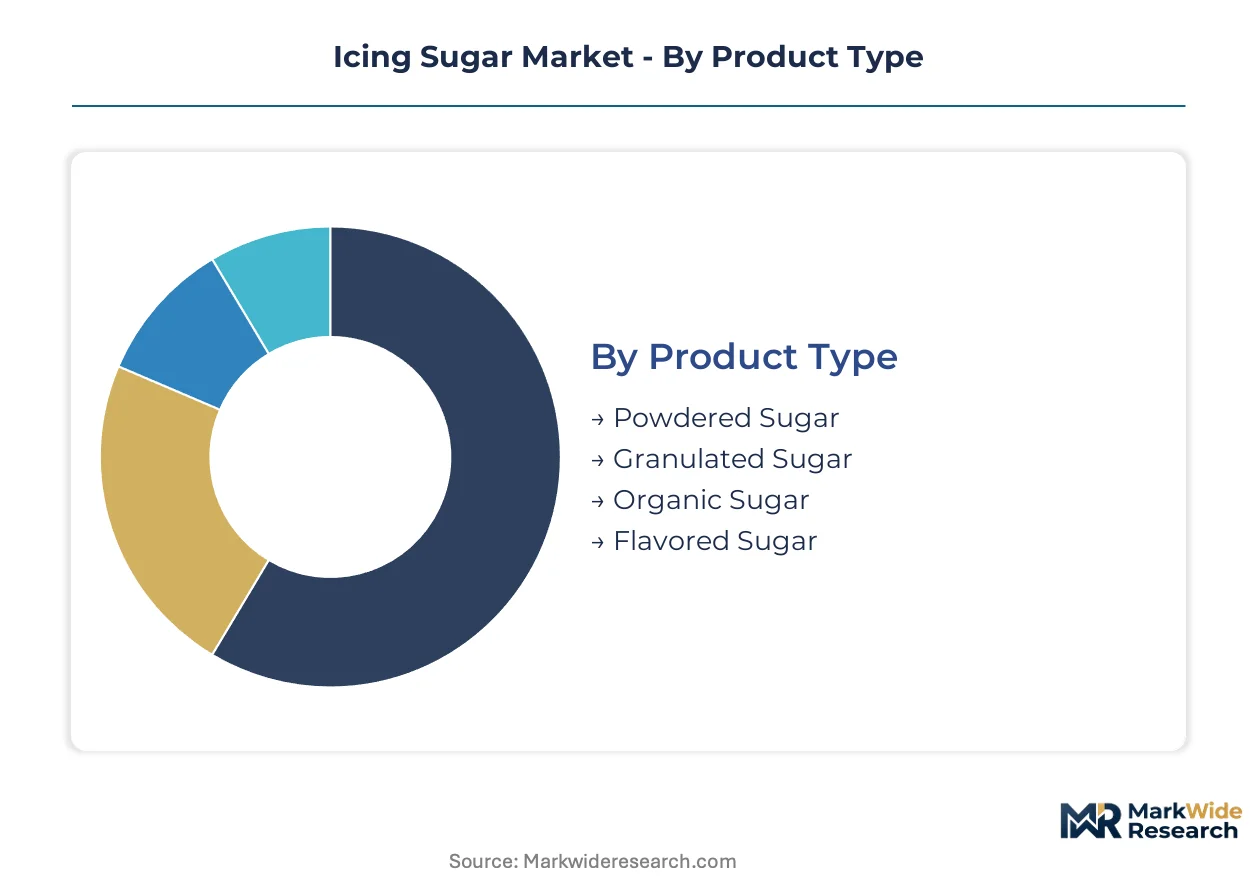
Icing sugar procurement patterns diverge sharply between high-volume industrial buyers and premium-segment artisanal operators. Sub-100-micron particle specifications and anti-caking agent formulations create tiered price bands that reshape supplier selection across end-use categories.
Product Type:
Volume leadership sits with commodity-grade milled sucrose, while certified organic and specialty variants capture margin expansion in premium channels.
- Powdered Sugar:Standard sucrose milled to sub-100-micron particle size with tricalcium phosphate or cornstarch anti-caking agents. Industrial bakeries in Germany's processing corridor specify this grade for fondant and royal icing formulations at scale. REACH compliance documentation for anti-caking provenance is becoming mandatory for EU market access.
- Granulated Sugar:Coarser crystalline structure above 200 microns, typically reserved for applications where controlled dissolution speed matters. Beverage manufacturers and some confectionery lines in emerging markets favor this grade for cost efficiency in bulk procurement.
- Organic Sugar:Beet or cane sourced under certified cultivation protocols with full pesticide residue traceability. French and Italian premium bakery accounts contract multi-year supply at sustained price premiums.
- Flavored Sugar:Vanilla, citrus, or spice-infused variants targeting home baker subscription channels and specialty retail. UK direct-to-consumer platforms bundle these with recipe content for holiday baking cycles.
Mature deployment sits with powdered sugar. Newer deployment is concentrated in organic certification tiers.
Application:
Commercial throughput requirements versus artisanal finishing precision determine formulation specifications and procurement channel selection.
- Baking:Industrial-scale fondant production and laminated dough finishing in Germany's industrial baking corridor. Air-classification milling systems with real-time particle feedback are consolidating supplier tiers by disqualifying batch-variance operations.
- Confectionery:Chocolate enrobing and panned candy lines in emerging markets standardize on instant-dissolve formulations. This segment is climbing the fastest as automation scales production throughput.
- Desserts:Pastry cream stabilization and mousse aeration in restaurant and foodservice settings. Margin compression from natural gas processing costs affects non-integrated refiners serving this mid-tier segment.
- Beverage:Ready-to-drink cocktail mixes and specialty coffee preparations. Flavored sugar variants gain traction in urban UK and US direct-to-consumer channels.
Established demand concentration rests with baking applications. Emerging deployment centers on confectionery automation.
End User:
Procurement scale and specification tolerance separate commodity buyers from premium-segment operators seeking certified provenance.
- Food Manufacturers:Integrated production lines requiring consistent sub-100-micron particle distribution for automated depositing equipment. Carbon-border adjustment compliance is filtering supplier pools ahead of enforcement milestones.
- Bakeries:Range from industrial-scale German operations to French and Italian artisanal producers. Heritage recipe commercialization drives specialty-grade procurement with strict particle specifications.
- Restaurants:Dessert finishing and beverage programs in foodservice settings. Cost pressure from input volatility favors granulated sugar where crystalline structure permits.
- Home Bakers:Margin-rich segment migrating toward subscription-based ingredient curation. E-commerce platforms displace conventional retail shelf purchasing in urban markets.
Volume concentration aligns with food manufacturers. Value expansion concentrates in home baker direct channels.
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and certification documentation requirements.
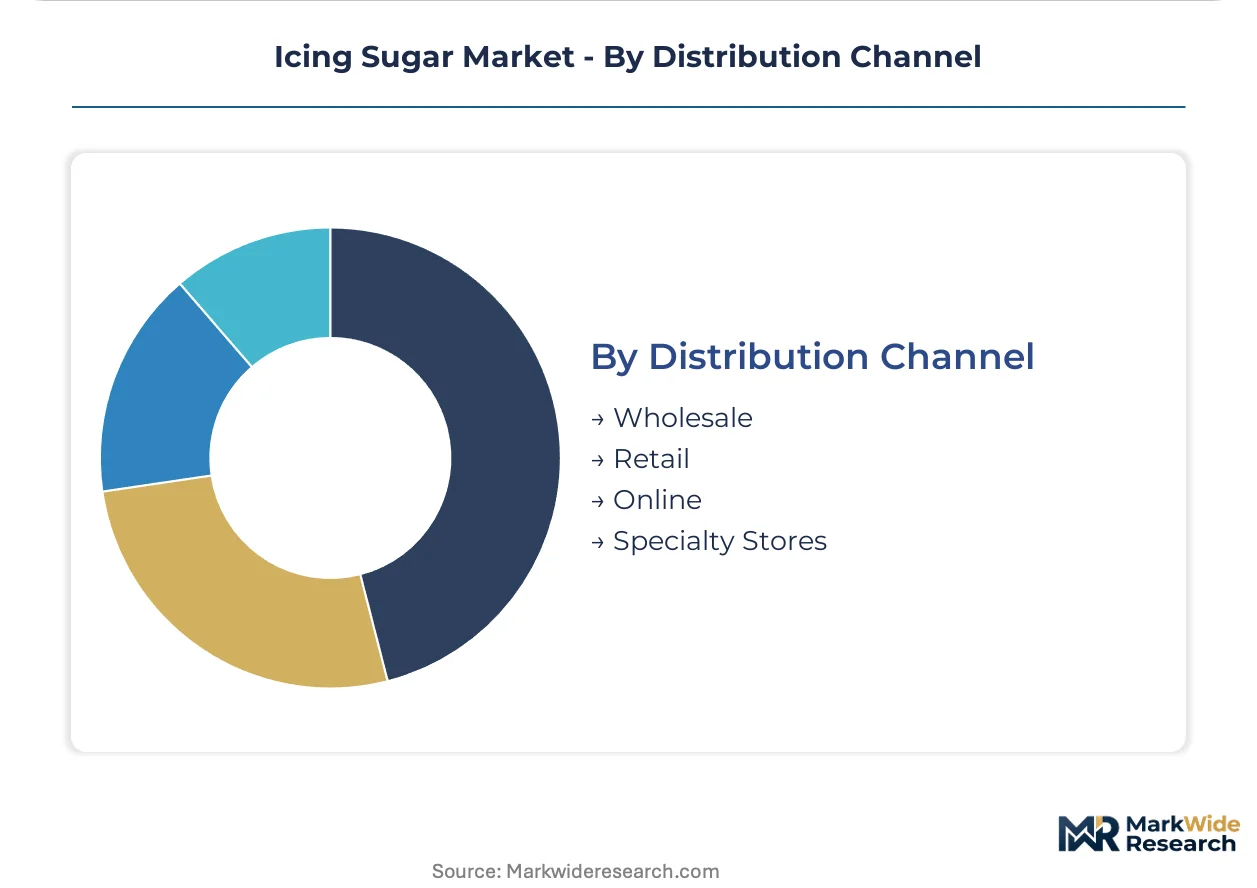
- Wholesale:Bulk procurement by industrial bakeries and food manufacturers with dedicated logistics contracts. Central European processing plant networks dominate high-grade output availability.
- Retail:Supermarket and mass-market shelf presence for standard powdered and granulated grades. Price competition intensifies as private-label offerings expand.
- Online:Direct-to-consumer platforms and subscription services targeting home bakers with specialty and organic variants. UK and US urban markets show fastest channel displacement.
- Specialty Stores:Premium bakery supply shops and culinary retailers in France, Italy, and Germany. Certified organic icing grades sustain price premiums through tactile quality verification.
Traditional volume flows through wholesale. Channel innovation is accelerating in online direct-to-consumer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial baking corridor stretching from Hamburg to Munich anchors continental demand for sub-100-micron icing grades. This concentration shapes procurement patterns across European sugar refiners and filters supplier qualification standards.
Germany
Artisanal bakery chains in Bavaria and Baden-Württemberg are commercializing heritage recipes requiring precise particle specifications. EU Green Deal carbon-border adjustment mechanisms are forcing beet-to-bag operators to document cultivation compliance. The Hamburg-Bremen processing cluster is retrofitting air-classification milling systems to maintain sub-100-micron consistency.
France
Premium bakery accounts in Île-de-France and Provence-Alpes-Côte d'Azur are contracting multi-year supply for certified organic icing grades. REACH authorization requirements for anti-caking agent provenance are extending documentation burdens through supply chains. Lyon-based specialty stores are sustaining price premiums through tactile quality verification of organic variants.
United States
Home baker subscription channels in urban Northeast and West Coast markets are displacing conventional retail shelf purchasing. FDA food-grade purity standards under 21 CFR and EPA wastewater discharge regulations are shaping compliance costs for domestic refiners. Chicago-area food manufacturers are standardizing on instant-dissolve formulations for automated depositing equipment.
United Kingdom
Direct-to-consumer platforms targeting holiday baking cycles are bundling specialty icing grades with recipe content. EFSA pesticide residue limits are filtering which suppliers qualify for continental distribution post-Brexit. London and Southeast England logistics hubs are consolidating last-mile delivery for premium organic variants.
Italy
Pastry cream stabilization demand in Emilia-Romagna and Lombardy foodservice settings favors granulated sugar where crystalline structure permits. EFSA frameworks impose maximum residue limits on beet-sourced raw material. Turin and Milan industrial bakeries are scaling specialty-grade procurement as regional heritage recipes gain export traction.
Icing Sugar Market Vendor Landscape
The competitive structure tilts toward integrated beet-to-bag operators with captive cultivation control. Central European processing networks dominate high-grade output, while North American players anchor supply through corn-derived diversification. Three archetypes define positioning: integrated agricultural processors, regional specialty refiners, and diversified commodity traders. Capacity expansion in precision milling and strategic partnerships for carbon-border compliance represent the dominant competitive moves.
Among integrated agricultural processors, Südzucker and Nordzucker AG exemplify the Central European archetype with beet-sourced operations. Cargill occupies a position representing North American corn-derived diversification and foodservice channel presence. These three entities anchor the supplier landscape across distinct geographic and feedstock vectors.
| Leading Market Players |
|---|
| Wilmar Sugar |
| U.S. Sugar |
| Cargill |
| Imperial Sugar |
| Nordzucker AG |
| Südzucker |
| Bundaberg Sugar |
| Mitr Phol Group |
| American Crystal Sugar Company |
| Others |
Supply Flow & Price Mechanics
Family-owned beet cultivation cooperatives across Central Europe anchor supply discipline through captive sourcing, translating cultivation compliance costs directly into contract pricing power over industrial bakery buyers. Their integrated beet-to-bag operations limit price volatility exposure while passing through EU Green Deal carbon-accounting premiums to downstream accounts.
Pricing Analysis
Value-based pricing anchored to dissolution-speed performance in automated confectionery lines separates premium sub-100-micron grades from commodity alternatives. Three-tier pricing structure across organic-certified, REACH-compliant standard, and unverified economy levels creates clear buyer segmentation. Pricing pressure stems from natural gas processing costs compressing margins at non-integrated refiners serving mid-tier dessert applications. Food manufacturers exhibit highest price sensitivity due to volume procurement scales, while home baker subscription channels absorb sustained premiums for certified organic variants.
Supply Chain Analysis
Freight cost differentials between Central European processing clusters and North American corn-derived alternatives reshape procurement calculus for transatlantic buyers. Supply concentrates in Germany, France, and Poland for beet-sourced high-grade output, while the United States anchors cornstarch anti-caking agent production. Raw material dependencies rest on sugar beet cultivation cycles, phosphate rock for tricalcium phosphate, and natural gas for processing energy. Single-region weather and energy disruption poses structural supply risk. Distribution runs through wholesale bulk contracts for industrial buyers and direct-to-consumer platforms for premium home baker segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air-classification milling systems with real-time particle feedback are displacing legacy batch-variance operations, compressing quality tolerance windows and consolidating supplier tiers around precision-engineering capabilities.
For Market Incumbents: Cement control over sub-100-micron specification consistency through precision milling capacity additions in Germany's Hamburg-Bremen corridor. Erythritol and allulose substitution pressure in clean-label confectionery demands defensive certification investments in organic and carbon-border-compliant grades to preserve bakery account contracts.
For New Entrants and Emerging Players: EU Green Deal carbon-border adjustment mechanisms in Europe open a window for third-country suppliers with early compliance documentation to capture displaced conventional import share. Target home baker subscription channels in UK and US urban markets with limited-edition organic variants bundled with recipe content, leveraging direct-to-consumer platform economics against incumbent retail shelf dominance.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated beet-to-bag operators with captive cultivation in Poland and eastern Germany facing legacy refinery retrofit burdens. Long-term viability hinges on anaerobic digestion wastewater compliance and precision milling engineering talent retention. Watch REACH authorization enforcement milestones for anti-caking agent provenance as inflection indicator for supplier qualification shakeouts.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Milling Capacity Expansion | Air-classification systems with real-time feedback consolidate supplier tiers by disqualifying batch-variance operations in Germany. |
| Backward Integration into Beet Cultivation | Captive sourcing secures EU Green Deal carbon-accounting compliance and filters pesticide residue exposure through controlled agriculture. |
| Organic Certification Program | Multi-year supply contracts with French and Italian premium bakery accounts sustain price premiums against commodity erosion. |
| Direct-to-Consumer Platform Launch | Subscription-based ingredient curation displaces conventional retail in UK and US urban home baker markets. |
| REACH Compliance Documentation Investment | Anti-caking agent provenance certification preserves continental market access ahead of enforcement milestones. |
Methodological Framework
Multi-period observation of particle specification adoption rates, carbon-border compliance documentation filings, and milling technology deployment anchored the trend analysis, supplemented by interviews with sugar refinery operations directors, industrial bakery procurement leads, specialty store buyers, confectionery line engineers, and home baker platform operators. Secondary validation drew from EU EFSA pesticide residue databases, REACH authorization registries, FDA 21 CFR food-grade standards, customs trade flows for beet and cornstarch inputs, and SEC filings of publicly traded processors. Bottom-up demand modeling across end-user segments triangulated against top-down value chain revenue estimates.
Segment-weighting approaches distributed value across product type tiers, application throughput requirements, end-user procurement scales, and distribution channel economics. CAGRs were derived from fitted growth curves applied to base-year sizing across the projection horizon. Forecast inputs incorporated EU Green Deal implementation pacing, natural gas price trajectory assumptions for processing energy, and substitution elasticity estimates for alternative sweeteners in clean-label formulations.
The model assumes a particular technology adoption path for air-classification milling systems; alternative pathways for legacy batch processing retention would alter the outlook through extended supplier fragmentation. Forecasts reflect documented assumptions regarding regulatory enforcement timing and input cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sanding Sugar Market
Sweeteners
China Food Sweetener Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Australia Allulose Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
South Korea Allulose Market
Sweeteners
Maltodextrin Market
Sweeteners
Food Sweetener Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Tagatose Market
Sweeteners
Sodium Saccharin Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
South America Stevia Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Low-Calorie Sweetener Market