
 Coconut Cream Powder Market | 2026-2036
Coconut Cream Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Cream Powder Market Analytics
Beverage applications are hardening as the dominant demand vertical for coconut cream powder, displacing traditional bakery dominance. Axelum Resources Corp. leverages its integrated Philippine supply chain to control raw material quality from plantation to powder. Nestle anchors global distribution reach through its existing plant-based beverage portfolios. S&P Industries Sdn Bhd specializes in spray-drying technology for lipid retention, competing on functional performance rather than commodity pricing.
Coconut cream powder consists of dehydrated coconut milk solids, typically containing 60-70% fat content, produced through spray-drying or drum-drying of fresh coconut kernel extract; it functions as a shelf-stable dairy alternative and fat source in formulated foods. Unsweetened variants lead volume due to cleaner-label positioning and formulation flexibility across industrial accounts. Organic certification commands premium positioning, though conventional grades still occupy the bulk of hospitality procurement. Pouch packaging is displacing tins in retail channels, while bulk formats dominate exporter transactions to food manufacturers.
FDA GRAS status and USDA organic certification govern US market access, while REACH compliance and EU deforestation regulation shape European import requirements. BIS standards in India and FSSAI labeling mandates create layered compliance obligations for multi-destination suppliers. Stakeholders must monitor evolving EUDR traceability deadlines and shifting palm oil substitution dynamics that could accelerate or constrain coconut cream powder uptake in confectionery reformulations.
Market Dynamics
The EU Green Deal's deforestation-free supply chain requirements are forcing coconut cream powder suppliers to rebuild traceability infrastructure from plantation to port, compressing margins for non-integrated processors while advantaging plantation-backed operators.
Growth Catalysts
- Plant-based beverage reformulation:Coffee chains and ready-to-drink manufacturers are substituting coconut cream powder for dairy and synthetic creamers to meet clean-label mandates.
- REACH compliance upgrades:European food manufacturers are qualifying coconut-derived fat sources ahead of tightened contaminant thresholds for lipid-based ingredients.
- Indonesian raw material concentration:Sulawesi and North Sumatra plantation clusters provide year-round kernel supply with lower moisture variance than competing origins.
Market Restraints
- Copra price volatility:Coconut oil futures on the Bursa Malaysia Derivatives exchange transmit directly to cream powder input costs, squeezing fixed-contract food service suppliers.
- Philippine supply concentration risk:Typhoon corridor exposure across Eastern Visayas and Mindanao creates single-origin vulnerability for buyers without multi-source hedging.
- Spray-drying energy intensity:Natural gas-fired atomization accounts for substantial production cost, disadvantaging processors in jurisdictions without subsidized fuel.
Strategic Opportunities
- Vietnamese processing expansion:New spray-drying capacity in Ben Tre and Tra Vinh provinces offers lower-cost organic certification pathways than established Philippine facilities.
- Confectionery fat substitution:Palm oil displacement in chocolate and compound coatings opens formulation trials for coconut cream powder as a tropical fat with cleaner traceability.
- EUDR traceability infrastructure:Early compliance investment creates supplier lock-in with European dairy alternatives manufacturers facing 2025 due diligence deadlines.
Industry Challenges
- Organic certification timeline compression:Three-year conversion periods for plantation land create supply gaps during demand surges for certified ingredients.
- Spray-drying technician scarcity:Lipid retention optimization requires specialized process engineering talent concentrated in Malaysian and Thai equipment vendor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Cream Powder Market |
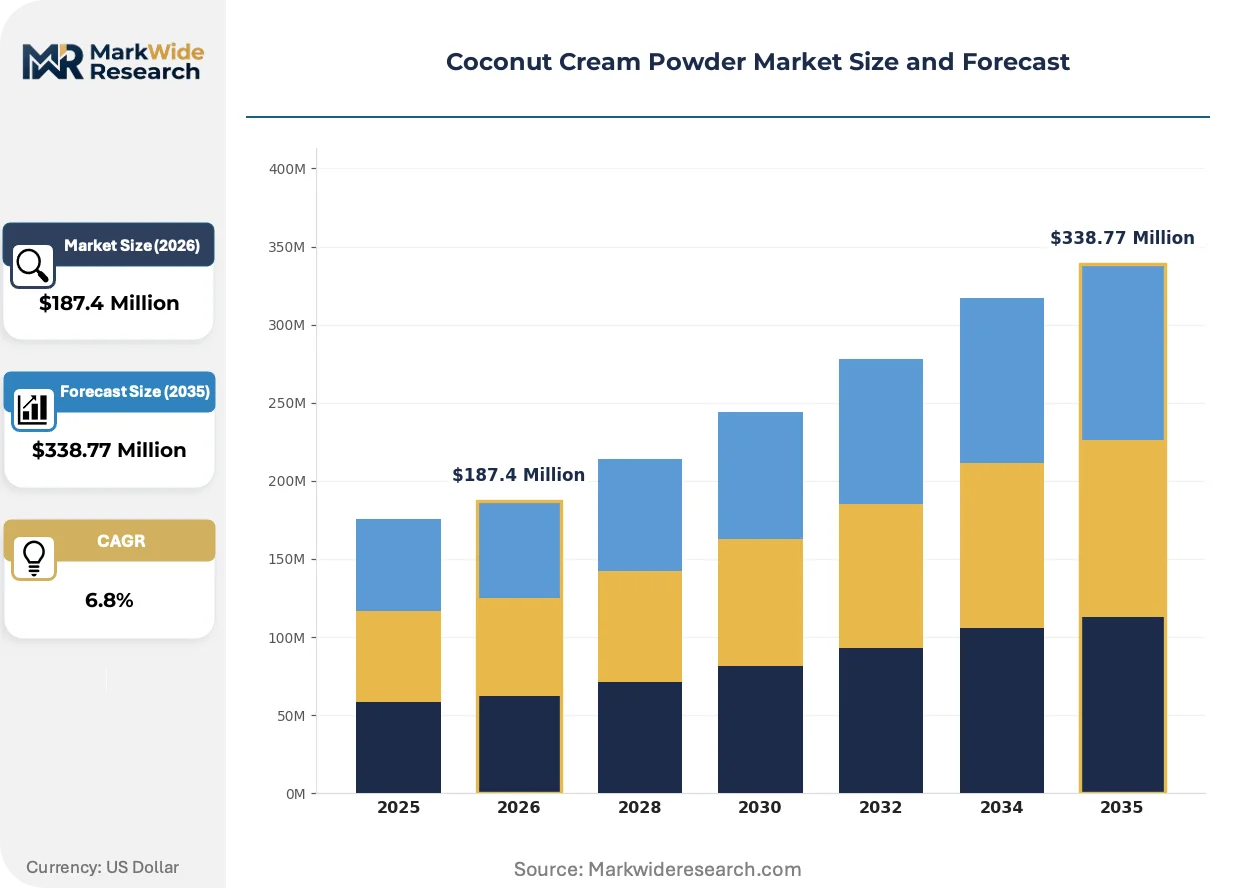
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened, Unsweetened, Organic, Conventional Application: Bakery, Confectionery, Beverages, Sauces End User: Food Industry, Hospitality, Retail, Exporters Packaging Type: Bags, Tins, Pouches, Bulk |
| Companies Covered | Axelum Resources Corp., Renuka Foods, Nestle, Earth Circle Organics, Cocomi Bio Organic, The Coconut Company, S&P Industries Sdn Bhd, Asia Saigon Food Ingredients AFI, Kara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Cream Powder Market Evolving Landscape
Processing technology and procurement protocols are rewriting how coconut cream powder moves from plantation to formulated food, with implications for cost structure and supplier selection criteria.
Encapsulation technology using modified starch and maltodextrin carriers is rewriting shelf-stability performance for high-fat coconut cream powder. Beverage manufacturers in North America are adopting these grades for single-serve stick packs, compressing the traditional bulk-drum supply chain into direct-to-factory powder dosing systems.
EU deforestation regulation (EUDR) implementation timelines are forcing traceability system investments across Southeast Asian supply bases. Coconut processors must deploy satellite-linked plantation mapping and mass-balance documentation to maintain European market access, with compliance costs falling heaviest on smallholder-dependent aggregators in the Philippines.
Direct contracting between plantation groups and end-use formulators is displacing traditional commodity broker channels. Specialty coffee roasters and plant-based dairy startups in Germany and the Netherlands are sourcing through verified cooperative networks, bypassing regional trading houses that previously controlled price discovery and quality arbitrage.
Coconut Cream Powder Market Segmentation
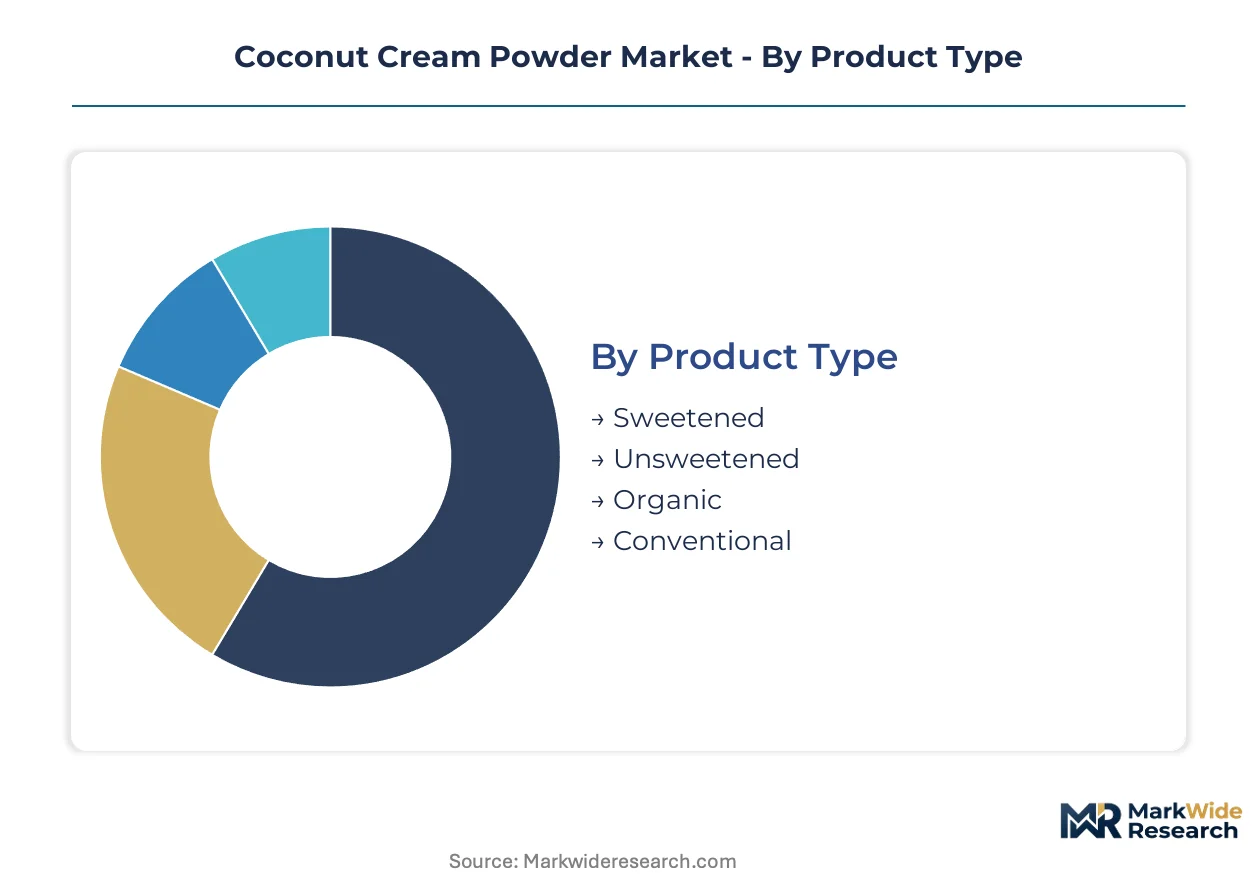
Segmentation in coconut cream powder reveals how formulation flexibility, packaging economics, and end-use specifications reshape procurement patterns across industrial and retail channels. Buyers select grades based on fat retention requirements, shelf-life demands, and clean-label positioning rather than commodity pricing alone.
Product Type:
Standardization dominates at the commodity end, while premium tiers demand plantation-level traceability and certified organic conversion documentation.
- Unsweetened:Contains 60-70% fat with no added sucrose, enabling precise sweetness control in industrial formulations. Beverage manufacturers in Germany and the Netherlands favor this grade for plant-based coffee creamer applications where clean-label positioning drives procurement decisions.
- Organic:Requires three-year plantation conversion periods and mass-balance documentation under EU deforestation regulation. European dairy alternative startups source directly from verified cooperative networks in Ben Tre province, Vietnam, bypassing traditional commodity brokers.
- Sweetened:Pre-blended with maltodextrin or sucrose for instant beverage applications. Southeast Asian hospitality channels favor this grade for simplified kitchen operations.
- Conventional:Plantation-standard grades without certification premiums. Bulk exporters to food manufacturers in India and China procure this tier for cost-sensitive bakery and sauce applications.
Leading the category by volume: Unsweetened. Growing fastest: Organic.
Application:
End-use concentration determines fat stability requirements, with beverage applications demanding superior lipid retention through spray-drying optimization.
- Beverages:Coffee chains and ready-to-drink manufacturers specify high-fat powders with modified starch encapsulation for single-serve stick packs. North American direct-to-factory dosing systems are compressing traditional bulk-drum supply chains.
- Bakery:Traditional volume leader now ceding share to beverage applications. Industrial bakeries in Indonesia and the Philippines use conventional grades for laminated dough and filling applications where fat functionality matters more than traceability.
- Confectionery:Chocolate and compound coating manufacturers trial coconut cream powder as palm oil displacement accelerates. REACH compliance upgrades for lipid-based ingredients are qualifying coconut-derived fat sources ahead of tightened contaminant thresholds.
- Sauces:Coconut milk reconstitution for curry and soup bases in food service. Hospitality procurement in Thailand and Malaysia favors pouch formats for portion control.
Volume concentrates in: Beverages. Steepest expansion trajectory: Confectionery fat substitution.
End User:
Procurement scale and specification rigor separate industrial accounts from fragmented hospitality and retail channels.
- Food Industry:Multinational formulators demand EUDR-compliant documentation, satellite-linked plantation mapping, and fixed-contract pricing. Nestle anchors global distribution through existing plant-based beverage portfolios.
- Exporters:Regional trading houses face margin compression as direct contracting between plantation groups and end-use formulators displaces traditional broker channels. Axelum Resources Corp. leverages integrated Philippine supply chains to control quality from plantation to powder.
- Hospitality:Restaurants and hotels prioritize portion-control packaging and reconstitution convenience over certification premiums. Pouch formats are displacing tins in this channel.
- Retail:Supermarkets and specialty grocers stock smaller formats with prominent organic and clean-label positioning. S&P Industries Sdn Bhd competes on functional performance through specialized spray-drying technology.
Dominant procurement scale: Food Industry. Fastest channel shift: Exporters adopting traceability infrastructure.
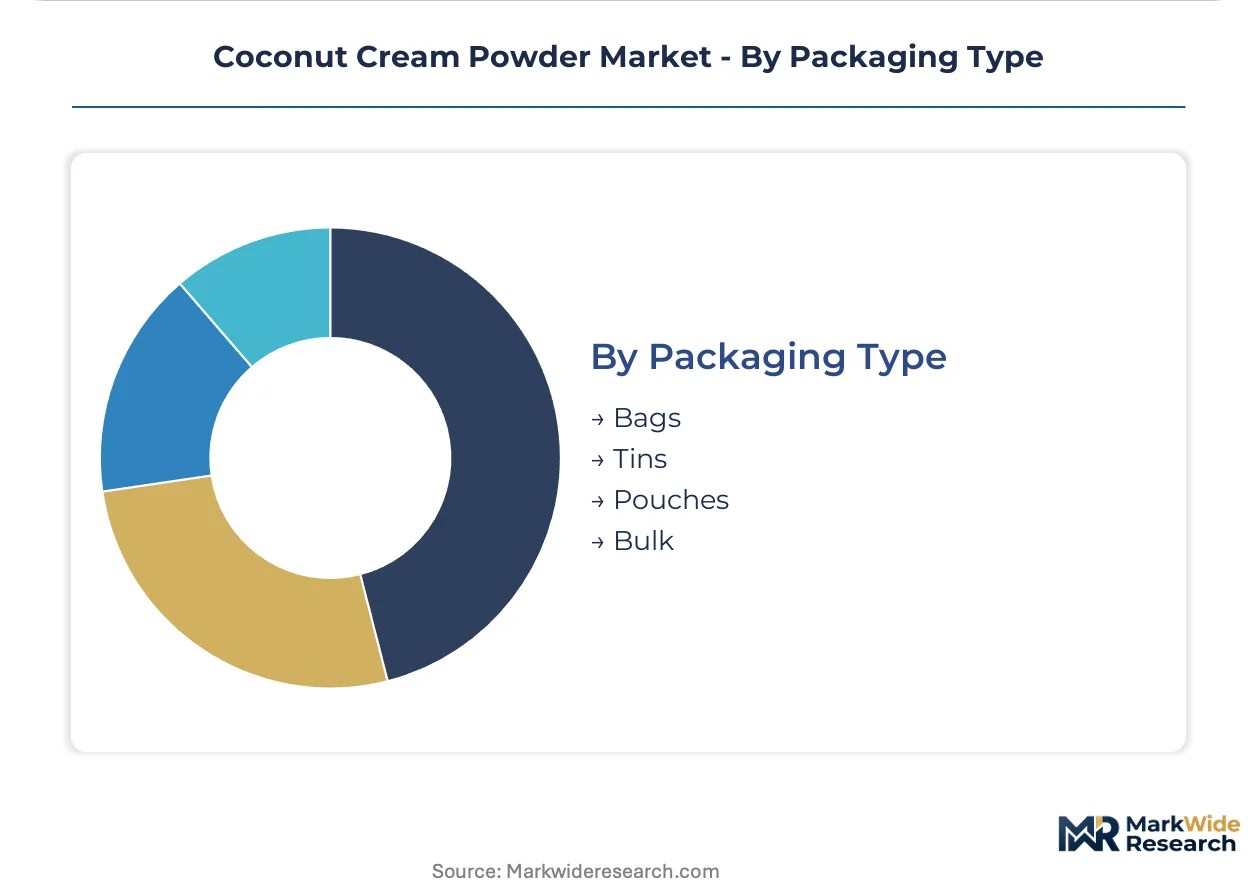
Packaging Type:
Format selection tracks customer scale and supply chain compression, with bulk dominating exporter transactions and pouches capturing retail growth.
- Bulk:Drum and tote formats for food manufacturer direct delivery. Natural gas-fired atomization cost structures disadvantage processors without subsidized fuel access.
- Pouches:Flexible packaging gaining share in retail and hospitality channels. Lower material cost and improved shelf-life performance through barrier films.
- Bags:Intermediate formats for regional distributors and mid-scale food service. Common in Indian and Vietnamese domestic markets.
- Tins:Legacy format retaining presence in gift and premium export segments. Higher material cost limits growth in price-sensitive channels.
Highest volume format: Bulk. Fastest packaging shift: Pouches displacing tins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Ben Tre and Tra Vinh provinces concentrate Vietnamese spray-drying capacity. Philippine plantation corridors face EUDR compliance pressure. Indonesian kernel supply clusters attract integrated processor investment.
Indonesia
Sulawesi and North Sumatra plantation clusters provide year-round kernel supply with lower moisture variance than competing origins. The country's national food safety regulator enforces halal certification mandates that shape export-grade processing protocols. Integrated processors in North Sumatra are deploying satellite-linked plantation mapping to satisfy EU deforestation regulation traceability requirements.
Philippines
Typhoon corridor exposure across Eastern Visayas and Mindanao creates single-origin vulnerability for buyers without multi-source hedging. The Philippine Coconut Authority coordinates industry standards compliance for export-oriented processors. Davao del Sur and Quezon province processing hubs are consolidating smallholder supply chains under cooperative structures to meet mass-balance documentation demands.
Vietnam
Ben Tre and Tra Vinh provinces offer lower-cost organic certification pathways than established Philippine facilities. The Ministry of Agriculture and Rural Development administers plantation conversion timelines that compress supply during certified ingredient demand surges. Mekong Delta spray-drying clusters are capturing contract manufacturing volume from European dairy alternative startups seeking EUDR-compliant sourcing.
Germany
Specialty coffee roasters and plant-based dairy startups in Hamburg and Berlin are sourcing through verified cooperative networks, bypassing regional trading houses. ECHA administers REACH compliance upgrades that are qualifying coconut-derived fat sources ahead of tightened contaminant thresholds. Cologne and Munich formulation labs are trialing coconut cream powder for palm oil displacement in chocolate and compound coatings.
United States
Coffee chains and ready-to-drink manufacturers specify high-fat powders with modified starch encapsulation for single-serve stick packs. FDA GRAS status governs market access for imported coconut-derived ingredients. California and Pacific Northwest beverage formulators are compressing traditional bulk-drum supply chains into direct-to-factory powder dosing systems.
Coconut Cream Powder Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with plantation-backed operators commanding premium positioning while toll processors compete on unit economics. Three archetypes dominate: integrated plantation-to-powder operators controlling traceability documentation, technology-focused spray-drying specialists competing on lipid retention performance, and commodity exporters serving price-sensitive industrial accounts in India and China. Capacity expansion and EUDR compliance infrastructure investment represent the dominant competitive moves, with early traceability system deployment creating supplier lock-in with European dairy alternatives manufacturers.
Among plantation-integrated operators, Axelum Resources Corp. exemplifies the vertically controlled supply chain archetype, while Nestle occupies a position leveraging global distribution reach through existing plant-based beverage portfolios. S&P Industries Sdn Bhd represents the technology-specialist tier, competing on functional performance through proprietary spray-drying expertise rather than commodity pricing.
| Leading Market Players |
|---|
| Axelum Resources Corp. |
| Renuka Foods |
| Nestle |
| Earth Circle Organics |
| Cocomi Bio Organic |
| The Coconut Company |
| S&P Industries Sdn Bhd |
| Asia Saigon Food Ingredients AFI |
| Kara |
| Others |
Value Network & Pricing Analysis
Family-owned plantation operators in the Philippines and Indonesia anchor supply discipline through generational land tenure, translating into pricing power that resists spot-market volatility while compressing margins for non-integrated toll processors dependent on brokered kernel supply.
Pricing Analysis
Short lead-time premiums command substantial markups from beverage manufacturers facing reformulation deadlines, while spot inventory discounts clear seasonal overhang from processors lacking fixed-contract coverage. Three-tier pricing structure across premium organic, standard certified, and economy conventional grades separates plantation-backed EUDR-compliant supply from commodity exporters. Pricing pressure stems from natural gas-fired spray-drying cost inflation, with margins tightening most acutely for Philippine processors lacking renewable energy access. Industrial bakery accounts in India and China exhibit highest price sensitivity, while European dairy alternative startups absorb premium tiers for traceability assurance.
Supply Chain Analysis
Single-source vulnerability sits with Philippine kernel supply exposed to typhoon corridor disruption across Eastern Visayas and Mindanao, forcing multi-source hedging strategies among qualified buyers. Geographic concentration centers on Indonesia, the Philippines, and Vietnam for raw material extraction, with Ben Tre and Tra Vinh provinces capturing processing expansion. Raw material dependencies draw from fresh coconut kernel, natural gas for atomization energy, and modified starch carriers for encapsulation grades. Tariff exposure looms for US-bound shipments lacking FDA GRAS documentation. Distribution runs through direct plantation-to-formulator contracting that displaces traditional regional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU deforestation regulation traceability infrastructure creates a barrier-to-entry moat favoring early-investing plantation-backed operators over smallholder-dependent aggregators.
For Market Incumbents: Deploy satellite-linked plantation mapping to lock in European dairy alternative manufacturer contracts ahead of due diligence deadlines. Axelum Resources Corp.'s integrated Philippine supply chain exemplifies the defensive posture that captures premium positioning through mass-balance documentation. Capacity addition in Vietnamese organic-certified zones counters Philippine typhoon exposure. Certification investment in spray-drying lipid retention technology defends against S&P Industries Sdn Bhd's functional performance competition.
For New Entrants and Emerging Players: Capture confectionery fat substitution trials in German and Dutch chocolate formulation labs where palm oil displacement accelerates clean-label tropical fat sourcing. The most penetrable white-space sits with mid-scale Vietnamese processors offering lower-cost organic certification pathways than established Philippine facilities. Direct contracting with specialty coffee roasters bypasses exporter margin compression. A go-to-market angle anchored in EUDR-compliant documentation for European plant-based beverage startups secures supplier lock-in before incumbent compliance completion.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Vietnamese spray-drying specialists in Ben Tre and Tra Vinh provinces facing working capital pressure from organic conversion timeline compression. Long-term viability across the five-to-ten-year window rests on backward integration into plantation supply rather than toll-processing dependence. Acquisition targets should demonstrate captive kernel supply or secured cooperative networks with satellite traceability deployment. The signal to watch is EUDR enforcement intensity against non-compliant Philippine smallholder aggregators as a demand-shock catalyst for verified supply.
| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Traceability Infrastructure Deployment | Satellite-linked plantation mapping secures European market access for compliant operators. |
| Backward Integration into Kernel Supply | Captive plantation control eliminates broker margin layers and price volatility exposure. |
| Spray-Drying Capacity Expansion | New Ben Tre and Tra Vinh facilities capture organic certification demand from European startups. |
| Encapsulation Technology Investment | Modified starch carrier systems enable single-serve stick pack penetration in North American beverage channels. |
| Direct-to-Formulator Distribution | Bypassing regional trading houses captures price discovery margin and quality arbitrage value. |
Research Methodology
Document review covered EU deforestation regulation implementation guidance, Bursa Malaysia Derivatives coconut oil futures data, and Philippine Coconut Authority industry standards, complemented by interviews with spray-drying plant managers, procurement leads at European dairy alternative manufacturers, distribution channel partners in Southeast Asian export corridors, and technical R&D directors specializing in lipid retention optimization. Secondary validation drew from FDA GRAS filings, REACH compliance documentation, FSSAI labeling mandates, and customs trade records. Bottom-up volume modeling and top-down value triangulation anchored forecast construction.
Segment-level projections across the modeling period integrated unsweetened, organic, sweetened, and conventional product grades; beverage, bakery, confectionery, and sauce applications; food industry, exporter, hospitality, and retail end users; and bulk, pouch, bag, and tin packaging formats. CAGRs were derived from elasticity-adjusted demand curves and input cost trajectory assumptions. Industry-specific forecast inputs included copra price volatility transmission coefficients and EUDR compliance cost absorption rates by processor scale tier.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU deforestation regulation enforcement intensity, typhoon frequency in Philippine plantation corridors, and natural gas price trajectories affecting spray-drying economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Broccoli Powder Market
Ingredients
Meat Starter Culture Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
Vegetable Fats Market
Ingredients
South America Fats and Oil Market
Ingredients
Fish Feed Ingredients Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Textured Milk Protein Market
Ingredients
Apple Extract Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Organic Starch Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Spain Sodium Reduction Ingredient Market