
 Broccoli Powder Market | 2026-2036
Broccoli Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Broccoli Powder Market Outlook
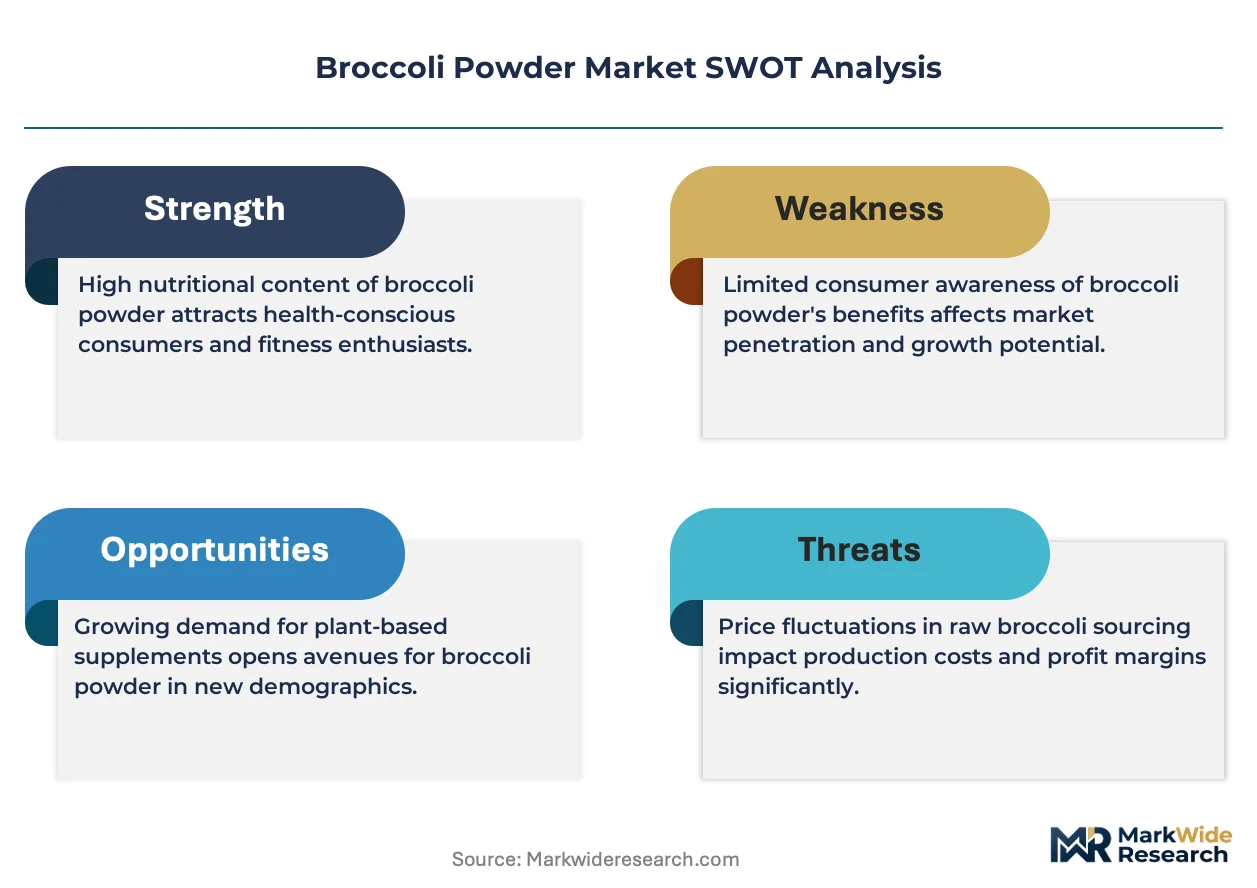
Subscription-based replenishment programs for functional ingredients is recalibrating how broccoli powder reaches end-formulators. NutraDry leverages its spray-drying infrastructure to sustain consistent supply for North American nutraceutical clients. Xi'an Lifewe Biological Technology Co., Ltd. anchors its position through backward integration into raw broccoli cultivation in Shaanxi province. VDF FutureCeuticals, Inc. differentiates via specialized extraction protocols that preserve sulforaphane activity.
Broccoli powder consists of dehydrated and milled Brassica oleracea var. italica, typically standardized for glucosinolate or sulforaphane content and processed through freeze-drying or spray-drying to below 5% moisture for stability in downstream applications. The powder functions primarily as a functional food additive, nutritional supplement base, and natural colorant in formulations requiring vegetable-derived bioactive compounds. Organic powder occupies the premium tier where certification requirements limit supplier pools and sustain higher margin structures. Spray-dried forms dominate volume throughput due to lower unit production costs, while freeze-dried variants capture concentrated demand from pharmaceutical-grade applications where thermal degradation sensitivity matters.
The FDA maintains GRAS oversight for broccoli powder used in food and beverage applications, while the USDA National Organic Program governs certification requirements for organic-labeled products in the United States. EFSA evaluates health claim substantiation for sulforaphane-related marketing in European markets, creating divergence in permissible label language across jurisdictions. Stakeholders must monitor evolving Novel Food catalog updates and adapt formulation dossiers to preempt regulatory friction in priority export corridors.
Market Dynamics
Clean-label certification requirements are compressing supplier pools while concentrating procurement power among vertically integrated cultivators who control both raw broccoli sourcing and downstream powder processing.
Growth Catalysts
- EU Novel Food Regulation:Standardized approval pathways accelerate market entry for new broccoli powder entrants, reducing regulatory uncertainty for sulforaphane-standardized products.
- Dietary supplements sector:Capsule and tablet manufacturers expand broccoli powder incorporation as bioactive compound demand intensifies across preventive nutrition categories.
- Germany retail placement:Clean-label nutrition products command premium shelf space, driving formulation-grade powder consumption through pharmacy and specialty channels.
Market Restraints
- Input cost volatility:Raw broccoli prices fluctuate with seasonal yield variations and climate-driven crop losses, compressing margins for non-integrated processors.
- Supply concentration risk:Shaanxi province cultivation dominance creates geographic single-point vulnerability for Chinese-origin organic powder supply.
- Thermal degradation limitation:Spray-drying processes reduce sulforaphane bioavailability compared to freeze-dried alternatives, limiting pharmaceutical-grade application expansion.
Strategic Opportunities
- Underpenetrated US organic channel:USDA National Organic Program certification gaps among mid-tier suppliers create white space for compliant entrants targeting natural products retail.
- Subscription replenishment models:Direct-to-formulator delivery programs reduce working capital burdens for small-batch nutraceutical manufacturers.
- Dual carbon convergence:Renewable energy-powered drying infrastructure paired with regenerative agriculture sourcing addresses Scope 3 emissions reporting requirements under EU CSRD.
Industry Challenges
- Glucosinolate assay standardization:Inconsistent laboratory methodologies across jurisdictions create certification timeline delays and batch rejection risks.
- Spray-drying capex intensity:Industrial-scale dehydration equipment requires substantial capital deployment, favoring incumbent processors with depreciated infrastructure.
- Legacy ERP integration:Traceability systems for organic chain-of-custody documentation clash with established inventory management platforms at mid-sized formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broccoli Powder Market |
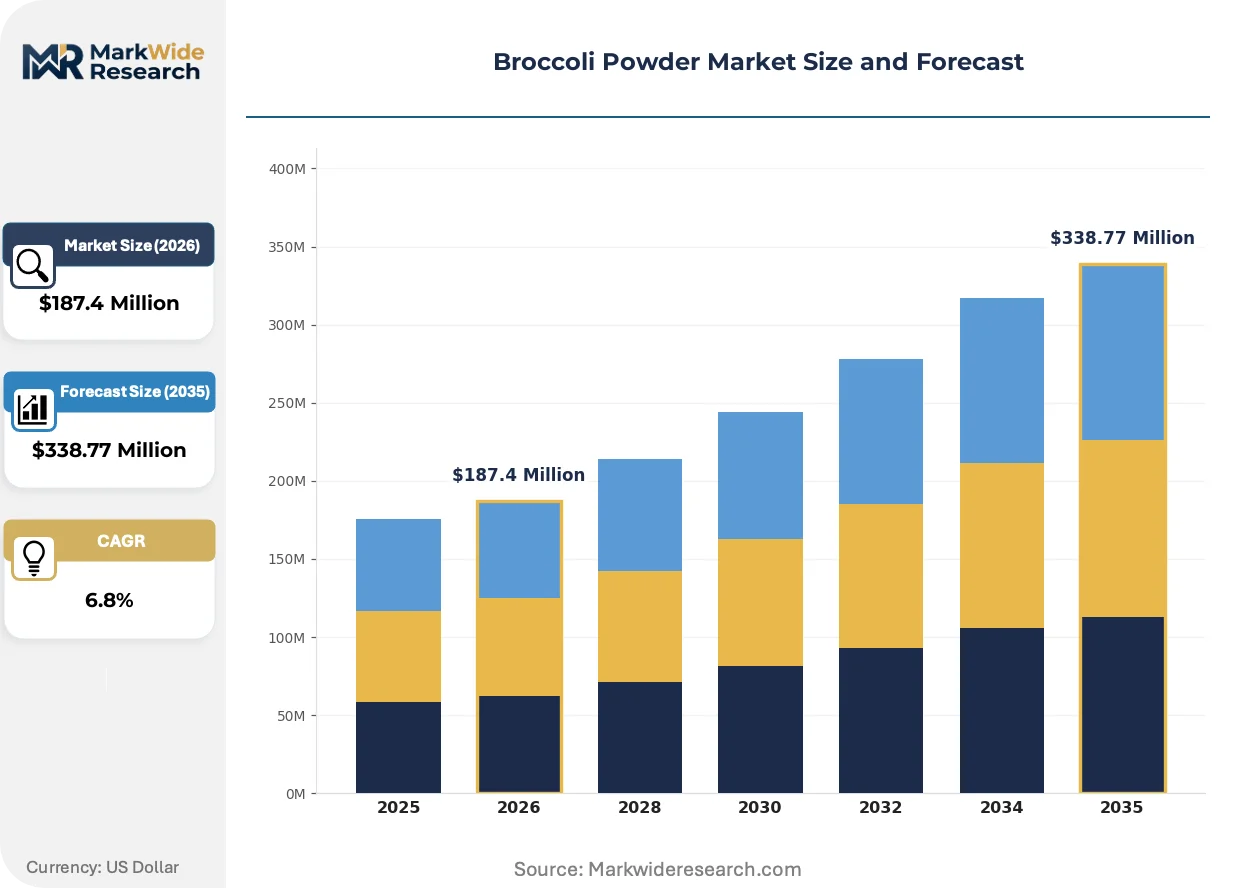
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Powder, Conventional Powder, Instant Powder, Nutraceutical Powder End User: Food & Beverage, Dietary Supplements, Pharmaceuticals, Cosmetic Industry Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Form: Freeze-Dried, Spray-Dried, Granulated, Extract |
| Companies Covered | Saipro Biotech Private Limited, NutraDry, Xi’an Lifewe Biological Technology Co., Ltd., Pioneer Herb Industrial Co., Ltd., American International Foods, Inc., Nutraonly (Xi’an) Nutritions Inc., VDF FutureCeuticals, Inc., Vinayak Corporation, VehGro B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broccoli Powder Market Strategic Shifts
Processing technology convergence with sustainability mandates is reconfiguring competitive advantage around energy efficiency and bioactive preservation rather than scale alone.
Low-temperature vacuum belt drying is integrating into premium powder production lines to reduce thermal exposure while maintaining throughput economics. Pharmaceutical-grade formulators in Switzerland and Germany adopt this equipment fastest, compressing the performance gap between freeze-dried and spray-dried outputs. The technology is integrating quality-tier boundaries that previously separated commodity and specialty supply streams.
EFSA health claim substantiation requirements for sulforaphane-related marketing are tightening evidentiary standards across European markets. This regulatory pressure forces reformulation dossier investments and truncates permissible label language for non-compliant suppliers. Dietary supplement segments in France and Germany face the steepest compliance costs, driving consolidation toward established dossier holders.
Direct procurement from cultivator-processors is displacing traditional ingredient distributor relationships among mid-scale nutraceutical manufacturers. North American contract manufacturers now source spray-dried powder through vertically integrated channels rather than multi-ingredient wholesalers, compressing margin capture at intermediary levels. This pattern is most visible in California and Texas formulation clusters where supply chain transparency requirements intensify.
Broccoli Powder Market Segmentation
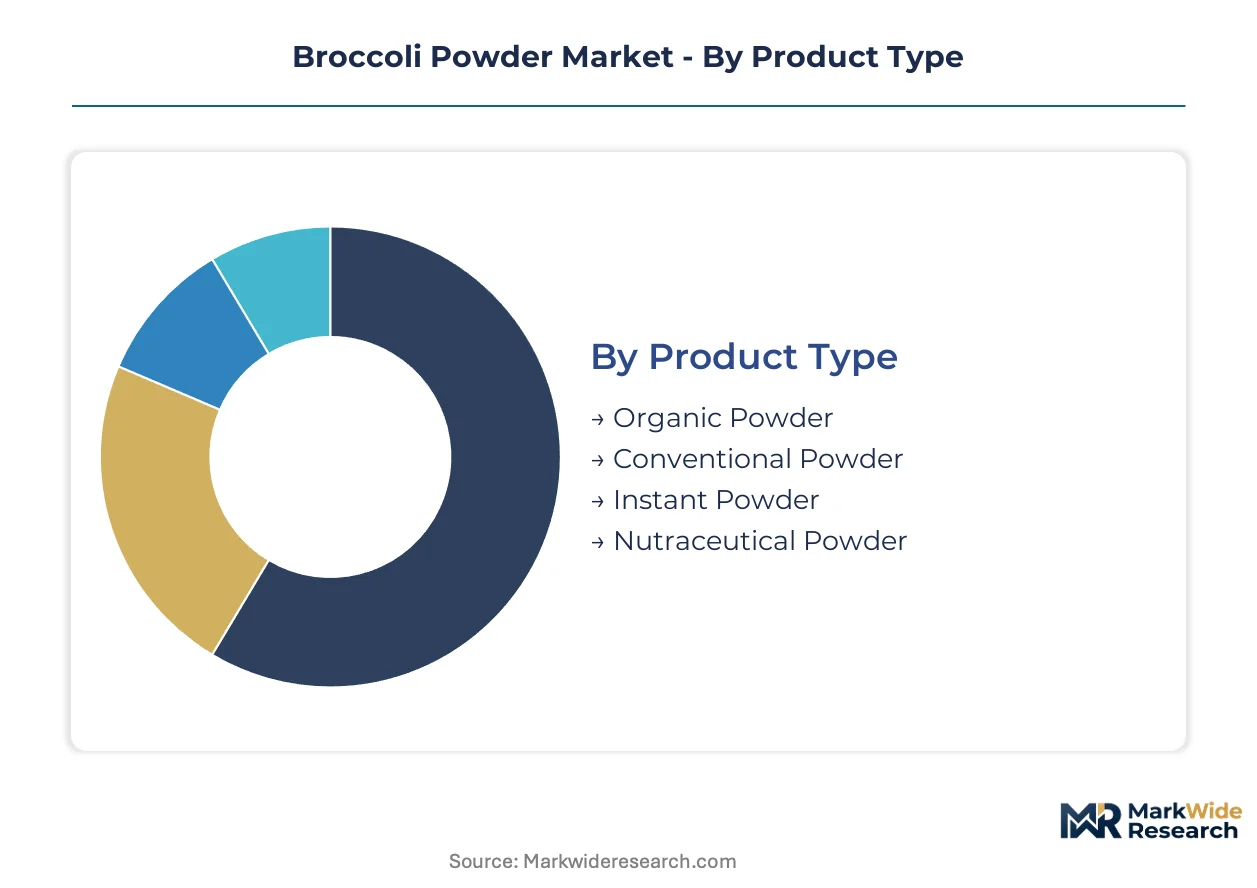
Broccoli powder segmentation reveals divergent value capture between standalone nutraceutical applications and embedded food systems. Each dimension carries distinct margin profiles, regulatory burdens, and supply chain configurations that shape procurement strategy.
Product Type:
Integration depth separates powder grades optimized for direct consumption from those engineered for formulation embedding.
- Organic Powder:USDA National Organic Program or EU organic certification restricts supplier pools through chain-of-custody requirements. German pharmacy channels and California natural products retailers drive premium placement where certification documentation commands shelf access.
- Conventional Powder:Standard agricultural sourcing without certification overhead serves cost-sensitive food manufacturing. Mass-market soup and sauce formulators in US Midwest production clusters absorb volume throughput.
- Instant Powder:Pre-solubilized particle engineering targets beverage applications requiring rapid dispersion. Functional drink manufacturers in Texas and Florida formulation hubs specify this grade for ready-to-mix portfolios.
- Nutraceutical Powder:Standardized glucosinolate or sulforaphane content meets dietary supplement capsule and tablet specifications. cGMP-compliant processors in Utah and North Carolina dietary supplement corridors concentrate demand.
Conventional powder leads volumes today; organic powder is gaining share fastest.
End User:
Application maturity determines whether broccoli powder functions as a primary bioactive or a supporting ingredient matrix.
- Food & Beverage:Clean-label vegetable fortification in soups, sauces, and baked goods embeds powder as a secondary colorant and nutrient carrier. Major CPG manufacturers in Illinois and New Jersey maintain qualified supplier lists for this tier.
- Dietary Supplements:Capsule, tablet, and powder-in-capsule formats position sulforaphane standardization as the primary purchase driver. Preventive nutrition brands in Colorado and Oregon direct-to-consumer channels expand formulation portfolios.
- Pharmaceuticals:Investigational drug applications and medical food categories require freeze-dried, high-potency grades with full analytical documentation. Swiss and German pharmaceutical-grade processors enforce the steepest specification thresholds.
- Cosmetic Industry:Topical antioxidant claims in skincare formulations utilize broccoli powder as a botanical marketing ingredient. Korean and French cosmetic manufacturers integrate trace amounts for green-positioned product lines.
Dietary supplements anchor revenue concentration; pharmaceutical applications show steepest specification escalation.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements rather than simple price sensitivity.
- Online Retail:Direct-to-consumer and small-batch formulator procurement bypasses traditional distributor markups. Amazon and specialized ingredient marketplaces capture growing share from startup nutraceutical brands.
- Supermarkets:Mass-market retail placement serves consumer-packaged finished goods, not bulk powder itself. This channel represents downstream endpoint, not input sourcing pathway.
- Specialty Stores:Natural products retailers and pharmacy chains in Germany and Austria stock finished supplements containing specified powder grades. Shelf placement depends on organic certification and EFSA-aligned label claims.
- Direct Sales:Vertically integrated cultivator-processors supply contract manufacturers through long-term supply agreements. California and Texas formulation clusters increasingly bypass multi-ingredient distributors.
Direct sales dominate volume procurement; online retail is expanding most quickly among emerging formulators.
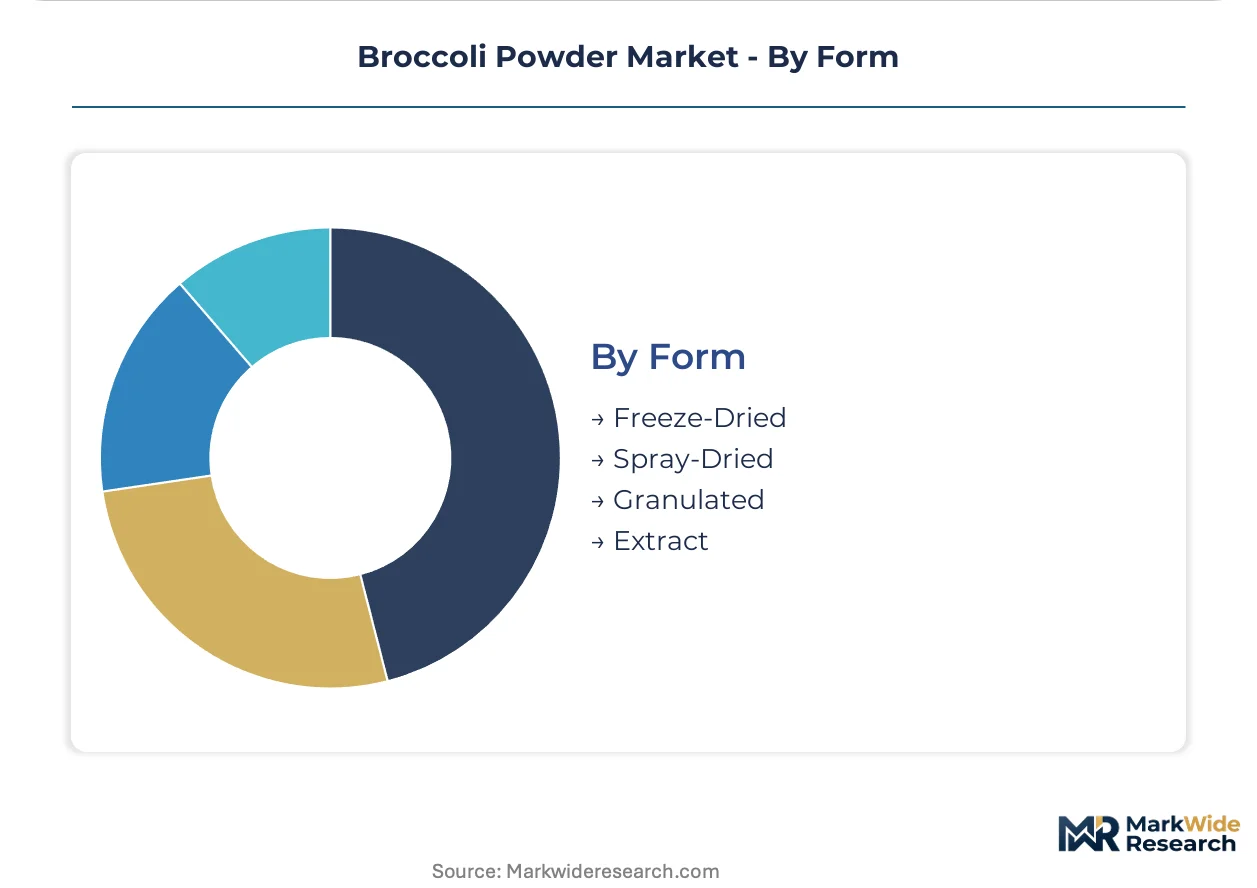
Form:
Processing technology creates irreversible quality tiering that segments end-use applicability.
- Freeze-Dried:Sublimation dehydration preserves sulforaphane bioavailability and volatile compound integrity. Pharmaceutical and premium nutraceutical applications in Switzerland and Germany specify this grade exclusively.
- Spray-Dried:Atomization and hot-air dehydration delivers cost-efficient volume for food-grade applications. NutraDry and comparable processors in North American corridors sustain supply for mainstream formulators.
- Granulated:Agglomerated particle engineering improves flowability for high-speed capsule filling operations. Dietary supplement contract manufacturers in Utah and Florida specify this grade for production efficiency.
- Extract:Solvent or supercritical CO2 concentration of bioactive fractions yields standardized sulforaphane or glucoraphanin content. Specialized extraction houses in China and India serve pharmaceutical and research chemical demand.
Spray-dried forms command volume leadership; freeze-dried grades capture margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting broccoli powder production toward jurisdictions with streamlined novel-food approval pathways and lower certification overhead. Manufacturers migrate capacity to exploit compliance-cost differentials between stringent European frameworks and more permissive Asian regulatory environments.
United States
Capsule and tablet manufacturers in Utah and North Carolina drive nutraceutical-grade demand. FDA GRAS oversight governs food and beverage applications while USDA National Organic Program certification gates premium retail placement. California formulation clusters increasingly source through vertically integrated cultivator-processors rather than traditional distributors.
Germany
Pharmacy and specialty retail channels command premium shelf space for clean-label nutrition products. EFSA health claim substantiation requirements tighten evidentiary standards for sulforaphane-related marketing. Bavarian and Baden-Württemberg processing hubs enforce the steepest specification thresholds for pharmaceutical-grade applications.
China
Shaanxi province cultivation dominance creates geographic concentration for organic powder supply. SAMR food safety standards and GB quality specifications govern domestic market entry. Xi'an-based processors anchor backward integration into raw broccoli cultivation to control input costs and traceability documentation.
Switzerland
Pharmaceutical-grade formulators specify freeze-dried grades with full analytical documentation for investigational drug applications. Swissmedic medical food regulations exceed standard food-grade requirements. Basel and Zurich corridors adopt low-temperature vacuum belt drying technology fastest to preserve bioactive compound integrity.
India
FSSAI food safety compliance and Ayush ministry guidelines shape ingredient approval for functional food applications. Gujarat and Maharashtra extraction houses serve pharmaceutical and research chemical demand for standardized sulforaphane fractions. Domestic nutraceutical manufacturers expand capsule formulation capacity for preventive nutrition export markets.
Broccoli Powder Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with spray-drying infrastructure owners capturing volume leadership while extraction protocol innovators defend margin concentration. The vendor base organizes around three strategic archetypes: vertically integrated cultivator-processors controlling raw material sourcing, specialized dehydration equipment operators serving commodity throughput, and bioactive-standardization laboratories targeting pharmaceutical-grade specifications. Dominant competitive moves include geographic expansion toward regulatory-favorable jurisdictions and technology licensing agreements that transfer low-temperature drying expertise.
Among North American dehydration specialists, NutraDry exemplifies scale-driven infrastructure deployment, while VDF FutureCeuticals, Inc. occupies a position within the bioactive-preservation tier. Xi'an Lifewe Biological Technology Co., Ltd. anchors the Chinese-origin integrated supply segment. These three represent distinct competitive vectors: throughput efficiency, extraction protocol differentiation, and backward integration into captive cultivation.
| Leading Market Players |
|---|
| Saipro Biotech Private Limited |
| NutraDry |
| Xi'an Lifewe Biological Technology Co., Ltd. |
| Pioneer Herb Industrial Co., Ltd. |
| American International Foods, Inc. |
| Nutraonly (Xi'an) Nutritions Inc. |
| VDF FutureCeuticals, Inc. |
| Vinayak Corporation |
| VehGro B.V. |
| Others |
Value Chain & Pricing Dynamics
Organic versus conventional certification divergence creates a two-ladder pricing architecture where USDA National Organic Program compliance gates premium placement in California natural products retail while Shaanxi-origin conventional powder feeds cost-sensitive Midwest food manufacturing through depreciated spray-drying infrastructure. This bifurcation concentrates margin capture among backward-integrated cultivator-processors who control both input costs and chain-of-custody documentation.
Pricing Analysis
Distributor markups compress as direct-to-formulator channels displace multi-ingredient wholesalers in California and Texas formulation clusters. Three-tier pricing structure across organic-certified, conventional food-grade, and pharmaceutical-grade freeze-dried tiers reflects certification overhead and thermal processing intensity. Cost compression in conventional spray-dried segments intensifies because Shaanxi cultivation dominance exposes non-integrated processors to raw broccoli price volatility. Dietary supplement contract manufacturers in Utah and North Carolina corridors exhibit highest price sensitivity; Swiss pharmaceutical-grade formulators demonstrate lowest sensitivity due to bioactive standardization requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from North American nutraceutical contract manufacturers while specialty distributors serve small-batch formulators through online marketplaces. Raw broccoli cultivation concentrates in China's Shaanxi province, with secondary sourcing from Gujarat and Maharashtra extraction houses in India and Utah processing corridors in the United States. Input dependencies rest on seasonal broccoli yields, glucosinolate assay reagents, and spray-drying energy inputs. Single-source vulnerability from Shaanxi geographic concentration threatens supply continuity for organic-certified powder. Distribution runs through vertically integrated cultivator-processor relationships that bypass traditional ingredient wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Novel Food Regulation compliance costs in Germany and France exceed SAMR pathway expenses in China, incentivizing capacity migration toward lower-certification-overhead jurisdictions.
For Market Incumbents: Cement supply security through captive cultivation expansion in Shaanxi or Gujarat to offset climate-driven yield volatility threatening raw input costs. Lock in cGMP-compliant processing capacity in Utah and North Carolina dietary supplement corridors before specification escalation tightens qualification timelines. Freeze-drying infrastructure investments in Swiss and German pharmaceutical-grade hubs defend margin position against low-temperature vacuum belt drying technology diffusion. For New Entrants and Emerging Players: EU Novel Food Regulation in Germany opens a window for sulforaphane-standardized powder entrants who pre-invest in EFSA-aligned dossier documentation before health claim substantiation requirements tighten. Target underpenetrated USDA National Organic Program-certified supply to California natural products retailers where certification gaps among mid-tier Chinese suppliers create shelf-access white space. Deploy subscription replenishment models for small-batch nutraceutical manufacturers in Texas and Florida to bypass distributor markups and establish direct procurement relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where spray-drying capex intensity and glucosinolate assay standardization complexity strand sub-scale processors without depreciated infrastructure or dossier holdings. Long-term viability favors vertically integrated cultivator-processors with backward control over Shaanxi organic cultivation and downstream cGMP processing capability. Acquisition target archetype: mid-tier Chinese processors with SAMR compliance seeking North American USDA certification to unlock California retail channels. Signal to watch: EFSA health claim catalog updates that invalidate existing label language and force dossier reinvestment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive Shaanxi organic broccoli supply secures input cost control and traceability documentation for EU export. |
| Low-Temperature Vacuum Belt Drying Adoption | Swiss and German pharmaceutical-grade processors preserve sulforaphane bioavailability while maintaining throughput economics. |
| EFSA Dossier Pre-Investment | German and French supplement manufacturers preempt health claim substantiation tightening that truncates permissible label language. |
| Direct-to-Formulator Subscription Launch | North American nutraceutical contract manufacturers in California and Texas reduce working capital burdens through replenishment programs. |
| USDA Organic Certification Expansion | Chinese-origin processors unlock California natural products retail placement previously gated by certification gaps. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with spray-drying equipment operators, dietary supplement formulation executives, organic certification auditors, and procurement leads at North American contract manufacturers triangulate against trade data from USDA National Organic Program filings, SAMR food safety registrations, EFSA novel food applications, and customs records tracking broccoli powder import volumes. Bottom-up demand modeling from end-use segments cross-references top-down supply-side capacity assessments.
Granularity-level modeling operates at product type, end user, distribution channel, and form dimensions across the analysis window. Segmentation by organic versus conventional certification, dietary supplement versus food and beverage application, direct sales versus online retail channel, and freeze-dried versus spray-dried processing technology enables discrete CAGR derivation from input cost trajectories and specification escalation patterns. Sulforaphane bioavailability preservation rates and glucosinolate standardization assay adoption curves inform pharmaceutical-grade demand projections.
Revisions become necessary when EFSA health claim catalog updates, SAMR food safety standard revisions, or climate-driven Shaanxi yield disruptions materialize beyond modeled scenarios. Forecasts reflect assumptions regarding certification timeline stability and energy input cost trajectories for thermal processing infrastructure. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Aroma Ingredients Market
Ingredients
Truffle Oil Market
Ingredients
Calcium Caseinate Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Licorice Root Market
Ingredients
Peanut Flour Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
United States Corn Glucose Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Sodium Caseinate Market
Ingredients
Fresh Yeast Market
Ingredients
Omega 6 Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Fucoidan Extract Market