
 South America Fats and Oil Market | 2026-2036
South America Fats and Oil Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fats and Oil Market Analytics
ANP biofuel mandates is hardening the cost-of-entry calculus for new refiners seeking to serve both food and fuel buyers. Bunge Limited leverages its crushing footprint across Brazil and Argentina to sustain dual-stream supply flexibility. Cargill Inc. anchors its position through integrated origination and port terminal control along the Paraná-Paraguay waterway. Louis Dreyfus Company competes on South American soybean origination scale, while Wilmar International specializes in refined palm oil distribution through Colombian and Ecuadorian channels.
South America fats and oils encompass triglyceride-based lipids derived from oilseed crushing, animal rendering, and tropical palm cultivation, typically characterized by fatty acid profiles ranging from C16:0 palmitic acid in palm oil to C18:2 linoleic acid dominant in soybean oil, serving as caloric inputs, chemical precursors, and oleochemical feedstocks across industrial and consumer applications. Vegetable oil leads product type volumes given soybean crushing dominance in Argentina and Brazil, though palm oil claims faster growth as Colombian and Ecuadorian plantations mature. Food Processing dominates application demand through bakery, snack, and prepared meal manufacturing, while Biofuels captures expanding margin pools as ANP and Argentine SE biodiesel mandates tighten blending requirements.
Brazil's ANP and Argentina's Secretariat of Energy enforce diverging biodiesel blend mandates that redirect oilseed flows between edible and fuel uses, while MERCOSUR food safety protocols govern trans-fat labeling and maximum limits across member states. ANVISA in Brazil and INAL in Argentina maintain separate pharmaceutical-grade oil standards that constrain import sourcing for excipient manufacturers. Stakeholders must monitor how Brazil's RenovaBio carbon intensity scoring and Argentina's export tax volatility jointly reshape crush margins and regional trade routing decisions.
Market Dynamics
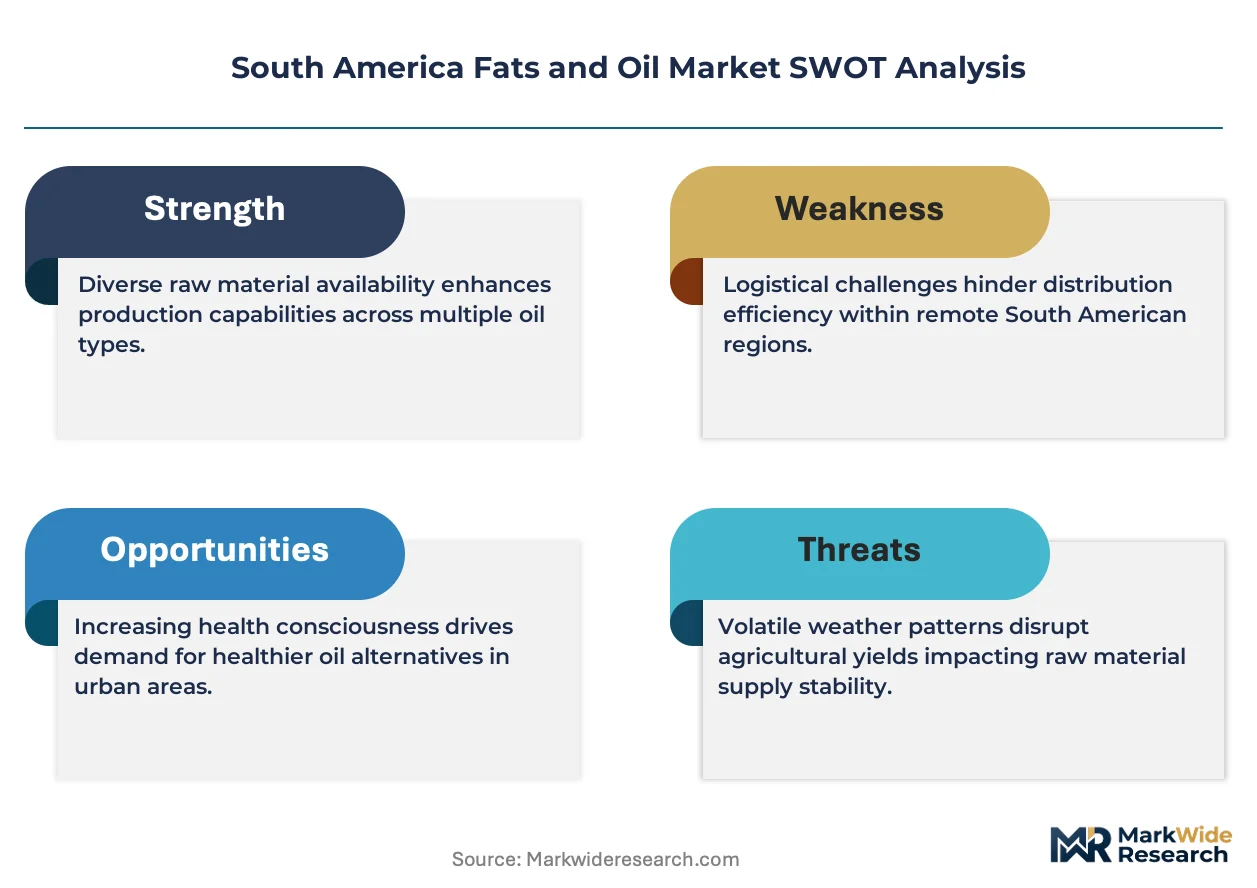
Brazil's ANP biofuel mandates are redirecting soybean oil flows from food processing toward biodiesel feedstock, tightening supply availability for packaged goods manufacturers while elevating crush margins for integrated processors with dual-stream flexibility.
Growth Catalysts
- ANP Biodiesel Blending Mandates:Brazil's escalating biodiesel blend requirements under Resolution 758 are structurally expanding offtake volumes for domestic soybean oil refiners serving fuel distributors.
- Colombian Palm Maturity:Expanding plantation acreage in the Magdalena River basin is accelerating crude palm oil output for regional oleochemical and food manufacturing buyers.
- Argentina Export Tax Architecture:Differential soybean product taxation under AFIP regulations is incentivizing domestic crushing over raw bean exports, deepening local oilseed processing capacity.
Market Restraints
- Soybean Input Volatility:Weather-driven production swings across Argentina's Pampas and Brazil's Mato Grosso generate crush margin instability for unhedged refiners.
- Port Infrastructure Concentration:Oilseed export flows depend heavily on Santos and Paranaguá terminals, creating bottleneck risk during peak harvest windows.
- Trans-Fat Labeling Compliance:MERCOSUR food safety protocols impose reformulation costs on bakery and snack manufacturers using partially hydrogenated oils.
Strategic Opportunities
- Ecuadorian Palm Expansion:Underdeveloped plantation zones in Esmeraldas province offer greenfield investment potential for integrated palm oil processors.
- RenovaBio Carbon Credits:Brazil's fuel decarbonization program generates tradable CBIO credits for biodiesel producers achieving below-baseline carbon intensity scores.
- Paraguay Crushing Gap:Limited domestic processing infrastructure relative to soybean output creates arbitrage potential for cross-border oilseed flows to Argentine and Brazilian refiners.
Industry Challenges
- Dual-Certification Burden:Refiners serving both ANVISA pharmaceutical-grade standards and ANP fuel specifications face parallel audit and quality management system investments.
- Intermodal Coordination:Synchronizing barge movements on the Paraná-Paraguay waterway with port vessel scheduling demands specialized logistics talent scarce in regional labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fats and Oil Market |
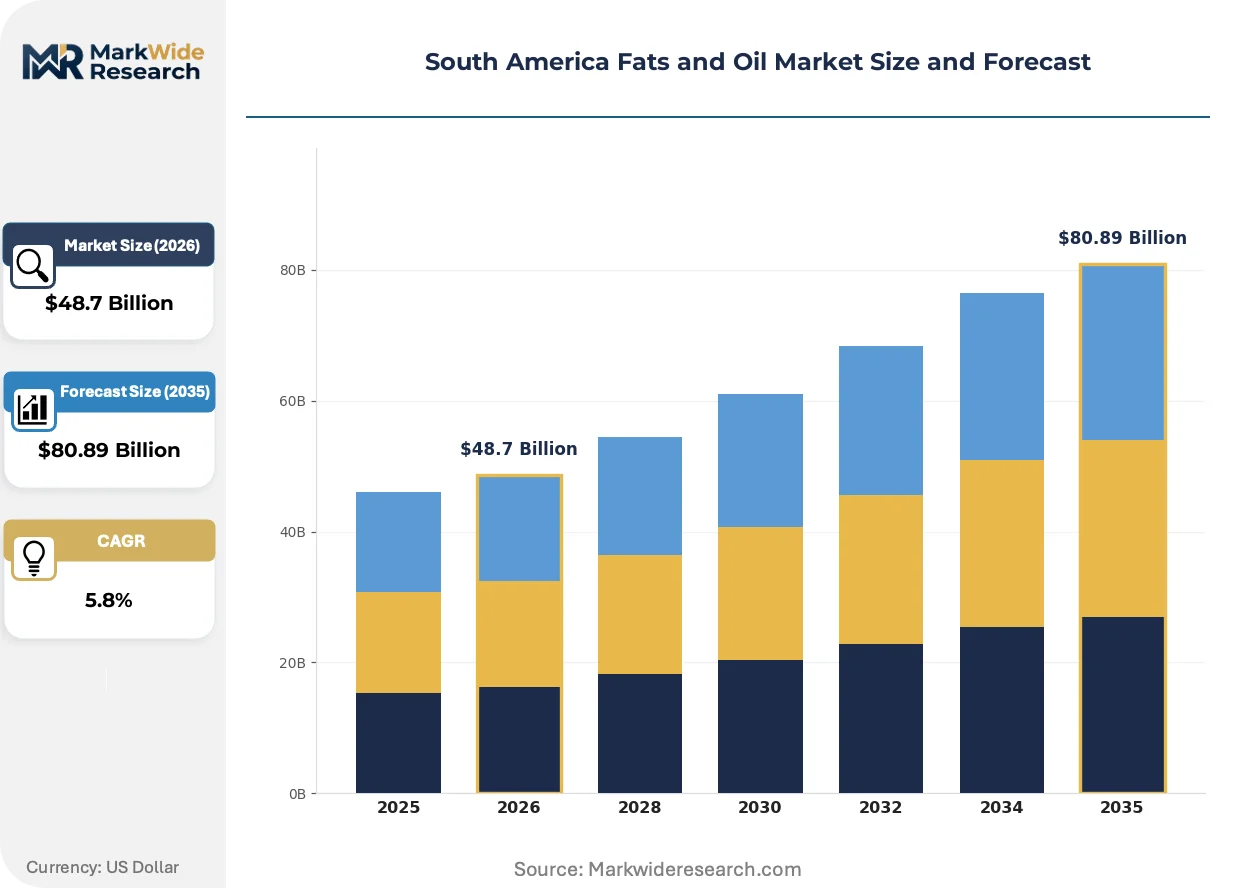
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oil, Palm Oil, Olive Oil, Animal Fat Application: Food Processing, Personal Care, Biofuels, Pharmaceuticals Form: Liquid, Solid, Semi-solid, Emulsified Distribution Channel: Online Retail, Supermarkets, Wholesalers, Food Service |
| Companies Covered | ADM, Fuji Oil Holding Inc., Cargill Inc., Wilmar International, COFCO International, Bunge Limited, Olam International Limited, Soyven, Louis Dreyfus Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fats and Oil Market Evolving Landscape
Processing technology and regulatory architecture are jointly reshaping how South American oilseed flows divide between edible and fuel applications, with implications for refinery configuration and capital deployment priorities.
Enzymatic interesterification is absorbing growing capital allocation from Brazilian and Argentine refiners seeking to produce trans-fat-free bakery shortenings without full hydrogenation. Food processing buyers in São Paulo and Buenos Aires are qualifying enzymatically modified palm-soy blends at accelerated pace. This technology is absorbing market share from traditional chemical interesterification while enabling cleaner label positioning for packaged goods exporters.
Argentina's Secretariat of Energy has tightened biodiesel blend mandates through Decree 543, compressing edible oil supply availability during peak crushing seasons. Domestic refiners are reconfiguring fractionation capacity to prioritize fuel-grade methyl ester output over food applications. The policy shift most acutely affects small and mid-scale food manufacturers in Córdoba and Rosario lacking long-term supply contracts.
Large-scale food processors are consolidating vegetable oil procurement through direct origination partnerships with crushing cooperatives, bypassing traditional trading house intermediaries. This disintermediation concentrates volume commitments among buyers with sufficient scale to justify dedicated logistics arrangements. The pattern is most pronounced in Brazil's southeastern industrial corridor, where bakery and snack conglomerates are securing captive supply streams from Mato Grosso crushers.
South America Fats and Oil Market Segmentation
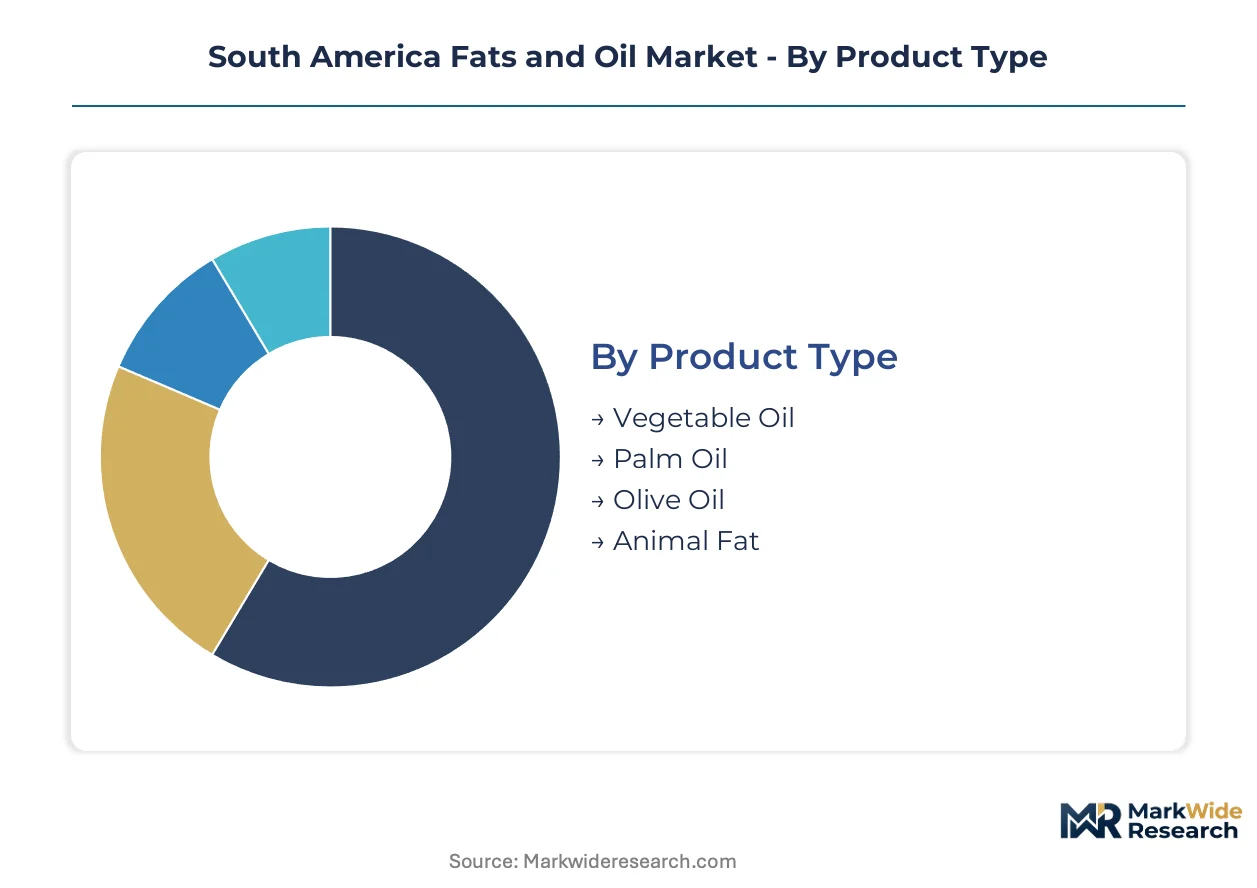
South American oilseed processors configure refinery assets around distinct product specifications and end-use certifications. Segmentation discipline separates commodity crush operations from specialty fat formulations commanding premium margins.
Product Type:
Capital intensity varies sharply across oilseed processing pathways, with palm plantation development demanding the longest payback horizons and soybean crushing offering the fastest equipment redeployment.
- Vegetable Oil:Triglyceride mixtures derived from soybean, sunflower, and canola crushing dominate regional output volumes. Brazilian food manufacturers in São Paulo and Minas Gerais absorb the largest contracted flows for packaged goods production, though ANP biodiesel mandates are redirecting increasing volumes toward fuel methyl ester production.
- Palm Oil:Semi-solid lauric fat harvested from Elaeis guineensis plantations in Colombia's Magdalena River basin and Ecuador's coastal lowlands. Oleochemical manufacturers in Barranquilla and Guayaquil are expanding fractionation capacity to serve surfactant and cosmetic ingredient demand.
- Olive Oil:Monounsaturated oil from Olea europaea cultivation concentrated in Argentina's Mendoza and San Juan provinces. Premium extra-virgin grades supply domestic gourmet retail channels with limited export penetration.
- Animal Fat:Rendered tallow and lard from cattle and swine processing operations, primarily serving Argentine soap manufacturing and Chilean pet food formulations.
Most installed capacity flows through Vegetable Oil. Expansion is steepest in Palm Oil.
Application:
Customer procurement scale determines margin capture, with multinational food conglomerates negotiating long-term crush contracts while pharmaceutical buyers pay certification premiums.
- Food Processing:Bakery shortenings, frying oils, and confectionery fats formulated for MERCOSUR trans-fat compliance standards. Brazilian snack manufacturers are accelerating enzymatic interesterification adoption to eliminate partial hydrogenation from ingredient declarations.
- Personal Care:Cosmetic-grade palm kernel oil derivatives and refined olive squalane for skincare formulations. Colombian oleochemical refiners are qualifying pharmaceutical-grade glycerin outputs for export to North American personal care multinationals.
- Biofuels:Biodiesel methyl esters produced under ANP Resolution 758 and Argentine Secretariat of Energy Decree 543 specifications. Domestic fuel distributors in Brazil's Center-West are securing crush-origin supply contracts bypassing traditional trading intermediaries.
- Pharmaceuticals:Excipient-grade oils meeting ANVISA and INAL purity standards for parenteral and oral dosage forms. Limited domestic production forces Brazilian drug manufacturers to import refined coconut and palm kernel oils through approved sourcing channels.
Food Processing commands the largest volume commitments. Biofuels is climbing the fastest as mandate compliance tightens.
Form:
Physical state specifications dictate storage infrastructure requirements, with liquid bulk terminals offering the lowest handling costs and emulsified products demanding specialized blending equipment.
- Liquid:Crude and refined oils in bulk tank storage, the default state for soybean and sunflower outputs. Argentine crushing cooperatives are consolidating riverfront liquid terminal investments to secure Paraná-Paraguay waterway access.
- Solid:Fully hydrogenated fats and stearin fractions for bakery and industrial applications. Brazilian margarine manufacturers are qualifying enzymatically solidified blends to replace chemically hydrogenated bases.
- Semi-solid:Palm olein and interesterified shortenings with tailored melting profiles. Colombian food processors are adopting semi-solid palm-soy blends for tropical climate stability.
- Emulsified:Water-in-oil dispersions for mayonnaise, dressings, and cosmetic creams. Argentine prepared sauce manufacturers represent the primary regional demand concentration.
Liquid form handles the greatest tonnage. Emulsified products are gaining share fastest in prepared foods.
Distribution Channel:
Channel selection reflects buyer scale and certification requirements, with institutional procurement bypassing retail markup structures entirely.
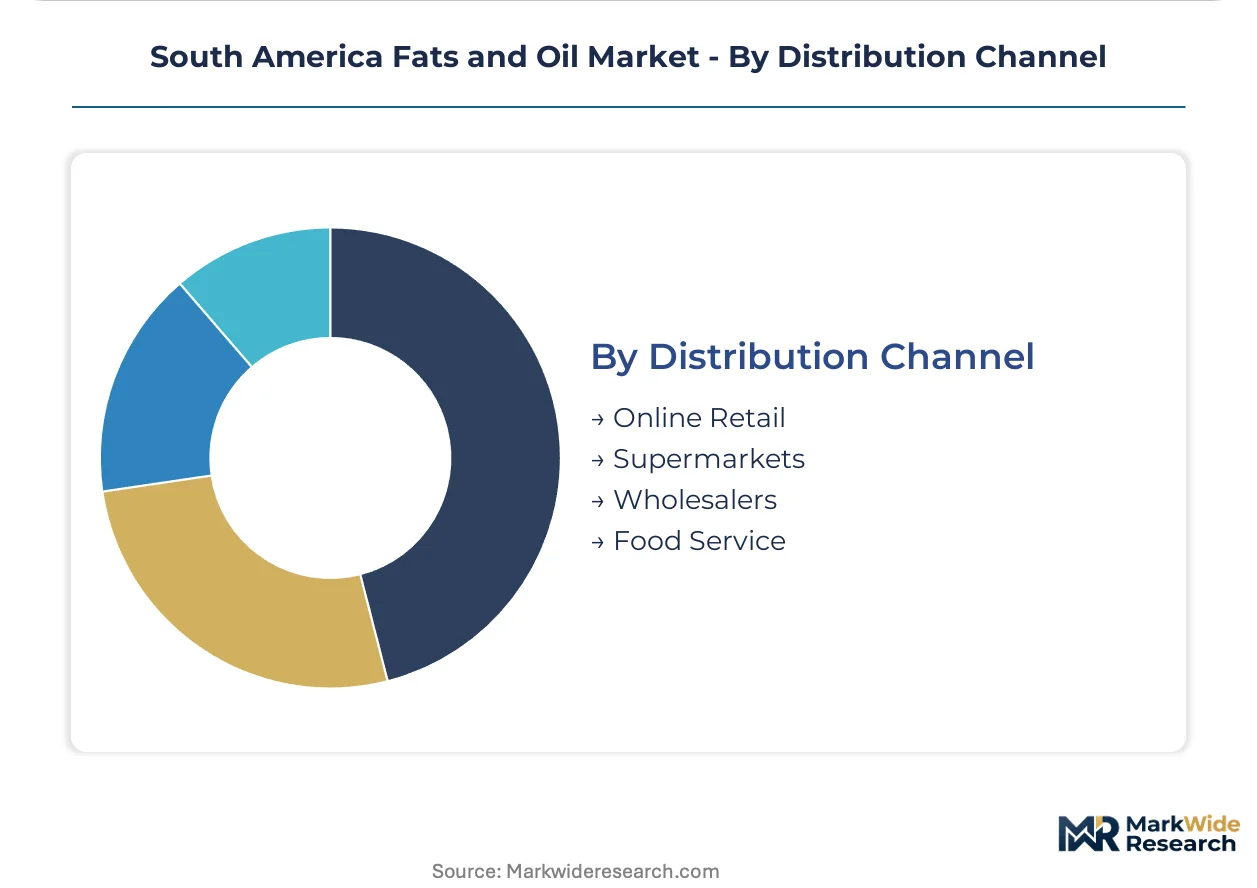
- Online Retail:Direct-to-consumer olive oil and specialty nut oil sales through Mercado Libre and regional e-commerce platforms. Premium packaging and cold-chain logistics constrain margin capture.
- Supermarkets:Branded bottled oils for household consumption, dominated by Carrefour and Cencosud retail networks across Chile and Argentina. Private label expansion is compressing branded manufacturer margins.
- Wholesalers:Bulk refined oil distribution to small and mid-scale food manufacturers lacking direct crush relationships. Paraguayan processors rely on Brazilian wholesale networks for supply security.
- Food Service:High-oleic frying oils and pan-release sprays for restaurant and institutional kitchens. Brazilian fast-casual chains are consolidating procurement through approved distributor networks with quality audit capabilities.
Wholesalers move the largest consolidated volumes. Online Retail is expanding most quickly in premium olive oil segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing engineers and logistics specialists cluster around the Paraná-Paraguay waterway and Brazil's southeastern ports, anchoring regional oilseed flow coordination. Talent density in crushing operations and port terminal management concentrates export capacity in specific sub-regional corridors.
Brazil
ANP biodiesel mandates under Resolution 758 are redirecting soybean oil from São Paulo food manufacturers toward Center-West fuel distributors. RenovaBio carbon intensity scoring creates compliance complexity for biodiesel producers seeking CBIO credit generation. The Santos-Paranaguá port cluster handles the majority of soybean export flows, with crushing capacity expanding in Mato Grosso to serve both domestic and international offtake.
Argentina
AFIP differential export taxation incentivizes domestic crushing over raw bean exports, deepening processing capacity in the Pampas grain belt. The Secretariat of Energy's Decree 543 tightens biodiesel blend requirements, compressing edible oil availability during peak harvest windows. Rosario and Buenos Aires anchor the crushing corridor, with riverfront liquid terminal investments securing Paraná waterway access for bulk oil movements.
Colombia
Magdalena River basin palm plantations are maturing, accelerating crude palm oil output for regional oleochemical manufacturers. National biofuel blending regulations under the Ministry of Mines and Energy are expanding domestic vegetable oil offtake for fuel applications. Barranquilla hosts expanding fractionation capacity serving surfactant and cosmetic ingredient demand from coastal processing complexes.
Ecuador
Esmeraldas province plantation development offers greenfield investment potential for integrated palm oil processors seeking upstream control. The Ministry of Agriculture and Livestock oversees plantation expansion permits affecting supply growth timelines. Guayaquil refiners are qualifying pharmaceutical-grade glycerin outputs for North American personal care multinational supply chains.
Paraguay
Limited domestic crushing infrastructure relative to soybean output creates arbitrage opportunities for cross-border oilseed flows to Argentine and Brazilian refiners. The National Biofuels Program under the Vice Ministry of Mines and Energy is developing blending infrastructure that may redirect future oilseed processing decisions. Asunción-based cooperatives coordinate river barge movements linking production zones to downstream crushing assets.
South America Fats and Oil Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across upstream origination, midstream crushing, and downstream refining segments. Market structure tilts toward consolidation at the crushing tier, where capital intensity and port access create scale barriers. Three archetypes dominate: integrated trading houses with waterway terminal control, plantation-to-refinery palm specialists, and cooperative crushers serving captive food manufacturer demand. Competitive moves center on backward integration into origination assets and strategic partnerships securing RenovaBio carbon credit eligibility.
Within the integrated trading house tier, Bunge Limited and Cargill Inc. exemplify archetypes combining crushing footprint with dual-stream supply flexibility for food and fuel buyers. Louis Dreyfus Company occupies a position emphasizing South American soybean origination scale. Wilmar International represents the plantation-integrated specialist model through refined palm oil distribution channels. These three entities anchor competitive dynamics across Brazilian biodiesel compliance markets and Colombian oleochemical supply chains.
| Leading Market Players |
|---|
| ADM |
| Fuji Oil Holding Inc. |
| Cargill Inc. |
| Wilmar International |
| COFCO International |
| Bunge Limited |
| Olam International Limited |
| Soyven |
| Louis Dreyfus Company |
| Others |
Value Network & Pricing Analysis
Chicago Board of Trade soybean futures cascade through South American crush margins into three distinct pricing tiers: food-grade refined oils for São Paulo manufacturers, fuel-grade methyl esters for ANP-compliant biodiesel blenders, and pharmaceutical-grade excipients for ANVISA-certified drug formulators. This commodity benchmark tethering concentrates pricing power among integrated crushers with dual-stream flexibility while squeezing unhedged refiners exposed to basis risk between CME settlements and local port differentials.
Pricing Analysis
Unbundled commodity crush services dominate transactional flows, while bundled origination-to-refinery contracts secure volume commitments from multinational food processors. Three-tier pricing structure across pharmaceutical-grade, food-grade, and fuel-grade certifications separates premium excipient oils from standard edible applications and economy biodiesel feedstocks. Price differentiation hinges on carbon intensity scores under RenovaBio and ANVISA purity certifications. Margins are tightening due to ANP mandate-driven feedstock competition. Small and mid-scale food manufacturers in Argentina's interior exhibit highest price sensitivity, lacking long-term offtake agreements.
Supply Chain Analysis
Reverse-logistics flows for used cooking oil collection and re-refining remain embryonic across South America, with informal sector recovery in Brazilian urban centers supplying limited biodiesel feedstock supplementation. Geographic supply concentrates in Brazil, Argentina, and Colombia, with crushing capacity clustering around Santos, Rosario, and Barranquilla terminals. Raw material dependencies center on Mato Grosso soybeans, Magdalena River basin palm fruit, and Pampas sunflower seed. Single-source vulnerability runs through Paraná-Paraguay waterway chokepoints during low-water windows. Distribution runs through integrated trading house networks controlling riverfront liquid terminals and port vessel scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America presents a geographic-arbitrage play between Brazilian RenovaBio carbon credit generation and Argentine export tax volatility, with crush margin differentials widening based on biodiesel mandate compliance costs.
For Market Incumbents: Acquire riverfront liquid terminal assets along the Paraná-Paraguay waterway to secure barge-to-vessel transfer capacity. Consolidate crushing footprint in Mato Grosso to capture both food and fuel offtake streams. Defensive positioning requires investment in enzymatic interesterification technology to eliminate trans-fat reformulation costs threatening bakery shortening margins. For New Entrants and Emerging Players: Enter via Esmeraldas province greenfield palm plantations, exploiting underdeveloped Ecuadorian processing infrastructure relative to Colombian maturation curves. Target pharmaceutical-grade glycerin qualification for North American personal care supply chains. White-space concentration exists in Paraguayan cross-border oilseed arbitrage to Argentine refiners. Go-to-market leverage rests on direct origination partnerships bypassing trading house intermediaries. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated palm plantation-to-refinery specialists controlling Magdalena River basin acreage. Long-term viability favors upstream asset control over pure-play trading exposure. Acquisition screening should prioritize crushers with dual ANVISA-ANP certification capabilities. Monitor AFIP export tax decree modifications as inflection signal for Argentine crush margin direction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Upstream control over Magdalena River basin palm acreage secures feedstock certainty for Barranquilla fractionation capacity. |
| Dual-Certification Capacity Investment | Parallel ANVISA pharmaceutical and ANP fuel qualification opens premium margin pools across excipient and biodiesel segments. |
| RenovaBio Carbon Credit Optimization | Below-baseline carbon intensity scoring generates tradable CBIO credits for Center-West biodiesel producers. |
| Enzymatic Interesterification Adoption | Trans-fat-free bakery shortening production eliminates MERCOSUR reformulation compliance costs for packaged goods exporters. |
| Cross-Border Paraguay Crushing Arbitrage | Limited domestic processing infrastructure creates feedstock sourcing advantages for Argentine and Brazilian refiners. |
Research Methodology
Coverage spans Brazil, Argentina, Colombia, Ecuador, and Paraguay, with primary inputs from each national market. Crushing plant managers, ANP compliance officers at fuel distributors, pharmaceutical procurement leads, and river barge logistics coordinators supplied operational data. Secondary validation drew from ANP Resolution filings, AFIP tax decree records, SEC 10-K disclosures by listed trading houses, and customs export statistics. Bottom-up volume estimates triangulated against top-down macroeconomic consumption benchmarks.
Granularity-level modeling distinguished vegetable oil, palm oil, olive oil, and animal fat product types; food processing, personal care, biofuels, and pharmaceutical applications; liquid, solid, semi-solid, and emulsified physical forms; and online retail, supermarket, wholesale, and food service channels. CAGRs were derived from segment-level growth trajectory analysis. Forecast inputs incorporated ANP blend mandate escalation schedules, AFIP differential taxation regimes, and plantation maturity curves across the Magdalena and Esmeraldas basins.
Inputs from ANP, AFIP, and national agricultural ministries were available through the study window; gaps in real-time crush margin data introduce uncertainty bands around quarterly estimates. Forecasts reflect documented assumptions regarding mandate compliance trajectories and weather-normalized soybean yields. Practitioners should monitor ANP Resolution amendments, AFIP export tax decree modifications, and Paraná River hydrological indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Gluten-Free Flour Market
Ingredients
Avocado Oil Market
Ingredients
Proteose Peptone Market
Ingredients
Soybean Meal Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Black Seed Oil Market
Ingredients
Fats and Oils Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Cocoa Liquor Market
Ingredients
Indonesia Edible Oil Market
Ingredients
Pea Peptones Market
Ingredients
North America Carrageenan Market
Ingredients
North America Wheat Protein Ingredients Market
Ingredients
North America Gelatin Market