
 Cobalt Acetate Solution Market | 2026-2036
Cobalt Acetate Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Acetate Solution Market Analysis
Specialty chemical distribution is fragmenting as regional distributors lose ground to direct manufacturer-to-end-user contracts in cobalt acetate supply. Umicore leverages its integrated refining network across Belgium and Finland to secure feedstock certainty. Freeport Cobalt anchors North American supply through captive mine-to-metal processing in the Democratic Republic of Congo and Iowa refining. Mechema Chemicals International competes on specification flexibility, offering customized concentration grades for catalyst formulators.
Cobalt acetate solution, typically prepared as a pink aqueous solution containing cobalt(II) acetate tetrahydrate at concentrations between 5% and 20% Co by weight, serves primarily as a precursor for oxidation catalysts in polyester resin production and desulfurization systems. Industrial grade material dominates volume flows into catalyst production for PTA manufacturing, where margin pools remain deepest due to long-term supply agreements with petrochemical operators. Reagent grade solutions command premium positioning in pharmaceutical and laboratory channels where analytical purity specifications under ACS standards create defensible pricing tiers.
REACH registration requirements in Europe and EPA hazardous substance reporting in the United States elevate compliance costs for importers, pushing end-users toward qualified suppliers with established regulatory dossiers. China's GB standards for cobalt compound purity and SAMR environmental licensing for chemical manufacturers constrain new entrant capacity additions. Stakeholders must monitor cobalt sourcing transparency initiatives and evolving battery-material competition for mined feedstock as determinants of acetate solution availability and cost structure.
Market Dynamics
China's SAMR export licensing regime for cobalt raw materials is compressing spot market liquidity and forcing petrochemical catalyst producers into long-term offtake negotiations with integrated refiners.
Growth Catalysts
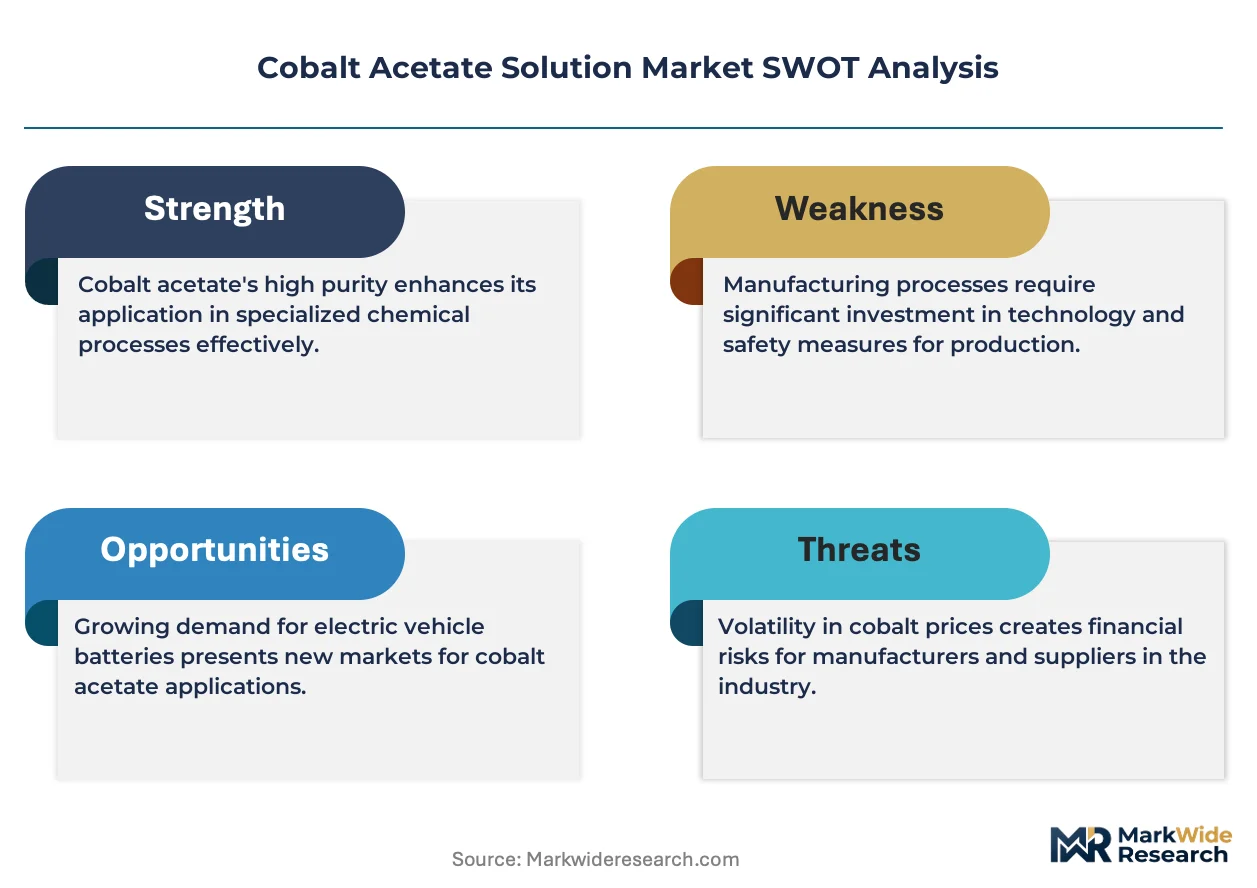
- REACH registration dossiers:European ECHA compliance requirements for cobalt compounds create qualified supplier lists that lock out unregistered traders and cement incumbent positions.
- Hydrodesulfurization intensity:Stricter sulfur specifications in marine fuels under IMO 2020 are expanding cobalt acetate consumption in refinery catalyst systems.
- Jiangsu refining cluster:Concentrated domestic cobalt processing capacity in eastern China is shortening lead times for Asia-Pacific catalyst formulators.
Market Restraints
- Feedstock cost volatility:Cobalt metal price swings on the London Metal Exchange transmit directly into acetate solution manufacturing economics.
- Single-origin supply risk:Democratic Republic of Congo mine concentration creates ESG audit exposure and forced labor disclosure obligations under US CTPA and EU CSRD.
- Phosphate substitution:Cobalt-free catalyst precursors for certain oxidation reactions are advancing in laboratory validation.
Strategic Opportunities
- India PTA expansion:Reliance Industries and Indian Oil Corporation are adding purified terephthalic acid capacity that requires cobalt acetate catalyst systems.
- Closed-loop recycling:Spent catalyst recovery streams from polyester manufacturing offer secondary cobalt feedstock with lower carbon intensity than primary mining.
- Direct manufacturer contracts:Catalyst producers are bypassing regional distributors to secure specification-customized solutions and technical service integration.
Industry Challenges
- Metallurgical expertise scarcity:Cobalt hydrometallurgy process engineers command premium compensation and limited mobility between mining and chemical processing sectors.
- Multi-jurisdiction dossier maintenance:Simultaneous EPA TSCA reporting, REACH registration updates, and China's MEE chemical inventory compliance create ongoing administrative burden.
- Legacy specification inertia:Petrochemical operators resist reformulating catalyst systems despite modest performance gains from alternative cobalt concentrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Acetate Solution Market |
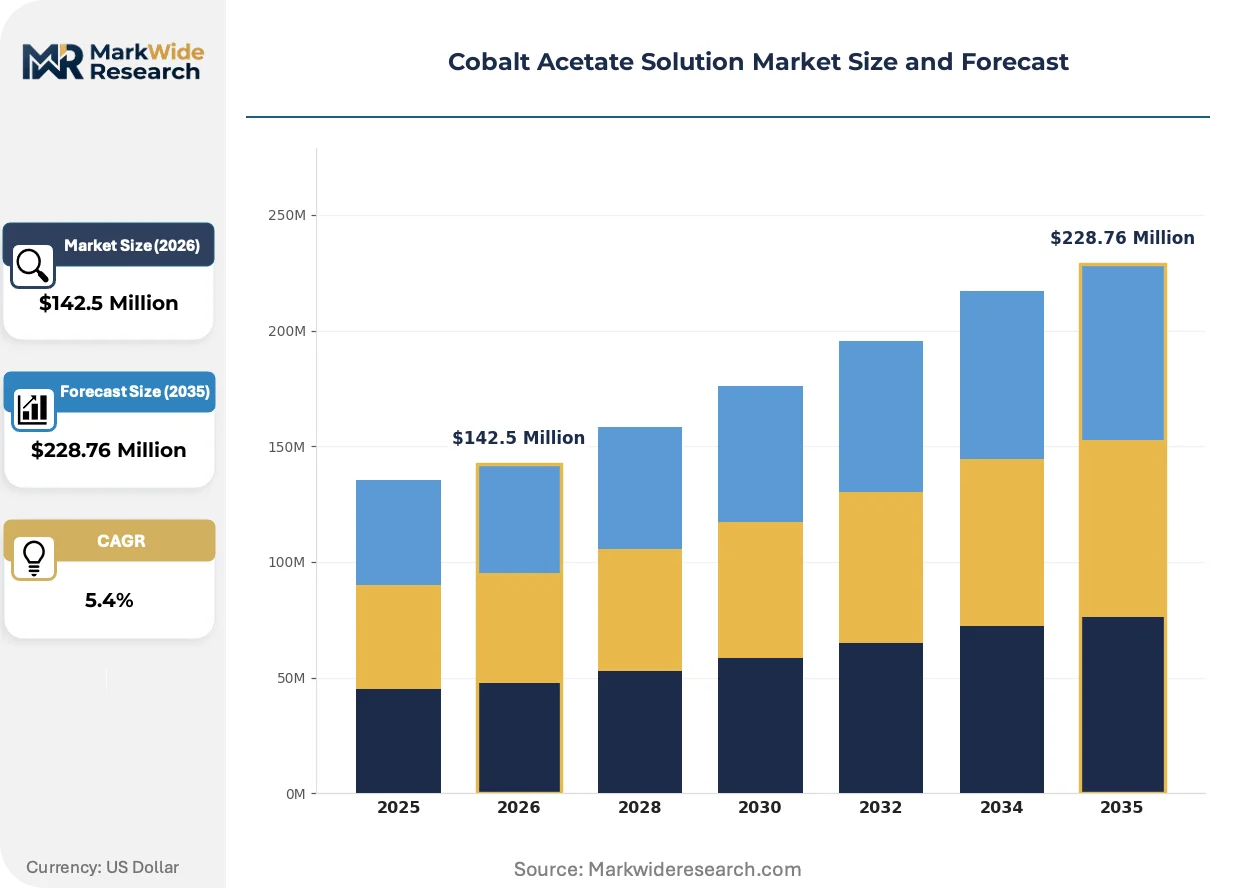
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $228.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Analytical Grade, Laboratory Grade Application: Catalyst Production, Pigment Manufacturing, Chemical Synthesis, Nutritional Supplement End User: Pharmaceuticals, Agriculture, Electronics, Various Industries Packaging Type: Drums, Bottles, Bulk Containers, Customized Packaging |
| Companies Covered | Coremax Corporation, Umicore, Mechema Chemicals International, Freeport Cobalt, American Elements, Nanjing Chemical Reagent, Liaoyang Synthetic Catalyst, Jiangxi Nuclear Industry, TIANFU CHEMICAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Acetate Solution Market Emerging Trajectories
Process intensification and regulatory disclosure requirements are reshaping how cobalt acetate solutions are manufactured, certified, and procured across catalyst supply chains.
Continuous flow synthesis of cobalt acetate tetrahydrate is rendering obsolete traditional batch crystallization methods in European and North American production facilities. Specialty chemical manufacturers in Belgium and Finland are retrofitting pilot plants to demonstrate consistent particle size distribution and reduced solvent waste. The shift is compressing capital recovery timelines for producers while raising barriers for batch-only competitors.
ECHA's SCIP database obligations under the EU Waste Framework Directive are forcing catalyst formulators to document cobalt origin through entire supply chains. Downstream petrochemical operators now require batch-level traceability certificates to satisfy circular economy reporting mandates. German and Dutch catalyst consumers are consolidating supplier panels to reduce compliance administration costs.
Specification-driven purchasing is displacing commodity spot buying among North American polyester resin producers. Technical service agreements now bundle cobalt acetate supply with catalyst performance guarantees and spent material take-back programs. The model is most visible along the US Gulf Coast where integrated PTA manufacturers negotiate multi-year contracts with embedded price adjustment mechanisms.
Cobalt Acetate Solution Market Segmentation
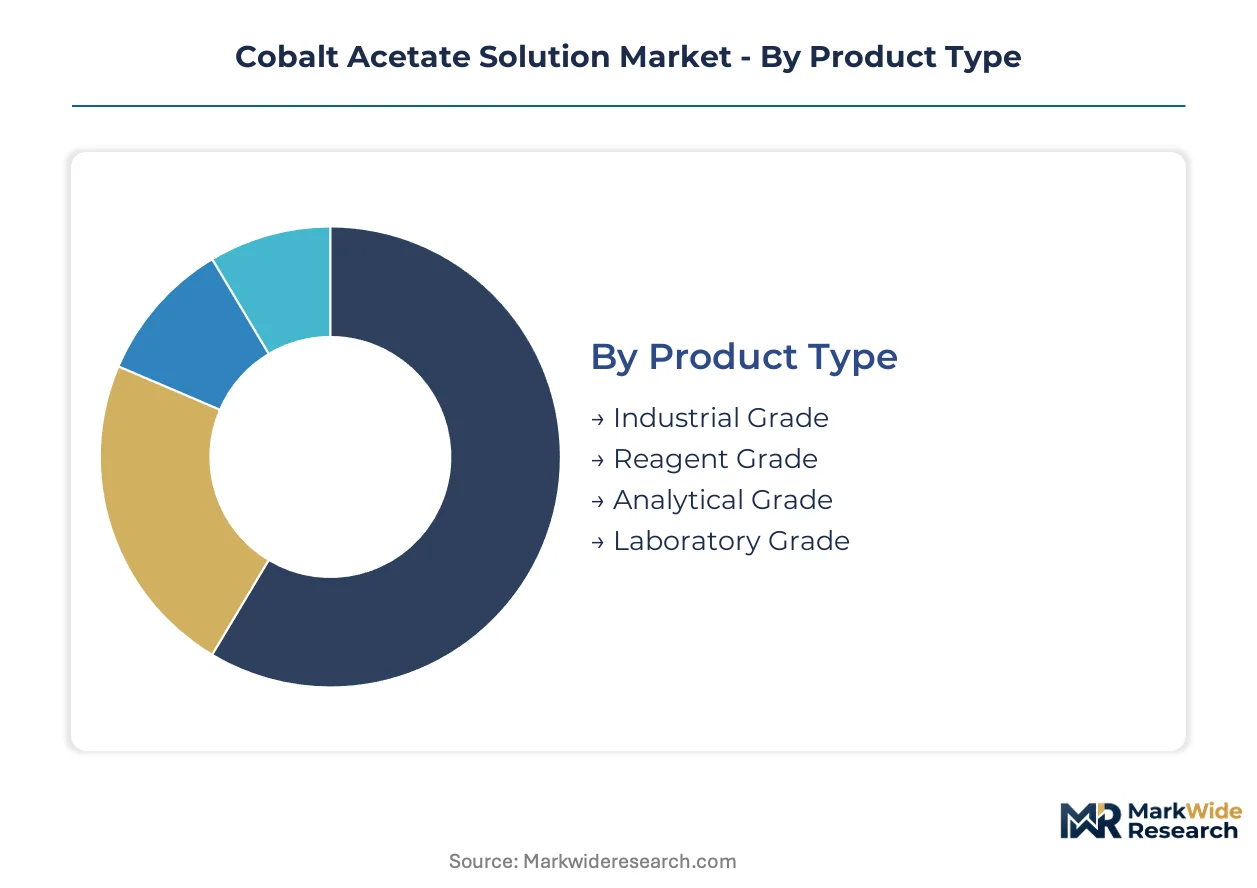
Cobalt acetate solution procurement cycles vary dramatically across grades and end-uses, from quarterly bulk catalyst replenishment to sporadic laboratory reagent orders. Understanding these velocity patterns helps suppliers align inventory positioning with actual consumption rhythms rather than aggregated demand assumptions.
Product Type:
Cycle times compress sharply as purity escalates, with industrial grade moving on monthly contracts while analytical grade sits in multi-year qualification pipelines.
- Industrial Grade:Aqueous solutions containing 5-20% cobalt by weight dominate hydrodesulfurization catalyst formulation for PTA manufacturing. Petrochemical operators in Jiangsu province negotiate annual tonnage commitments with integrated refiners to hedge against SAMR export licensing volatility.
- Reagent Grade:ACS-standard purity specifications support pharmaceutical synthesis and quality control laboratories. German and Dutch catalyst consumers now require batch-level SCIP database traceability under ECHA Waste Framework Directive obligations, extending procurement lead times.
- Analytical Grade:Ultra-high purity for instrumental calibration and reference standards.
- Laboratory Grade:Educational and routine testing applications with relaxed specification tolerances.
Industrial grade anchors the volume base while reagent grade gains share at the steepest rate.
Application:
Margin structures diverge widest here, with catalyst production capturing embedded technical service value versus commodity pigment blending.
- Catalyst Production:Oxidation catalyst precursors for polyester resin manufacturing require precise cobalt concentration control and spent catalyst take-back programs. Reliance Industries and Indian Oil Corporation are expanding purified terephthalic acid capacity that specifies cobalt acetate systems.
- Pigment Manufacturing:Ceramic and glass colorants utilize lower-purity solutions with minimal technical support bundling.
- Chemical Synthesis:Organic reaction intermediates and specialty chemical manufacturing.
- Nutritional Supplement:Cobalt fortification for animal feed and trace mineral formulations.
Catalyst production commands the deepest margin pools while pigment manufacturing competes primarily on delivered cost.
End User:
Customer concentration patterns split the market between consolidated pharmaceutical procurement teams and fragmented agricultural distributors.
- Pharmaceuticals:GMP-compliant manufacturing demands reagent-grade material with full regulatory dossiers including REACH registration and EPA TSCA reporting. Multi-jurisdiction compliance maintenance creates supplier stickiness once qualified.
- Agriculture:Nutritional supplement applications for livestock feed cobalt fortification.
- Electronics:Specialty plating and battery material research applications.
- Various Industries:Diverse industrial applications including surface treatment and adhesives.
Pharmaceuticals concentrate purchasing power among few qualified suppliers while agriculture fragments across regional distributors.
Packaging Type:
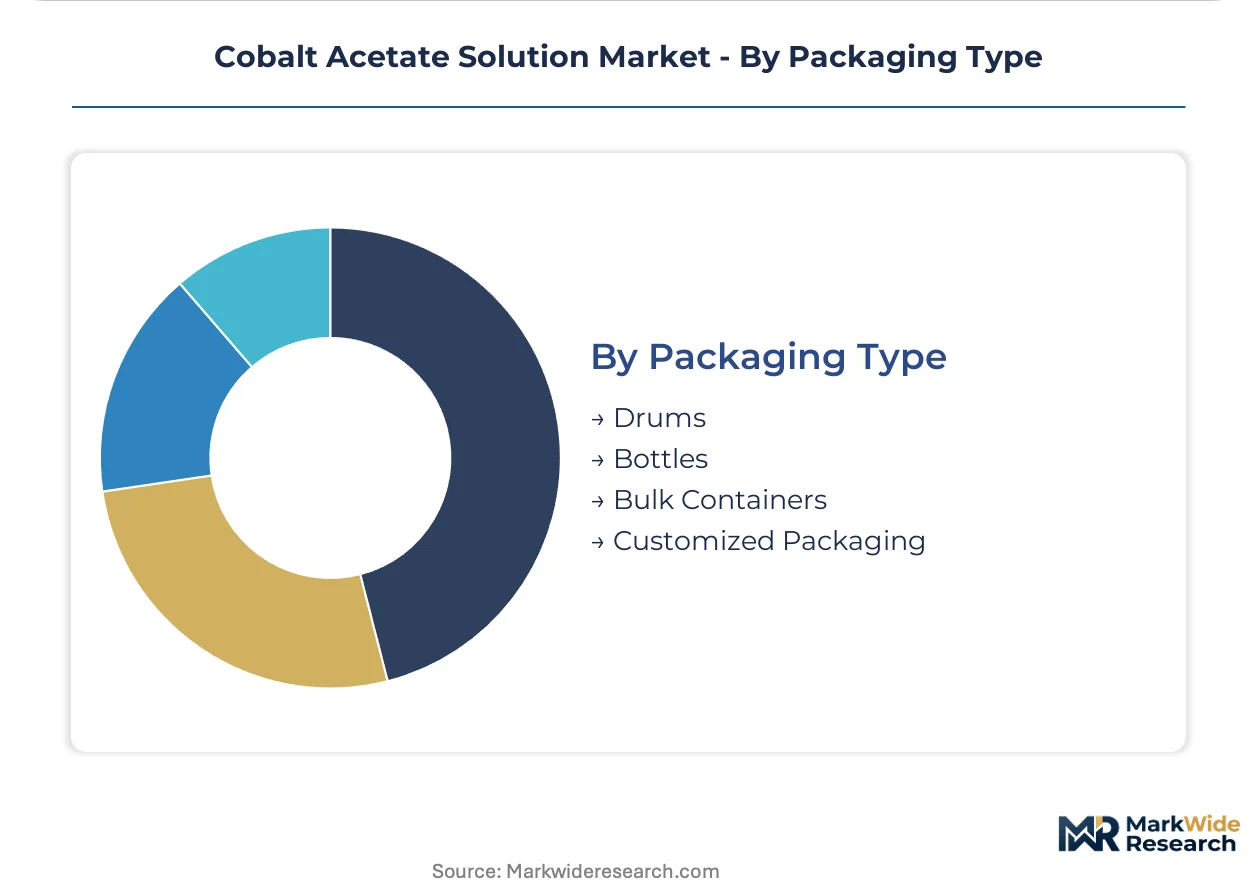
Logistics economics favor bulk for integrated PTA producers while flexibility premiums attach to customized configurations.
- Drums:Standard 200-liter steel drums serve mid-volume catalyst formulators with predictable consumption schedules.
- Bottles:Laboratory and pilot-scale quantities for pharmaceutical development and quality control.
- Bulk Containers:ISO tank deliveries and dedicated tanker shipments for US Gulf Coast polyester resin manufacturers under multi-year direct contracts.
- Customized Packaging:Client-specified containers with embedded RFID tracking for ESG audit trails under EU CSRD disclosure requirements.
Bulk containers dominate tonnage flows while customized packaging expands most quickly on traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao-Yantai port corridor on China's Shandong Peninsula anchors cobalt acetate logistics for Asia-Pacific catalyst formulators, with dedicated chemical tanker berths reducing inland transit exposure.
China
Jiangsu province hosts the densest cobalt refining cluster globally, with Zhenjiang and Taizhou facilities supplying PTA manufacturers under SAMR-licensed export protocols. GB standards for cobalt compound purity constrain new chemical inventory registrations. The Yangtze River Delta concentration shortens procurement cycles for Korean and Japanese catalyst formulators.
United States
Gulf Coast polyester resin producers negotiate multi-year cobalt acetate contracts with embedded LME price adjustment clauses. EPA TSCA reporting requirements for cobalt compounds elevate compliance costs for importers. Iowa-based refining operations process DRC-sourced feedstock through captive mine-to-metal infrastructure.
Germany
Ruhr Valley catalyst formulators source reagent-grade material under REACH-registered supplier panels. ECHA's SCIP database mandates batch-level cobalt origin documentation. Leverkusen and Ludwigshafen chemical parks concentrate technical service bundling for pharmaceutical-grade specifications.
India
Reliance Industries' Jamnagar refinery expansion specifies cobalt acetate catalyst systems for purified terephthalic acid output. CDSCO pharmaceutical manufacturing compliance drives reagent-grade qualification timelines. Gujarat's Dahej chemical zone attracts direct manufacturer contracts bypassing Mumbai distributors.
Belgium
Antwerp's integrated refining network secures feedstock certainty for European catalyst producers through Rotterdam port access. REACH registration dossiers for cobalt acetate lock out unregistered traders from qualified supplier lists. The Port of Antwerp-Bruges chemical terminals handle bulk ISO tank flows for German and Dutch end-users.
Cobalt Acetate Solution Market Vendor Landscape
On the supply side, the industry is consolidating around integrated refiners with captive feedstock access and qualified regulatory dossiers. Three strategic archetypes dominate: integrated mining-to-chemical processors securing upstream cobalt control, specialty chemical distributors competing on specification flexibility, and regional reagent manufacturers serving pharmaceutical qualification pipelines. Capacity expansion and direct manufacturer contracting represent the dominant competitive moves, with catalyst formulators bypassing distributors for technical service integration.
Among integrated refining specialists, Umicore anchors the European tier through Belgium-Finland network coverage, while Freeport Cobalt occupies the North American position with DRC-Iowa processing infrastructure. Mechema Chemicals International exemplifies the specification-flexibility archetype, competing on customized concentration grades for catalyst formulators. These three represent the structural poles around which procurement patterns organize.
| Leading Market Players |
|---|
| Coremax Corporation |
| Umicore |
| Mechema Chemicals International |
| Freeport Cobalt |
| American Elements |
| Nanjing Chemical Reagent |
| Liaoyang Synthetic Catalyst |
| Jiangxi Nuclear Industry |
| TIANFU CHEMICAL |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Jiangsu province's cobalt refining cluster is tightening spot availability and pushing petrochemical catalyst producers toward annual offtake negotiations with integrated suppliers. SAMR export licensing constraints on raw cobalt feedstock have compressed supplier margins while amplifying pricing power for qualified refiners with captive mine access.
Pricing Analysis
Volume-discount tiering separates industrial-grade bulk contracts from reagent-grade qualification premiums. Three-tier pricing structure across premium, standard, and economy levels anchors the market: industrial-grade solutions for PTA manufacturing compete on delivered cost, while reagent-grade material commands certification premiums under REACH and ACS standards. Cost compression in industrial-grade segments is intensifying because phosphate-based catalyst substitutes are advancing in laboratory validation. Petrochemical operators show lowest price sensitivity due to embedded catalyst performance guarantees, whereas pigment manufacturers exhibit highest sensitivity with minimal technical service bundling.
Supply Chain Analysis
Contract-manufacturing concentration rests with Umicore's Belgium-Finland network and Freeport Cobalt's DRC-Iowa infrastructure. Geographic supply concentration centers on China, Belgium, and the United States, with Jiangsu province hosting the densest refining cluster globally. Raw material dependencies draw from DRC-mined cobalt ore, sulfuric acid for hydrometallurgical processing, and acetic acid for salt formation. Single-origin supply risk from DRC mine concentration creates ESG audit exposure under US CTPA and EU CSRD. Distribution runs through direct manufacturer-to-end-user contracts bypassing regional distributors, particularly along the US Gulf Coast and in Gujarat's Dahej chemical zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cobalt acetate solution demand functions as a substitution defense against phosphate-based oxidation catalyst precursors now advancing through laboratory validation pipelines. Incumbents must navigate this substitute threat while securing feedstock certainty amid tightening Chinese export controls.
For Market Incumbents: Harden qualified supplier positions by deepening backward integration into DRC mine-to-metal infrastructure and accelerating REACH registration dossier updates ahead of ECHA SCIP database expansion. Lock in multi-year offtake agreements with Reliance Industries and Indian Oil Corporation as Indian PTA capacity scales. Technical service bundling with spent catalyst take-back programs creates stickiness against phosphate substitution threats. For New Entrants and Emerging Players: Pursue specification-flexibility positioning in reagent-grade pharmaceutical channels where ACS-standard qualification timelines extend 18-24 months and incumbent panels remain thin. Target CDSCO-compliant manufacturing in India where direct contracts are displacing Mumbai distributors. Closed-loop recycling partnerships with polyester manufacturers offer lower-carbon-intensity feedstock differentiation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous-flow synthesis retrofitting as batch crystallization methods become obsolete. Long-term viability over the next decade hinges on captive cobalt sourcing and regulatory dossier depth rather than commodity trading margins. Acquisition candidates should demonstrate integrated refining networks with SAMR-licensed export protocols. The signal to watch is ECHA database expansion mandating batch-level origin documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DRC Mining | Secures feedstock certainty against SAMR export licensing volatility for integrated refiners. |
| Continuous Flow Synthesis Retrofit | Compresses capital recovery timelines while raising barriers for batch-only European competitors. |
| REACH Registration Dossier Expansion | Locks out unregistered traders from qualified supplier panels under ECHA compliance requirements. |
| Direct Manufacturer Contracting | Bypasses regional distributors for US Gulf Coast polyester resin producers seeking technical integration. |
| Closed-Loop Recycling Partnership | Offers secondary cobalt feedstock with lower carbon intensity than primary DRC mining operations. |
Methodological Framework
Operator-level perspectives from cobalt refinery plant managers, petrochemical catalyst procurement leads, specialty chemical distribution channel partners, and pharmaceutical quality control directors anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings for diversified chemical companies, and SAMR chemical inventory registrations. Bottom-up capacity modeling across Jiangsu and Shandong provinces triangulated against top-down demand estimates from PTA manufacturing capacity announcements.
Scenario-bracketing framed projections across base, high, and low cases without specifying endpoint years. Segmentation dimensions modeled included grade tier (industrial versus reagent), end-use industry (catalyst production versus pigment manufacturing), packaging format (bulk versus drums versus bottles), and regional production hub concentration. CAGRs derived from historical volume trajectories adjusted for announced capacity additions and regulatory intervention timing. Forecast inputs incorporated LME cobalt price volatility bands and IMO 2020 sulfur specification enforcement intensity.
Sensitivities concentrate around SAMR export licensing regime changes, phosphate catalyst substitution breakthroughs, and DRC supply disruptions from ESG audit failures. Forecasts reflect assumptions about continued petrochemical catalyst demand and REACH registration maintenance without guarantee. Quarterly review of ECHA database expansion, Indian PTA construction timelines, and cobalt metal exchange spreads is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Proline Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Cryogenic Column Market