
 Cetrorelix Acetate API Market | 2026-2036
Cetrorelix Acetate API Market Size, Share, and Industry Trends Forecast 2026-2036
Cetrorelix Acetate API Market Insights
EMA's revised peptide impurity guidelines is recalibrating the capital threshold for European market entry. Bachem AG leverages its Swiss manufacturing base and captive raw material sourcing to sustain cost predictability amid regulatory escalation. Polypeptide Group anchors its competitive position through dedicated GMP peptide suites in Sweden and the United States. Merck KGaA differentiates via analytical method development partnerships that accelerate client regulatory filings.
Cetrorelix Acetate API comprises a synthetic decapeptide antagonist of gonadotropin-releasing hormone, manufactured through solid-phase peptide synthesis with acetylation at the N-terminus and acetate salt formation for enhanced stability in parenteral formulations. The compound blocks GnRH receptor signaling to prevent premature luteinizing hormone surges during assisted reproductive technology cycles. Injectable formulations dominate current revenue contribution due to established clinical protocols and refrigeration-dependent supply chains, while lyophilized formats represent the fastest-expanding category as ambulatory fertility centers seek reduced cold-chain dependency. Cancer therapy applications command premium pricing relative to fertility treatments, reflecting smaller batch sizes and more stringent endotoxin specifications.
FDA peptide CMC guidance, EMA MDR transition timelines, and India's CDSCO Schedule M compliance mandates collectively elevate documentation burdens for API exporters. ISO 17025-accredited analytical testing has become a de facto market access requirement rather than a competitive differentiator. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and EP monographs, as divergence in assay acceptance criteria directly impacts batch release economics and inventory allocation across regulated markets.
Market Dynamics
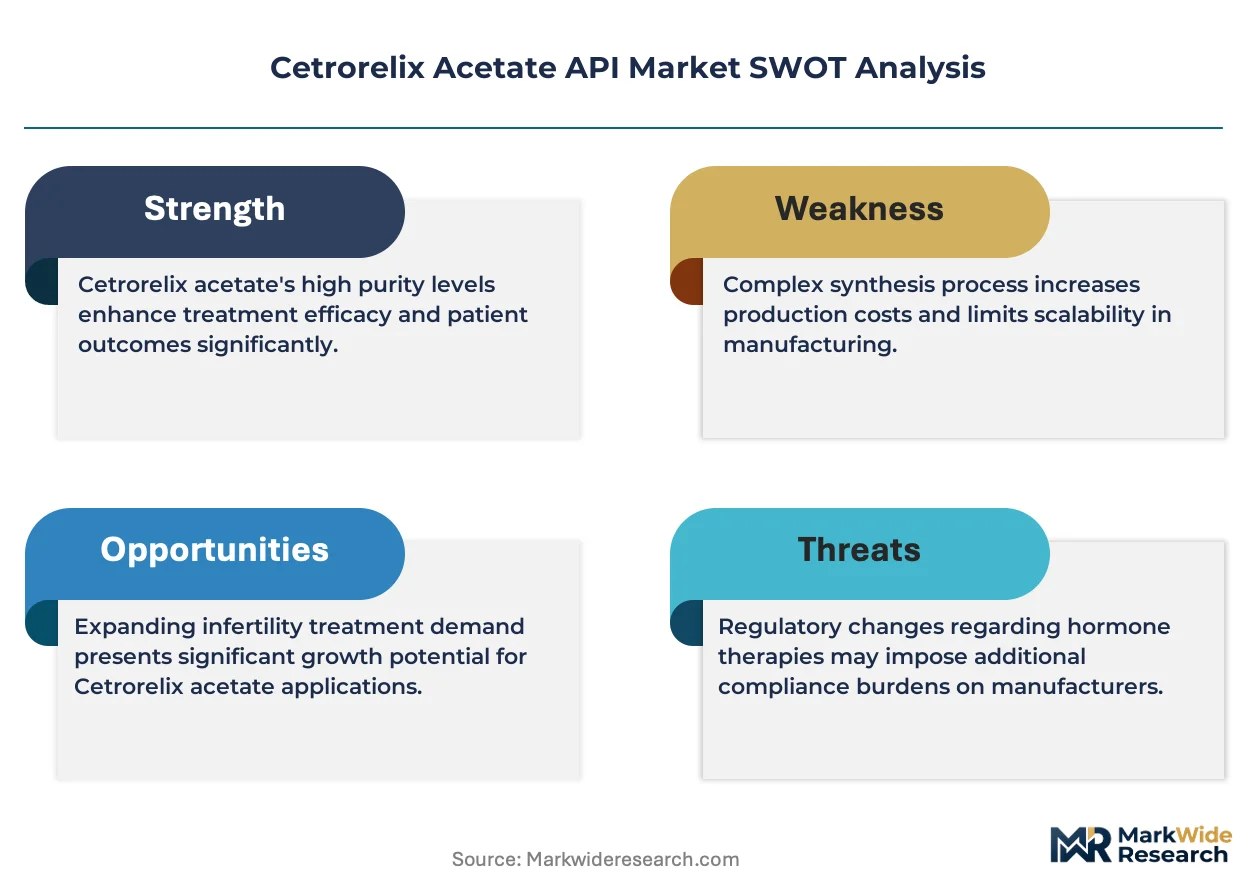
EMA's tightened impurity profiling mandates for synthetic peptides are forcing manufacturers to reconfigure quality systems and capital deployment across European supply chains.
Growth Catalysts
- Controlled ovarian stimulation protocols:Fertility clinics in Germany, India, and the United States are expanding GnRH antagonist procurement volumes to support rising IVF cycle volumes.
- CDSCO Schedule M compliance:India's tightened plant audit standards are filtering out subscale peptide manufacturers, concentrating contract manufacturing demand among certified suppliers.
- Lyophilized format adoption:Ambulatory fertility centers are switching from refrigerated injectables to cold-chain-independent presentations, opening new distribution channels.
Market Restraints
- Amino acid raw material concentration:Captive supply of protected amino acids sits with a limited set of European and Japanese chemical suppliers, creating input cost volatility.
- Solid-phase synthesis capacity scarcity:Large-scale SPPS reactor availability is geographically concentrated in Switzerland and Sweden, limiting rapid capacity expansion.
- Peptide impurity specification divergence:Misalignment between USP-NF and EP monograph acceptance criteria forces dual-method validation and inventory segmentation.
Strategic Opportunities
- Cancer therapy applications:GnRH antagonist use in oncology protocols commands premium pricing and smaller batch economics distinct from fertility markets.
- ISO 17025 analytical partnerships:Third-party testing accreditation is becoming a de facto market access requirement, creating service revenue streams for qualified laboratories.
- Indian contract manufacturing:BIS certification and export-oriented peptide synthesis capabilities position domestic manufacturers for European and North American outsourcing.
Industry Challenges
- Peptide synthesis specialist talent:Solid-phase chemistry and analytical method development expertise is concentrated among aging workforces in Basel and Stockholm clusters.
- GMP suite reconfiguration timelines:EMA's revised guidelines require 18-24 month facility upgrade cycles, compressing effective capacity during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cetrorelix Acetate API Market |
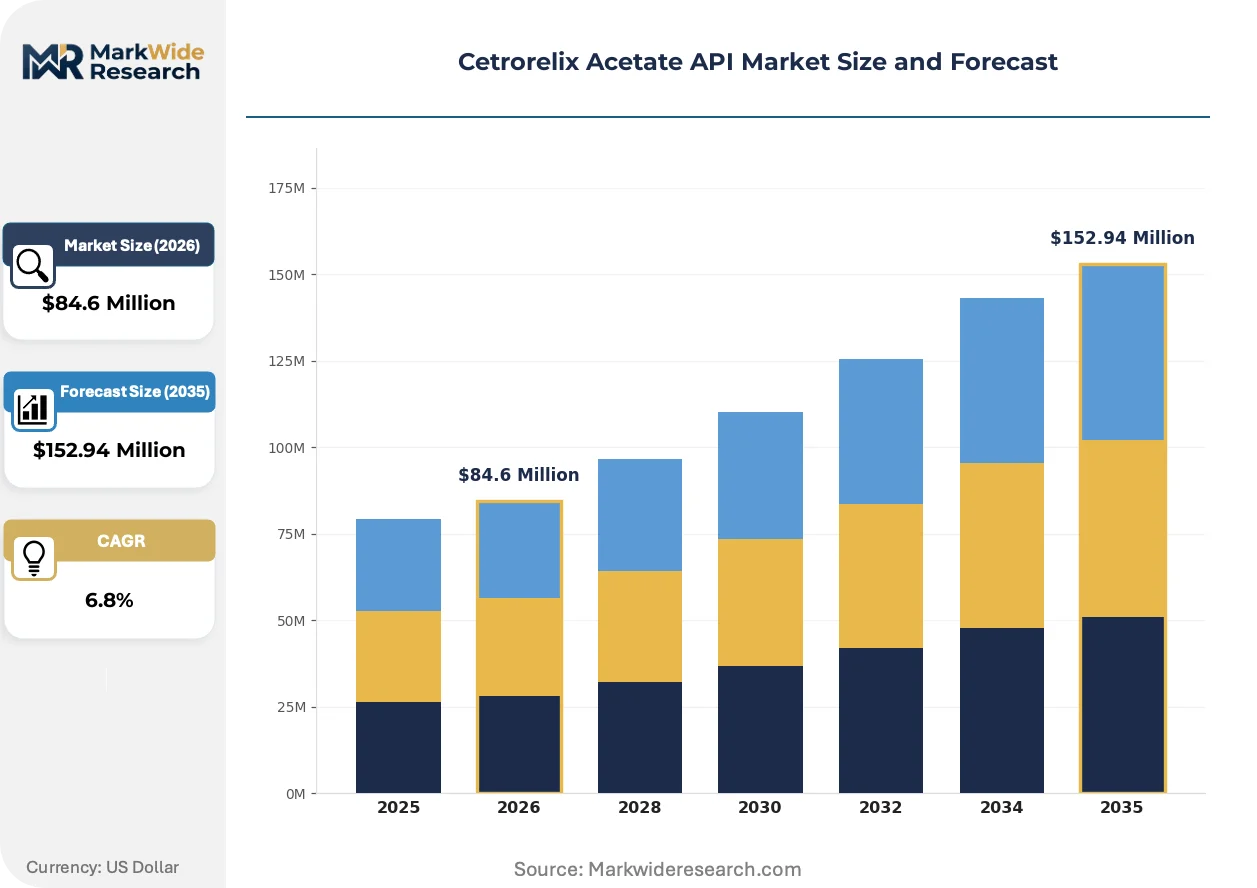
| Market Size in 2026 | $84.6 Million |
| Market Size in 2035 | $152.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Lyophilized, Solution, Powder Application: Fertility Treatments, Hormonal Interventions, Cancer Therapy, Endometriosis Management End User: Hospitals, Clinics, Pharmacies, Research Laboratories Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Bachem AG, Polypeptide Group, Merck KGaA, Teva Pharmaceutical Industries Ltd., Hemmo Pharmaceuticals, AmbioPharm Inc., Hybio Pharmaceutical Co., Ltd., CPC Scientific, Inc., Biophore India Pharmaceuticals Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cetrorelix Acetate API Market Trends and Innovations
Continuous processing technologies and regulatory harmonization efforts are compressing batch economics while redrawing competitive boundaries between integrated and modular supply architectures.
Continuous flow peptide synthesis is modularizing production economics by enabling real-time process analytical technology integration and reduced solvent consumption. Mid-scale API manufacturers in India and Eastern Europe are piloting these systems to bypass large-batch reactor bottlenecks. The technology is modularizing capital deployment patterns, allowing entrants to scale through replicated skid units rather than single-site mega-facilities.
EMA's Medical Device Regulation transition timelines are recalibrating combination product filing strategies for peptide-delivery systems. Drug-device developers must now synchronize API CMC documentation with device quality management system audits. Injectable fertility products face the steepest compliance burden, with sponsors consolidating regulatory affairs functions in Brussels and Amsterdam to manage parallel EMA-NB interactions.
Long-term offtake agreements are displacing spot procurement for multi-kilogram peptide batches as fertility clinic networks consolidate purchasing through group procurement organizations. Large US clinic chains and Indian hospital networks are centralizing API sourcing decisions, squeezing regional distributor margins. This concentration is most visible in Germany's university hospital fertility centers, where tender volumes now exceed single-manufacturer annual capacity.
Cetrorelix Acetate API Market Segmentation
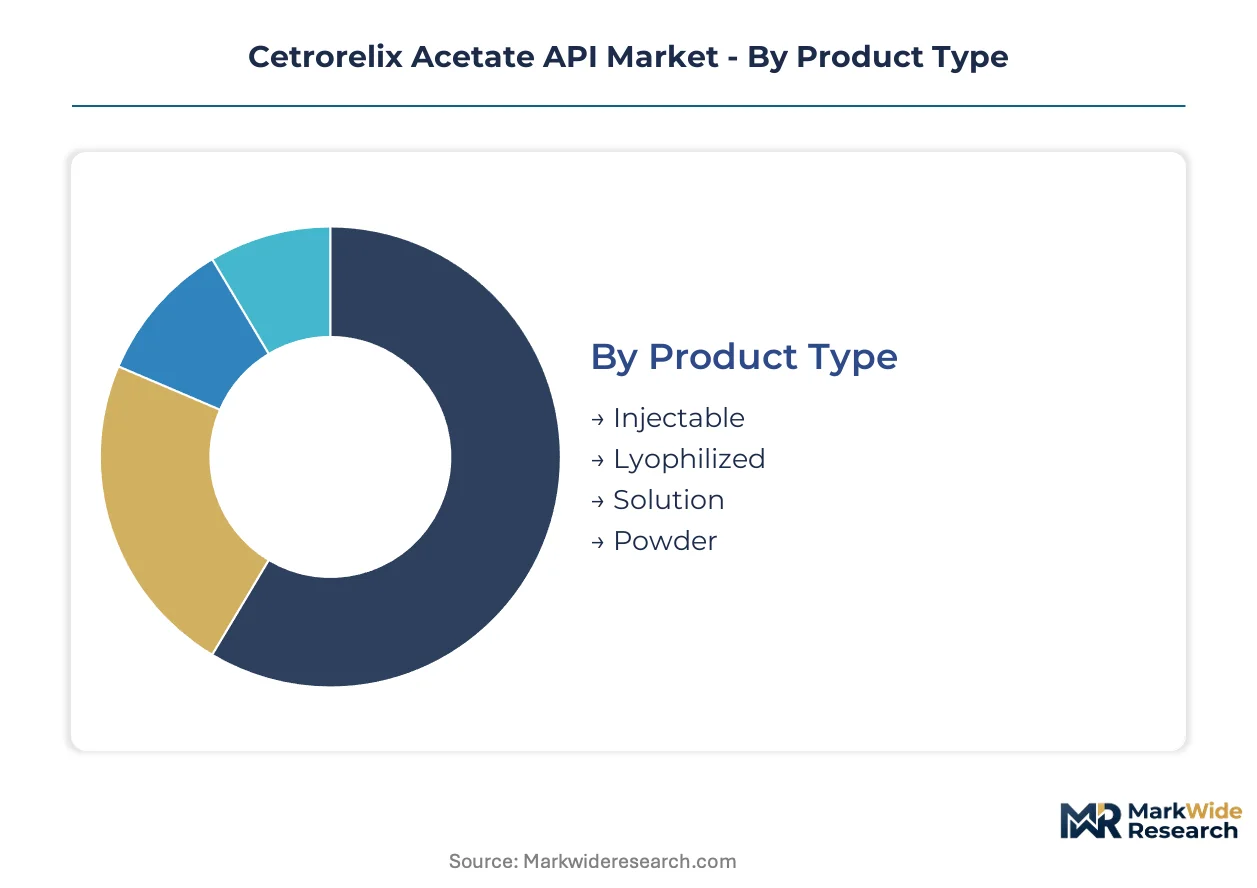
Cetrorelix Acetate API demand fragments across formulation formats, therapeutic protocols, and procurement channels. Each segment carries distinct specification burdens, cold-chain requirements, and margin profiles that reshape supplier competitive positioning.
Product Type:
Standardization dominates injectable and solution formats, while lyophilized presentations demand customized stability validation and modified release testing protocols.
- Injectable:Liquid parenteral formulations in vials or pre-filled syringes require continuous cold-chain maintenance from GMP suites through fertility clinic storage. German university hospital networks and US specialty pharmacy chains anchor procurement volumes for this segment, though refrigeration dependency limits distribution reach into India's tier-two cities.
- Lyophilized:Freeze-dried powder presentations eliminate refrigeration requirements through enhanced chemical stability, enabling ambulatory fertility center dispensing and direct-to-patient shipment models. India's expanding clinic networks and Middle Eastern hospital groups are driving fastest adoption here.
- Solution:Ready-to-use liquid concentrates suit high-volume IVF centers with on-site compounding capabilities.
- Powder:Bulk API powder serves contract formulation manufacturers and institutional repackaging operations.
Most installed capacity flows through Injectable formats. Expansion is steepest in Lyophilized.
Application:
Volume concentration sits with fertility protocols, while margin architecture favors oncology applications with their stringent endotoxin limits and smaller batch economics.
- Fertility Treatments:Controlled ovarian stimulation in IVF cycles represents the dominant consumption pathway, with GnRH antagonist protocols replacing agonist regimens across German, Indian, and US clinic networks. CDSCO-registered Indian manufacturers and EMA-compliant European suppliers compete for multi-kilogram tenders from consolidating hospital group purchasing organizations.
- Cancer Therapy:Prostate and breast cancer hormone suppression protocols command premium pricing per gram due to pharmacopeial-grade purity requirements and dedicated GMP suite allocation. Swiss and Swedish manufacturers anchor supply here, with batch sizes typically one-tenth of fertility volumes.
- Hormonal Interventions:Precocious puberty and gender-affirming care protocols generate steady mid-tier demand.
- Endometriosis Management:Off-label and investigational uses create sporadic procurement patterns with limited contract predictability.
Revenue concentration pools in Fertility Treatments. Margin expansion concentrates in Cancer Therapy.
End User:
Procurement scale and specification stringency diverge sharply between institutional buyers and retail-access channels.
- Hospitals:Academic medical centers and fertility institutes in Germany, India, and the United States drive bulk API contracting through centralized pharmacy committees. EMA MDR transition and FDA peptide CMC documentation requirements now dominate supplier qualification timelines.
- Clinics:Ambulatory fertility centers are consolidating purchasing through group procurement organizations, squeezing distributor margins while demanding lyophilized formats.
- Pharmacies:Specialty and compounding pharmacies handle patient-specific dosing with variable batch sizes.
- Research Laboratories:Preclinical and clinical trial material supply generates small-volume, high-documentation orders.
Contract value aggregates at Hospitals. Volume growth is accelerating fastest through Clinics.
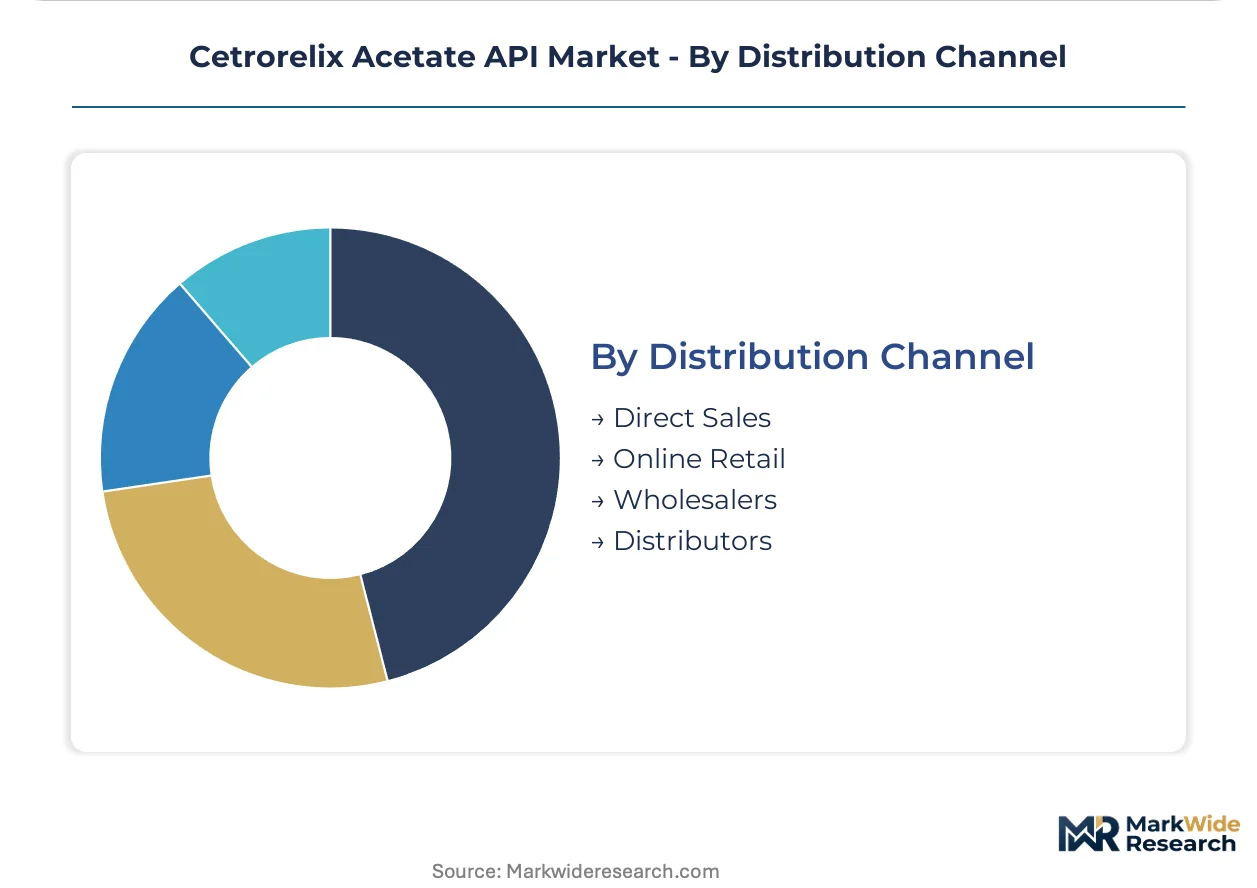
Distribution Channel:
Channel selection tracks buyer scale and regulatory jurisdiction complexity, with direct relationships displacing intermediaries among large-volume purchasers.
- Direct Sales:Manufacturer-to-institution relationships dominate multi-kilogram procurement from GPO-affiliated hospital networks and transnational fertility clinic chains. Long-term offtake agreements with 24-36 month horizons are displacing spot purchasing.
- Wholesalers:Regional pharmaceutical distributors maintain relevance in fragmented European markets and India's state-level hospital procurement systems.
- Distributors:Specialty peptide and API-focused intermediaries serve mid-tier manufacturers lacking direct regulatory filing capabilities.
- Online Retail:Limited to reference standard and analytical-grade materials for research applications.
Transaction volume concentrates through Direct Sales. Channel diversification is most pronounced among Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solid-phase peptide synthesis expertise clusters in Basel and Stockholm anchor European supply capacity, while Indian contract manufacturers scale GMP peptide suites to capture export demand from North American and European fertility clinic networks.
United States
Fertility clinic consolidation through group procurement organizations concentrates multi-kilogram API tendering among large hospital networks in California and New York. FDA peptide CMC guidance elevates documentation burdens for European and Asian suppliers seeking IND-enabling partnerships. The Greater Boston biotech corridor houses analytical method development specialists serving combination product sponsors navigating drug-device filing complexity.
Germany
University hospital fertility centers in Bavaria and North Rhine-Westphalia drive controlled ovarian stimulation protocol standardization across European clinic networks. EMA MDR transition timelines force synchronization of API quality documentation with device quality management system audits. The Rhine-Main pharmaceutical cluster hosts regulatory affairs functions managing parallel EMA-notified body interactions for injectable fertility products.
Switzerland
Captive supply of protected amino acids and large-scale SPPS reactor infrastructure sustains cost predictability for peptide antagonist manufacturing amid raw material volatility. Swissmedic oversight of GMP peptide suites maintains alignment with EMA impurity profiling mandates. The Basel pharmaceutical corridor concentrates aging solid-phase chemistry expertise that contract manufacturers compete to access through targeted recruitment.
India
CDSCO Schedule M compliance and BIS certification filter subscale manufacturers from export-oriented peptide synthesis tenders. Maharashtra and Gujarat-based contract manufacturers expand dedicated GMP peptide capacity to supply European and North American fertility clinic networks. Telangana's pharmaceutical corridor attracts analytical method development partnerships seeking ISO 17025-accredited testing for regulatory filing acceleration.
Sweden
Dedicated GMP peptide suites in the Stockholm-Uppsala biotech corridor serve oncology applications with stringent endotoxin specifications distinct from fertility market economics. REACH-aligned chemical handling protocols govern protected amino acid storage and synthesis waste management. The Nordic pharmaceutical cluster competes for solid-phase chemistry talent against Swiss and German employers through specialized training partnerships with technical universities.
Cetrorelix Acetate API Market Competitive Landscape
The competitive structure tilts toward vertically integrated European specialists with captive raw material sourcing and dedicated GMP peptide infrastructure. Swiss and Swedish manufacturers anchor premium-tier supply for oncology applications, while Indian contract manufacturers capture volume-driven fertility market procurement. Three archetypes dominate: integrated peptide specialists with backward amino acid supply control, regional contract manufacturers scaling GMP capacity for export qualification, and diversified pharmaceutical conglomerates leveraging analytical partnerships for regulatory filing acceleration. Capacity expansion and long-term offtake agreements with consolidating clinic networks represent the dominant competitive moves reshaping supplier-buyer relationships.
Among Swiss-integrated specialists, Bachem AG exemplifies the captive-supply archetype through its Basel manufacturing base and protected amino acid sourcing infrastructure. Polypeptide Group occupies a position within the dedicated GMP peptide tier, with its Swedish and United States facilities serving distinct regulatory jurisdictions. Merck KGaA represents the diversified conglomerate model, anchoring competitive positioning through analytical method development partnerships that accelerate client regulatory submissions across EMA and FDA pathways.
| Leading Market Players |
|---|
| Bachem AG |
| Polypeptide Group |
| Merck KGaA |
| Teva Pharmaceutical Industries Ltd. |
| Hemmo Pharmaceuticals |
| AmbioPharm Inc. |
| Hybio Pharmaceutical Co., Ltd. |
| CPC Scientific, Inc. |
| Biophore India Pharmaceuticals Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
Protected amino acid costs flow from European and Japanese chemical suppliers through three-tier pricing structures that stratify across pharmacopeial-grade purity, GMP certification status, and volume commitment tiers. Fertility clinic group procurement organizations in Germany and the United States compress margins on multi-kilogram contracts while oncology applications sustain premium positioning through stringent endotoxin specifications.
Pricing Analysis
Contract-based long-term offtake agreements now dominate multi-kilogram procurement, displacing spot purchasing as fertility clinic networks consolidate. Price differentiation hinges on pharmacopeial-grade purity certification and ISO 17025-accredited analytical testing inclusion. Cost compression in standard-grade fertility API intensifies because Indian contract manufacturers scale GMP peptide capacity for export qualification. Hospital group purchasing organizations in Germany and the United States exhibit highest price sensitivity, while cancer therapy protocols show least sensitivity due to smaller batch economics and dedicated GMP suite allocation.
Supply Chain Analysis
Regional distribution centers in Basel, Stockholm, and Mumbai anchor hub-and-spoke patterns for temperature-sensitive peptide shipments. Manufacturing concentrates in Switzerland, Sweden, and India, with captive supply of protected amino acids resting on a limited set of European and Japanese chemical suppliers. Solid-phase peptide synthesis capacity scarcity in large-scale reactors creates single-source vulnerability for rapid volume scaling. Distribution runs through direct manufacturer-to-institution relationships for multi-kilogram tenders, supplemented by specialty peptide distributors serving mid-tier buyers lacking regulatory filing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EMA's tightened impurity profiling mandates and FDA peptide CMC guidance shift procurement toward premium-certified suppliers with validated analytical methods.
For Market Incumbents: Deepen captive supply control over protected amino acids through backward integration into Japanese and European chemical supplier relationships. Expand dedicated GMP peptide suite capacity in India to capture CDSCO-compliant export demand before subscale competitors achieve BIS certification. EMA's 18-24 month facility upgrade timelines compress effective capacity during transition periods, rewarding early movers with locked-in long-term offtake agreements from consolidating clinic networks. For New Entrants and Emerging Players: Specialty peptide distributors with ISO 17025-accredited testing partnerships offer the most penetrable channel for market access without direct regulatory filing infrastructure. Target lyophilized format production for India's tier-two fertility clinic networks and Middle Eastern hospital groups seeking cold-chain-independent presentations. A go-to-market angle anchored on continuous flow peptide synthesis technology enables modular capital deployment and real-time process analytical technology integration that bypasses large-batch reactor bottlenecks. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR transition timelines and FDA peptide CMC documentation requirements exceed subscale manufacturer compliance capacity. The 5-10 year viability window favors acquisition targets with existing BIS certification and CDSCO-registered GMP peptide suites in Maharashtra or Gujarat. The signal to watch is pharmacopeial harmonization progress between USP-NF and EP monographs, as divergence in assay acceptance criteria directly impacts batch release economics and inventory allocation strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks in multi-kilogram volume commitments from German hospital group purchasing organizations. |
| Backward Integration | Secures captive supply of protected amino acids from Basel and Tokyo chemical suppliers. |
| Manufacturing Scale-Up | Expands dedicated GMP peptide suite capacity in India for CDSCO-compliant export qualification. |
| Regulatory Approval Pathway | Accelerates EMA and FDA filings through ISO 17025-accredited analytical method partnerships. |
| Pipeline Diversification | Extends GnRH antagonist applications into oncology protocols with premium endotoxin specifications. |
Research Methodology
Coverage spans Germany, Switzerland, India, Sweden, and the United States, with primary inputs from each market cluster combining interviews with solid-phase chemistry specialists, regulatory affairs leads at peptide manufacturers, fertility clinic procurement directors, and hospital pharmacy committee members. Secondary validation draws from EMA impurity guideline documents, FDA peptide CMC guidance, CDSCO Schedule M compliance directives, USP-NF and EP monograph databases, and customs trade data on protected amino acid flows. Bottom-up volume modeling triangulates against top-down market sizing across formulation formats and therapeutic applications.
Granularity-level modeling disaggregates demand by injectable, lyophilized, solution, and powder formats; fertility treatment, cancer therapy, hormonal intervention, and endometriosis management applications; and hospital, clinic, pharmacy, and research laboratory end users. CAGRs derive from segment-level volume trajectories and price elasticity assumptions across the projection horizon. Industry-specific forecast inputs include IVF cycle volume growth in target geographies and EMA MDR transition compliance cost estimates for combination product filings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial harmonization delays, raw material supply disruptions from Japanese chemical suppliers, and regulatory divergence between FDA and EMA peptide impurity specifications. Outputs reflect documented assumptions around clinic network consolidation pace and continuous flow synthesis technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Calcium Citrate Market