
 Proline Market | 2026-2036
Proline Market Size, Share, and Industry Trends Forecast 2026-2036
Proline Market Outlook
Aftermarket service revenue for proline quality certification and custom synthesis documentation is tilting toward specialized amino acid houses. Ajinomoto Co., Inc. leverages its decades-long fermentation expertise to dominate food-grade proline supply chains across East Asia. Evonik sustains pharmaceutical-grade leadership through in-house production of high-purity L-proline for peptide drug applications. KYOWA HAKKO BIO CO., LTD. anchors nutraceutical-grade positioning with proprietary enzymatic conversion technologies.
Proline is a cyclic, non-essential amino acid characterized by its unique pyrrolidine side ring and imino group configuration, typically synthesized via microbial fermentation or chemical hydrolysis of collagen with purity thresholds reaching 99.5% for injectable-grade applications. Its primary industrial purpose centers on protein structure stabilization in biopharmaceutical formulations, osmoprotection in cell culture media, and flavor enhancement in processed foods. Pharmaceutical-grade proline commands premium positioning due to stringent endotoxin and heavy-metal specifications required for therapeutic peptide manufacturing. Food-grade proline occupies mature, volume-driven channels where cost efficiency determines supplier selection. Nutraceutical-grade proline in capsule and powder forms represents the fastest-expanding margin pool as sports nutrition and cognitive health brands reformulate with conditionally essential amino acid blends.
FDA purity guidelines for injectable amino acids and EMA's ICH Q3D elemental impurity standards shape pharmaceutical-grade proline qualification timelines and testing costs for manufacturers seeking dual-territory approval. China's NMPA enforces GB standards for fermentation-derived amino acids while SAMR monitors food additive safety classifications, creating layered compliance obligations for suppliers serving both drug and nutrition markets. India's CDSCO and BIS frameworks add further certification complexity for imports targeting generic peptide API production. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs to anticipate qualification cost shifts and regional supply reallocations.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing supplier margins while concentrating procurement among fermentation specialists capable of endotoxin-compliant production. The divergence between food-grade commoditization and injectable-grade premiumization is forcing dual-capability manufacturers to segment operations by certification tier.
Growth Catalysts
- Peptide Therapeutics Expansion:GLP-1 analog and ADC manufacturing protocols require L-proline as a chiral building block. Contract development organizations in Massachusetts and Basel are qualifying amino acid suppliers against ICH Q3D elemental impurity standards.
- China's NMPA Purity Mandates:Tightened GB standards for fermentation-derived amino acids are disqualifying legacy hydrolysis producers. Jiangsu province contract manufacturers are upgrading to chromatographic purification to retain pharmaceutical intermediate licenses.
- Cell Culture Osmoprotection Demand:CHO and HEK293 bioreactor titers above 5 g/L require proline-supplemented media formulations. Serum-free and chemically defined media adoption is accelerating amino acid premix specification.
Market Restraints
- Collagen Hydrolysate Input Volatility:Porcine and bovine gelatin supply fluctuations from rendering plant consolidation create feedstock cost instability for chemical synthesis routes.
- Fermentation Capacity Concentration:Industrial-scale L-proline bioreactors cluster in East Asian fermentation hubs. Single-source dependency for pharmaceutical-grade volumes exposes buyers to force majeure disruption.
- Endotoxin Testing Burden:LAL and rFC assay requirements for injectable-grade certification add 12-18 week qualification timelines. Smaller API manufacturers lack in-house QC infrastructure to absorb these costs.
Strategic Opportunities
- Indian Generic Peptide API Manufacturing:CDSCO's streamlined peptide drug approval pathway is attracting investment in Mumbai and Hyderabad CMOs. Local proline qualification against BIS and USP monographs reduces import dependency.
- Precision Fermentation Scale-Up:Microbial strain engineering and continuous bioprocessing convergence promises 40% yield improvement over batch fermentation. Synthetic biology platforms are redesigning Corynebacterium glutamicum metabolic pathways.
- Sports Nutrition Conditioned Positioning:Collagen synthesis and joint health claims are driving proline inclusion in pre-workout and recovery formulations. Direct-to-consumer powder brands are bypassing traditional ingredient distributors.
Industry Challenges
- Dual Pharmacopeial Harmonization Lag:Divergent USP, EP, and ChP monograph specifications for proline assay and impurity profiles force redundant method validation. Manufacturers seeking multi-territory approval face 18-24 month documentation cycles.
- Specialized Fermentation Talent Scarcity:Industrial microbiologists with amino acid strain optimization expertise command premium compensation. University pipeline gaps in metabolic engineering constrain facility expansion timelines.
- Legacy Hydrolysis Asset Stranding:Collagen-derived proline producers face stranded equipment risk as pharmaceutical buyers shift to fermentation-sourced material. Acid hydrolysis reactors lack retrofit path to GMP compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proline Market |
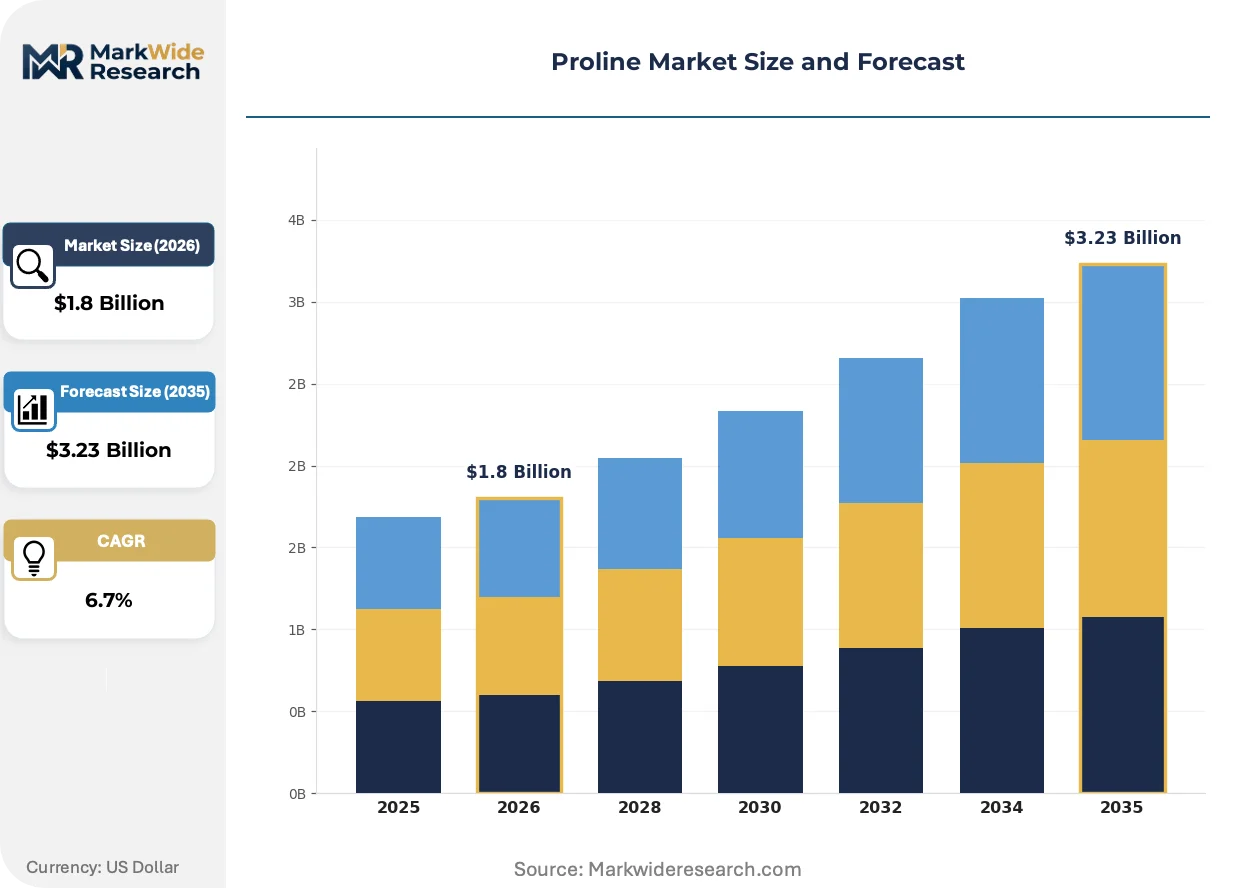
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Nutraceutical Grade End User: Food Industry, Pharmaceutical Companies, Cosmetics, Dietary Supplements Form: Powder, Granules, Liquid, Capsules Application: Food Additives, Nutritional Supplements, Therapeutics, Personal Care Products |
| Companies Covered | Ajinomoto Co., Inc., KYOWA HAKKO BIO CO., LTD., Evonik, PepTech Corporation, Anaspec, Inc., Iris Biotech GmbH, ChemPep Inc., Shijiazhuang Baokang Biotechnology Co., Ltd., Wuhan Vanz Pharm Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proline Market Strategic Shifts
Digital process control and real-time release testing are compressing batch cycle times while regulatory data integrity requirements reshape documentation workflows. Synthetic biology and continuous manufacturing convergence is redrawing competitive boundaries between chemical and biological production routes.
Continuous chromatography and in-line PAT sensors are digitizing proline purification workflows. Biopharmaceutical contract manufacturers in Switzerland and Singapore are adopting these platforms to reduce hold times between fermentation harvest and final packaging. Real-time endotoxin monitoring is eliminating quarantine inventory positions and accelerating customer qualification cycles.
EMA's revised Annex 1 sterile manufacturing guidelines and FDA's data integrity ALCOA+ expectations are mandating electronic batch records for amino acid excipient suppliers. European peptide API manufacturers are auditing upstream proline producers against these standards. Documentation automation investments are becoming table stakes for pharmaceutical-grade supply relationships.
Biopharmaceutical procurement teams are consolidating amino acid purchasing through platform distributors with integrated quality documentation. Large molecule CDMOs in Boston and Basel are reducing direct supplier relationships from 12-15 to 3-4 qualified partners. This concentration is compressing price discovery transparency and elevating contract manufacturers with embedded amino acid testing capabilities.
Proline Market Segmentation
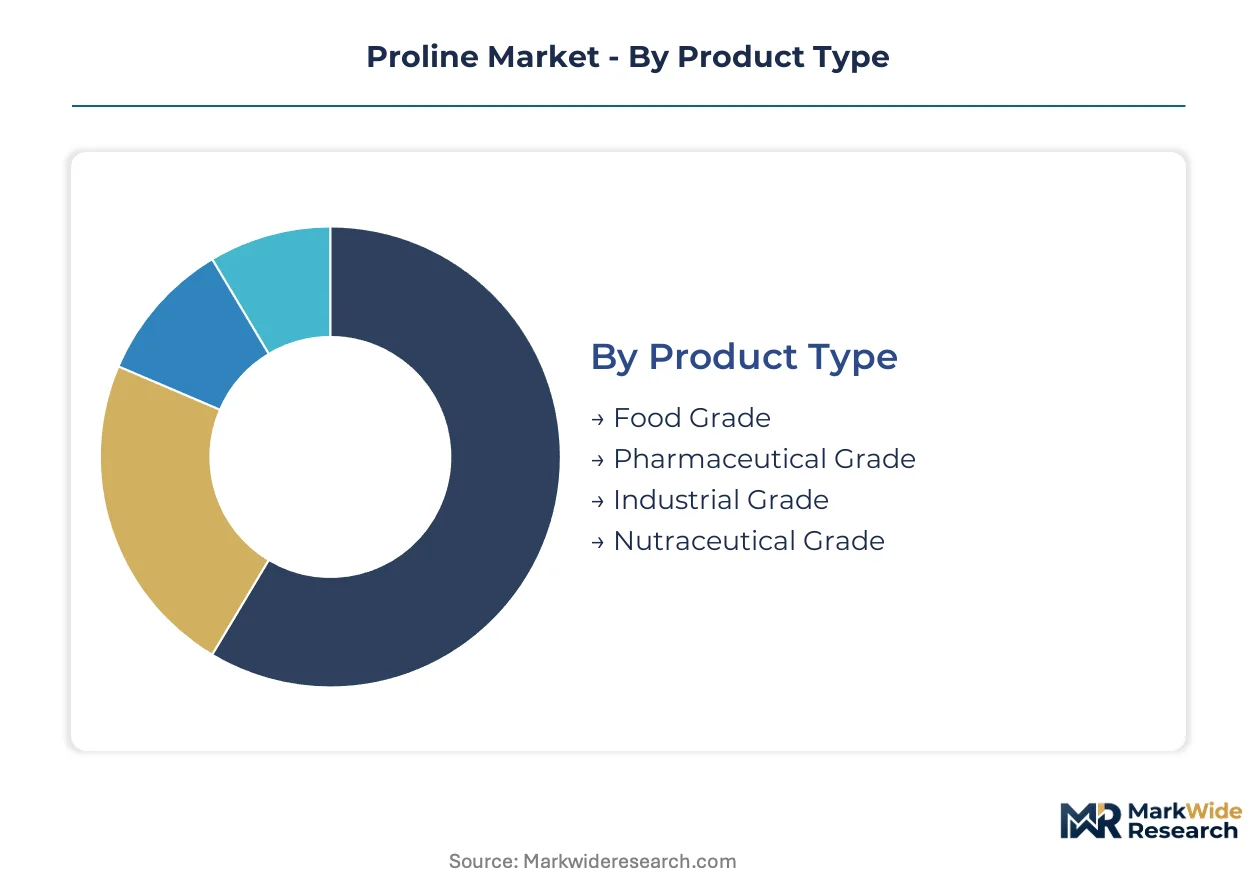
Proline market segmentation reveals how purity thresholds and end-use specifications fragment supply chains. Each dimension—grade, application, form, and customer type—carries distinct regulatory burdens and margin profiles that reshape procurement patterns.
Product Type:
Grade differentiation determines fermentation complexity, testing protocols, and pricing power across the supply base.
- Food Grade:Minimum 98% purity with flavor-enhancement and protein stabilization functions in processed foods. Demand concentrates in East Asian seasoning manufacturers where cost efficiency dominates supplier selection and fermentation scale determines contract awards.
- Pharmaceutical Grade:Injectable specifications demand 99.5% purity with endotoxin limits below 10 EU/g and full ICH Q3D elemental impurity documentation. Peptide API manufacturers in Basel and Boston are qualifying suppliers against USP and EP monographs simultaneously.
- Industrial Grade:Technical specifications for chemical synthesis and polymer applications with relaxed purity tolerances. Specialty chemical producers in Germany and Japan absorb volumes for chiral intermediate manufacturing.
- Nutraceutical Grade:Capsule and powder formats for sports nutrition with microbial and heavy-metal testing. Direct-to-consumer brands in North America are bypassing traditional distributors for conditioned positioning claims.
Pharmaceutical Grade holds installed capacity. Nutraceutical Grade is rotating up the share rankings.
End User:
Customer sophistication varies from commodity procurement to integrated quality documentation requirements.
- Food Industry:Seasoning and processed meat manufacturers purchasing bulk powder through annual contracts. Jiangsu province fermentation hubs supply regional flavor houses with documented halal and kosher certifications.
- Pharmaceutical Companies:Peptide drug developers requiring amino acid excipient qualification with regulatory filing support. CDMOs in Massachusetts and Switzerland are consolidating supplier bases to 3-4 qualified partners.
- Cosmetics:Collagen-boosting claims in anti-aging formulations drive low-volume, high-margin powder demand. South Korean and French formulators specify cosmetic-grade certificates of analysis.
- Dietary Supplements:Sports nutrition and cognitive health brands blending proline into conditionally essential amino acid stacks. Powder premix suppliers in Utah and Florida are capturing contract manufacturing volumes.
Pharmaceutical Companies anchor premium pricing. Dietary Supplements is gaining share fastest.
Form:
Physical presentation shapes packaging, stability testing, and handling infrastructure investments.
- Powder:Dominant format for food and nutraceutical applications with 24-month shelf life under controlled humidity. Bulk handling systems at contract manufacturers in India and China prefer free-flowing crystalline grades.
- Granules:Improved flow properties for high-speed capsule filling operations. European supplement manufacturers specify granulated proline to reduce dust exposure and compression variability.
- Liquid:Concentrated solutions for cell culture media and bioreactor supplementation. Serum-free media formulators in Singapore and California require sterile-filtered, endotoxin-tested liquid formats.
- Capsules:Finished dosage forms for direct-to-consumer sports nutrition brands. Private label manufacturers in Arizona and Florida control encapsulation and bottling workflows.
Powder commands volume leadership. Liquid is climbing the fastest.
Application:
Use-case specificity determines regulatory pathway, documentation depth, and customer stickiness.
- Food Additives:Flavor modulation and protein structure enhancement in processed meats and savory seasonings. China's SAMR monitors GB standard compliance for fermentation-derived amino acids in food channels.
- Nutritional Supplements:Collagen synthesis support and joint health positioning in sports and wellness products. Direct-to-consumer brands are reformulating with conditionally essential amino acid blends.
- Therapeutics:Chiral building block for GLP-1 analogs, ADCs, and synthetic peptide drugs. FDA and EMA pharmacopeial harmonization gaps force redundant method validation for multi-territory filings.
- Personal Care Products:Moisture retention and anti-aging claims in topical formulations. Korean beauty manufacturers specify amino acid complexes with documented dermal safety profiles.
Food Additives holds mature volume. Therapeutics shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical buyers in Switzerland and Massachusetts exhibit minimal price elasticity for endotoxin-compliant material, while food-grade procurement in East Asia operates on thin margin compression. This demand-elasticity contrast shapes regional supply chain configurations and certification investment patterns.
China
NMPA tightened GB standards for fermentation-derived amino acids, disqualifying legacy hydrolysis producers from pharmaceutical intermediate licenses. Jiangsu province contract manufacturers now deploy chromatographic purification to retain qualification. Nantong and Taizhou fermentation hubs cluster around peptide API contract manufacturing zones.
United States
FDA pharmacopeial harmonization gaps with EP force redundant method validation for multi-territory peptide filings. Massachusetts CDMOs consolidate amino acid supplier bases from 12-15 to 3-4 qualified partners. Greater Boston biotech corridors drive demand for real-time endotoxin monitoring capabilities.
Switzerland
EMA's revised Annex 1 sterile manufacturing guidelines mandate electronic batch records for excipient suppliers. Basel peptide API manufacturers audit upstream proline producers against ALCOA+ data integrity standards. Swissmedic oversight accelerates documentation automation investments.
India
CDSCO streamlined peptide drug approval pathways attract investment in Mumbai and Hyderabad CMOs. BIS and USP dual monograph qualification reduces import dependency for generic peptide API production. Maharashtra fermentation capacity expands to capture contract manufacturing migration.
Germany
ECHA REACH compliance and ICH Q3D elemental impurity standards shape pharmaceutical-grade procurement specifications. Specialty chemical producers in North Rhine-Westphalia absorb industrial-grade volumes for chiral intermediate manufacturing. Evonik anchors high-purity L-proline supply for peptide drug applications.
Proline Market Competitive Environment
Fermentation specialists and chemical synthesis houses split the market along purity-grade fault lines. Consolidation pressures concentrate pharmaceutical-grade supply among endotoxin-capable bioreactor operators while food-grade channels fragment across cost-driven fermentation scale players. Three archetypes dominate: integrated amino acid houses with decades-long fermentation expertise, precision synthesis specialists serving peptide API developers, and regional fermentation scale players capturing commoditized volume. Dominant competitive moves include backward integration into strain engineering capabilities and geographic expansion through distributor partnerships with embedded quality documentation.
Within the integrated fermentation archetype, Ajinomoto Co., Inc. and KYOWA HAKKO BIO CO., LTD. represent established positions built on microbial production scale. Evonik occupies a distinct tier through in-house pharmaceutical-grade purification infrastructure. Among Chinese fermentation specialists, Shijiazhuang Baokang Biotechnology Co., Ltd. exemplifies regional scale players upgrading to meet tightened NMPA purity mandates. These three anchors illustrate how certification tier and geographic origin stratify competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| KYOWA HAKKO BIO CO., LTD. |
| Evonik |
| PepTech Corporation |
| Anaspec, Inc. |
| Iris Biotech GmbH |
| ChemPep Inc. |
| Shijiazhuang Baokang Biotechnology Co., Ltd. |
| Wuhan Vanz Pharm Inc. |
| Others |
Value Chain & Pricing Dynamics
Jiangsu province fermentation capacity concentration anchors margin capture downstream, where pharmaceutical-grade qualification costs flow to peptide API buyers while food-grade buyers in East Asia compress supplier returns through volume aggregation.
Pricing Analysis
Aftermarket service revenue from quality certification documentation and custom synthesis support drives lifetime value for specialized amino acid houses. Pharmaceutical-grade proline commands premium-mid-economy pricing differentiation against food-grade commoditization, with endotoxin-compliant fermentation batches priced substantially above hydrolysis-sourced material. Pricing pressure stems from CDSCO's streamlined peptide approvals attracting Indian generic API manufacturers to local qualification. Pharmaceutical buyers in Basel and Massachusetts exhibit minimal price sensitivity, while East Asian seasoning manufacturers drive cost compression through annual contract aggregation.
Supply Chain Analysis
Contract manufacturing concentration at Jiangsu province peptide API zones and Massachusetts CDMO corridors shapes upstream amino acid procurement patterns. Supply draws from Chinese fermentation hubs, German specialty chemical producers, and Indian expanding bioreactor capacity. Raw material dependencies include glucose feedstock for microbial fermentation, chromatographic resins for purification, and porcine-derived collagen for legacy hydrolysis routes. Single-source vulnerability for pharmaceutical-grade endotoxin-compliant volumes exposes buyers to force majeure disruption. Distribution runs through platform distributors with embedded quality documentation serving consolidated CDMO supplier bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The proline market is in cyclical recovery as peptide therapeutics expansion drives demand for chiral building blocks after a period of generic API margin compression.
For Market Incumbents: Entrench pharmaceutical-grade positioning through backward integration into strain engineering capabilities and chromatographic purification infrastructure. Expand fermentation capacity in Maharashtra to capture CDSCO-driven contract manufacturing migration from legacy Chinese suppliers. Defend against precision fermentation startups by accelerating real-time release testing adoption and electronic batch record automation ahead of EMA Annex 1 compliance deadlines.
For New Entrants and Emerging Players: Indian nutraceutical-grade powder supply remains geographically underpenetrated by specialized amino acid houses with USP-BIS dual qualification. Target direct-to-consumer sports nutrition brands in North America bypassing traditional ingredient distributors for conditioned positioning claims. Enter through private-label encapsulation partnerships with Arizona and Florida contract manufacturers lacking in-house fermentation infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation specialists holding stranded hydrolysis equipment facing NMPA disqualification. Five-to-ten year viability hinges on successful retrofit to GMP-compliant bioreactor operations or specialty chemical pivot. Monitor CDSCO peptide approval velocity and Jiangsu province chromatographic upgrade completion rates as inflection indicators for regional supply reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial strain engineering promises yield improvement over batch fermentation for Corynebacterium glutamicum pathways. |
| Pharmacopeial Harmonization Investment | Dual USP-EP qualification reduces redundant method validation cycles for multi-territory peptide filings. |
| Real-Time Release Testing Adoption | In-line PAT sensors and continuous chromatography compress batch cycle times for Swiss and Singapore biopharmaceutical manufacturers. |
| Indian CDMO Capacity Expansion | Maharashtra and Hyderabad fermentation buildout captures CDSCO-streamlined generic peptide API manufacturing migration. |
| Direct-to-Consumer Channel Bypass | Utah and Florida powder premix suppliers capture sports nutrition contract manufacturing volumes from traditional distributors. |
Study Parameters
Operator-level perspectives from fermentation plant managers, peptide API procurement leads at CDMOs, regulatory affairs directors navigating pharmacopeial harmonization, and quality control heads managing endotoxin testing protocols anchored the qualitative base. Primary fieldwork combined with secondary validation from FDA pharmacopeial filings, EMA Annex 1 guideline revisions, NMPA GB standard updates, and CDSCO approval pathway documentation. Customs data on amino acid intermediate trade flows and SEC disclosures from listed fermentation specialists provided quantitative triangulation against bottom-up capacity modeling.
Scenario-bracketing around precision fermentation yield improvements and NMPA enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include grade tier, end-use application, physical form, and regional regulatory cluster. CAGRs derived from capacity expansion announcements, qualification timeline compression, and substitution elasticity between fermentation and hydrolysis routes. Industry-specific inputs incorporated CHO and HEK293 bioreactor titer trajectories and GLP-1 analog manufacturing scale-up schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by synthetic biology platforms or sudden NMPA enforcement escalation would shift outcomes beyond modeled ranges. Quarterly review of CDSCO peptide approval velocity, Jiangsu province chromatographic upgrade completion rates, and real-time endotoxin monitoring technology adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Asia Pacific Rotomoulding Powder Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Asia-Pacific Silica Sol Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Industrial Phosphate Market