
 E-Fluids Market | 2026-2036
E-Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
E-Fluids Market Foresight
China is rewriting the competitive map for e-fluids through aggressive capacity additions in Jiangsu and Zhejiang provinces dedicated to synthetic dielectric fluid production. ExxonMobil leverages its integrated base oil infrastructure to supply battery OEMs directly from Singapore refineries. Shell anchors its position through partnerships with European electric vehicle platforms requiring low-viscosity thermal management formulations. Castrol specializes in aerospace-grade e-fluid variants that tolerate extreme thermal cycling in electric aircraft prototypes.
E-fluids comprise engineered liquid formulations designed to manage heat, transmit force, or provide electrical insulation in electrified systems, typically featuring synthetic ester or polyalphaolefin bases with tailored dielectric constants above 2.5 and viscosity indices exceeding 140 for stable performance across wide temperature ranges. Their primary purpose centers on thermal regulation of lithium-ion battery packs, electric motor bearings, and power electronics where conventional petroleum fluids risk conductivity failures or oxidative breakdown. Dielectric fluids capture the dominant margin pool due to battery pack complexity and safety certification requirements, while nanofluids represent the fastest-expanding technology segment as dispersed metal oxide particles boost thermal conductivity without compromising electrical isolation. Bio-based fluids remain niche but gain traction among renewable energy end users seeking lifecycle carbon reductions in wind turbine and solar inverter cooling loops.
The EPA regulates fluid disposal and toxicity thresholds under TSCA, while the EU F-Gas Regulation mandates lower global warming potential in heat transfer chemistries, and China's MEE enforces dual carbon compliance disclosures that shape supplier qualification. These frameworks force reformulation cycles every three to five years, raising R&D barriers for non-integrated blenders. Stakeholders must track evolving thermal conductivity benchmarks set by battery OEMs as pack architectures shift from liquid-cooled plates to immersion designs requiring fundamentally different fluid chemistries.
Market Dynamics
Battery pack architectures are shifting from liquid-cooled plate designs to full immersion cooling systems, forcing fluid formulators to reformulate dielectric chemistries for direct contact with live electrical components.
Growth Catalysts
- EU F-Gas Regulation:Mandates on global warming potential in heat transfer chemistries are accelerating phase-out schedules for conventional fluorinated coolants across European automotive manufacturing.
- Immersion cooling adoption:Electric vehicle battery OEMs are specifying single-phase dielectric fluids capable of submerging entire cell modules without electrical breakdown.
- Jiangsu-Zhejiang corridor:China's concentrated synthetic base oil capacity additions are compressing regional supply costs for dielectric fluid production.
Market Restraints
- Synthetic ester feedstock volatility:Palm oil and neopentyl glycol price swings transmit directly into formulated fluid costs, squeezing blender margins.
- Base oil supply concentration:Polyalphaolefin production clusters in Singapore and the US Gulf Coast create geographic vulnerability for non-integrated formulators.
- Dielectric breakdown limitations:Existing fluid chemistries struggle to meet 80 kV/mm insulation thresholds required by 800V battery architectures.
Strategic Opportunities
- Electric aviation:Aerospace-grade thermal management specifications for electric aircraft prototypes command 3-4x fluid pricing premiums over automotive grades.
- Wind turbine gearboxes:Offshore wind operators in the North Sea are specifying bio-based e-fluids to meet lifecycle carbon disclosure requirements under EU CSRD.
- Direct OEM supply contracts:Battery manufacturers are bypassing traditional distribution to qualify fluid suppliers for co-development programs.
Industry Challenges
- Electrochemical compatibility testing:Each new cell chemistry requires 18-24 month validation cycles for thermal interface materials, delaying revenue recognition.
- Fire safety certification backlog:UL 9540A testing capacity constraints are extending time-to-market for immersion-cooled battery packs by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Fluids Market |
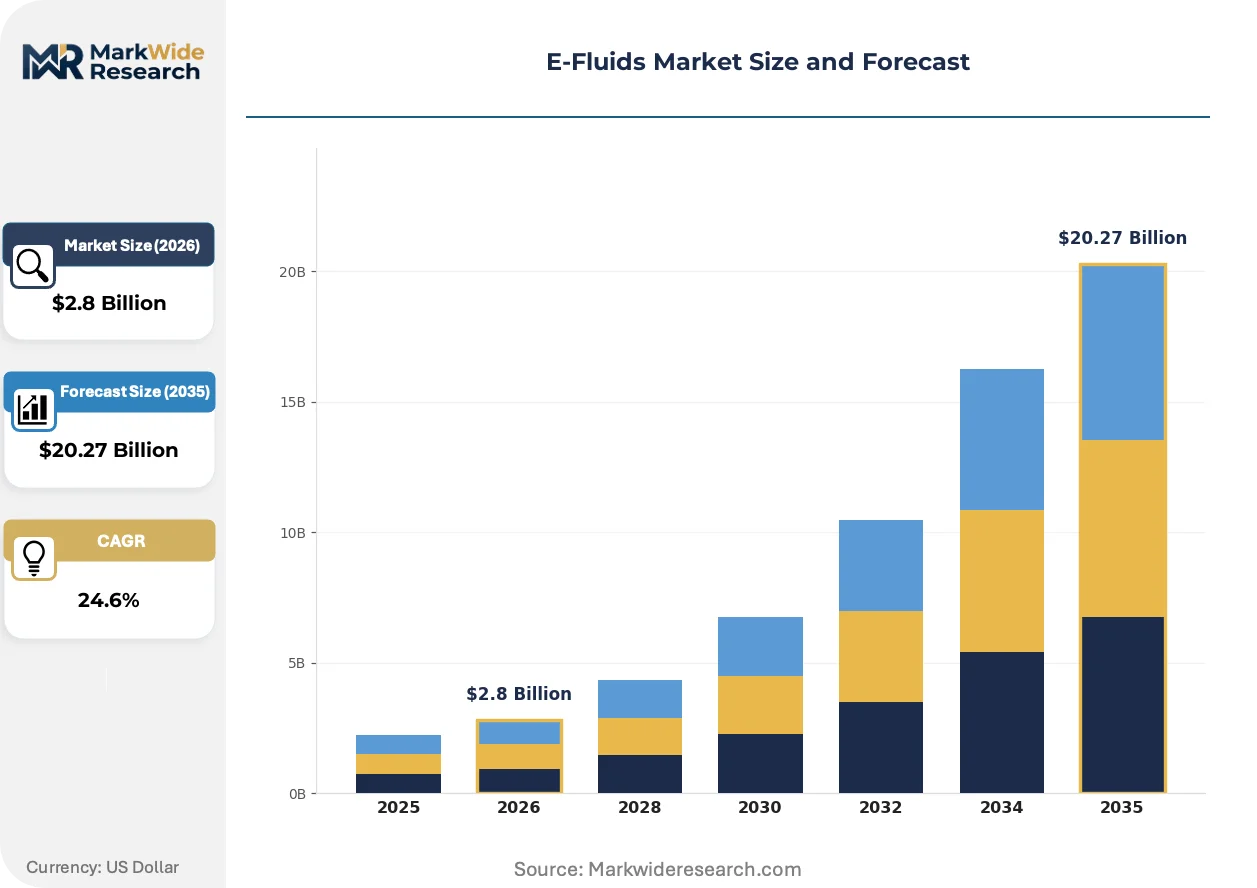
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dielectric Fluids, Heat Transfer Fluids, Hydraulic Fluids, Lubricants Application: Energy Storage, Electric Vehicles, Industrial Cooling, Aerospace End User: Manufacturing, Automotive, Renewable Energy, Transportation Technology: Nanofluids, Bio-Based Fluids, Synthetic Fluids, Conductive Fluids |
| Companies Covered | ExxonMobil, Shell, TotalEnergies, BP, FUCHS, Castrol, Afton Chemical, Motul, Panolin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Fluids Market Shifts & Advancements
Fluid formulation is pivoting from passive heat exchange toward active thermal management integration, with chemistry decisions now made concurrently with battery pack electrical architecture design rather than as aftermarket specifications.
Nanofluid technology is virtualizing thermal conductivity limits in dielectric applications. Dispersed aluminum oxide and boron nitride particles boost heat transfer coefficients by 15-40% without compromising electrical isolation. Battery OEMs in Germany and South Korea are qualifying these formulations for high-fast-charge duty cycles. The technology is virtualizing the traditional trade-off between thermal performance and dielectric strength that constrained prior fluid generations.
China's MEE enforcement of dual carbon compliance disclosures is reshaping supplier qualification protocols. Domestic battery manufacturers now require documented cradle-to-gate carbon footprints for all thermal management chemistries. This regulatory pressure is accelerating domestic substitution of imported synthetic base stocks with locally produced bio-derived alternatives. Formulators without verified lifecycle data are losing approved vendor status with tier-one battery producers.
Service unbundling is fragmenting traditional fluid supply relationships. Battery OEMs are separating thermal management system design from fluid procurement, creating openings for specialized chemical suppliers to displace integrated system vendors. This pattern is most visible in China's electric vehicle manufacturing corridor, where CATL and BYD have established independent fluid qualification teams. Direct technical engagement between formulators and pack engineers is replacing distributor-mediated specifications.
E-Fluids Market Segmentation
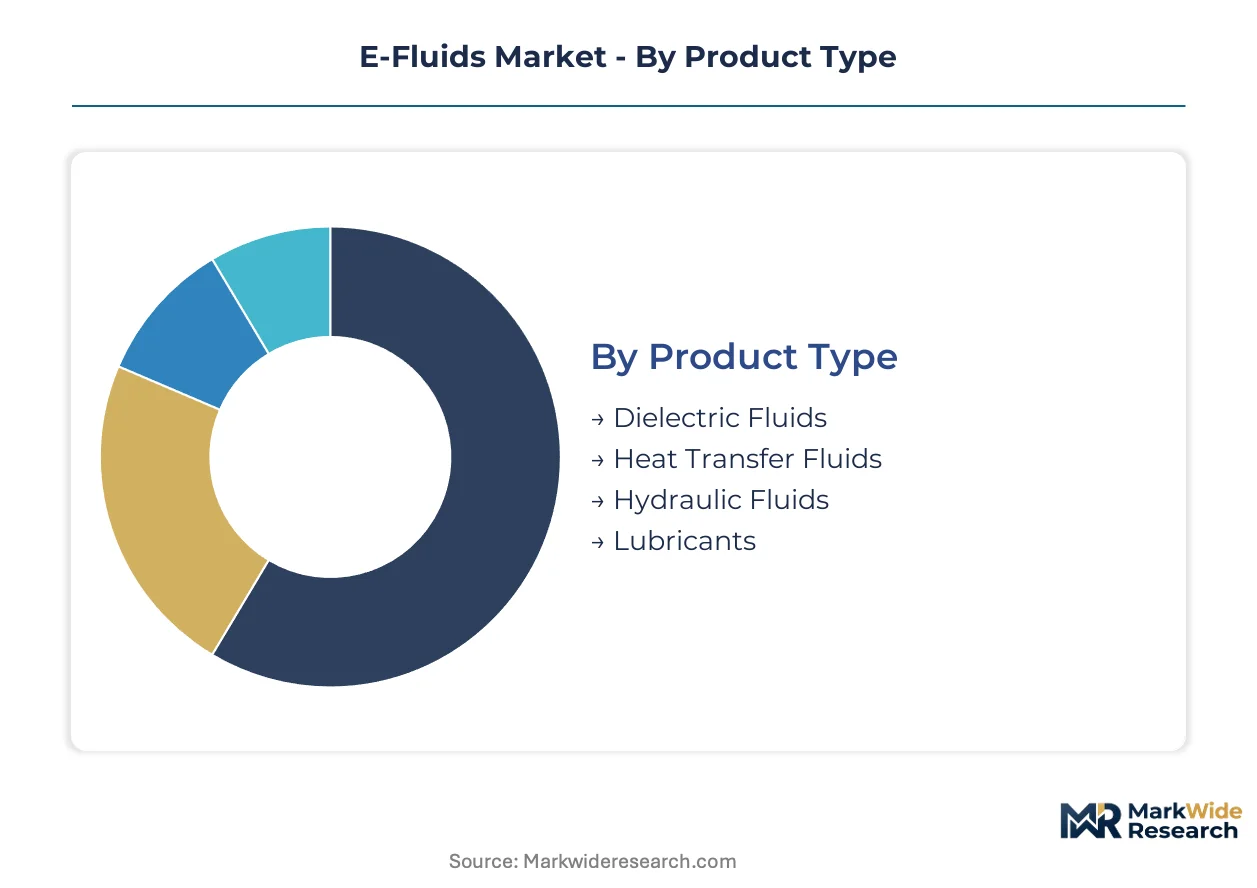
E-fluids require distinct formulation architectures for each electrified subsystem, from battery immersion cooling to motor bearing lubrication. Segmentation reveals where technical specifications diverge and where procurement patterns consolidate across thermal management, power transmission, and electrical insulation functions.
Product Type:
After-sales service intensity varies sharply across fluid categories, with immersion-cooled battery packs demanding scheduled dielectric fluid analysis and replacement protocols that lubricant applications rarely match.
- Dielectric Fluids:Synthetic ester and polyalphaolefin formulations engineered for electrical insulation above 2.5 dielectric constant. Demand concentrates in Germany's automotive corridor around Stuttgart and Munich, where battery OEMs specify single-phase immersion chemistries for 800V architectures. The EU F-Gas Regulation accelerates phase-out schedules for conventional fluorinated alternatives.
- Heat Transfer Fluids:Low-viscosity formulations with viscosity indices exceeding 140 for stable thermal performance across wide temperature ranges. China's Jiangsu-Zhejiang synthetic base oil corridor compresses regional supply costs for these formulations serving energy storage and industrial cooling loops.
- Hydraulic Fluids:Force-transmission formulations for electric actuator systems in industrial automation and aerospace landing gear.
- Lubricants:Electric motor bearing and gearbox formulations addressing electrical discharge damage risks in high-frequency inverter environments.
Dielectric fluids hold the largest share; momentum sits with heat transfer fluids as immersion cooling displaces cold-plate designs.
Application:
Volume concentration tracks battery pack complexity, with energy storage and electric vehicle platforms consuming formulation capacity at scales that dwarf industrial and aerospace niches.
- Energy Storage:Grid-scale battery installations requiring thermal management for lithium-ion cell modules operating in continuous charge-discharge cycles. China's MEE dual carbon compliance disclosures now mandate documented cradle-to-gate carbon footprints for all thermal management chemistries in domestic utility-scale projects.
- Electric Vehicles:Passenger and commercial vehicle battery packs, power electronics, and motor cooling systems. OEMs in Germany and South Korea are qualifying nanofluid formulations for high-fast-charge duty cycles, with dispersed aluminum oxide particles boosting heat transfer coefficients.
- Industrial Cooling:Manufacturing equipment and data center thermal management applications with standardized fluid specifications.
- Aerospace:Electric aircraft prototypes commanding 3-4x fluid pricing premiums for formulations tolerating extreme thermal cycling and altitude pressure variations.
Electric vehicles command dominant volume; aerospace represents the steepest expansion trajectory as electrified flight prototypes multiply.
End User:
Procurement authority is fragmenting as battery manufacturers establish independent fluid qualification teams, bypassing traditional automotive tier-one distributors.
- Manufacturing:Industrial automation and semiconductor fabrication facilities with established thermal management infrastructure and conservative specification change cycles.
- Automotive:Electric vehicle OEMs and battery pack producers driving co-development programs with formulators. CATL and BYD in China have separated thermal management system design from fluid procurement, creating direct technical engagement channels.
- Renewable Energy:Offshore wind operators in the North Sea specifying bio-based e-fluids to meet lifecycle carbon disclosure requirements under EU CSRD.
- Transportation:Rail, marine, and aviation electrification programs with extended qualification timelines and safety certification backlogs.
Automotive captures the dominant margin pool; renewable energy is climbing the fastest as offshore wind capacity expands.
Technology:
Reformulation cycles accelerate under regulatory pressure, with the EU F-Gas Regulation and China's MEE enforcement driving chemistry refreshes every three to five years.
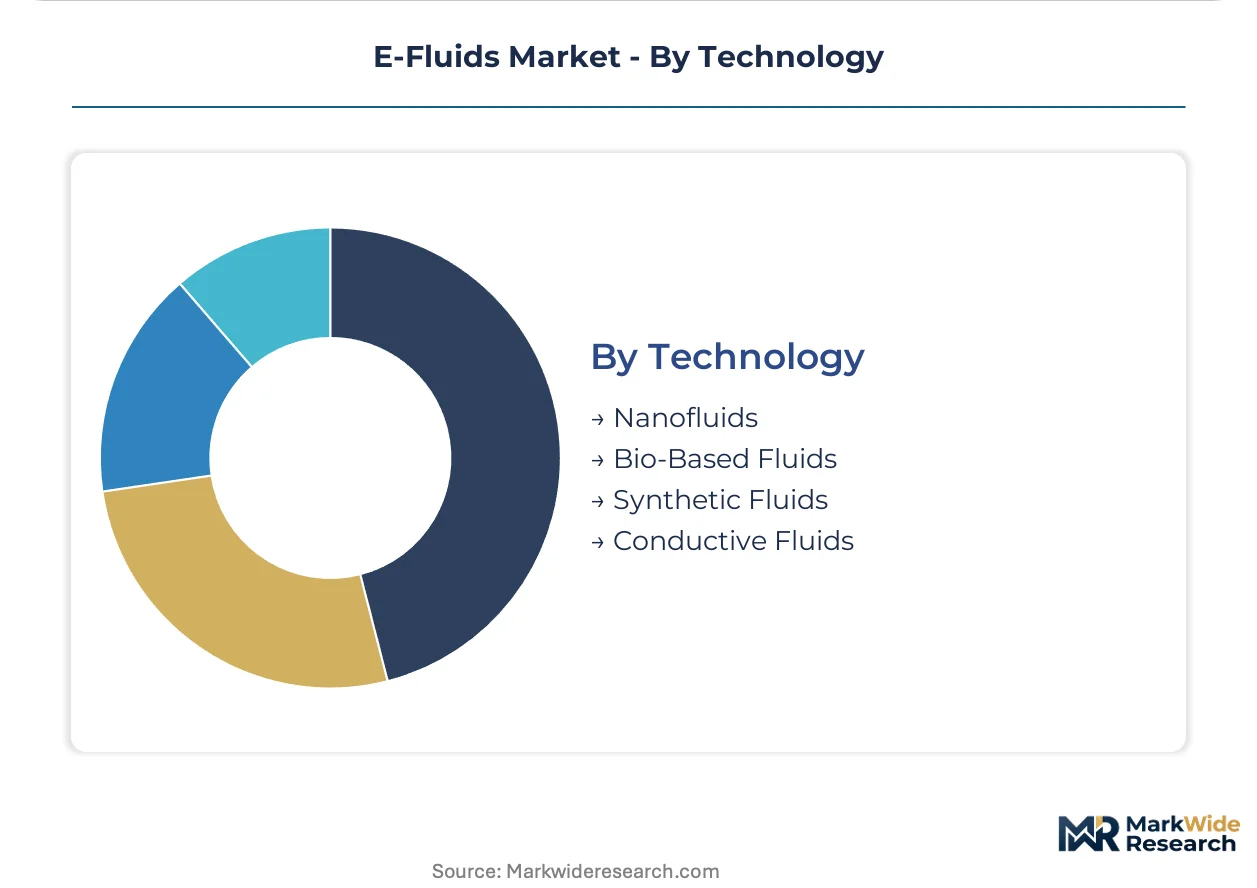
- Nanofluids:Metal oxide particle dispersions boosting thermal conductivity 15-40% without compromising electrical isolation. Battery OEMs in Germany and South Korea are qualifying these formulations for high-fast-charge duty cycles, virtualizing traditional trade-offs between thermal performance and dielectric strength.
- Bio-Based Fluids:Palm oil and neopentyl glycol derived formulations serving renewable energy end users seeking lifecycle carbon reductions. Feedstock price volatility transmits directly into formulated fluid costs, squeezing blender margins.
- Synthetic Fluids:Polyalphaolefin and synthetic ester bases dominating dielectric and heat transfer applications with proven electrochemical compatibility.
- Conductive Fluids:Specialized formulations for grounding and static dissipation applications in explosive atmosphere environments.
Synthetic fluids retain installed base dominance; nanofluids are gaining share fastest as 800V architectures stress conventional thermal limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes e-fluids predominantly for battery immersion cooling in electric vehicles, while Germany prioritizes aerospace-grade formulations and the United States distributes demand across data center thermal management and industrial automation.
China
CATL and BYD drive dielectric fluid procurement for 800V battery architectures under the MIIT's new energy vehicle mandates. The MEE enforces dual carbon compliance disclosures that reshape supplier qualification protocols. Synthetic base oil capacity concentrates in Jiangsu and Zhejiang provinces, compressing regional production costs for domestic formulators.
Germany
Battery OEMs around Stuttgart and Munich specify single-phase immersion chemistries for next-generation electric vehicle platforms. The EU F-Gas Regulation accelerates phase-out schedules for conventional fluorinated coolants in automotive manufacturing. Aerospace-grade thermal management specifications from electric aircraft prototypes in Bavaria command substantial pricing premiums over automotive grades.
United States
Data center operators and industrial automation facilities diversify e-fluid demand beyond electric vehicle applications. The EPA regulates fluid disposal and toxicity thresholds under TSCA, forcing reformulation cycles every three to five years. Polyalphaolefin production clusters along the US Gulf Coast create geographic supply vulnerability for non-integrated blenders.
South Korea
Battery manufacturers qualify nanofluid formulations with dispersed aluminum oxide particles for high-fast-charge duty cycles. The MFDS maintains chemical safety standards that parallel EU REACH frameworks for thermal management chemistries. Seoul-based OEMs are separating thermal management system design from fluid procurement, enabling direct technical engagement with specialized formulators.
Singapore
Integrated refineries supply synthetic base oils to battery OEMs across Asia-Pacific under the country's chemicals hub strategy. The Economic Development Board incentivizes advanced materials manufacturing for electrification supply chains. Jurong Island's concentrated petrochemical infrastructure anchors regional dielectric fluid production for export markets.
E-Fluids Market Competitive Landscape
Capability concentration sits with integrated petrochemical majors possessing synthetic base oil infrastructure; scale advantage sits with specialized lubricant blenders serving niche thermal management specifications. The market structure reflects a tiered hierarchy where upstream integration determines cost position and formulation expertise secures premium segments. Three archetypes dominate: integrated oil majors with captive base stock supply, independent chemical specialists with OEM co-development relationships, and regional blenders competing on logistics proximity. Capacity expansion and direct OEM supply contracts represent the dominant competitive vectors as battery manufacturers bypass traditional distribution channels.
Within the integrated oil major tier, ExxonMobil leverages Singapore refinery infrastructure to supply battery OEMs directly, while Shell anchors European market position through partnerships with electric vehicle platforms requiring low-viscosity formulations. Castrol occupies a specialized position representing aerospace-grade e-fluid variants for extreme thermal cycling applications. These three exemplify how upstream integration and segment-specific formulation expertise create defensible competitive positions as immersion cooling adoption accelerates.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| TotalEnergies |
| BP |
| FUCHS |
| Castrol |
| Afton Chemical |
| Motul |
| Panolin |
| Others |
Supply & Pricing Matrix
The Singapore-Jurong Island freight corridor compresses logistics costs for synthetic base oil movements to battery OEMs, amplifying price differentiation between integrated formulators with captive supply and independent blenders sourcing at spot. This corridor's cost dynamics concentrate procurement power among refiners with backward integration into polyalphaolefin production, while non-integrated players absorb margin compression from feedstock volatility.
Pricing Analysis
Long-term offtake contracts dominate dielectric fluid procurement as battery OEMs lock in supply security for 800V architecture ramps. Pricing stratifies across aerospace-grade, automotive immersion, and industrial heat transfer tiers, with certification level—particularly UL 9540A fire safety—commanding substantial premiums. Cost compression in automotive grades is intensifying as China's Jiangsu-Zhejiang synthetic base oil capacity expands. Tier-one battery manufacturers exhibit lowest price sensitivity due to co-development program investments, while industrial cooling buyers negotiate aggressively on volume.
Supply Chain Analysis
Extended payment terms from battery OEMs are forcing working capital discipline on mid-tier formulators without balance sheet depth. Supply concentrates in Singapore, the US Gulf Coast, and China's Jiangsu-Zhejiang corridor for polyalphaolefin and synthetic ester base stocks. Formulated e-fluids draw from palm oil, neopentyl glycol, and dispersed metal oxide nanoparticles as critical inputs. Single-source vulnerability runs through Singapore's Jurong Island refining cluster, where concentrated petrochemical infrastructure anchors regional dielectric fluid production. Distribution runs through direct OEM technical engagement channels that displace traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-fluids sit in early-cycle expansion as immersion cooling adoption accelerates battery pack architecture redesigns. Penetration tailwinds from 800V platform ramps and electric aviation prototyping extend addressable demand beyond conventional automotive volumes.
For Market Incumbents: Build formulation moats around nanofluid electrochemical compatibility datasets that require 18-24 month validation cycles to replicate. Deepen backward integration into synthetic ester production to offset palm oil and neopentyl glycol price volatility squeezing blender margins. Secure UL 9540A testing capacity commitments to compress time-to-market advantages as fire safety certification backlogs extend 6-9 months. For New Entrants and Emerging Players: Pursue electric aviation thermal management specifications where 3-4x pricing premiums over automotive grades persist. Target offshore wind operators in the North Sea specifying bio-based e-fluids under EU CSRD lifecycle carbon disclosure mandates. Establish direct technical engagement with battery OEM fluid qualification teams that have separated procurement from system design. For Investors and Strategic Acquirers: Specialized chemical formulators with OEM co-development relationships and verified dual carbon compliance data represent the most defensible acquisition archetype. Long-term viability hinges on immersion cooling displacement of cold-plate designs across the projection horizon. Watch nanofluid qualification velocity at German and South Korean battery OEMs as the inflection signal for thermal conductivity benchmark shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Oil Production | Captive polyalphaolefin supply from Singapore or US Gulf Coast refineries insulates margin from feedstock volatility. |
| Nanofluid Electrochemical Compatibility Investment | Dispersed aluminum oxide and boron nitride formulations address 800V dielectric breakdown thresholds for fast-charge duty cycles. |
| Direct OEM Supply Contract Establishment | Battery manufacturers bypassing traditional distribution creates exclusive co-development channels with CATL, BYD, and European platforms. |
| EU F-Gas Regulation Compliance Certification | Accelerated phase-out schedules for fluorinated coolants qualify formulators for German automotive corridor procurement. |
| Dual Carbon Compliance Data Infrastructure | China's MEE enforcement requires documented cradle-to-gate carbon footprints for approved vendor status with tier-one battery producers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with thermal management engineers at battery OEMs, procurement leads at electric vehicle platforms, refinery operations managers, and fluid formulation R&D directors; and secondary validation through customs trade data, SEC filings from integrated oil majors, MIIT new energy vehicle production statistics, and EU F-Gas Regulation implementation reports. Bottom-up triangulation across synthetic base oil capacity, battery pack production forecasts, and fluid content per vehicle converged with top-down market sizing.
Forecast inputs span dielectric fluid, heat transfer fluid, and lubricant product categories across electric vehicle, energy storage, aerospace, and industrial cooling applications. Segmentation dimensions include fluid technology type—synthetic, bio-based, nanofluid—voltage architecture tier, and regional regulatory cluster. CAGRs were derived from battery pack production trajectories, immersion cooling adoption curves, and reformulation cycle frequencies driven by EU F-Gas and China's MEE enforcement. Nanofluid thermal conductivity benchmarks and 800V dielectric strength requirements shaped technology-specific growth assumptions.
Sensitivities concentrate around battery pack architecture shifts from cold-plate to immersion cooling, nanofluid qualification timelines at OEMs, and synthetic ester feedstock price volatility. Forecasts reflect assumptions on regulatory phase-out schedules and dual carbon compliance enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Proline Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Europe Isocyanates Market