
 Low Trauma/Skin Friendly Adhesives Market | 2026-2036
Low Trauma/Skin Friendly Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Low Trauma/Skin Friendly Adhesives Market Intelligence
The transition to medical-grade silicone adhesives with superior breathability and peel performance is reorganizing the competitive landscape. 3M Company leverages its deep material science expertise to develop advanced skin-contact solutions. Molnlycke Health Care AB specializes in gentle-adhesion products for the wound care sector. Avery Dennison Corporation competes by offering a broad portfolio of medical-grade materials to device manufacturers.
Low trauma adhesives are engineered materials designed for repeated application and removal without causing skin stripping, irritation, or pain. Their formulation focuses on achieving a secure bond with low peel adhesion force, often measured in N/cm. Silicone-based materials command a significant portion of the market due to their inert and hypoallergenic properties. The wound care application segment represents the largest area of use, followed by post-surgical dressings.
Biocompatibility and safety standards set by the US FDA and the European Union's Medical Device Regulation (MDR) are critical for market access. In Asia, compliance with requirements from bodies like Japan's PMDA and China's NMPA is essential for commercialization. Future success hinges on a manufacturer's ability to innovate materials that meet these stringent global regulatory demands while improving patient comfort.
Market Dynamics
The market's trajectory is defined by the convergence of advanced material science and escalating global regulatory scrutiny. This dynamic forces manufacturers to innovate materials for enhanced patient comfort, particularly in chronic care, while simultaneously ensuring compliance with divergent standards from the US FDA, the EU's MDR, and Japan's PMDA.
Growth Catalysts
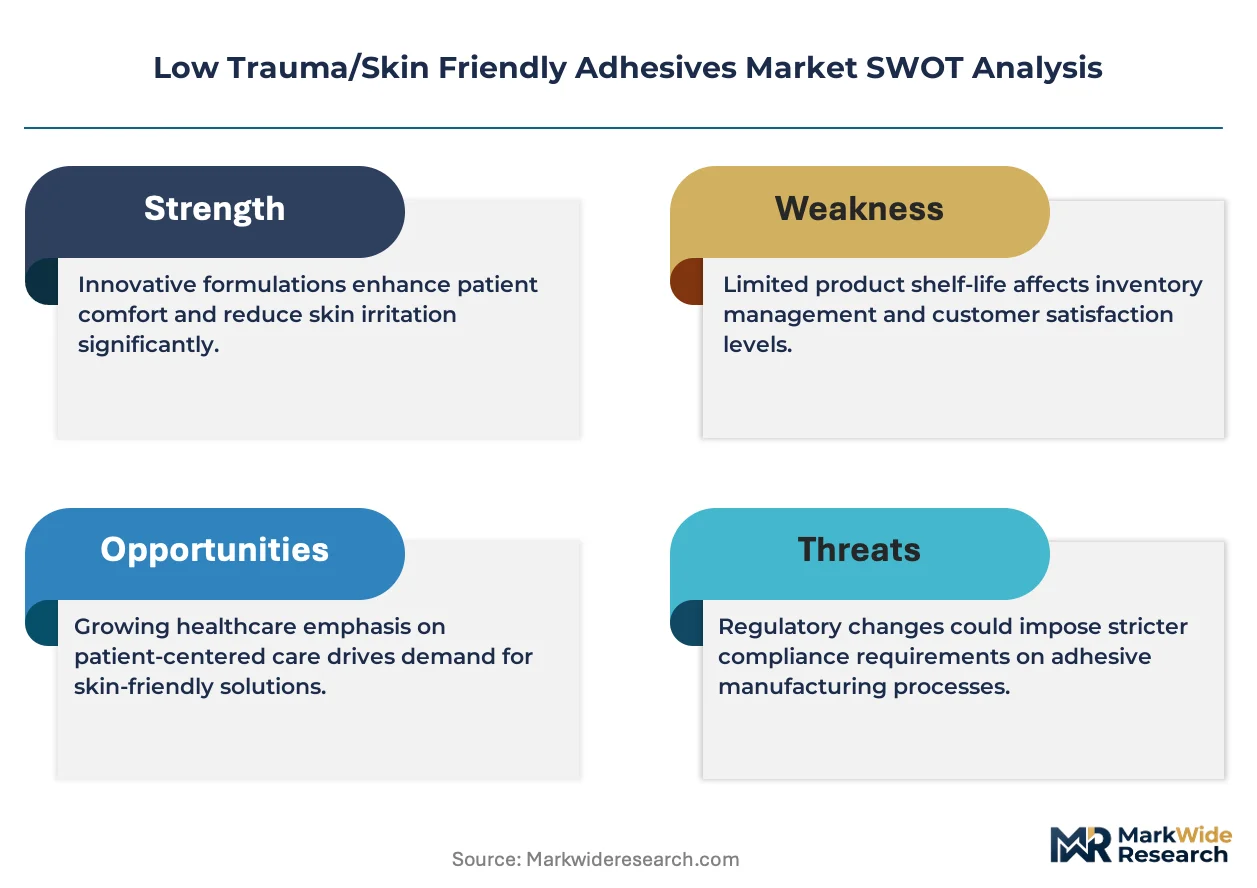
- Advanced Polymer Development:The creation of novel biocompatible polymers with superior breathability and controlled adhesion is expanding applications in chronic wound care, especially for the fragile skin of elderly patients.
- Chronic Disease Prevalence:A rising incidence of conditions like diabetes and vascular ulcers in developed nations, including Germany and Japan, drives consistent demand for gentle adhesives in wound management and device fixation. li>Regulatory Up-Classification: Stricter requirements under frameworks like the EU's Medical Device Regulation (MDR) elevate the quality bar, favoring premium, well-documented adhesives and creating a barrier for non-compliant materials.
Market Restraints
- Raw Material Costs:The high price of medical-grade silicone, the primary material for hypoallergenic adhesives, translates to higher end-product costs, which can limit adoption in cost-sensitive healthcare systems.
- Regulatory Fragmentation:Navigating disparate and evolving regulatory requirements from the FDA, EU MDR, and China's NMPA increases compliance costs and extends product development timelines for manufacturers.
- Technical Performance Trade-offs:A persistent engineering challenge involves balancing secure, long-lasting adhesion with the extremely low peel force required to prevent skin damage upon removal, especially for repeated applications.
Strategic Opportunities
- Wearable Medical Devices:Expanding use of wearable health monitors, such as continuous glucose monitors and cardiac sensors, creates a significant opportunity for adhesives designed for long-term, irritation-free skin contact.
- Emerging Market Penetration:Healthcare infrastructure improvements and a growing middle class in countries like Brazil and India present new growth frontiers for advanced wound care and skin-friendly adhesive products.
- Functional Adhesive Systems:There is an opportunity to develop adhesives that incorporate active functionalities, such as antimicrobial properties or moisture management, to contribute directly to therapeutic outcomes.
Industry Challenges
- Certification Timelines:The lengthy and resource-intensive process of achieving biocompatibility certification under ISO 10993 and securing market approval from national regulators presents a significant operational hurdle.
- Supply Chain Vulnerability:Reliance on a limited number of specialized suppliers for high-purity silicone and other advanced polymers creates potential vulnerabilities and risks for manufacturing continuity.
- Clinical Education Gap:A need exists to educate clinicians and patients on proper application and removal techniques to ensure the full benefits of low-trauma adhesives are realized and to prevent user error.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Trauma/Skin Friendly Adhesives Market |
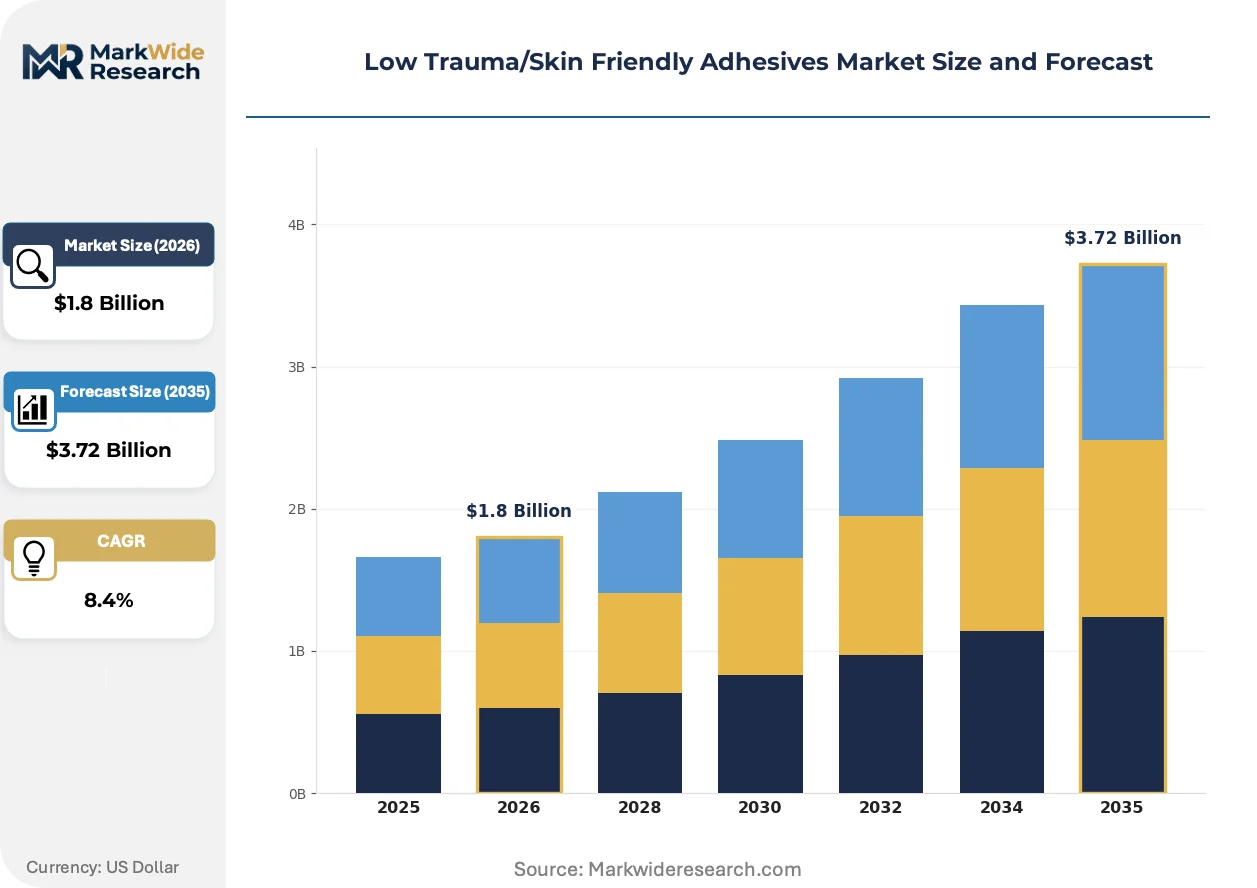
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Tapes, Dressings, Bandages, Gel Adhesives Application: Wound Care, Post-Surgical, Cosmetic, Dermatological End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Material: Silicone, Hydrocolloid, Foam, Biocompatible Polymers |
| Companies Covered | Nitto Denko Corporation, Scapa Group plc, 3M Company, Molnlycke Health Care AB, Smith & Nephew plc, Henkel AG & Co. KGaA, Avery Dennison Corporation, Vancive Medical Technologies, Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Trauma/Skin Friendly Adhesives Market Strategic Shifts & Innovations
The market is evolving from providing passive adhesion to enabling active skin-interface solutions. This shift is propelled by material innovations that integrate new functionalities, addressing sophisticated demands from the wearable technology sector and the advanced wound care field for improved patient outcomes and comfort.
Smart polymers featuring responsive characteristics are gaining traction in product design. These materials, which can alter their adhesive properties based on triggers like temperature or pH, are being adopted by developers of next-generation drug delivery patches and wearable biosensors. This technology is displacing conventional static adhesives by enabling active, controlled release or detachment, enhancing both therapeutic efficacy and user convenience.
The European Union's Medical Device Regulation (MDR) imposes significantly more stringent requirements for clinical evidence and post-market surveillance. This forces manufacturers to generate a higher level of safety and performance data for any product classified as a medical device, including adhesive dressings. The wound care and surgical dressing segments are most affected, prompting significant investment in updated technical files and clinical evaluation reports to maintain market access in Europe.
A definitive shift toward home healthcare and remote patient monitoring is altering consumption patterns. This movement away from acute, in-hospital settings favors adhesives designed for extended wear and self-management by patients in a non-clinical environment. This trend is most pronounced in the management of chronic conditions like diabetes in the United States, where patients increasingly use multi-day wearable sensors that require reliable, non-irritating skin fixation.
Low Trauma/Skin Friendly Adhesives Market Segmentation
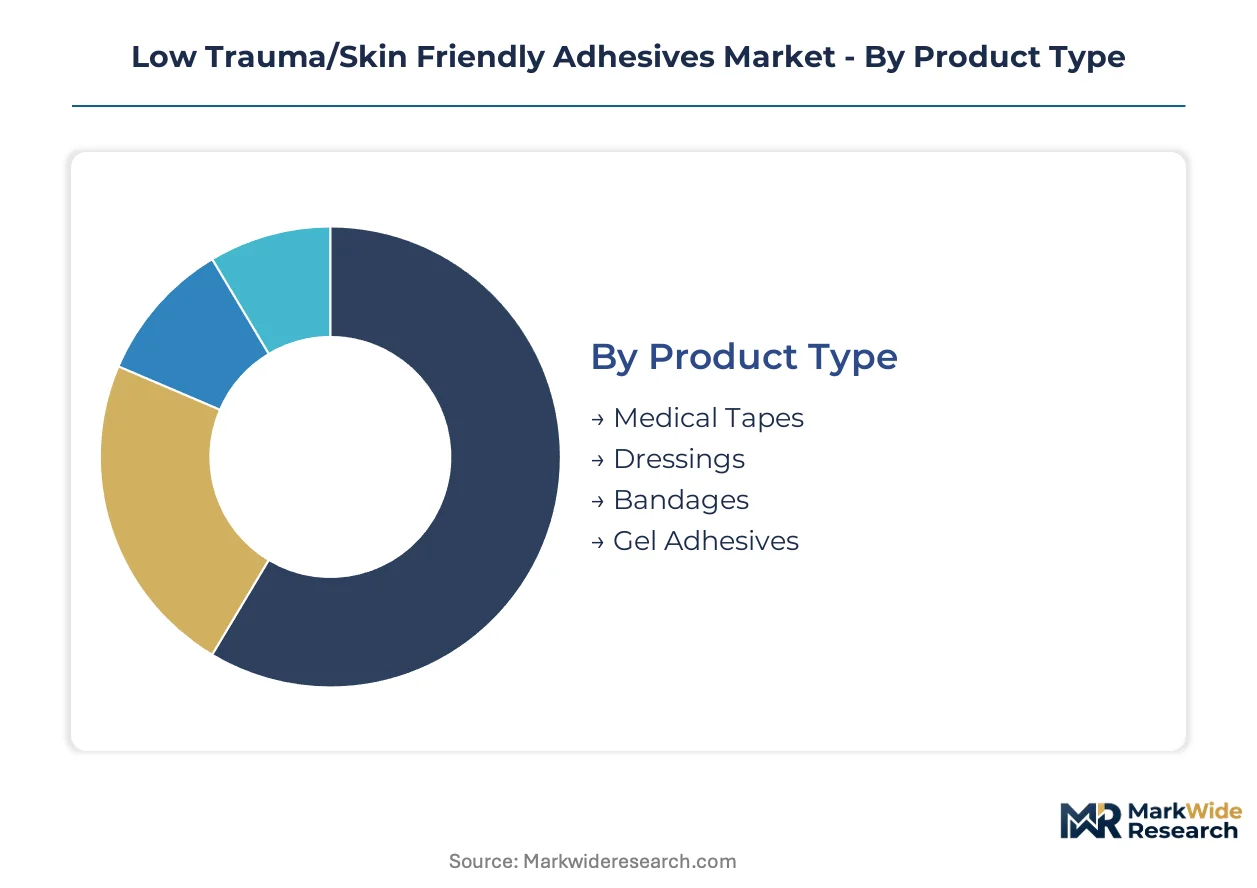
Market segmentation provides a critical framework for understanding the diverse structural forces and demand drivers within the low trauma/skin friendly adhesives landscape. This analysis illuminates how varying product characteristics, application needs, end-user requirements, and material science advancements collectively shape competitive dynamics and growth opportunities.
Product Type:
Margin pools within this category are heavily influenced by product complexity and regulatory burden.
- Dressings:Multi-layered constructions for wound management, often incorporating absorption and gentle adhesion, designed to protect and promote healing. Demand concentrates in chronic wound care for elderly patients, especially in Germany and Japan, driven by conditions like diabetes.
- Medical Tapes:Pressure-sensitive adhesive products for securing devices or wound dressings, engineered for repeated skin contact without irritation. Demand is strong in post-surgical applications and device fixation, particularly for wearable sensors requiring long-term, non-irritating wear.
- Bandages:Flexible fabric or film-based products with an adhesive layer, used primarily for minor cuts, abrasions, and securing small medical items.
- Gel Adhesives:Viscous, often hydrogel-based formulations providing a moist healing environment and minimal skin trauma upon removal from sensitive areas.
Medical Tapes hold installed capacity. Dressings are rotating up the share rankings.
Application:
Demand volume in this category directly correlates with patient demographics and the prevalence of chronic conditions.
- Wound Care:Adhesives engineered for primary or secondary dressings, facilitating healing while protecting fragile skin from stripping or irritation. This segment dominates the market, driven by the increasing incidence of chronic wounds in aging populations across developed healthcare markets.
- Post-Surgical:Adhesives used for securing surgical sites, drains, or ostomy appliances, requiring secure yet gentle removal to prevent skin damage. This segment maintains consistent demand in hospital settings, focusing on patient comfort and infection prevention post-operation.
- Cosmetic:Adhesives for temporary skin applications, such as aesthetic patches or prosthetic attachment, prioritizing discreet wear and gentle removal.
- Dermatological:Products designed for skin conditions, including transdermal drug delivery patches or protective barriers for sensitive or compromised skin.
Wound Care holds significant application volume. Dermatological applications are gaining share fastest.
End User:
The customer type in this category dictates procurement scale and the level of required clinical support.
- Hospitals:Large-scale procurement of various adhesive types for diverse medical procedures and patient populations across multiple departments. Hospitals remain a foundational segment for high-volume surgical and acute wound care, particularly in regions with established healthcare infrastructure.
- Home Care:Adhesives designed for ease of self-application and extended wear, often by non-medical professionals or patients themselves. This segment is experiencing substantial growth due to the shift towards remote patient monitoring and chronic disease management in the United States.
- Clinics:Outpatient facilities utilizing adhesives for minor procedures, specialized wound care, and dermatological treatments, often in smaller volumes than hospitals.
- Rehabilitation Centers:Facilities requiring adhesives for long-term patient care, physical therapy, and assistive device fixation, focusing on maintaining skin integrity during extended use.
Hospitals maintain their market position. Home Care shows substantial expansion.
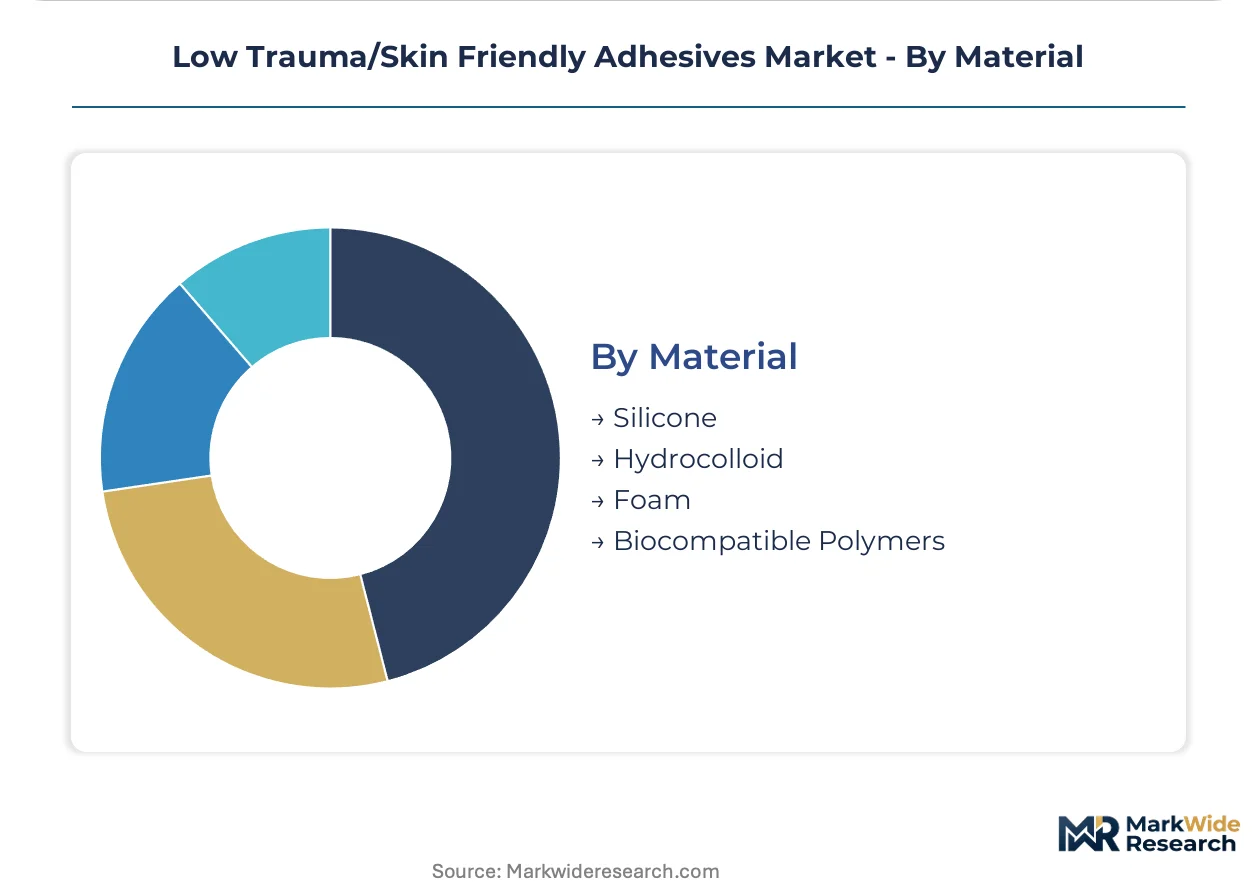
Material:
Technical specifications and biocompatibility standards primarily define material selection within this category.
- Silicone:Inert, hypoallergenic polymers offering secure adhesion with low peel force, crucial for sensitive and fragile skin. Silicone commands a significant market share due to superior breathability and patient comfort, especially in advanced wound care products.
- Biocompatible Polymers:Advanced synthetic or natural polymers engineered to minimize adverse reactions with biological systems and enhance functional properties. This material segment is growing rapidly for next-generation wearable devices and drug delivery systems, driven by innovation in material science.
- Hydrocolloid:Gel-forming materials that absorb wound exudate while providing a moist healing environment and gentle adhesion for wound healing.
- Foam:Porous polymer materials used in dressings for absorption and cushioning, often combined with a skin-friendly adhesive layer for enhanced protection.
Silicone materials hold the largest production capacity. Biocompatible Polymers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global demand for low trauma adhesives exhibits a nuanced export-import balance, driven by specialized manufacturing hubs and high-consumption healthcare markets. Developed nations often import advanced materials while exporting finished medical devices. This dynamic shapes regional market accessibility and material flow.
Germany
Germany represents a significant market for low trauma adhesives, fueled by its aging population and high incidence of chronic conditions like diabetes. Compliance with the EU's Medical Device Regulation (MDR) is paramount for market entry and product acceptance. Medical technology clusters in Bavaria and North Rhine-Westphalia drive advanced wound care innovation.
Japan
Japan's market for skin-friendly adhesives is propelled by an extremely elderly demographic and a strong emphasis on patient comfort in wound management. Adherence to the Pharmaceuticals and Medical Devices Agency (PMDA) standards is crucial for product commercialization. Research centers in Tokyo and Osaka focus on developing next-generation biocompatible polymers.
United States
The United States exhibits robust demand for low trauma adhesives, particularly for home healthcare and the expanding wearable medical device segment. Products must meet stringent US FDA biocompatibility and safety standards for market approval. Biotech hubs in Massachusetts and California lead in transdermal patch technologies.
China
China's market is expanding due to improving healthcare infrastructure and a rising prevalence of chronic diseases across its vast population. Manufacturers navigate complex requirements set by the National Medical Products Administration (NMPA) for device approval. Localized production and R&D facilities in the Yangtze River Delta enhance supply chain resilience.
United Kingdom
The United Kingdom demonstrates consistent demand for gentle adhesives within its National Health Service (NHS) for post-surgical and chronic wound care applications. Products must comply with the Medicines and Healthcare products Regulatory Agency (MHRA) guidelines for medical devices. Innovation centers in Cambridge and London foster advancements in skin interface solutions.
Low Trauma/Skin Friendly Adhesives Market Key Industry Players
Concentration sits with large, diversified material science conglomerates, alongside specialized medical device manufacturers. The market exhibits a tiered structure, with innovation-driven leaders and niche players. Strategic archetypes include integrated solution providers, raw material specialists, and dedicated wound care product developers. Companies pursue portfolio diversification, targeted mergers and acquisitions, and strategic partnerships to expand their market reach and technological capabilities.
Within the integrated solution provider archetype, the 3M Company, a prominent US-based conglomerate, anchors a broad portfolio of advanced skin-contact solutions across various medical applications. Molnlycke Health Care AB, a Swedish medical device specialist, exemplifies expertise in gentle-adhesion products specifically for the wound care sector, emphasizing patient comfort. US-based Avery Dennison Corporation occupies a position as a key supplier of medical-grade materials to device manufacturers globally, reflecting their extensive material science capabilities and broad product offering in the sector.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Scapa Group plc |
| 3M Company |
| Molnlycke Health Care AB |
| Smith & Nephew plc |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Vancive Medical Technologies |
| Lohmann GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Medical-grade silicone replacing traditional acrylics reshapes both the geographic concentration of polymer production and the overall pricing economics for low trauma adhesives. This material shift elevates input costs while demanding specialized manufacturing capabilities across the value chain.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing for high-volume orders. Price differentiation stems from the specific FDA/MDR certification level and the degree of material customization for unique device applications. Pricing pressure stems from the escalating cost of medical-grade silicone raw materials. Hospitals and large healthcare systems exhibit higher price sensitivity compared to specialized wearable device manufacturers.
Supply Chain Analysis
Inventory buffers for specialized medical-grade polymers maintain longer lead times due to stringent quality control and limited production capacity. Geographic supply concentration for high-purity silicone sources from the United States and Germany, alongside specialized polymer innovation in Japan. Raw material dependencies center on medical-grade silicone and advanced biocompatible polymers. Single-source vulnerability for critical components represents a structural risk. Distribution runs through direct channels to device manufacturers and specialized medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low trauma adhesives market demands specialized material science expertise, creating a scarcity in advanced polymer development capabilities. This skill gap limits innovation in next-generation skin-friendly solutions for complex medical applications.
For Market Incumbents: Fortify material science capabilities through targeted R&D investment in smart polymers, addressing the threat of stringent regulatory up-classification under the EU MDR. Pursue strategic acquisitions of niche technology firms specializing in advanced biocompatible polymers. Deepen certification investment to maintain market access and differentiate against less compliant materials. Control key intellectual property in next-generation skin-contact solutions.
For New Entrants and Emerging Players: Lead with highly specialized, biocompatible adhesive solutions for the expanding wearable medical device segment, particularly continuous glucose monitors. Target the home care application in the United States, leveraging demand for extended wear and patient self-management. Partner with established device manufacturers to integrate novel functional adhesives, such as those with antimicrobial properties, into new product lines. Focus on niche applications requiring superior patient comfort.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized material science firms with strong intellectual property. Long-term viability remains robust, driven by persistent demand from aging populations and the expansion of chronic disease management. Identify vertically integrated mid-cap specialists with proprietary biocompatible polymer technologies as prime acquisition targets. The signal to watch is the accelerated pace of regulatory approvals for novel adhesive formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Ensures reliable supply for European medical device manufacturers. |
| Green Manufacturing Transition | Enhances brand reputation and meets evolving environmental regulations. |
| Joint Venture | Accelerates market penetration for novel skin-contact solutions. |
| Regulatory Approval Pathway | Secures market access for advanced wound care dressings in Europe. |
| Pipeline Diversification | Creates new revenue streams beyond passive adhesion products. |
Research Approach
Operator-level perspectives from biomedical engineers, hospital procurement managers, and R&D directors at adhesive manufacturers anchored the qualitative base. Primary interviews were triangulated with extensive secondary validation from US FDA filings, EU MDR guidance documents, and ISO 10993 standards. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down data synthesis.
Sensitivity analysis informed the quantitative modeling framework across the analysis window. Segmentation dimensions including product type, application, end-user, material, and regional regulatory compliance were meticulously modeled. Compound Annual Growth Rates were derived from historical trend analysis and projected demand drivers such as chronic disease prevalence rates. Medical device innovation cycles also served as key forecast inputs.
Underlying assumptions cover a stable regulatory environment and consistent raw material supply, with deviation risk concentrated in unforeseen shifts in global healthcare policies. Rapid material science breakthroughs could also alter market trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Anti-Adhesion Products Market